
 Cup Fill and Seal Machine Market | 2026-2036
Cup Fill and Seal Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cup Fill and Seal Machine Market Analysis
Buyer concentration among European dairy cooperatives is rebalancing toward mid-sized regional processors seeking semi-automatic and fully automatic systems. Waldner leverages its engineering depth in rotary filling technology to sustain premium positioning across German-speaking markets. ProMach competes through integrated packaging line architectures that anchor North American beverage accounts. IMA Group dominates pharmaceutical-grade cleanroom configurations, extending its regulatory compliance capabilities into food applications.
A cup fill and seal machine dispenses measured product into pre-formed cups, applies lidding material through thermal or ultrasonic welding, and outputs sealed packages at speeds from 30 to 600 units per minute depending on rotary or linear configuration. The equipment serves dairy, beverage, and ready-meal producers requiring hermetic seals for shelf stability and contamination control. Fully automatic rotary systems command the widest installed base among large-volume dairy operations, while linear thermal technology captures growing share in pharmaceutical applications where changeover flexibility outweighs raw throughput. High-speed configurations concentrate margin pools in aseptic beverage packaging, where ultrasonic sealing reduces energy consumption compared to conventional thermal methods.
EU Green Deal packaging regulations and REACH compliance frameworks shape machine specifications, particularly lidding material compatibility and energy efficiency thresholds for thermal sealing systems. FDA sanitary design standards govern pharmaceutical and dairy applications in the United States, while ISO 22000 food safety management systems influence buyer qualification protocols across export-oriented manufacturers. Stakeholders must monitor evolving extended producer responsibility schemes and decide between modular upgrade paths versus complete system replacements as sealing technology shifts toward lower-temperature ultrasonic methods.
Market Dynamics
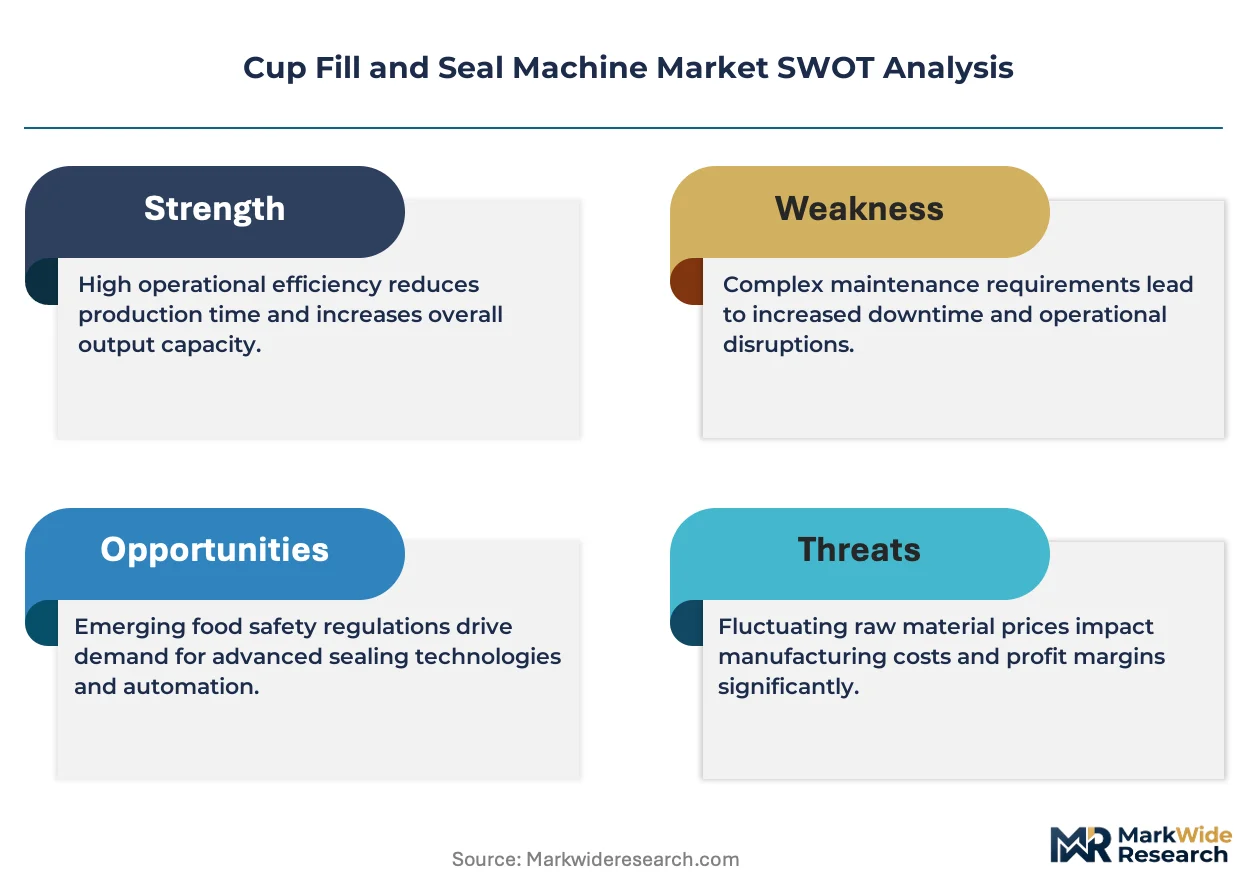
Ultrasonic sealing technology is compressing thermal sealing margins across dairy and beverage packaging lines, forcing incumbent suppliers to reconfigure rotary platform architectures or cede high-speed aseptic contracts to engineering specialists with proprietary acoustic welding systems.
Growth Catalysts
- EU Green Deal packaging waste targets:Dairy processors in Germany and France are retrofitting automated lines to meet extended producer responsibility mandates, creating replacement demand for energy-efficient sealing systems.
- Aseptic beverage packaging:Extended shelf-life dairy and plant-based drinks require hermetic ultrasonic seals, pulling rotary system orders from North American beverage manufacturers.
- Pharmaceutical-grade cleanroom migration:Food manufacturers are adopting ISO 22000-aligned configurations previously developed for injectable drug packaging, expanding the addressable machine base.
Market Restraints
- Stainless steel input volatility:Grade 316L and 304 price swings compress margin predictability for European machine builders dependent on Asian mill supply.
- Linear thermal technology lock-in:Mid-sized regional processors in Southern Europe face sunk-cost barriers when evaluating ultrasonic rotary upgrades against functional existing equipment.
- REACH chemical compliance:Lidding material reformulations to eliminate perfluorinated compounds extend qualification timelines and freeze specification decisions at major dairy cooperatives.
Strategic Opportunities
- Modular retrofit architectures:Machine builders can capture upgrade revenue from installed linear thermal bases by offering ultrasonic sealing head swaps without full platform replacement.
- Pharmaceutical-beverage convergence:Cleanroom-validated rotary systems originally engineered for parenteral drugs are finding second applications in high-value probiotic dairy formats.
- India FSSAI modernization:The country's food safety regulator is tightening packaged dairy standards, creating first-time automation demand among unorganized sector processors.
Industry Challenges
- Ultrasonic transducer calibration expertise:Field service networks lack depth in acoustic welding parameter optimization, extending commissioning timelines and eroding customer satisfaction scores.
- Legacy SCADA integration:Brownfield dairy plants operate proprietary control architectures from the 1990s, complicating Industry 4.0 data extraction from new rotary sealing lines.
- CE-MDR dual certification:Machine builders serving both food and medical device markets face diverging documentation requirements that strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cup Fill and Seal Machine Market |
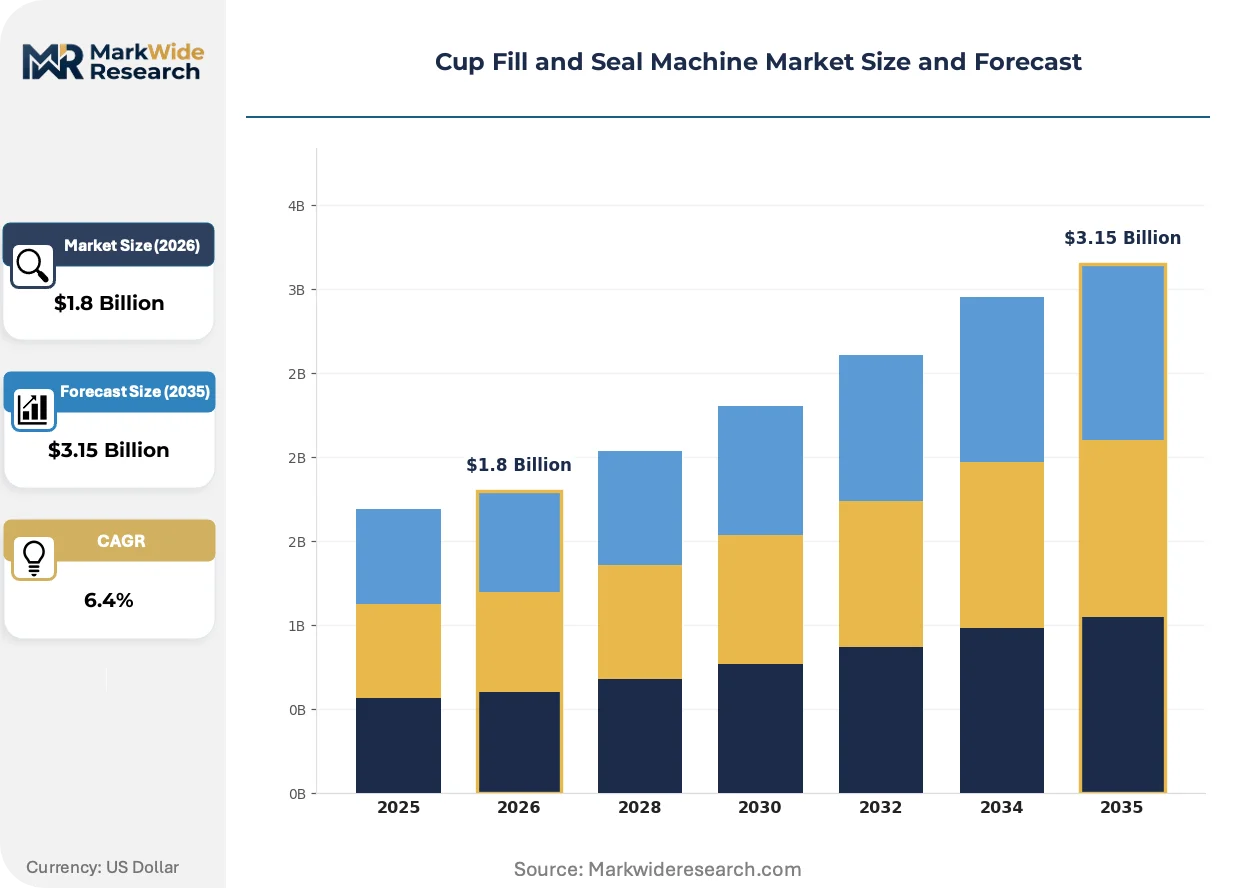
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-automatic, Fully Automatic, High-speed Technology: Thermal, Ultrasonic, Rotary, Linear End User: Dairy, Beverage, Food, Pharmaceuticals Material: Plastic, Paper, Aluminum, Others |
| Companies Covered | IMA Group, Serac Group, Waldner, ProMach, Ronchi Mario, Trepko, Ilpra, Packline Ltd, Amtec Packaging Machines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cup Fill and Seal Machine Market Emerging Trajectories
Acoustic welding systems are reshaping competitive positioning in high-speed packaging, while regulatory pressure on packaging waste and energy intensity accelerates specification changes across European dairy operations.
Ultrasonic sealing is electrifying the aseptic beverage segment by eliminating thermal mass and reducing energy draw per sealed unit. Large-volume dairy cooperatives in Northern Europe are specifying acoustic rotary platforms for extended shelf-life milk and plant-based alternatives. This technology is compressing the performance gap between premium European engineering and mid-tier Asian suppliers.
REACH perfluorinated compound restrictions are forcing lidding material reformulations that demand lower-temperature sealing profiles. Thermal rotary systems face retrofit pressure as film suppliers withdraw legacy barrier coatings. German dairy processors are responding with phased ultrasonic upgrades to maintain supply continuity.
Service unbundling is fragmenting the traditional machine sale model. Dairy cooperatives are separating capital equipment procurement from multi-year maintenance contracts, pressuring OEM margin structures. This pattern is most visible in the Benelux region, where processor buying consortia negotiate aftermarket services through competitive tender.
Cup Fill and Seal Machine Market Segmentation
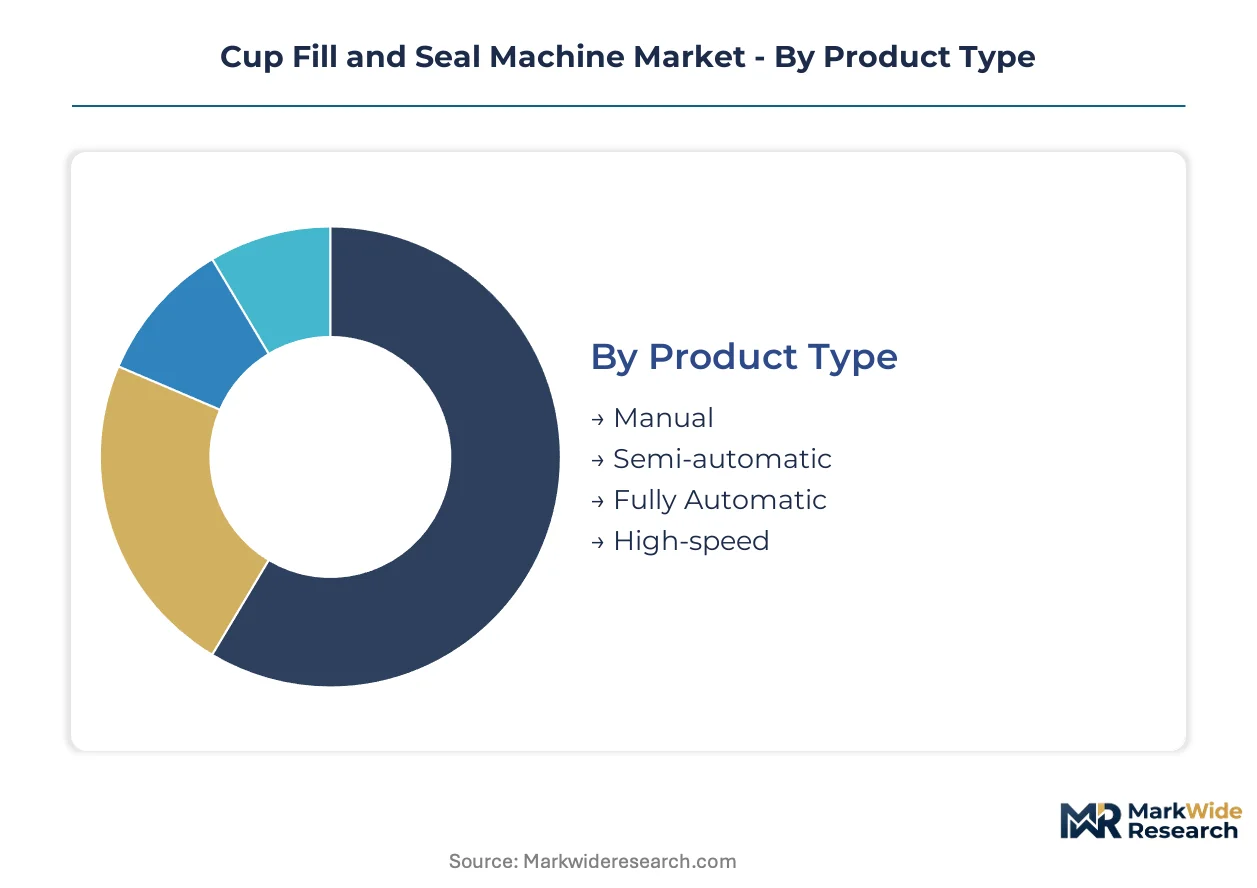
Segmentation in cup fill and seal machines reveals how capital allocation, regulatory pressure, and end-use shelf-life requirements reshape equipment procurement. Buyers prioritize automation tiers and sealing technologies based on production scale and compliance burden.
Product Type:
Fully automatic systems demand the heaviest upfront capital outlays, requiring integrated rotary platforms, servo-driven filling heads, and cleanroom-validated controls.
- Fully Automatic:Rotary configurations with 200-600 units per minute throughput dominate large-volume dairy cooperatives. German processors specify these for extended shelf-life milk lines under EU Green Deal energy efficiency mandates.
- High-speed:Ultrasonic sealing variants serve aseptic beverage packaging where hermetic integrity and reduced thermal mass cut per-unit energy draw. North American plant-based drink manufacturers anchor demand here.
- Semi-automatic:Mid-sized regional processors in Southern Europe favor these for flexibility across SKUs with moderate volume requirements.
- Manual:Entry-level units serve artisanal dairy and specialty food producers with batch-scale output needs.
Most installed capacity flows through Fully Automatic systems. Expansion is steepest in High-speed configurations.
Technology:
Sealing method selection hinges on energy thresholds, film compatibility, and regulatory timelines for material reformulation.
- Ultrasonic:Acoustic welding eliminates thermal mass, cutting energy consumption per seal. REACH perfluorinated compound restrictions are accelerating specification shifts here as lidding suppliers withdraw legacy barrier coatings.
- Rotary:Continuous-motion platforms maximize throughput for dairy and beverage volumes. These systems command premium positioning in Germany's industrial corridor.
- Thermal:Conventional hot-bar sealing retains share in legacy dairy lines where sunk costs and qualified film stocks delay upgrade cycles.
- Linear:Intermittent-motion configurations suit pharmaceutical applications where changeover flexibility outweighs raw speed.
Rotary technology carries the largest installed base. Ultrasonic platforms are gaining share fastest.
End User:
End-use segmentation tracks how shelf-life requirements and contamination control standards translate into equipment specifications.
- Dairy:Extended shelf-life milk and probiotic formats require hermetic seals and aseptic filling environments. German and French cooperatives drive rotary system demand.
- Pharmaceuticals:Injectable drug packaging standards migrate into high-value food applications. ISO 22000-aligned cleanroom configurations originally developed for parenteral products now serve probiotic dairy.
- Beverage:Plant-based alternatives and functional drinks specify ultrasonic sealing for energy efficiency and seal integrity.
- Food:Ready-meal and sauce producers balance throughput with recipe flexibility across thermal and ultrasonic options.
Dairy accounts for the dominant share of installed equipment. Pharmaceutical-grade configurations are climbing the fastest.
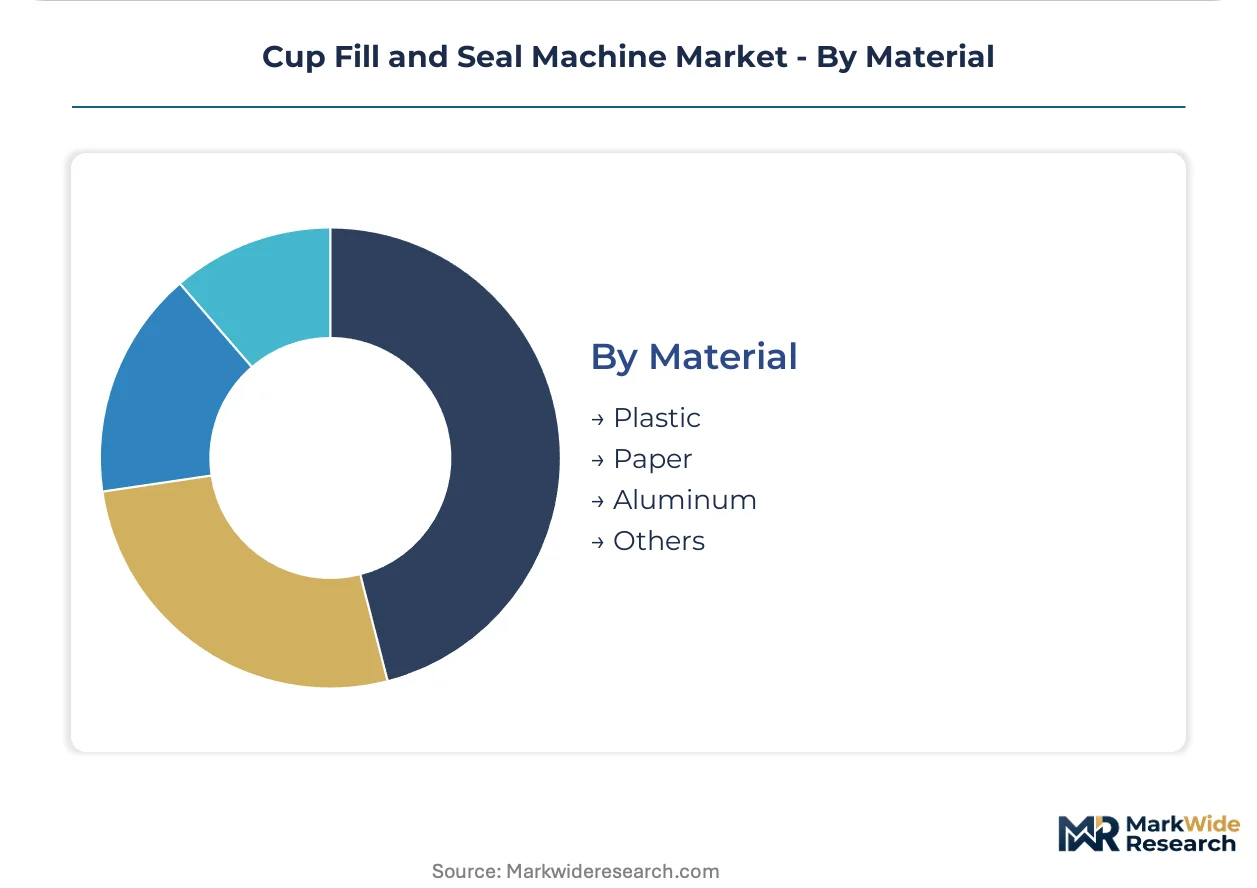
Material:
Substrate selection constrains sealing temperature profiles and machine compatibility, particularly under evolving chemical compliance frameworks.
- Plastic:Multi-layer barrier films dominate dairy and beverage lidding. REACH reformulations are forcing lower-temperature sealing protocols.
- Aluminum:Foil laminates serve high-barrier pharmaceutical and premium food applications requiring complete light and oxygen exclusion.
- Paper:Fiber-based lidding gains traction in sustainability-focused European markets, though seal integrity challenges persist.
- Others:Emerging bio-based and compostable substrates test equipment flexibility as EU extended producer responsibility schemes tighten.
Plastic substrates carry the largest installed base. Paper-based alternatives are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium rotary system demand while India generates first-time automation pull from regulatory modernization, illustrating how mature and emerging markets diverge in equipment procurement patterns.
Germany
Dairy cooperatives in Bavaria and North Rhine-Westphalia specify high-speed ultrasonic rotary platforms for extended shelf-life milk lines. EU Green Deal energy efficiency mandates accelerate replacement cycles for thermal sealing equipment. The Stuttgart industrial corridor hosts engineering specialists developing acoustic welding modules for aseptic beverage applications.
United States
Plant-based beverage manufacturers in California and Wisconsin anchor North American demand for hermetic sealing systems. FDA sanitary design standards govern pharmaceutical-grade cleanroom configurations migrating into probiotic dairy formats. Chicago-area dairy processors deploy integrated packaging line architectures to capture functional drink market share.
India
FSSAI modernization of packaged dairy standards creates virgin automation demand among unorganized sector processors in Maharashtra and Gujarat. Central food safety regulations now mandate hermetic seals for extended shelf-life products. The Pune-Ahmedabad industrial belt attracts semi-automatic system deployments from regional dairy cooperatives upgrading from manual operations.
France
Dairy processors in Brittany and Normandy retrofit automated lines to meet extended producer responsibility mandates under EU packaging waste directives. REACH perfluorinated compound restrictions force lidding material reformulations requiring lower-temperature sealing profiles. Lyon-based engineering firms supply rotary platforms calibrated for barrier film compatibility.
China
Domestic dairy majors in Inner Mongolia and Heilongjiang expand aseptic filling capacity for ambient yogurt and probiotic drinks. SAMR food safety regulations tighten contamination control standards for high-value packaged dairy. The Yangtze River Delta concentration of film suppliers accelerates qualification timelines for ultrasonic sealing compatibility.
Cup Fill and Seal Machine Market Vendor Landscape
German producers anchor one tier; Italian specialists hold differentiated positions in cleanroom-validated configurations. The vendor base stratifies across engineering-intensive rotary platforms, integrated line architects, and regional fabrication houses serving mid-scale processors. Three archetypes dominate: acoustic welding technology specialists, full-line packaging integrators, and pharmaceutical-grade cleanroom validators. Capacity expansion and modular retrofit architectures constitute the primary competitive moves as ultrasonic sealing displaces thermal methods.
Among German engineering houses, Waldner GmbH and IMA Group occupy positions reflecting divergent specialization vectors. Waldner exemplifies rotary filling technology depth calibrated for dairy cooperative specifications. IMA Group represents pharmaceutical-grade cleanroom capabilities extending into food safety applications. ProMach Inc. anchors North American integrated line architecture for beverage sector accounts. These three fabricators illustrate how geographic origin and regulatory compliance heritage shape competitive positioning across automation tiers.
| Leading Market Players |
|---|
| IMA Group |
| Serac Group |
| Waldner |
| ProMach |
| Ronchi Mario |
| Trepko |
| Ilpra |
| Packline Ltd |
| Amtec Packaging Machines |
| Others |
Supply Flow & Price Mechanics
EU Green Deal packaging waste targets gate qualified supply for premium-tier rotary systems while compressing margins for thermal sealing equipment lacking energy-efficient certification. German dairy cooperatives restrict vendor pools to builders with validated acoustic welding modules, translating sustainability compliance into pricing power concentration.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for mid-tier linear thermal equipment. Three-tier pricing structure across premium rotary ultrasonic, standard thermal rotary, and economy linear configurations separates Waldner-engineered platforms from Asian fabrication houses. Cost compression in economy-tier manual systems is intensifying because Indian regional cooperatives prioritize first-time automation over performance specifications. Mid-sized Southern European processors show highest price sensitivity; German extended shelf-life lines show lowest.
Supply Chain Analysis
Dual-sourcing mandates from Benelux buying consortia require German and Italian machine builders to qualify secondary component vendors for servo drives and ultrasonic transducers. Supply concentration rests on Germany for precision rotary platforms, Italy for cleanroom-validated configurations, and China for standardized linear systems. Grade 316L stainless steel, servo motor assemblies, and acoustic welding transducers anchor raw material dependencies. Single-source vulnerability in Asian mill supply for medical-grade stainless compresses margin predictability. Distribution runs through OEM direct sales for large dairy cooperatives and regional distributor networks for mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and France exceed FSSAI modernization thresholds in India, creating margin expansion opportunities for builders with modular export architectures.
For Market Incumbents: To counter ultrasonic technology displacement from acoustic welding specialists, Waldner and IMA Group should deepen backward integration into transducer calibration capabilities and expand field service networks in Bavaria and North Rhine-Westphalia. Capacity additions in India's Pune-Ahmedabad belt offer defensive positioning against Southern European margin erosion. For New Entrants and Emerging Players: Regional distributor partnerships in India's unorganized dairy sector unlock virgin automation demand where FSSAI hermetic seal mandates outpace local fabrication capacity. Semi-automatic ultrasonic retrofits for Southern European mid-sized processors represent the most penetrable white-space target. Go-to-market positioning should emphasize modular upgrade paths without full platform replacement. For Investors and Strategic Acquirers: Roll-up economics work for pharmaceutical-grade cleanroom validators because ISO 22000 alignment creates certification moats transferable to high-value probiotic dairy formats. Five-to-ten year viability hinges on acoustic welding patent estates and transducer calibration IP. Watch for REACH perfluorinated compound enforcement acceleration as inflection signal for lidding material reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Sealing Module Development | Proprietary acoustic welding IP captures EU Green Deal replacement cycles in German dairy. |
| Modular Retrofit Architecture Launch | Sealing head swaps without platform replacement unlock Southern European upgrade revenue. |
| India Distribution Network Expansion | FSSAI compliance mandates create first-time automation pull from unorganized sector processors. |
| Pharmaceutical-Beverage Convergence Platform | Cleanroom-validated rotary systems serve high-value probiotic formats with migrated drug standards. |
| Field Service Capability Buildout | Transducer calibration expertise shortens commissioning timelines and anchors maintenance contracts. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured plant engineers at German dairy cooperatives, procurement leads at French packaging lines, aftermarket service heads at Italian cleanroom specialists, and maintenance directors at North American beverage manufacturers. Secondary validation drew from EU ECHA REACH substance databases, FDA sanitary design guidance filings, FSSAI packaged dairy notifications, and customs records for stainless steel mill shipments. Bottom-up equipment shipment tallies triangulated against top-down dairy production capacity estimates.
Historical reference periods anchored the projection horizon to pre-pandemic baseline capacity utilization and post-regulatory-shift replacement cycles. Segmentation modeling tracked automation tier, sealing technology, end-use application, and regional regulatory cluster. CAGRs derived from equipment procurement intention surveys weighted against installed base depreciation schedules. Forecast inputs incorporated EU extended producer responsibility phase-in timelines and India FSSAI enforcement acceleration patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH perfluorinated compound withdrawal schedules and stainless steel input volatility. Deviation in ultrasonic transducer supply chain concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Heavy Duty Band Sealer Machine Market
Packaging Machinery
Tissue Paper Embosser Machine Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Global Blister Packaging Machinery Market
Packaging Machinery
Paper Slitting Machine Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Folding Gluing Machines Market
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Pick Fill Seal Machines Market