
 Pallet Banding Machine Market | 2026-2036
Pallet Banding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Banding Machine Market Analytics
Modular strapping-head configurations is expanding buyer choice as facilities retrofit existing conveyor lines rather than replace entire systems. Mosca GmbH leverages its servo-driven sealing technology to sustain premium positioning in high-speed food and beverage lines. FROMM Packaging Systems anchors its competitive stance through captive production of polyester strap, ensuring supply continuity across European distribution channels. Signode Industrial Group LLC dominates the North American installed base with extensive field-service networks that lock in aftermarket revenue streams.
A pallet banding machine applies tensioned plastic or steel strap around palletized loads and seals the joint through heat welding, friction welding, or mechanical crimping to secure goods during transport and storage; typical systems operate at tensions between 400 and 2,500 newtons depending on load weight and strap specification. Automatic architectures lead volume shipments as labor-cost escalation pushes warehouse operators toward unattended pallet closure, while mobile units represent the fastest-expanding configuration category due to flexibility demands in third-party logistics yards where dock layouts change seasonally. Heat-seal technology occupies the dominant technology position because of joint reliability under vibration, though strapping retains substantial share in heavy-industrial applications where steel strap withstands sharp-edged loads.
OSHA guidelines in the United States mandate guarding and emergency-stop integration on powered strapping equipment, pushing manufacturers toward sensor-rich designs that reduce liability exposure. The EU Machinery Directive and CE marking requirements enforce documented risk assessments and conformity procedures that filter out low-cost imports lacking technical file support. REACH compliance on chemical composition of polypropylene and polyester strap materials shapes raw-material sourcing decisions for European producers. Stakeholders must monitor how California's SB 54 extended producer responsibility framework and analogous state-level packaging laws in the US reshape material specifications and end-of-life collection obligations for plastic strapping.
Market Dynamics
E-commerce fulfillment velocity is compressing pallet closure cycle times, forcing warehouse operators to abandon semi-automatic equipment in favor of continuous-feed architectures that eliminate operator intervention between loads.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recovery targets for strapping materials are tightening material specifications and accelerating equipment refresh cycles among German automotive exporters.
- Polyester strap chemistry:Advances in tensile strength-to-weight ratios enable lighter strap specifications that reduce material cost per pallet while maintaining load integrity during intermodal transfers.
- Third-party logistics yard flexibility:Seasonal dock reconfigurations in European distribution hubs are pulling mobile banding configurations into the fastest-expanding equipment category.
Market Restraints
- Steel strap input volatility:Scrap metal price fluctuations and energy-intensive production create margin pressure for heavy-industrial applications where steel remains mandatory for sharp-edged loads.
- REACH compliance burden:Chemical composition documentation for polypropylene and polyester strap materials extends raw-material qualification timelines for European producers sourcing outside the EU.
- Heat-seal technical ceiling:Joint reliability under extreme vibration loads limits heat-seal technology penetration in bulk chemical and mineral transport segments where mechanical crimping dominates.
Strategic Opportunities
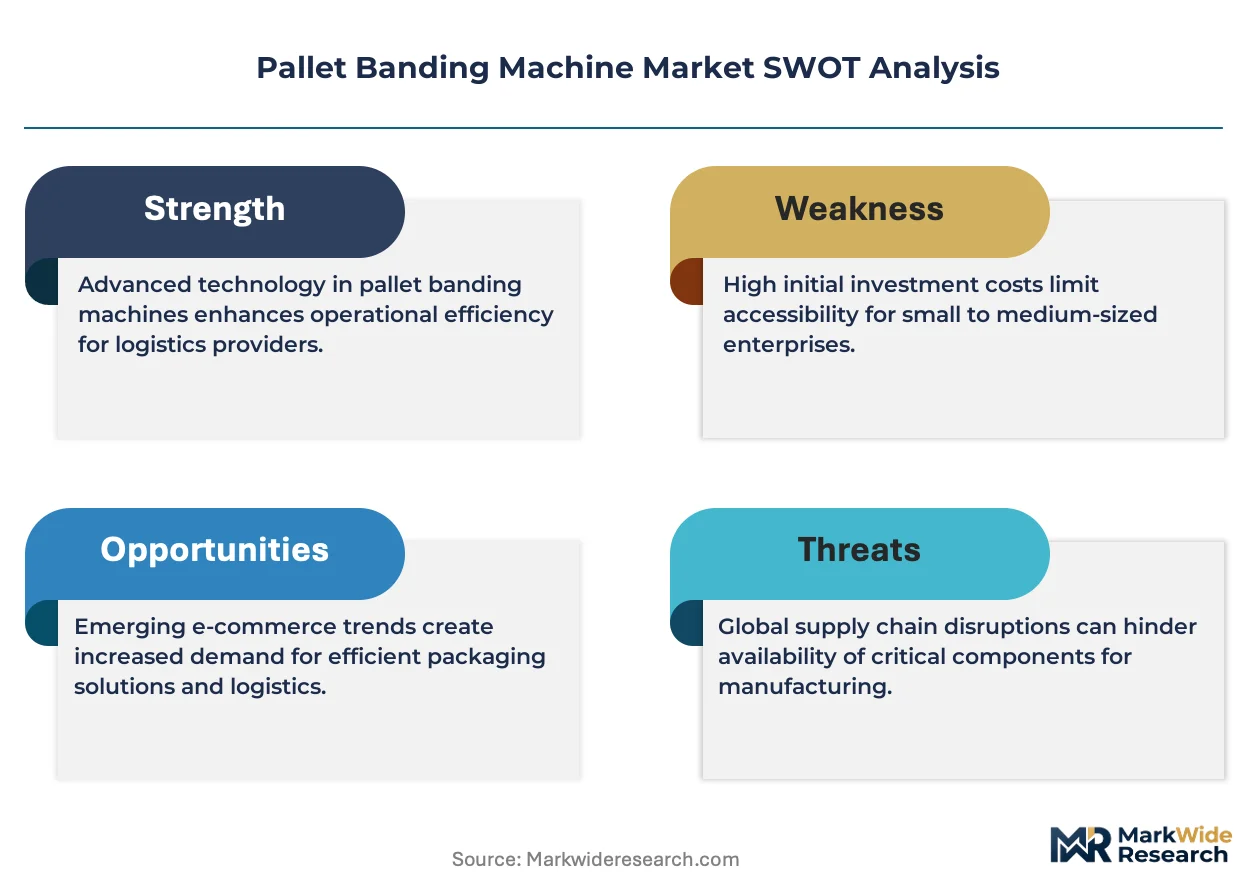
- Retrofit market white space:Modular strapping-head configurations allow facilities to upgrade existing conveyor lines rather than replace entire systems, capturing capital-constrained mid-tier warehouses.
- California SB 54 extended producer responsibility:State-level packaging laws in the US are reshaping material specifications and creating aftermarket service demand for collection infrastructure.
- Servo-driven sealing convergence:Integration of precision motor control with sensor-based tension monitoring enables predictive maintenance models that unbundle traditional service contracts.
Industry Challenges
- CE marking technical file gaps:Low-cost imports lacking documented risk assessments and conformity procedures are filtering into distribution channels, creating liability exposure for integrators.
- Legacy system integration friction:Sensor-rich designs mandated by OSHA guarding requirements conflict with older warehouse management system architectures that lack real-time data handshakes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Banding Machine Market |
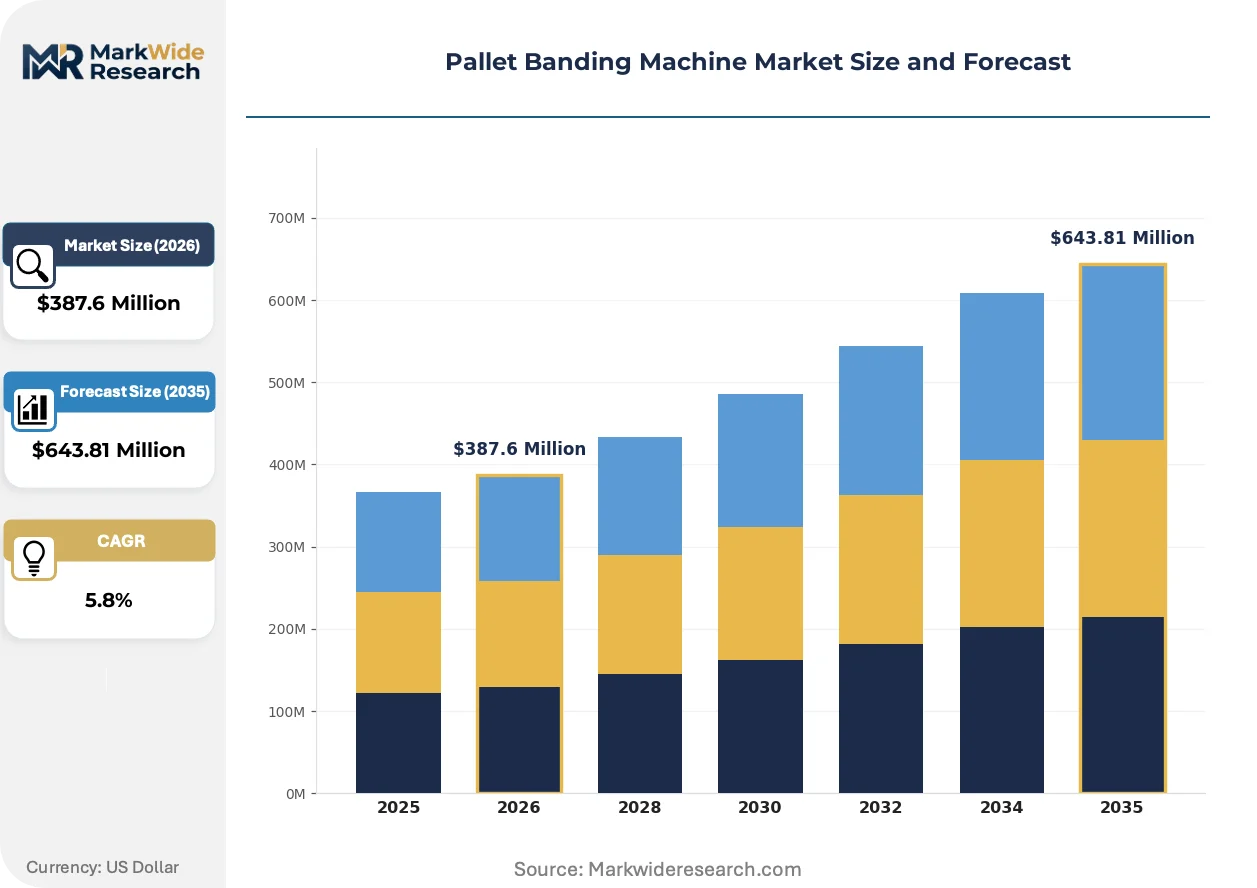
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Mobile End User: Logistics, Warehousing, Manufacturing, Retail Technology: Heat Seal, Heat Shrink, Stretch Film, Strapping Capacity: Low, Medium, High, Custom |
| Companies Covered | Signode Industrial Group LLC, Mosca GmbH, FROMM Packaging Systems, StraPack Inc., Dynaric Inc., Samuel Strapping Systems, Transpak Equipment Corp., Strapex AG, MAILLIS GROUP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Banding Machine Market Evolving Landscape
Equipment architectures are fragmenting along throughput and flexibility axes, with diverging R&D investment patterns between fixed high-speed lines and reconfigurable mobile units serving volatile logistics environments.
Servo-driven tension control is modularizing the strapping-head subsystem, enabling food and beverage lines to swap sealing modules without conveyor downtime. High-volume bottling facilities in Germany are adopting these configurations fastest, compressing the traditional 7-10 year replacement cycle into 3-5 year upgrade intervals that favor component suppliers over system integrators.
REACH chemical composition requirements are forcing strap manufacturers to document polymer chain structures and additive packages across the supply chain. European producers are responding by consolidating sourcing within REACH-compliant zones, while non-EU suppliers face extended qualification timelines that advantage incumbent regional producers with established technical files.
After-sales service unbundling is disrupting the traditional bundled maintenance model. North American warehouse operators are separating preventive maintenance contracts from parts supply, favoring third-party service providers with multi-brand capability over OEM captive service networks. This pattern is most visible in California and Texas logistics corridors where operator labor mobility accelerates vendor switching.
Pallet Banding Machine Market Segmentation
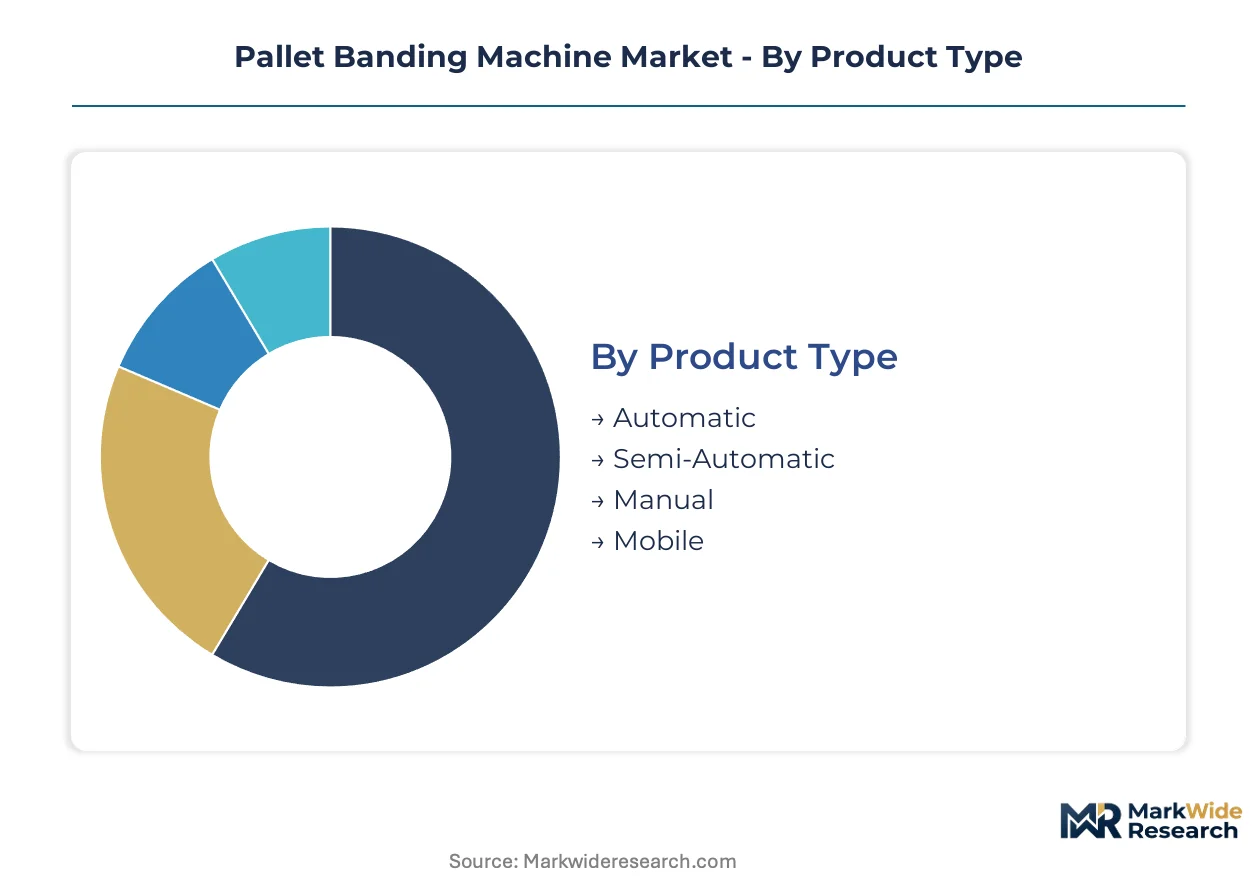
Pallet banding equipment varies sharply in capital intensity and operational integration. Procurement decisions hinge on throughput requirements, labor cost structures, and the degree of conveyor-line embedding.
Product Type:
Standalone units dominate retrofit installations where existing material handling infrastructure remains fixed. Embedded architectures penetrate greenfield fulfillment centers with synchronized conveyor controls.
- Automatic:Continuous-feed architectures eliminate operator intervention between loads through sensor-activated strap dispensing and tensioning. German automotive exporters and high-velocity e-commerce fulfillment centers in the Netherlands drive specifications toward 60+ pallets per hour throughput.
- Semi-Automatic:Requires operator initiation for each cycle but automates tensioning and sealing. Mid-tier warehousing operations in France and Poland favor this tier for mixed-SKU environments where load variability exceeds automatic system calibration ranges.
- Manual:Hand-held tensioners and sealers serve low-volume applications with minimal capital budgets. Small-scale retail distribution in rural Spain and Italy maintains this segment through third-party maintenance networks.
- Mobile:Battery-powered units on casters reconfigure with seasonal dock layouts. Third-party logistics yards across Belgium and the UK pull this configuration fastest as flexibility demands outpace fixed-line investments.
Automatic systems lead volumes today; mobile configurations are gaining share fastest.
End User:
Cost-to-serve profiles diverge across customer types, with contract terms and service bundling varying by operational scale and technical sophistication.
- Logistics:Asset-light third-party operators prioritize equipment mobility and rapid reconfiguration. Seasonal volume spikes in German parcel hubs drive short-term rental models over capital purchases.
- Warehousing:Dedicated distribution centers favor fixed automatic lines with predictive maintenance contracts. Temperature-controlled facilities in the Netherlands specify corrosion-resistant strapping heads for frozen food environments.
- Manufacturing:In-house palletization at automotive and chemical plants demands steel-strap compatibility for sharp-edged loads. REACH-compliant polyester alternatives are penetrating lighter-load segments in French automotive supply chains.
- Retail:Store-backroom operations and regional distribution centers balance capital constraints with throughput needs. Italian grocery chains favor semi-automatic units for promotional surge handling.
Warehousing commands the largest installed base; logistics represents the steepest expansion trajectory.
Technology:
Joint reliability under vibration and environmental exposure determines technology selection, with chemistry and mechanical engineering constraints filtering options by application severity.
- Heat Seal:Friction-welded polymer joints dominate food and beverage lines where vibration resistance prevents load shift. German bottling facilities specify servo-driven heat-seal modules with real-time tension monitoring.
- Heat Shrink:Film-based unitization competes in lightweight, uniform-load segments. Pharmaceutical distribution in Switzerland favors shrink systems for contamination-sensitive cleanroom environments.
- Stretch Film:Elastic film wrapping penetrates produce and irregular-load applications where strap tension risks product damage. Dutch agricultural exporters maintain substantial stretch-film banding hybrid systems.
- Strapping:Mechanical crimping of steel or polyester strap retains dominance in bulk chemical and mineral transport. Sharp-edged metal loads in Swedish steel distribution mandate steel-strap mechanical sealing.
Heat seal occupies the dominant position; strapping retains the highest value per unit in heavy-industrial niches.
Capacity:
Volume tiering reflects capital availability and throughput predictability, with custom specifications capturing complex load geometries that standard equipment cannot accommodate.
- Low:Entry-level pneumatic and manual systems serve single-shift operations with fewer than 200 pallets daily. Small metal fabricators in Portugal specify low-capacity units for intermittent export shipments.
- Medium:Mid-range electric systems balance acquisition cost with 400-800 pallet daily throughput. Regional distribution centers in Austria and Czechia concentrate demand in this tier.
- High:Continuous-duty architectures with redundant strapping heads target 24/7 operations. Automated grocery fulfillment in the UK and Germany drives high-capacity specifications with sub-30-second cycle times.
- Custom:Engineered solutions for oversized, hazardous, or temperature-extreme loads. Nuclear logistics in France and cryogenic chemical transport in Belgium require custom tension and sealing configurations.
Medium capacity leads current shipments; custom systems command the highest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pallet banding machine industry traces its industrial lineage to post-war Germany, where automated strapping systems first scaled to serve the Ruhr Valley's coal and steel distribution networks. Equipment architectures subsequently diffused through Western European manufacturing corridors before establishing production footholds in North American automotive hubs and East Asian export manufacturing zones.
Germany
Automotive exporters in Stuttgart and Wolfsburg maintain dense palletization networks that compress equipment replacement cycles to 3-5 years. The EU Machinery Directive enforces CE marking with documented risk assessments that filter non-compliant imports. Bavarian food and beverage bottlers in Munich's hinterland specify servo-driven heat-seal modules with real-time tension monitoring for 60+ pallets per hour throughput.
United States
E-commerce fulfillment velocity in California and Texas logistics corridors pushes warehouse operators toward continuous-feed automatic architectures. OSHA mandates guarding and emergency-stop integration on powered strapping equipment, driving sensor-rich designs that reduce liability exposure. Chicago's Midwest distribution hub concentrates demand for high-capacity systems serving 24/7 grocery fulfillment operations.
Netherlands
Temperature-controlled facilities in Rotterdam's port zone specify corrosion-resistant strapping heads for frozen food environments. REACH compliance on chemical composition of polypropylene strap materials shapes raw-material sourcing decisions for European producers. Dutch agricultural exporters in the Noord-Brabant region maintain substantial stretch-film banding hybrid systems for produce handling.
China
Export manufacturing clusters in Guangdong and Zhejiang provinces drive volume demand for medium-capacity electric systems balancing acquisition cost with throughput. The country's national quality regulator enforces GB standards on industrial machinery safety that parallel CE marking requirements. Yangtze River Delta logistics hubs are pulling mobile banding configurations for seasonal dock reconfigurations.
United Kingdom
Automated grocery fulfillment centers in the Midlands and Southeast England specify high-capacity architectures with sub-30-second cycle times. The Health and Safety Executive aligns powered equipment regulations with EU Machinery Directive principles post-Brexit. Third-party logistics yards in the East Midlands gateway region favor mobile units for flexibility in volatile freight volumes.
Pallet Banding Machine Market Competitive Landscape
The competitive structure tilts toward technology-differentiated specialists rather than scale-driven generalists. Regional champions with captive component production coexist alongside modular subsystem suppliers that retrofit existing conveyor infrastructure. Three archetypes dominate: servo-driven sealing technology leaders, vertically integrated strap-and-equipment producers, and aftermarket service network operators with multi-brand maintenance capability. Geographic expansion through distribution partnerships and technology licensing for localized production represent the dominant competitive vectors.
Among German-origin precision engineering specialists, Mosca GmbH and Strapex AG exemplify the servo-driven technology tier that commands premium positioning in high-velocity food and beverage lines. Signode Industrial Group LLC anchors the North American installed base through extensive field-service networks. FROMM Packaging Systems occupies a position among integrated producers with captive polyester strap manufacturing ensuring supply continuity across European channels.
| Leading Market Players |
|---|
| Signode Industrial Group LLC |
| Mosca GmbH |
| FROMM Packaging Systems |
| StraPack Inc. |
| Dynaric Inc. |
| Samuel Strapping Systems |
| Transpak Equipment Corp. |
| Strapex AG |
| MAILLIS GROUP |
| Others |
Value Network & Pricing Analysis
REACH compliance documentation gates both qualified raw-material supply and premium-tier equipment pricing access in European pallet banding markets. German automotive exporters absorb cost premiums for REACH-certified polyester strap and servo-driven sealing modules, while uncertified imports face extended qualification timelines that compress their addressable market to price-sensitive segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates servo-driven heat-seal systems from pneumatic semi-automatic units from entry-level manual equipment. Price differentiation hinges on CE marking certification tier and after-sales service bundling intensity. Pricing pressure stems from steel scrap volatility eroding margins in heavy-industrial steel-strap applications. Third-party logistics operators exhibit highest price sensitivity due to asset-light business models, whereas German food and beverage bottlers prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
CE marking and REACH technical file requirements filter out low-cost Asian imports that lack documented risk assessments and polymer chain documentation. Equipment manufacturing concentrates in Germany, Italy, and China, while polyester strap resin sourcing draws from Belgium, the Netherlands, and South Korea. Supply chain risk centers on single-source vulnerability for high-tensile specialty strap grades. Distribution runs through captive OEM service networks in automotive corridors and multi-brand aftermarket providers in logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through predictive maintenance unbundling and servo-driven module upgrade cycles that compress replacement intervals. Component suppliers capture value migration from system integrators as facilities favor retrofit over greenfield investment.
For Market Incumbents: Anchor aftermarket revenue through sensor-rich predictive maintenance contracts that reduce third-party service encroachment. Deepen backward integration into REACH-compliant polyester strap production to defend margin position against resin price volatility. Prioritize certification investment in California SB 54 extended producer responsibility frameworks to lock in West Coast logistics corridor access.
For New Entrants and Emerging Players: Servo-driven sealing convergence with real-time tension monitoring offers entry wedge into mid-tier warehousing segments underserved by Mosca and Signode. Target mobile banding configurations in Belgian and UK third-party logistics yards where seasonal dock reconfiguration demands outpace incumbent response capacity. Pursue rental-service go-to-market models that convert capital-constrained operators from purchase to operating expenditure structures.
For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket service networks with multi-brand capability because warehouse operator labor mobility accelerates vendor switching and fragments OEM captive service penetration. Five-to-ten year viability favors consolidators of third-party maintenance providers in California and Texas logistics corridors. Watch for inflection in steel scrap price stabilization that would signal margin recovery timing for heavy-industrial equipment portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyester Strap Production | REACH-compliant captive supply secures margin protection against resin qualification delays. |
| Predictive Maintenance Platform Launch | Sensor-based tension monitoring unbundles traditional service contracts and locks in recurring revenue. |
| Mobile Configuration Portfolio Expansion | Battery-powered castor-mounted units capture seasonal flexibility demand in third-party logistics yards. |
| CE Marking Technical File Investment | Documented risk assessments filter low-cost imports and defend premium positioning in German automotive. |
| California SB 54 Compliance Certification | Extended producer responsibility alignment opens state-level packaging law opportunities in West Coast corridors. |
Research Methodology
Multiple input streams — maintenance director interviews, plant engineer consultations, OEM procurement team discussions, and aftermarket service head surveys — were reconciled against customs trade data, EU Machinery Directive filings, and SEC equipment manufacturer disclosures. Primary fieldwork across German automotive exporters, Dutch temperature-controlled facilities, and Texas logistics corridors informed demand-side calibration. Secondary validation drew from OSHA enforcement records, REACH chemical registration databases, and e-commerce fulfillment capex tracking. Bottom-up equipment shipment tallies and top-down industrial automation spend estimates were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against expert panel input on retrofit versus replacement propensity across the projection horizon. Segmentation modeling spanned product architecture, capacity tier, technology type, end-use vertical, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of annual shipment data adjusted for equipment replacement cycle compression. Industry-specific forecast inputs included German automotive export volume correlation and e-commerce fulfillment center buildout pipeline tracking.
The model holds under stable REACH enforcement intensity and continued EU Machinery Directive alignment in post-Brexit UK; deviation in scrap metal price volatility or California SB 54 implementation pace would shift equipment mix assumptions. Forecasts reflect documented base-case conditions regarding labor cost escalation and seasonal logistics flexibility demand. A model refresh is warranted upon material change in EU Packaging and Packaging Waste Regulation recovery target timelines or OSHA sensor-mandate expansion scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Europe Palletizer Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Middle East and Africa Lumber Pallet Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
Palletizer Market
Pallets Packaging
Foldable Pallet Container Market
Pallets Packaging
Canada Pallets Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Composite Pallet Market