
 Hand-Held Capping Machines Market | 2026-2036
Hand-Held Capping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
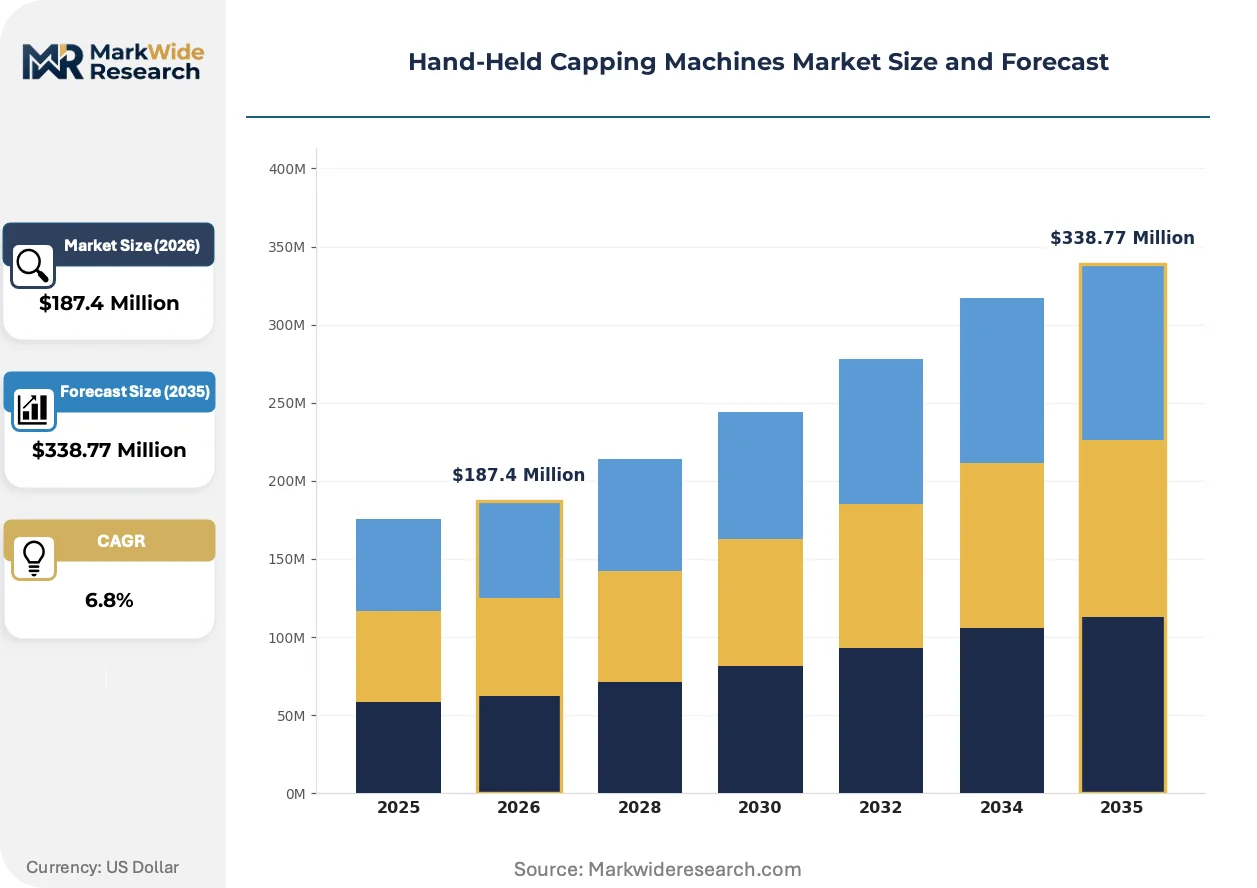
Hand-Held Capping Machines Market Outlook
Aftermarket service revenue is reshaping profitability in the hand-held capping machines landscape as OEMs extend recurring revenue streams beyond hardware sales. Accutek Packaging Equipment Companies, Inc. leverages its California manufacturing base to anchor North American distribution networks for spare parts and field calibration. Spheretech Packaging India Private Limited dominates price-sensitive emerging markets with localized assembly and regional service depots. Kinex Cappers specializes in pharmaceutical-grade validation documentation that sustains premium positioning against lower-cost alternatives.
Hand-held capping machines are portable torque-application devices designed to seal containers with threaded closures, typically operating at torque ranges from 5 to 200 inch-pounds depending on cap diameter and material composition. These units serve primary industrial purposes in small-batch production, laboratory settings, and contract packaging operations where changeover speed outweighs throughput volume. Electric cappers command the widest addressable market due to their repeatability and reduced operator fatigue, while servo-driven technology captures the fastest expansion as precision requirements tighten in pharmaceutical and cosmetics packaging. Manual cappers retain durable demand in developing manufacturing economies and remote field operations where power infrastructure remains inconsistent.
FDA cGMP guidelines and EU MDR traceability requirements compel pharmaceutical packagers to document torque validation data, directly elevating demand for calibrated hand-held units with digital readout capabilities. OSHA ergonomic standards in the United States and REACH material compliance through ECHA in Europe further constrain supplier design choices around handle polymers and lubricant chemistries. Stakeholders must monitor evolving serialization mandates and material disclosure rules across multiple jurisdictions to anticipate specification shifts before they disrupt procurement cycles.
Market Dynamics
Serialization mandates under EU MDR and FDA track-and-trace rules are compressing procurement cycles for pharmaceutical-grade hand-held cappers, forcing contract packagers to prioritize validation documentation over unit economics.
Growth Catalysts
- EU MDR traceability mandates:Pharmaceutical packaging lines in Germany must document torque validation data, elevating demand for calibrated digital-readout units.
- Small-batch flexibility:Contract packaging services across India and the United States now favor portable cappers over fixed automated lines for serialization runs.
- Servo-driven precision:Tightening torque tolerances in cosmetics and pharma applications accelerate replacement of pneumatic units with servo-electric systems.
Market Restraints
- Lithium battery supply concentration:Electric cappers depend on cell supplies concentrated in East Asian manufacturing clusters, exposing OEMs to input volatility.
- REACH material compliance:ECHA disclosure rules constrain handle polymer and lubricant chemistries, extending R&D timelines for European market entry.
- Fixed automated line substitution:High-volume pharma operations above 500 units per minute increasingly bypass hand-held units entirely.
Strategic Opportunities
- Indian contract packaging expansion:CDSCO serialization deadlines create immediate demand for validated portable cappers in Mumbai and Hyderabad clusters.
- Field calibration services:Aftermarket revenue streams through regional service depots capture margin otherwise lost to low-cost hardware competitors.
- Cosmetics cleanroom applications:ISO 14644-1 compliant portable cappers penetrate premium skincare packaging where changeover frequency exceeds throughput requirements.
Industry Challenges
- Torque validation technician scarcity:FDA cGMP documentation requirements outpace trained calibration specialist availability in mid-sized contract packagers.
- Legacy system integration friction:Digital readout cappers must interface with established MES and ERP platforms without disrupting serialization data flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand-Held Capping Machines Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Cappers, Manual Cappers, Semi-Automatic Cappers, Electric Cappers End User: Food & Beverage, Pharmaceutical, Cosmetics, Chemical Technology: Servo-Driven, Pneumatic, Mechanical, Hydraulic Application: Bottling, Jarring, Canning, Tubing |
| Companies Covered | Accutek Packaging Equipment Companies, Inc., Swan-Matic Bottle Capping Machines and Equipment, Kinex Cappers, Apacks Packaging, Inc., The CARY Company, Medi-Pack Process and Technologies, Inc., Spheretech Packaging India Private Limited, Quick Capper, Capper & Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand-Held Capping Machines Market Strategic Shifts
Digital torque logging and cloud-connected calibration protocols are compressing the gap between portable cappers and fixed-line validation systems, reshaping how contract packagers justify equipment procurement.
Cloud-based torque data logging is virtualizing the documentation burden that previously required dedicated validation hardware. Pharmaceutical contract packagers in Germany and the United States are adopting these systems at twice the rate of cosmetics manufacturers. This technology is virtualizing the distinction between portable and fixed-line equipment in compliance audits, allowing hand-held units to substitute for automated lines in serialized batch records.
EU MDR Article 16 and FDA DSCSA enforcement timelines are synchronizing procurement decisions across Atlantic pharmaceutical networks. The industrial consequence is compressed vendor qualification periods and pre-purchased calibration service contracts. Small-batch biologics packagers in Switzerland and Massachusetts are responding by specifying cappers with embedded digital certificates traceable to national metrology institutes.
Equipment-as-a-service models are displacing outright purchase in North American contract packaging. Regional service depots now bundle calibration, spare parts, and firmware updates into per-unit-sealed pricing. This shift is most visible in California and New Jersey clusters where serialization mandates have elevated total cost of ownership calculations above capital expenditure thresholds.
Hand-Held Capping Machines Market Segmentation
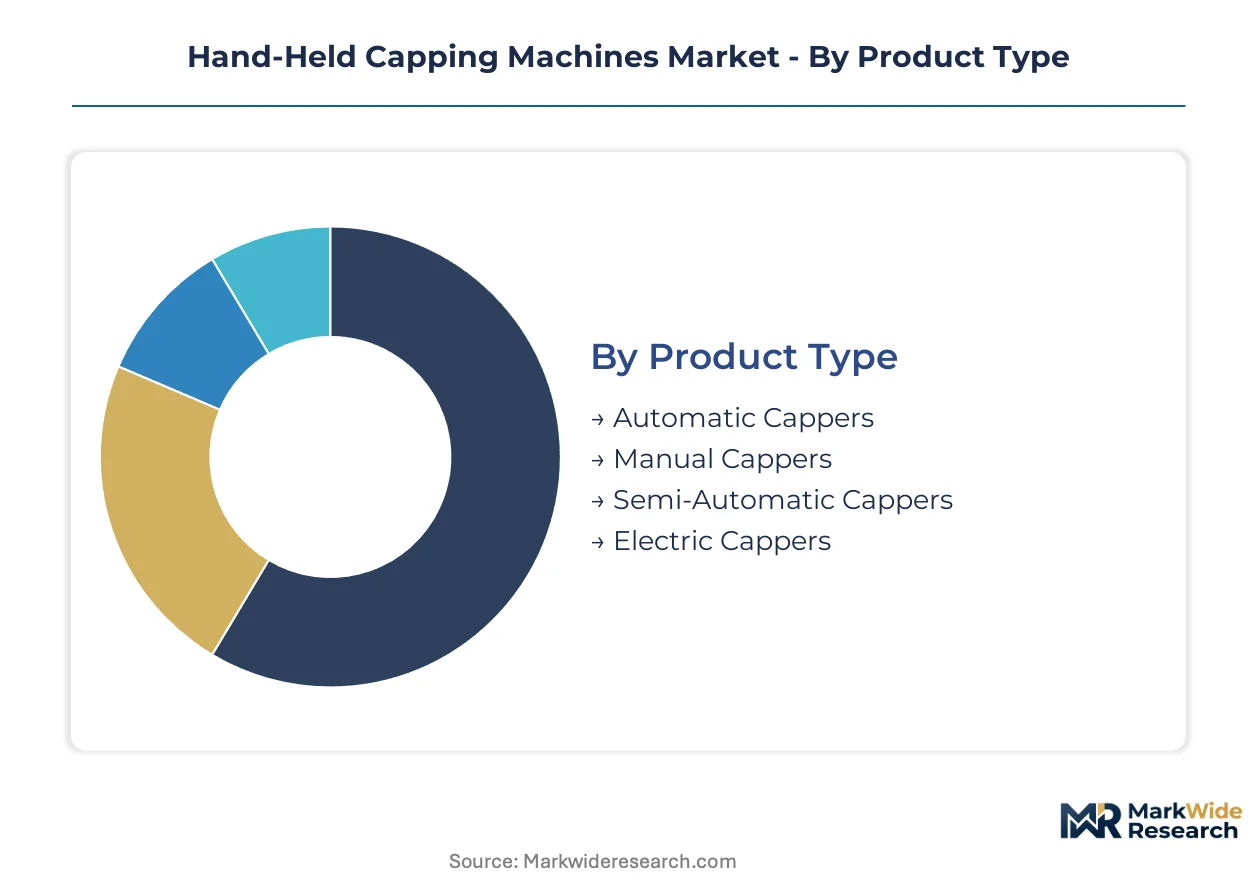
Segmentation in hand-held capping machines reveals distinct service intensity profiles across product architectures. Electric and servo-driven units generate recurring calibration revenue streams that manual alternatives cannot match, reshaping how OEMs allocate regional service depot investments.
Product Type:
After-sales service intensity varies sharply across product architectures, with electric and servo-driven units demanding quarterly calibration cycles that manual cappers never require.
- Electric Cappers:Battery-powered torque application systems operating at 5-200 inch-pounds with digital readout capabilities. Demand concentrates in German pharmaceutical contract packaging facilities where FDA cGMP documentation requirements mandate traceable torque validation records for every sealed container.
- Servo-Driven Cappers:Closed-loop motor control enables ±1% torque repeatability for critical pharmaceutical and cosmetics applications. Swiss biologics packagers and Massachusetts contract manufacturers specify these units for serialization runs where deviation logs must withstand regulatory audit scrutiny.
- Manual Cappers:Hand-operated mechanical devices serving remote field operations and developing manufacturing economies with inconsistent power infrastructure. Indian rural packaging cooperatives and Indonesian spice processors represent core demand pockets.
- Semi-Automatic Cappers:Hybrid systems combining manual container handling with powered torque application. Mexican beverage bottlers and Brazilian chemical repackagers favor these for mid-volume runs below automated line thresholds.
- Automatic Cappers:Trigger-activated portable units with preset torque limits. Japanese precision electronics manufacturers deploy these for cleanroom component packaging requiring contamination-controlled sealing protocols.
Electric cappers hold the largest share; momentum sits with servo-driven systems as torque tolerances tighten in pharmaceutical serialization mandates.
End User:
Cost tier stratification separates end-use segments, with pharmaceutical validation requirements commanding 3-4x hardware premiums over food-grade alternatives.
- Pharmaceutical:Serialization compliance under EU MDR and FDA DSCSA drives specification of calibrated digital-readout units with embedded metrology certificates. German packaging lines and Swiss biologics facilities represent concentrated procurement.
- Cosmetics:Premium skincare and cleanroom applications demand ISO 14644-1 compliant portable cappers with stainless steel housings. French luxury brands and South Korean beauty manufacturers lead specification intensity for changeover-flexible sealing equipment.
- Food & Beverage:High-volume bottling operations favor semi-automatic and electric units for sauce, condiment, and beverage packaging. Italian artisanal producers and Californian specialty food startups drive demand for portable alternatives to fixed lines.
- Chemical:Corrosion-resistant sealing for agrochemical and industrial solvent containers requires specialized polymer seals and vented closure systems. Brazilian agricultural chemical repackagers and Indian pesticide formulators represent price-sensitive volume demand.
Pharmaceutical applications command premium pricing tiers; cosmetics represents the steepest expansion trajectory as cleanroom skincare packaging proliferates.
Technology:
Volume concentration patterns distinguish technology categories, with mechanical systems saturating low-cost emerging markets while precision alternatives capture regulated segments.
- Servo-Driven:Microprocessor-controlled torque application with real-time feedback loops enabling closed-loop validation. Massachusetts medical device packagers and Bavarian pharmaceutical contractors specify these for FDA submission documentation.
- Pneumatic:Compressed-air torque systems offering lower capital cost but higher operating variability. Mexican contract packaging clusters and Thai beverage bottlers maintain installed bases despite accelerating electric substitution.
- Mechanical:Spring-clutch or slip-clutch designs without power dependency. Nigerian food processors and Bangladeshi pharmaceutical repackagers sustain demand where grid reliability remains intermittent.
- Hydraulic:Fluid-pressure torque multiplication for high-torque industrial closures. German chemical drum sealing operations and Texas oilfield chemical packaging represent niche heavy-duty applications.
Servo-driven systems gain share fastest; mechanical technology retains durable demand in power-constrained operating environments.
Application:
Customer type differentiation shapes application segments, with contract packagers driving portable equipment demand against captive manufacturer preference for fixed lines.
- Bottling:Threaded closure sealing for glass and plastic containers across beverage, pharmaceutical, and chemical sectors. Indian contract packaging services in Mumbai and Hyderabad clusters prioritize portable cappers for serialization compliance flexibility.
- Jarring:Wide-mouth container sealing for sauces, preserves, and cosmetic creams. Italian specialty food producers and French artisanal cosmetics manufacturers specify adjustable torque units for mixed-format production.
- Canning:Metal closure crimping and sealing for food preservation and industrial chemical containment. Spanish seafood processors and Portuguese olive oil cooperatives maintain manual capping traditions alongside modernized electric alternatives.
- Tubing:Flexible container sealing for creams, gels, and semi-solid pharmaceuticals. Swiss dermatological manufacturers and New Jersey topical drug packagers drive demand for precision torque control in laminate tube applications.
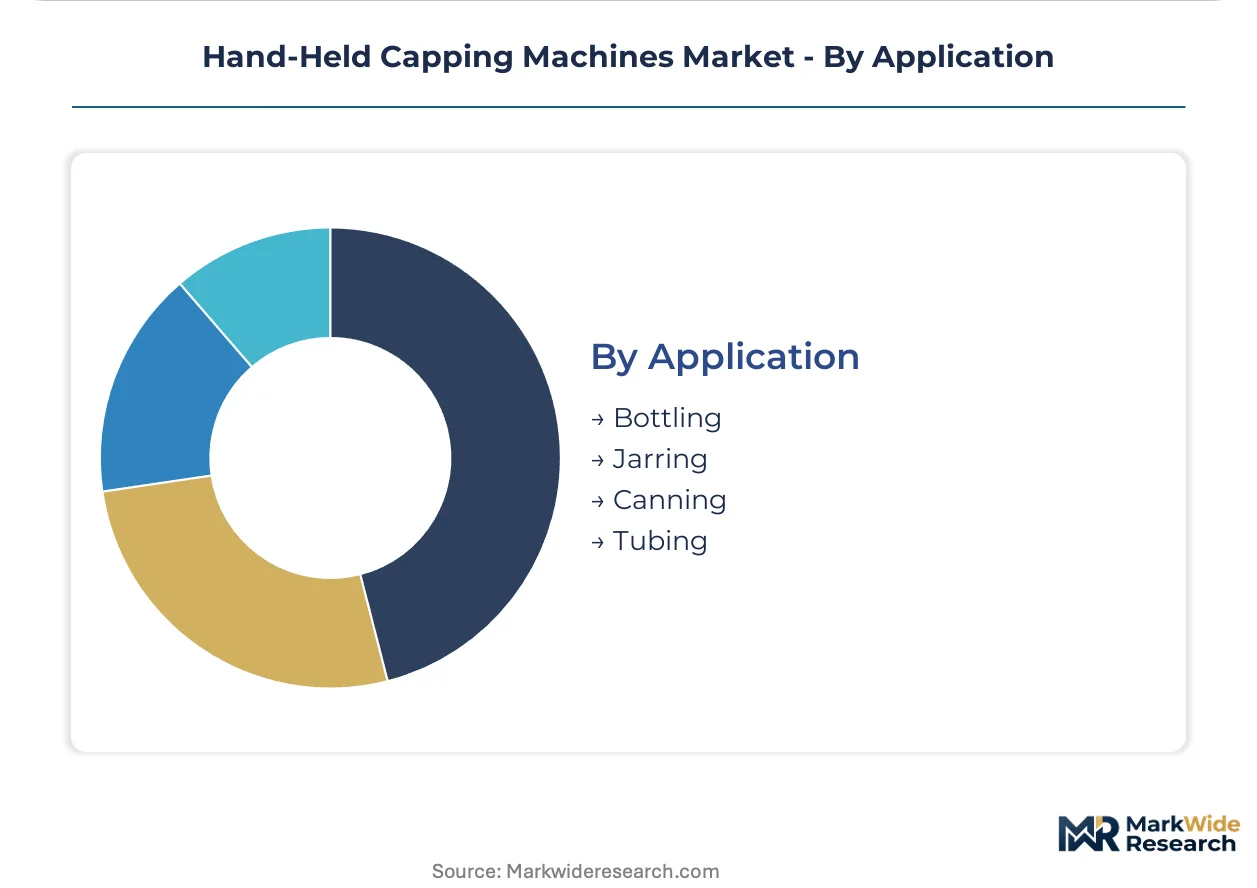
Bottling applications dominate unit volume; tubing represents the fastest-climbing segment as topical drug delivery formats expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Indian contract packagers prioritize unit economics and localized service networks, while German pharmaceutical facilities absorb 3-4x hardware premiums for validated documentation capabilities.
United States
California and New Jersey contract packaging clusters drive procurement of equipment-as-a-service models bundling calibration and firmware updates. FDA DSCSA enforcement compresses vendor qualification timelines. Massachusetts biologics packagers specify servo-driven units with embedded metrology certificates for serialization compliance.
Germany
Bavarian pharmaceutical contractors anchor European demand for digital-readout cappers with traceable torque validation. EU MDR Article 16 mandates synchronize procurement decisions across Atlantic networks. Stuttgart-area packaging lines pre-purchase calibration service contracts to meet compressed audit schedules.
India
Mumbai and Hyderabad contract packaging clusters prioritize portable cappers for CDSCO serialization deadline compliance. Price-sensitive procurement favors localized assembly and regional service depots over premium imported alternatives. Rural packaging cooperatives sustain manual capping demand where grid reliability remains intermittent.
Switzerland
Swiss biologics packagers command premium positioning for precision torque control in small-batch serialization runs. Swissmedic documentation requirements exceed standard EU MDR thresholds. Basel-area facilities specify closed-loop validation systems for FDA submission documentation.
Japan
Tokyo and Osaka precision electronics manufacturers deploy cleanroom-compliant portable cappers for contamination-controlled sealing. METI standards influence regional specification patterns. Nagoya-area automotive chemical packaging operations favor automatic trigger-activated units for mid-volume production.
Hand-Held Capping Machines Market Competitive Environment
Validation-focused specialists and scale-driven fabricators split the market into distinct competitive spheres. The vendor base concentrates around three strategic archetypes: North American full-service OEMs with captive aftermarket networks, Indian price-optimized assemblers with regional depot coverage, and European precision specialists commanding documentation premiums. Dominant competitive moves include geographic expansion through distributor partnerships and backward integration into calibration service capabilities.
Within the North American service-anchored tier, Accutek Packaging Equipment Companies, Inc. exemplifies the California-based manufacturing model supporting spare parts and field calibration networks. Kinex Cappers occupies a position among validation-intensive specialists serving pharmaceutical-grade documentation requirements. Spheretech Packaging India Private Limited represents the emerging-market archetype leveraging localized assembly and regional service depots to capture price-sensitive volume demand across South Asian contract packaging clusters.
| Leading Market Players |
|---|
| Accutek Packaging Equipment Companies, Inc. |
| Swan-Matic Bottle Capping Machines and Equipment |
| Kinex Cappers |
| Apacks Packaging, Inc. |
| The CARY Company |
| Medi-Pack Process and Technologies, Inc. |
| Spheretech Packaging India Private Limited |
| Quick Capper |
| Capper & Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Dongguan battery cell manufacturing clusters anchor electric capper production capacity, with their output fluctuations transmitting directly into OEM pricing power across German pharmaceutical and Indian contract packaging markets. Calibration service bundling now determines lifetime value capture, compressing pure hardware margins while elevating recurring revenue tiers.
Pricing Analysis
Aftermarket service contracts drive lifetime value more than initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated units with embedded metrology certificates from basic electric cappers and manual alternatives. Price differentiation rests on certification grade and geographic service depot density. Cost compression in economy tiers is intensifying because Indian assemblers localize component sourcing. Food and beverage packagers exhibit highest price sensitivity; Swiss biologics facilities absorb premiums for documentation traceability.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for lithium-ion cell procurement. Manufacturing concentrates in China, South Korea, and Japan for battery cells, with precision servo motors sourcing from Germany and Japan. Raw material dependencies include lithium carbonate, neodymium rare earth magnets, and medical-grade stainless steel housings. Single-source vulnerability concentrates in East Asian battery chemistry suppliers. Distribution runs through regional OEM service depots that anchor aftermarket revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates sticky customer relationships. Validation documentation requirements impose switching costs that protect incumbent positions against price-based competition.
For Market Incumbents: Pre-empt emerging Indian price-optimized assemblers by backward integration into calibration service capabilities across Mumbai and Hyderabad clusters. Anchor spare parts inventory in California and New Jersey distribution nodes to compress response times below competitor thresholds. Certification investment in EU MDR and FDA cGMP documentation systems reinforces premium positioning against commoditization pressure. For New Entrants and Emerging Players: Mid-market cosmetics cleanroom applications in South Korea and France represent the most penetrable entry point, as established pharma specialists overlook ISO 14644-1 compliant portable cappers for skincare packaging. Indian rural packaging cooperatives with intermittent grid access sustain durable manual capper demand underserved by electric-focused incumbents. Go-to-market execution through regional distributor partnerships with embedded service capabilities bypasses captive OEM depot networks. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because serialization mandates institutionalize calibration service contracts as operational necessities rather than discretionary purchases. Acquisition targets should display established FDA validation documentation libraries and regional service depot footprints in at least two of Germany, India, and the United States. Watch CDSCO enforcement timeline adherence across Indian contract packagers as inflection indicator for hardware replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calibration Services | Captures margin otherwise lost to third-party metrology providers in FDA-regulated environments. |
| Regional Service Depot Expansion | Mumbai and Hyderabad clusters require localized spare parts inventory to meet CDSCO deadline pressure. |
| Embedded Metrology Certificate Development | Swissmedic and FDA submission documentation demands traceable torque validation from national institutes. |
| Cleanroom Compliance Product Line | South Korean beauty manufacturers specify ISO 14644-1 compliant stainless steel housings for premium skincare. |
| Equipment-as-a-Service Model Launch | California and New Jersey contract packagers prefer per-unit-sealed pricing bundling firmware and calibration. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical packaging line managers, contract packaging procurement leads, OEM aftermarket service directors, and regulatory compliance officers. Secondary validation drew from FDA cGMP guidance documents, EU MDR Article 16 implementation notices, CDSCO serialization circulars, and SEC filings of listed packaging equipment manufacturers. Bottom-up unit demand estimates across German, Indian, and United States clusters were triangulated against top-down market value reconstructions.
Calibration against historical validation documentation adoption curves refined projection parameters across the analysis window. Segmentation dimensions modeled include product architecture, end-use industry, torque precision tier, and regional regulatory cluster. CAGRs were derived from weighted average growth contributions across these segments. Forecast inputs incorporated lithium battery cost trajectories and pharmaceutical serialization mandate enforcement timelines without year-specific anchoring.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or lithium carbonate pricing volatility would shift the trajectory. Forecasts reflect assumptions around regulatory enforcement consistency and supply chain continuity for precision servo components. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Banding Machine Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Bottle Blowing Machine Market
Packaging Machinery
Pillow Packing Machine Market
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Thermal Laminating Machine Market
Packaging Machinery
Sliding Injection Molding Machine Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Laminating Machines Market
Packaging Machinery
Twist Tie Machines Market
Packaging Machinery
Filling Machinery Market
Packaging Machinery
Bagging Machine Market
Packaging Machinery
Sack Fillers Market