
 Filling Machinery Market | 2026-2036
Filling Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Filling Machinery Market Analytics
Modular servo-driven architecture is narrowing the gap between batch and continuous processing lines. Krones AG leverages its German engineering base to dominate high-speed aseptic bottle filling. GEA Group AG sustains leadership in dairy and pharmaceutical liquid handling through precision pump integration. Syntegon Technology specializes in compact monobloc systems for mid-tier beverage producers seeking format flexibility without greenfield investment.
Filling machinery encompasses equipment designed to dispense measured quantities of liquid, powder, paste, or granule products into containers, operating through volumetric, gravimetric, or vacuum-assisted mechanisms with fill accuracies typically within plus or minus one percent. These systems serve as critical nodes in packaging lines across food safety, pharmaceutical sterility, and chemical containment workflows. Liquid fillers command the largest installed base due to beverage and pharmaceutical throughput requirements, while automated technology segments capture the fastest replacement cycle as labor costs rise and lot traceability mandates intensify. Powder fillers retain stable margin pools in infant formula and nutritional supplement applications where containment and cross-batch cleaning protocols justify premium positioning.
FDA cGMP guidelines and EU MDR traceability requirements shape equipment validation protocols and documentation burdens for pharmaceutical-oriented suppliers. REACH chemical safety standards and OSHA lockout-tagout rules further constrain material selection and maintenance access design for chemical filling applications. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal energy efficiency benchmarks redirect capital toward servo-electric actuation and reduced compressed-air dependency in next-generation platform development.
Market Dynamics
Modular servo-electric actuation is compressing the traditional mechanical-pneumatic divide in liquid filling lines, forcing incumbent suppliers to reengineer platform architectures around reduced compressed-air dependency and precision motion control.
Growth Catalysts
- FDA cGMP validation protocols:Pharmaceutical contract manufacturers in the United States are replacing legacy equipment to meet sterility documentation and lot traceability mandates, accelerating replacement cycles for aseptic liquid fillers.
- EU Green Deal energy benchmarks:Compressed-air reduction targets are redirecting capital toward servo-electric filling platforms that cut energy consumption by eliminating pneumatic actuation from bottle handling and pump drives.
- ASEAN beverage bottling clusters:Indonesian and Vietnamese soft-drink producers are automating manual filling operations to meet export-grade hygiene standards and reduce labor dependency in high-throughput lines.
Market Restraints
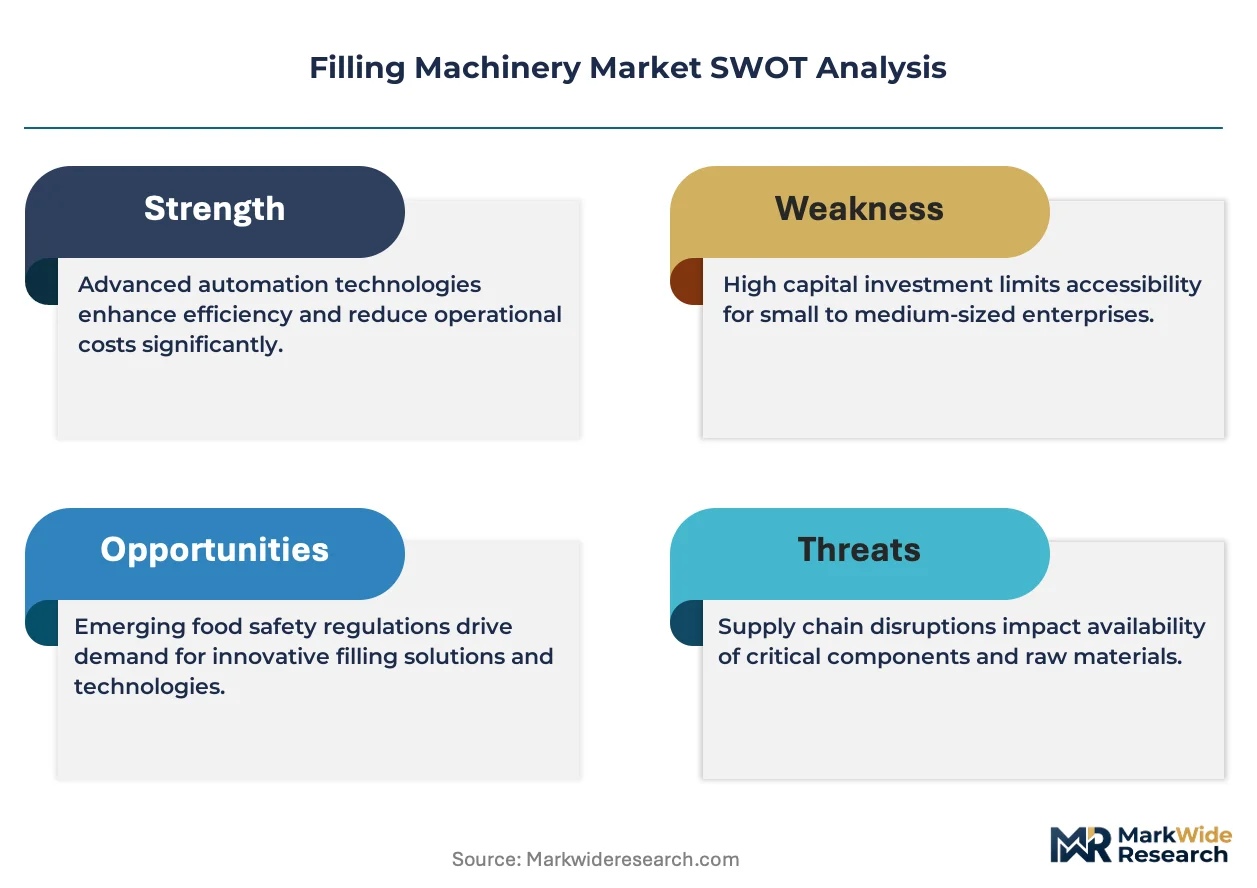
- Stainless steel input volatility:Grade 316L and 304 price swings compress margin stability for equipment fabricators sourcing corrosion-resistant contact surfaces for pharmaceutical and dairy applications.
- German engineering cluster concentration:Precision aseptic filling technology development concentrates in Bavarian and Baden-Württemberg supplier networks, creating geographic supply risk for buyers seeking alternative qualified sources.
- Pneumatic legacy lock-in:Existing compressed-air infrastructure investments in mature beverage plants create technical friction against servo-electric retrofits, extending replacement timelines.
Strategic Opportunities
- Indian pharmaceutical export expansion:CDSCO-aligned contract manufacturing organizations are upgrading to EU MDR-compatible filling lines to capture sterile injectable export contracts to European markets.
- Cell and gene therapy bioprocessing:Closed-system aseptic filling demand from viral vector and CAR-T production facilities is opening specialized equipment categories beyond traditional pharmaceutical liquid handling.
- China dual carbon policy alignment:Provincial energy efficiency mandates are creating procurement preference for servo-driven monobloc systems that reduce factory compressed-air load and qualify for green manufacturing incentives.
Industry Challenges
- Mechatronics engineering scarcity:The intersection of precision motion control, pharmaceutical validation documentation, and hygienic design expertise is concentrating in limited talent pools, constraining R&D velocity for mid-tier suppliers.
- Legacy SCADA integration complexity:Brownfield beverage plants running proprietary Allen-Bradley or Siemens architectures face protocol translation friction when connecting new servo-driven fillers to existing line control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filling Machinery Market |
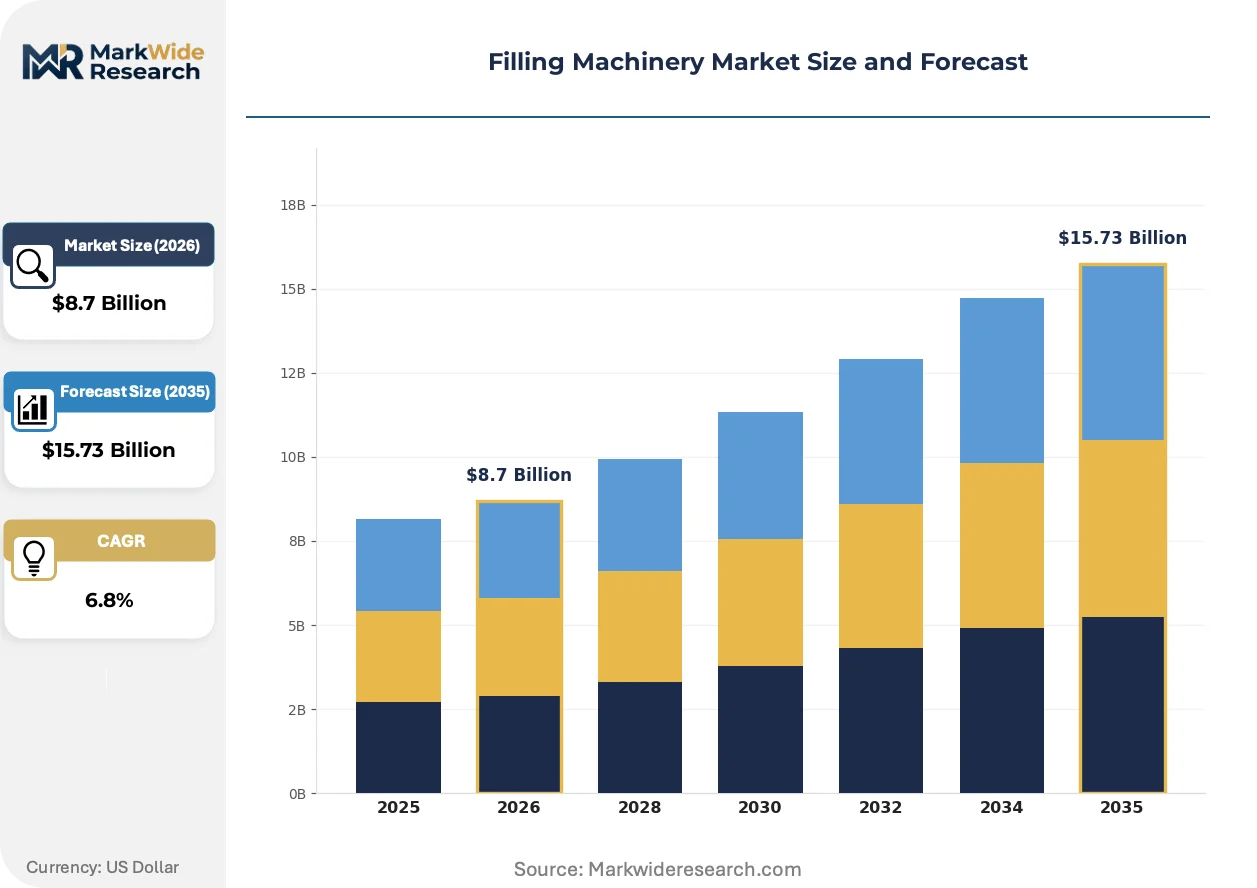
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fillers, Powder Fillers, Paste Fillers, Granule Fillers Technology: Automated, Semi-Automated, Manual, Vacuum End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Packaging Type: Bottles, Pouches, Cans, Buckets |
| Companies Covered | Syntegon Technology, GEA Group AG, Krones AG, JBT Corporation, Barry-Wehmiller Companies Inc, Tetra Laval International, KHS GmbH, Coesia Group, Ronchi Mario SPA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filling Machinery Market Evolving Landscape
Electrification of motion control and validation-data architecture are converging to redefine equipment lifecycle economics, compressing the traditional ten-year replacement horizon for high-volume liquid filling assets.
Magnetic levitation pump technology eliminates mechanical seals and reduces shear stress on biologic formulations. Biopharmaceutical fill-finish contractors in Switzerland and Massachusetts are specifying mag-lev systems for monoclonal antibody and vaccine production. Conventional rotary piston and peristaltic pump architectures are rendering obsolete for high-value sterile applications where particle generation risk must approach zero.
EU MDR Annex I technical documentation requirements are extending equipment qualification timelines for pharmaceutical filling lines sold into European markets. Suppliers must now generate clinical evidence linkages and post-market surveillance protocols that were previously absent from machinery contracts. German and Italian filling equipment manufacturers are restructuring service divisions to provide ongoing compliance support alongside hardware.
Outcome-based service contracting is displacing traditional break-fix maintenance arrangements in beverage bottling operations. Coca-Cola and PepsiCo bottling partners in Mexico and Brazil are piloting throughput-guarantee agreements where suppliers assume operational risk for line efficiency. This procurement evolution concentrates service revenue with OEMs possessing remote diagnostics infrastructure and regional spare-part depots.
Filling Machinery Market Segmentation
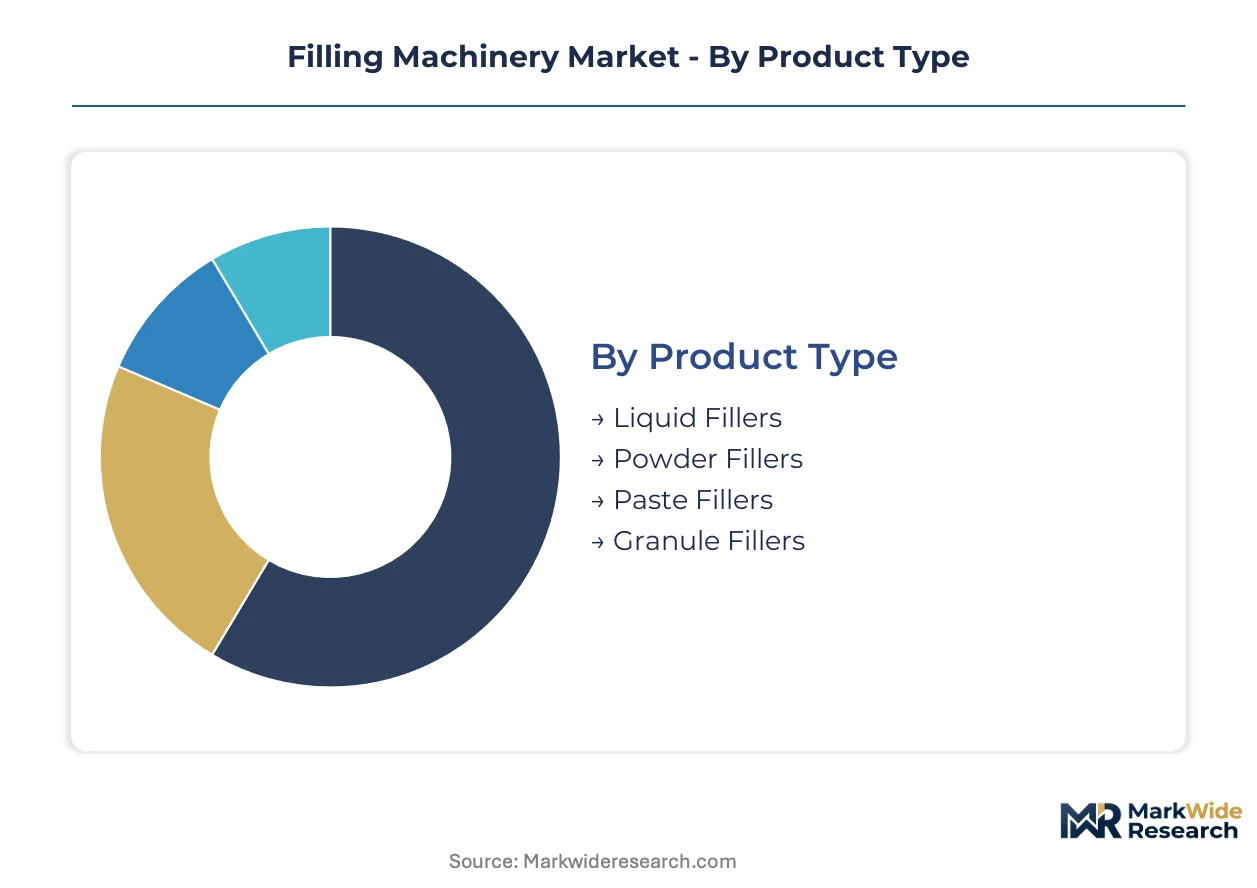
Filling machinery segmentation reveals how equipment specifications align with product rheology, regulatory exposure, and throughput economics. Each dimension—product type, technology, end user, and packaging format—creates distinct procurement criteria and margin structures for suppliers.
Product Type:
Use-case spectrum spans free-flowing liquids to cohesive pastes and free-flowing granules, with viscosity, particle size, and aeration risk determining mechanism selection.
- Liquid Fillers:Volumetric, gravimetric, and vacuum-assisted mechanisms handle Newtonian and non-Newtonian fluids with fill accuracies within plus or minus one percent. Beverage bottling in Germany and pharmaceutical sterile injectable production in Switzerland concentrate demand as FDA cGMP and EU MDR documentation mandates intensify replacement cycles.
- Powder Fillers:Auger, cup, and net-weigh systems manage cohesive and free-flowing powders with containment protocols for hazardous or sterile applications. Infant formula production in the Netherlands and nutritional supplement contract manufacturing in India drive specification toward cross-batch cleaning validation and dust containment.
- Paste Fillers:Piston and pump-based systems handle high-viscosity materials with shear-sensitive or abrasive properties. Cosmetic cream and sauce applications in France specify sanitary design with CIP compatibility.
- Granule Fillers:Multi-head weighers and volumetric cup fillers dispense free-flowing particulates. Snack food and agricultural chemical packaging in Brazil emphasize speed and changeover flexibility.
Established volume favors liquid fillers; emerging adoption favors powder fillers.
Technology:
Capital intensity and labor substitution rates stratify the technology landscape, with energy efficiency and traceability documentation now reshaping procurement priorities.
- Automated:Servo-electric motion control, integrated vision inspection, and SCADA-connected data architecture enable continuous operation with minimal operator intervention. ASEAN beverage bottlers in Indonesia and Vietnam are automating to meet export-grade hygiene standards and reduce labor dependency.
- Semi-Automated:Operator-fed systems with automated dispensing cycles balance throughput and capital outlay for mid-tier producers. Regional dairy processors in Poland and Mexico deploy these for SKU proliferation without full line integration.
- Manual:Hand-operated fillers serve micro-batch production and artisanal positioning where equipment cost must stay below ten thousand dollars. Craft beverage startups in Portugal and specialty sauce producers in Thailand tolerate lower throughput for format flexibility.
- Vacuum:Negative-pressure filling prevents oxidation and foam generation in wine, edible oil, and chemical applications. Italian wine cooperatives and California olive oil producers specify vacuum systems for product integrity.
Procurement momentum concentrates in automated platforms; semi-automated retains share in capital-constrained expansions.
End User:
Regulatory stringency and contamination consequence determine equipment specification tiers across downstream industries.
- Food & Beverage:Hygienic design, CIP/SIP protocols, and allergen management dominate specification. Dairy and ready-to-drink coffee bottling in Germany and soft-drink production in Mexico prioritize servo-electric actuation for energy efficiency and format agility.
- Pharmaceuticals:Aseptic isolation, barrier technology, and FDA cGMP or EU MDR validation documentation command premium positioning. Sterile injectable fill-finish in Switzerland and Massachusetts biotech clusters specifies magnetic levitation pumps to eliminate mechanical seal particle generation.
- Cosmetics:Viscosity range accommodation, decorative container handling, and batch flexibility shape procurement. Premium skincare production in France and South Korea emphasizes gentle product handling and quick changeover.
- Chemicals:Corrosion-resistant construction, explosion-proofing, and containment for hazardous materials define requirements. Agricultural chemical packaging in Brazil and industrial lubricant filling in the United States specify 316L stainless steel and ATEX-compliant electrical enclosures.
Pharmaceuticals command the steepest expansion trajectory; food and beverage retains the largest installed base.
Packaging Type:
Container geometry and material compatibility drive mechanism adaptation and line integration complexity.
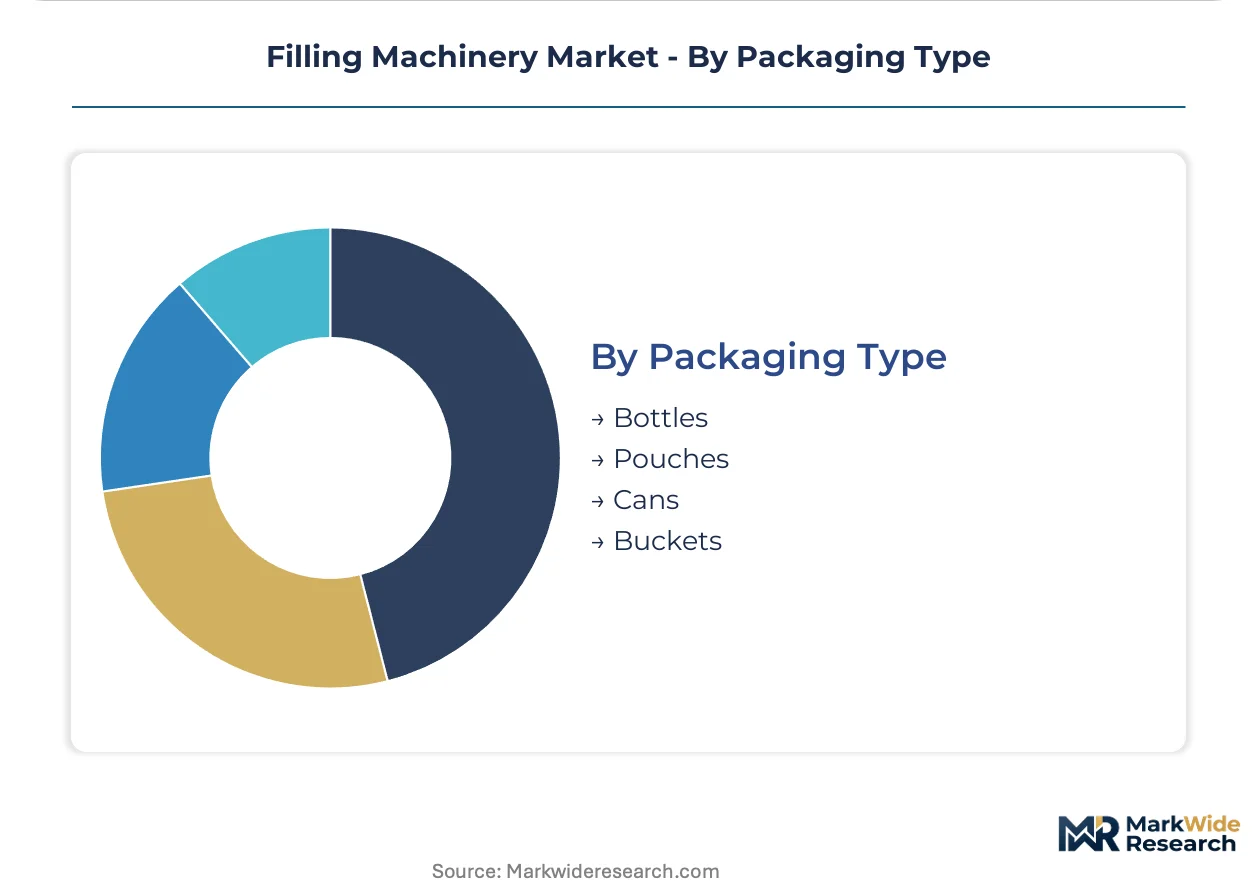
- Bottles:Glass and PET container handling with neck-centered transfer and cap torque control dominates beverage and pharmaceutical applications. German precision-engineered aseptic bottle filling clusters anchor global technology development.
- Pouches:Flexible film handling with spout insertion and seal integrity verification serves liquid and semi-liquid products. Stand-up pouch adoption in Indian dairy and Brazilian juice markets accelerates horizontal form-fill-seal integration.
- Cans:Aluminum and steel container handling with seaming technology integration concentrates in beer and carbonated soft drinks. Craft brewing in the United States and Mexico drives smaller-format canning line demand.
- Buckets:Rigid container filling for industrial and institutional volumes emphasizes net-weigh accuracy and lid placement. Paint and coating production in Italy and lubricant packaging in the United States specify pail filling with drip-free nozzles.
Bottles maintain volume leadership; pouches are climbing the fastest in flexible packaging conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented beverage bottling in Germany and pharmaceutical fill-finish in Switzerland generate machinery trade surpluses, while ASEAN import dependency rises as Indonesian and Vietnamese producers upgrade lines to meet EU hygiene standards.
Germany
Bavarian and Baden-Württemberg engineering clusters anchor precision aseptic filling technology development for global beverage and pharmaceutical export markets. EU Green Deal energy benchmarks redirect capital toward servo-electric platforms that eliminate pneumatic actuation. Krones AG and GEA Group AG concentrate R&D in Stuttgart and Nuremberg metropolitan zones, supplying high-speed bottle filling lines to Mexican and Brazilian bottling partners.
United States
FDA cGMP validation protocols accelerate replacement cycles for aseptic liquid fillers among pharmaceutical contract manufacturers in Massachusetts and North Carolina biotech corridors. OSHA lockout-tagout rules constrain maintenance access design for chemical filling applications. Boston-area viral vector production facilities are specifying closed-system aseptic filling equipment for CAR-T cell therapy manufacturing.
China
Provincial dual carbon policy mandates create procurement preference for servo-driven monobloc systems that reduce factory compressed-air load in Yangtze River Delta beverage plants. MIIT energy efficiency benchmarks qualify efficient equipment for green manufacturing incentives. Shanghai and Jiangsu province dairy processors are automating powder filling lines to meet infant formula export standards.
India
CDSCO-aligned contract manufacturing organizations in Maharashtra and Gujarat upgrade to EU MDR-compatible filling lines to capture sterile injectable export contracts to European markets. FSSAI hygiene mandates tighten for domestic dairy and beverage processing. Ahmedabad and Pune pharmaceutical clusters are installing aseptic isolator technology for lyophilized product fill-finish operations.
Brazil
Agricultural chemical packaging in São Paulo and Minas Gerais emphasizes corrosion-resistant 316L stainless steel construction and ATEX-compliant electrical enclosures. ANVISA pharmaceutical regulations align with FDA cGMP for contract manufacturing export qualification. Campinas industrial corridor hosts beverage bottling automation pilots with throughput-guarantee service contracting from European OEMs.
Filling Machinery Market Competitive Landscape
On the supply side, the industry is consolidating around precision-engineered aseptic technology clusters in Southern Germany while fragmenting across regional fabricators serving capital-constrained mid-tier beverage markets. Three archetypes dominate: German precision-engineering houses with pharmaceutical validation expertise, diversified packaging conglomerates with beverage line integration capabilities, and specialized monobloc fabricators targeting format-flexible mid-market segments. M&A activity concentrates on servo-electric technology acquisition and regional service network expansion.
Within the precision-engineering tier, Krones AG and GEA Group AG exemplify the German archetype of pharmaceutical-grade aseptic filling technology. Syntegon Technology occupies a position among compact monobloc specialists addressing mid-tier beverage producers seeking format flexibility without greenfield capital deployment. These three anchors illustrate how supply-side capability stratifies between high-validation pharmaceutical systems and agile beverage packaging platforms.
| Leading Market Players |
|---|
| Syntegon Technology |
| GEA Group AG |
| Krones AG |
| JBT Corporation |
| Barry-Wehmiller Companies Inc |
| Tetra Laval International |
| KHS GmbH |
| Coesia Group |
| Ronchi Mario SPA |
| Others |
Value Network & Pricing Analysis
Grade 316L stainless steel price volatility compresses margin stability for equipment fabricators while simultaneously widening spreads between premium aseptic systems and standard beverage lines, forcing buyers to recalibrate total-cost-of-ownership calculations around corrosion-resistant contact surfaces and energy-efficient actuation architectures.
Pricing Analysis
Current-generation servo-electric platforms command substantial premiums over legacy pneumatic systems and emerging magnetic levitation configurations. Three-tier pricing structure across premium pharmaceutical-grade, standard beverage, and economy semi-automated levels reflects FDA cGMP validation documentation intensity and after-sales service bundling. Pricing pressure stems from ASEAN beverage producers demanding format-flexible monoblocs without greenfield capital deployment. Contract manufacturing organizations in India exhibit highest price sensitivity due to EU MDR qualification cost absorption, while Swiss biopharmaceutical fill-finish contractors prioritize particle-generation risk elimination over capital outlay.
Supply Chain Analysis
German export-control restrictions on precision motion-control components limit servo-drive availability for non-EU equipment fabricators, concentrating qualified supplier networks in Bavarian and Baden-Württemberg engineering clusters. Manufacturing draws from German precision-engineering capabilities, Chinese stainless steel forging capacity, and Italian pneumatic component sourcing. Single-source vulnerability concentrates in high-torque servo motor supply from specialized producers. Distribution runs through OEM direct sales for pharmaceutical validation-intensive systems and regional distributor networks for mid-tier beverage platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-based service contracting is expanding faster than hardware sales as Coca-Cola and PepsiCo bottling partners pilot throughput-guarantee agreements, converting capital expenditure into recurring operational expenditure and elevating remote diagnostics infrastructure to strategic priority.
For Market Incumbents: Entrench pharmaceutical validation expertise through CDSCO-aligned qualification support for Indian contract manufacturing organizations and EU MDR documentation services that extend equipment lifecycle revenue. Acquire regional spare-part depot networks in ASEAN beverage clusters to defend against emerging monobloc specialists. Prioritize servo-electric platform R&D to eliminate pneumatic legacy exposure before compressed-air infrastructure lock-in hardens in mature plants.
For New Entrants and Emerging Players: Establish a beachhead in compact monobloc systems for Indonesian and Vietnamese soft-drink producers seeking format agility without full line automation capital. Target Indian pharmaceutical export expansion with EU MDR-compatible aseptic isolator technology priced below German precision-engineering premiums. Deploy direct technical sales teams emphasizing rapid qualification timeline compression versus incumbent documentation burden.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors servo-electric technology acquisition targets with established pharmaceutical validation credentials. Long-term viability centers on service-attach revenue multiples exceeding hardware margins as outcome-based contracting displaces break-fix arrangements. Monitor CDSCO-EU MDR alignment progress as inflection indicator for Indian pharmaceutical export equipment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Platform Development | Eliminates pneumatic dependency to meet EU Green Deal compressed-air reduction targets in German beverage clusters. |
| Magnetic Levitation Pump Integration | Reduces particle generation risk for Swiss monoclonal antibody and Massachusetts viral vector production facilities. |
| Regional Service Network Expansion | Enables throughput-guarantee contracting for Mexican and Brazilian Coca-Cola and PepsiCo bottling partners. |
| EU MDR Documentation Services | Extends equipment lifecycle revenue through ongoing compliance support for Italian and German pharmaceutical manufacturers. |
| CDSCO-Aligned Qualification Support | Captures Indian pharmaceutical export expansion to European sterile injectable contract manufacturing markets. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with filling machinery OEM technical directors, pharmaceutical contract manufacturing operations managers, and beverage bottling plant engineers; and secondary validation through SEC 10-K filings of listed packaging conglomerates, EU MDR technical documentation databases, and MIIT energy efficiency benchmark disclosures. Bottom-up equipment shipment triangulation against top-down end-use industry capacity expansion estimates anchored volume and value projections.
Forecast inputs encompassed product type segmentation across liquid, powder, paste, and granule fillers; technology tiers from manual through automated servo-electric platforms; end-user regulatory exposure stratification; and packaging format line integration complexity. CAGRs were derived from installed base replacement cycle compression analysis and greenfield capacity addition tracking across the projection horizon. Specific inputs included FDA cGMP validation protocol evolution, ASEAN beverage export-grade hygiene standard adoption curves, and Chinese provincial dual carbon policy implementation timelines.
Stress conditions across stainless steel input price bands, German engineering cluster supply disruption scenarios, and pneumatic-to-servo retrofit adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory alignment trajectories and energy efficiency mandate enforcement intensity. Material shifts in EU MDR Annex I technical documentation requirements or CDSCO export qualification pathway acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Packaging Machinery Market
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market
Packaging Machinery
Side Sealer Machines Market
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Horizontal Strapping Machine Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Extrusion Press Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Straw Machine Market
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Flow Pack Machine Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Heavy Duty Band Sealer Machine Market
Packaging Machinery
Lipstick Molding Machines Market
Packaging Machinery
Cosmetic Packaging Machinery Market