
 Automatic Liquid Filling Machines Market | 2026-2036
Automatic Liquid Filling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Liquid Filling Machines Market Outlook
Stainless steel substitution for aluminum contact surfaces is realigning capital expenditure patterns across liquid filling equipment. Krones leverages its captive stainless steel fabrication network to sustain margin stability in European pharmaceutical contracts. GEA Group anchors its competitive stance through R&D intensity in aseptic filling architectures, while Syntegon competes on servo-driven precision platforms for high-viscosity pharmaceutical formulations.
An automatic liquid filling machine is an electromechanical system that doses predetermined volumes of liquid into containers through pneumatic, gravity, vacuum, or electronic dispensing mechanisms, typically achieving fill accuracies within plus or minus 0.5 percent for pharmaceutical-grade applications. These systems serve primary packaging operations across food processing, drug manufacturing, chemical blending, and cosmetic compounding facilities where contamination control and throughput velocity determine operational viability. Electronic fillers command premium positioning due to programmable recipe management and real-time fill verification, while pneumatic systems retain cost advantages in emerging-market beverage bottling. Servo-driven technology leads growth trajectories as torque-controlled motion profiles enable gentle handling of shear-sensitive biologic liquids, with magnetic driven systems occupying niche positions in corrosive chemical environments where seal integrity failures carry catastrophic cost.
FDA cGMP guidelines and EMA Annex 1 sterile manufacturing standards shape equipment validation protocols, compelling manufacturers to integrate in-place cleaning circuits and isolator-compatible machine geometries. REACH compliance in Europe and EPA effluent regulations in the United States further constrain material selections for wetted components and wastewater handling subsystems. Stakeholders must monitor evolving serialization mandates and carbon border adjustment mechanisms to calibrate regional production footprints and supplier qualification strategies.
Market Dynamics
Electronic filler systems are displacing pneumatic architectures across pharmaceutical packaging lines as FDA and EMA serialization mandates harden compliance requirements for real-time fill verification and batch traceability.
Growth Catalysts
- FDA cGMP serialization mandates:Pharmaceutical manufacturers in the United States must integrate electronic dispensing with track-and-trace databases, forcing equipment upgrades across oral liquid and injectable filling lines.
- Servo-driven precision platforms:Torque-controlled motion profiles enable gentle handling of shear-sensitive biologic formulations, expanding addressable demand in cell therapy and vaccine production.
- Beverage bottling capacity expansion:Domestic producers in India and Vietnam are installing gravity and vacuum fillers to capture regional soft drink and bottled water consumption growth.
Market Restraints
- Stainless steel input cost volatility:Nickel and chromium price swings compress margin stability for equipment fabricators reliant on 316L-grade contact surfaces.
- Specialized valve actuator supply concentration:Precision pneumatic and servo-actuated dispensing valves concentrate among German and Japanese component suppliers, creating single-source vulnerability.
- REACH compliance material constraints:ECHA restrictions on certain sealing elastomers and lubricants limit wetted component options for European pharmaceutical contracts.
Strategic Opportunities
- ASEAN beverage contract manufacturing:Third-party bottlers in Thailand and Indonesia seek flexible filling platforms supporting rapid changeover between SKUs and container formats.
- EMA Annex 1 sterile manufacturing standards:The 2022 revision compels isolator-integrated filling architectures, creating upgrade cycles for legacy open-restricted barrier systems.
- Convergence of magnetic drive and isolator technology:Seal-less pump systems combined with gloveless isolator interfaces address corrosive chemical and high-potency pharmaceutical applications simultaneously.
Industry Challenges
- Validation engineer talent scarcity:Pharmaceutical equipment qualification requires specialists fluent in FDA 21 CFR Part 11 and EMA GMP Annex 15 documentation protocols.
- Legacy SCADA integration complexity:Brownfield facilities struggle to retrofit electronic fillers into proprietary Allen-Bradley or Siemens control architectures without line-wide automation overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Liquid Filling Machines Market |
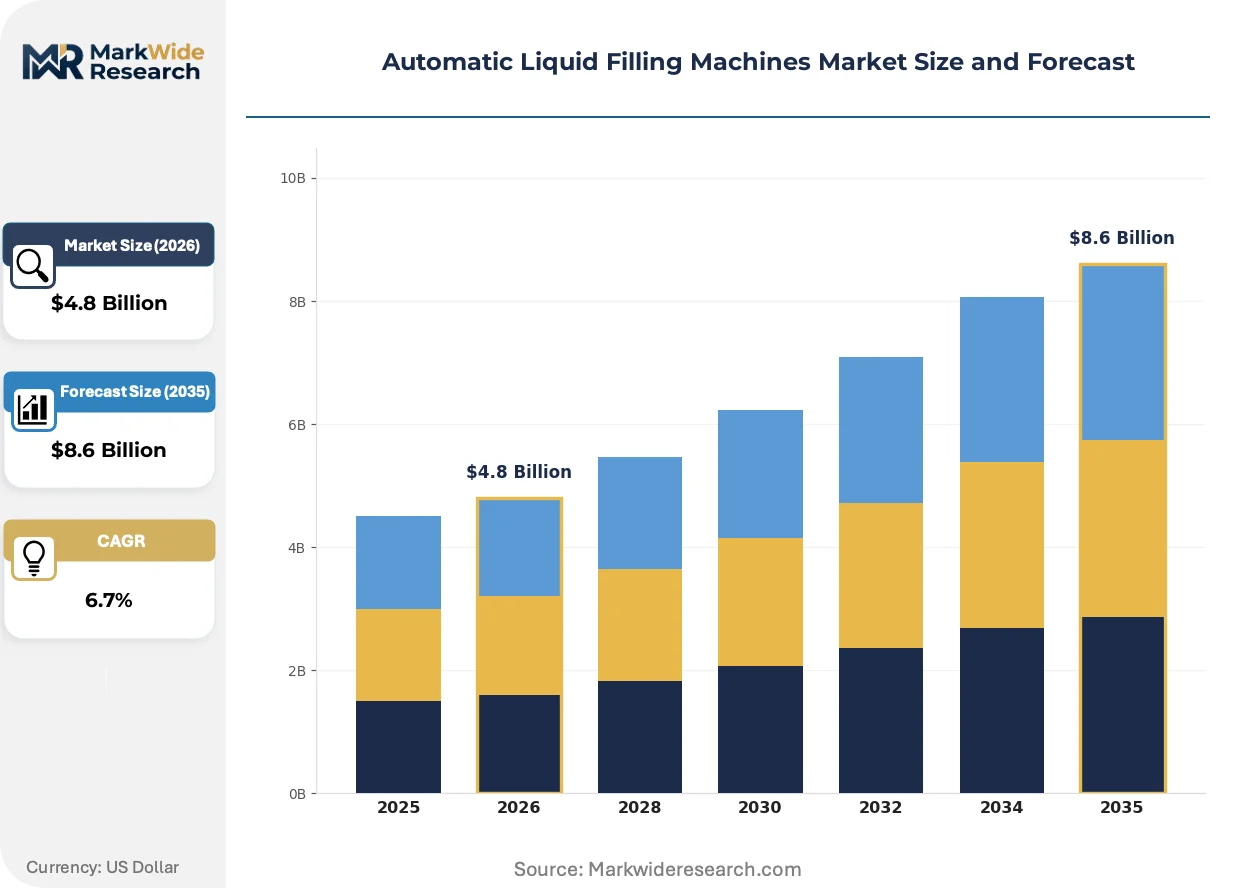
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Fillers, Gravity Fillers, Vacuum Fillers, Electronic Fillers End User: Food & Beverage, Pharmaceuticals, Chemicals, Cosmetics Technology: Servo Driven, Magnetic Driven, Auger Filling, Piston Filling Packaging Type: Bottles, Pouches, Jars, Cartons |
| Companies Covered | Krones, KHS GmbH, GEA Group, Syntegon, Tetra Pak, JBT, Accutek Packaging Equipment, ProMach Inc., Serac Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Liquid Filling Machines Market Strategic Shifts
Equipment architectures are fragmenting into configurable subsystems as pharmaceutical and beverage producers demand faster format changeovers and smaller batch economics.
Servo-driven filling modules with independent axis control are modularizing machine footprints across multi-format packaging halls. Contract manufacturers in Germany and Switzerland adopt plug-and-play turret and pump assemblies to compress product changeover from hours to minutes. This modularity is compressing capital deployment timelines for mid-scale biopharma facilities seeking to balance flexibility with containment.
EMA Annex 1 sterile manufacturing standards are mandating isolator-compatible geometries and continuous viable monitoring for aseptic filling operations. The regulation compels integration of rapid transfer ports and closed-loop cleaning circuits, elevating equipment qualification burdens. High-potency pharmaceutical and ATMP producers in the Netherlands and Denmark are accelerating adoption of restricted access barrier systems to preempt inspection findings.
After-sales service unbundling is fragmenting traditional equipment procurement contracts across emerging-market beverage installations. Bottlers in India and Brazil now source base gravity fillers from regional distributors while contracting directly with European specialists for spare parts and remote diagnostics. This disintermediation compresses distributor margins while expanding direct manufacturer relationships for high-margin consumables and technical support.
Automatic Liquid Filling Machines Market Segmentation
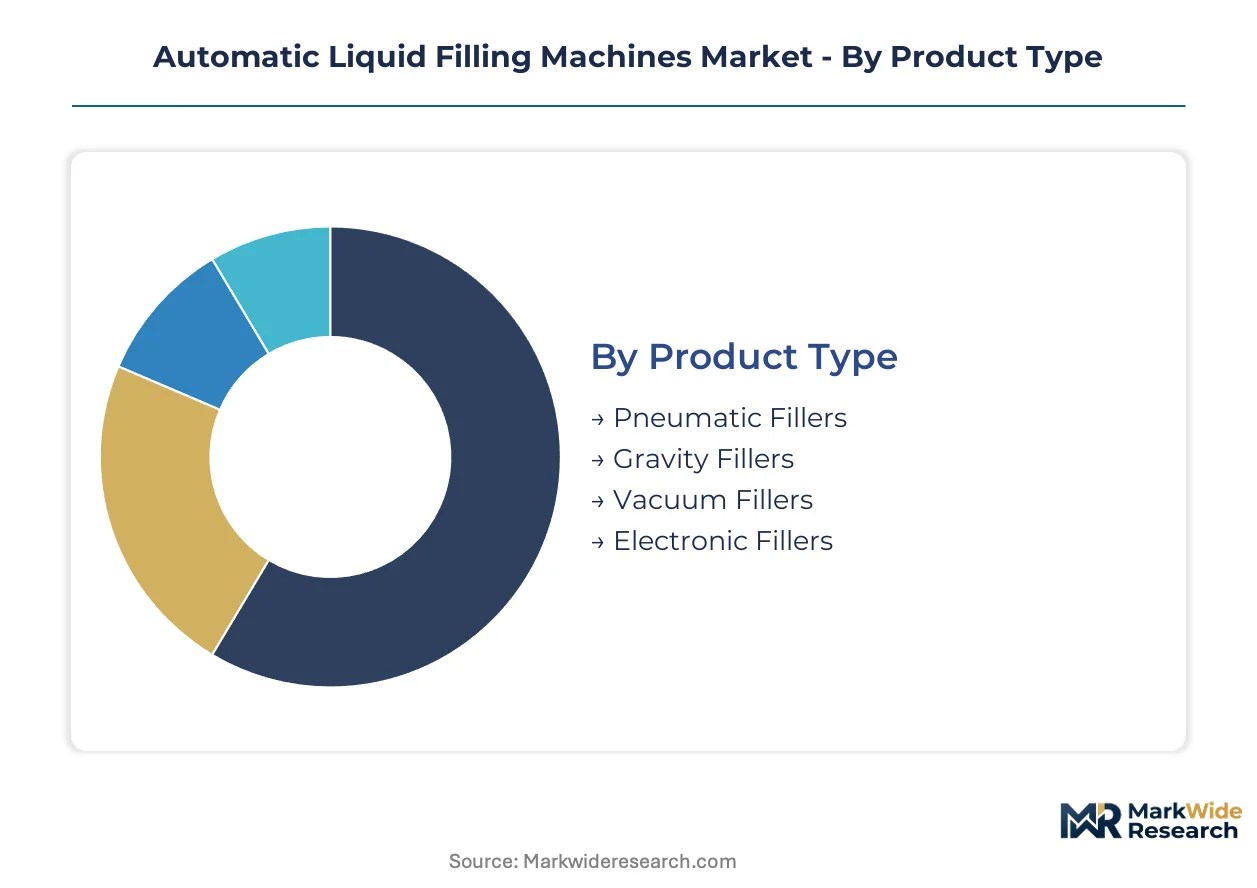
Liquid filling equipment segments diverge sharply by integration depth and automation intensity. Pharmaceutical manufacturers demand embedded electronic systems with SCADA connectivity, while beverage bottlers often deploy standalone pneumatic units for simpler syrup and water dosing operations.
Product Type:
Standalone pneumatic and gravity systems dominate emerging-market beverage installations, whereas electronic fillers embed deeply into pharmaceutical serialization architectures.
- Pneumatic Fillers:Compressed air drives piston displacement through mechanical valve sequencing, achieving fill accuracies around plus or minus one percent. Indian and Vietnamese bottlers favor these systems for mineral water and carbonated soft drinks where capital constraints outweigh precision requirements. FDA serialization mandates are accelerating displacement by electronic alternatives in regulated pharmaceutical environments.
- Electronic Fillers:Programmable logic controllers manage mass flow meters or load-cell feedback loops, enabling real-time fill verification and automatic reject routing. German and US pharmaceutical manufacturers deploy these systems to satisfy FDA cGMP and EMA Annex 1 documentation requirements for batch traceability. Servo-driven pump integration allows recipe-driven viscosity compensation without mechanical changeover.
- Gravity Fillers:Head-pressure dosing through timed nozzle opening suits free-flowing liquids with consistent density profiles.
- Vacuum Fillers:Negative pressure displacement handles foam-sensitive products and precise fill-level control in cosmetic and chemical applications.
Electronic fillers lead volumes in pharmaceutical contracts; pneumatic systems retain the largest installed base in beverage bottling.
End User:
Cost tiers separate validated pharmaceutical systems from standard-duty food and chemical equipment, with compliance documentation driving price multiples.
- Pharmaceuticals:Aseptic filling architectures with isolator-compatible geometries and in-place cleaning circuits dominate injectable and oral liquid packaging. EMA Annex 1 sterile manufacturing standards and FDA cGMP guidelines compel qualification protocols that add substantial engineering overhead. High-potency drug and cell therapy producers in Switzerland and the Netherlands demand restricted access barrier systems.
- Food & Beverage:High-throughput rotary fillers with rapid changeover capabilities serve multi-SKU bottling halls across carbonated drinks, juices, and dairy. Domestic producers in Thailand and Indonesia seek flexible platforms supporting frequent container format switches without line stoppage. FSSAI hygiene mandates in India shape stainless steel surface finish specifications.
- Chemicals:Corrosion-resistant contact surfaces and seal-less magnetic drive pumps address aggressive solvent and acid handling.
- Cosmetics:Precision dosing for high-viscosity creams and serums combines with aesthetic container handling requirements.
Food and beverage applications generate the highest unit volumes; pharmaceutical contracts command the steepest price premiums and fastest technology refresh cycles.
Technology:
Volume concentration separates mass-market mechanical systems from precision motion platforms serving biologic formulations.
- Servo Driven:Closed-loop torque control enables programmable acceleration profiles that protect shear-sensitive vaccines and monoclonal antibodies from mechanical degradation. Independent axis programming supports multi-format flexibility without hardware substitution. Cell therapy producers in Denmark and Germany specify these platforms for gentle handling of live cellular suspensions.
- Magnetic Driven:Seal-less pump architectures eliminate mechanical wear points in corrosive chemical environments and high-potency pharmaceutical containment applications. Containment failures in cytotoxic drug manufacturing carry catastrophic regulatory and liability costs that justify premium positioning. Dutch chemical processors combine magnetic drive with gloveless isolator interfaces.
- Auger Filling:Rotating screw mechanisms meter powders and semi-solids with consistent bulk density characteristics.
- Piston Filling:Positive displacement cylinders handle high-viscosity liquids and pastes across food and cosmetic compounding.
Servo-driven platforms are climbing fastest in pharmaceutical adoption; piston filling retains the broadest cross-industry penetration.
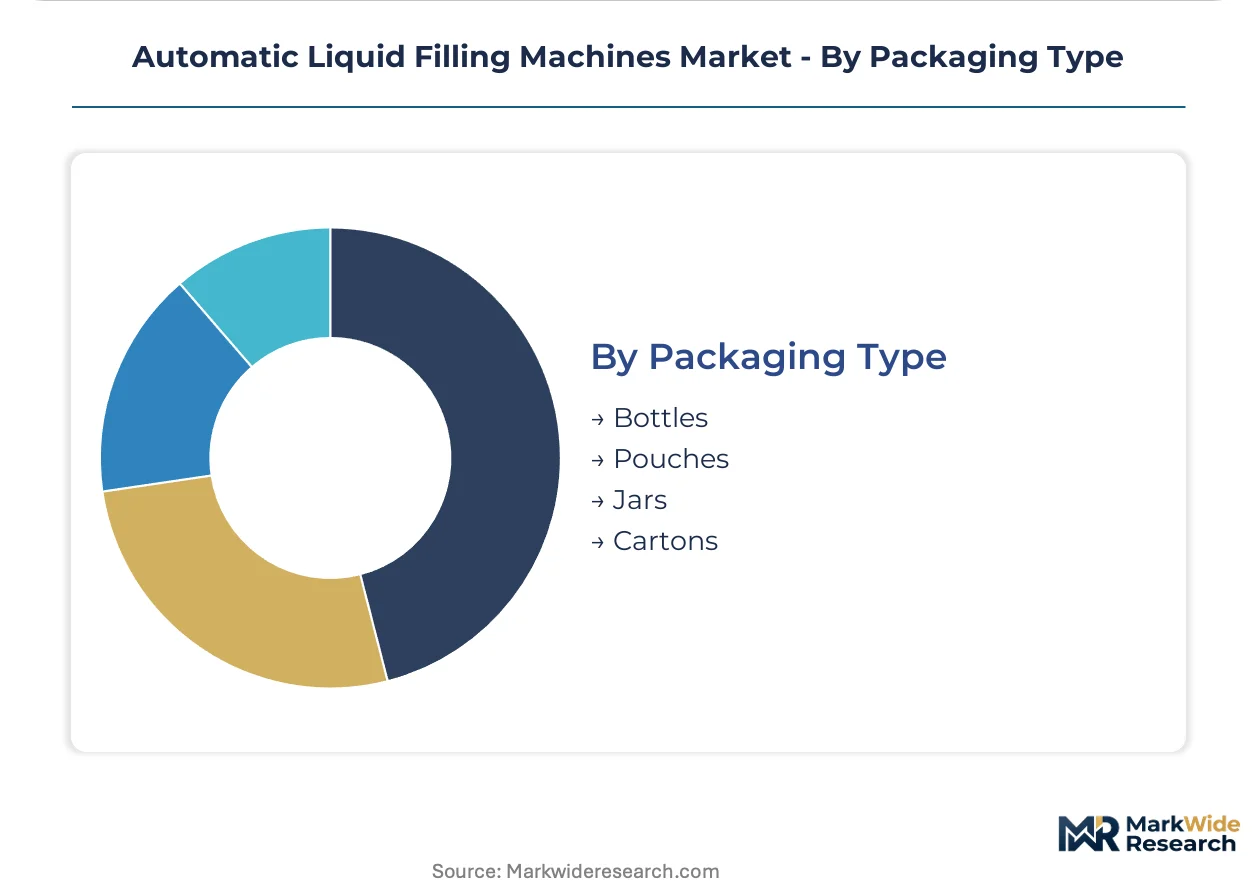
Packaging Type:
Container geometry dictates filling mechanism selection, with bottle systems embedding most deeply into automated packaging lines.
- Bottles:Neck handling and cap alignment systems integrate filling with capping and labeling in continuous rotary configurations. PET and glass container formats span beverage, pharmaceutical, and cosmetic applications with divergent sanitation requirements. German packaging halls demand quick-change turret systems supporting multiple bottle geometries per shift.
- Pouches:Form-fill-seal integration enables flexible packaging for single-serve beverages and liquid detergents with reduced material costs.
- Jars:Wide-mouth containers accommodate viscous products and scoop-accessible formulations in food and personal care.
- Cartons:Gable-top and aseptic brick formats serve extended-shelf-life dairy and juice products with specialized sterile filling environments.
Bottle filling dominates capital deployment; pouch systems are expanding most quickly in single-serve beverage and household chemical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical equipment clusters anchor European demand for aseptic filling architectures, while beverage bottling expansion across India and Southeast Asia concentrates growth momentum in Asia-Pacific manufacturing corridors.
United States
FDA cGMP serialization mandates drive pharmaceutical manufacturers toward electronic filler systems with integrated track-and-trace capabilities. The EPA constrains material selections for wetted components through effluent discharge regulations. Boston-Cambridge biotech corridors and New Jersey pharmaceutical corridors demand servo-driven precision platforms for cell therapy production.
Germany
EMA Annex 1 sterile manufacturing standards compel isolator-integrated filling architectures for injectable drug packaging. REACH compliance restricts sealing elastomer options for European pharmaceutical contracts. Bavarian packaging machinery clusters leverage captive stainless steel fabrication networks to sustain margin stability in high-value contracts.
India
Domestic beverage bottlers install gravity and vacuum fillers to capture regional soft drink and water consumption growth. FSSAI hygiene mandates shape stainless steel surface finish specifications for food-contact equipment. Maharashtra and Gujarat pharmaceutical corridors balance cost-sensitive pneumatic systems with emerging electronic filler adoption for export-oriented facilities.
China
NMPA pharmaceutical manufacturing standards align with international GMP protocols, elevating equipment validation requirements for domestic drug producers. The country's dual carbon goals pressure fabricators toward energy-efficient servo-driven architectures. Yangtze River Delta chemical processing clusters demand magnetic drive systems for corrosive solvent handling.
Vietnam
Rapid bottled water and carbonated soft drink consumption expansion attracts regional equipment distributors for standalone pneumatic installations. The country's national food safety regulator enforces progressive hygiene standards for beverage contact surfaces. Ho Chi Minh City industrial zones concentrate third-party bottling capacity seeking flexible format changeover capabilities.
Automatic Liquid Filling Machines Market Competitive Environment
Global majors compete with regional champions across technology tiers and geographic proximity to end-use clusters. The vendor base stratifies into three distinct layers: European precision specialists commanding pharmaceutical premium pricing, Asian scale fabricators serving cost-sensitive beverage installations, and mid-tier modular system integrators bridging both domains. Dominant competitive moves include backward integration into stainless steel component fabrication and strategic partnerships with isolator technology specialists for aseptic filling compliance.
Among German-based precision fabricators, Krones AG and GEA Group exemplify the European specialist archetype through captive supply chain control and R&D-intensive positioning. KHS GmbH represents the scale-driven diversified machinery conglomerate competing across beverage and pharmaceutical verticals simultaneously. Syntegon Technology GmbH occupies the servo-driven precision platform segment addressing high-viscosity pharmaceutical formulations. These three anchors illustrate divergent strategic postures within a market where technology specialization and geographic manufacturing footprint determine competitive viability.
| Leading Market Players |
|---|
| Krones |
| KHS GmbH |
| GEA Group |
| Syntegon |
| Tetra Pak |
| JBT |
| Accutek Packaging Equipment |
| ProMach Inc. |
| Serac Group |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade certification tiers bifurcate automatic liquid filling machines into premium servo-driven platforms and commodity pneumatic systems, with FDA cGMP validation requirements in the United States and EMA Annex 1 compliance in Germany anchoring premium pricing while stainless steel input costs and regional fabrication capacity shape supply chain geography across European precision clusters and Asian scale manufacturing.
Pricing Analysis
Input-cost pass-through from nickel and chromium price volatility compresses margins for 316L-grade stainless steel contact surfaces, forcing European fabricators to absorb fluctuations or renegotiate long-term pharmaceutical contracts. Three-tier pricing structure across premium servo-driven, standard electronic, and economy pneumatic levels differentiates on fill accuracy certification and serialization integration depth. Pricing pressure stems from Indian and Vietnamese beverage bottlers demanding stripped-down gravity systems without after-sales bundling. Contract manufacturers in Southeast Asia exhibit highest price sensitivity; Swiss cell therapy producers show lowest sensitivity due to containment failure liability costs.
Supply Chain Analysis
Certification and qualification gating concentrates precision valve actuator supply among German and Japanese component specialists, creating single-source vulnerability for servo-driven dispensing architectures. Equipment fabrication draws from stainless steel processing in Germany, China, and India, with captive forging networks in Bavaria sustaining margin stability. Raw material dependencies span 316L-grade stainless steel, rare-earth magnets for drive systems, and specialized sealing elastomers restricted under REACH. Supply chain risk centers on tariff exposure for magnetic drive components sourced through East Asian trading corridors. Distribution runs through regional machinery distributors in emerging markets and direct manufacturer relationships for validated pharmaceutical installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automatic liquid filling machines constitute a late-cycle quality story as pharmaceutical serialization mandates and EMA Annex 1 sterile manufacturing standards shift procurement toward premium servo-driven platforms with isolator-compatible geometries and real-time fill verification capabilities.
For Market Incumbents: Extend captive stainless steel fabrication networks to defend margin stability against nickel price volatility while deepening isolator technology partnerships to preempt EMA compliance upgrade cycles. Consolidate aftermarket service relationships directly with Indian and Brazilian bottlers to offset distributor disintermediation. Threat substitution from Chinese scale fabricators in economy pneumatic segments demands channel control reinforcement in ASEAN beverage corridors. For New Entrants and Emerging Players: Servo-driven modularity for rapid format changeover offers entry wedge into mid-scale European biopharma contract manufacturing facilities balancing flexibility with containment. Target white-space in Thailand and Indonesia third-party bottling halls seeking SKU agility without line stoppage. Go-to-market through remote diagnostics subscriptions bundled with base gravity filler hardware separates from incumbent full-service bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where validation engineer talent scarcity and legacy SCADA integration complexity strand mid-tier modular integrators between European precision specialists and Asian scale fabricators. Long-term viability favors acquirers of servo-drive control software assets and isolator-interface patent portfolios. Signal to monitor: FDA enforcement intensity on 21 CFR Part 11 documentation protocols as inflection indicator for electronic filler upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Forging | Bavarian fabricators anchor margin stability against nickel volatility through captive 316L-grade supply. |
| Isolator Technology Partnership | EMA Annex 1 compliance mandates elevate restricted access barrier systems to competitive necessity. |
| Servo-Drive Control Software Acquisition | Torque-controlled motion profiles differentiate gentle handling capabilities for shear-sensitive biologics. |
| Remote Diagnostics Platform Launch | Direct manufacturer relationships with Indian bottlers circumvent distributor margin compression. |
| Modular Turret System Development | Plug-and-play assemblies compress product changeover from hours to minutes in multi-format halls. |
Study Parameters
Direct dialogue with pharmaceutical packaging engineers, beverage plant managers, OEM procurement leads, and aftermarket service heads grounds qualitative findings, validated against FDA 510(k) filings, EMA GMP inspection databases, SEC equipment supplier disclosures, and stainless steel trade flow data. Bottom-up and top-down triangulation cross-checks installed base estimates against capital expenditure tracking across regional manufacturing corridors.
Bottom-up volume modeling by product type, end-user vertical, drive technology, and regional regulatory cluster converges with top-down macroeconomic elasticity assumptions across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against historical equipment shipment patterns and capacity expansion announcements. Forecast inputs incorporate EMA Annex 1 revision implementation timelines and FSSAI hygiene mandate enforcement intensity in Indian food-contact equipment.
The model holds under stable regulatory enforcement intensity and contained nickel price volatility; deviation in FDA serialization deadline acceleration or REACH sealing elastomer restrictions would shift upgrade cycle timing. Forecasts reflect documented assumptions on stainless steel input cost pass-through rates and ASEAN beverage bottling capacity expansion velocity. A model refresh is warranted upon material change in EMA GMP inspection finding severity or NMPA alignment pace with international validation protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Cosmetic Filling Machines Market
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Corrugated Box Machines Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
Robotic Carton Loading Machine Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
Blow Fill Seal (BFS) Technology Market
Packaging Machinery
Global Tissue Paper Converting Machines Market