
 CCL Laminating Machine Market | 2026-2036
CCL Laminating Machine Market Size, Share, and Industry Trends Forecast 2026-2036
CCL Laminating Machine Market Insights
Asset-light leasing and project finance for laminating equipment is fragmenting the competitive landscape. Burkle leverages its vertical integration into press systems to sustain engineering intensity across European installations. Seyi Electric anchors its position through manufacturing scale in Asian markets, while Panasonic Corporation competes via technology leadership in precision thermal control systems.
A CCL laminating machine bonds copper foil to resin-impregnated glass fiber substrates under controlled heat and pressure, typically operating at temperatures between 150°C and 200°C with platen flatness tolerances of ±0.02 mm to ensure uniform dielectric thickness in multilayer boards. Roll-to-roll laminators dominate volume production for flexible circuit applications where continuous processing minimizes material waste, while automatic laminators capture margin pools in high-mix PCB manufacturing by reducing operator-dependent variation. Thermal lamination technology leads installed capacity, though UV coating systems are gaining share in decorative panel applications requiring solvent-free finishes.
China's MIIT enforces GB standards that mandate thermal uniformity certification for electronics-grade laminating equipment, while REACH compliance in Europe restricts certain adhesive chemistries used in lamination processes. Japan's METI promotes JIS standards that influence export equipment specifications across Pacific supply chains. Stakeholders must monitor how evolving dual carbon goals in China reshape energy efficiency requirements for heated platen systems.
Market Dynamics
China's MIIT thermal uniformity mandates are compressing equipment replacement cycles while South Korean PCB clusters absorb automated capacity to serve Apple and Samsung HDI board contracts.
Growth Catalysts
- HDI Board Proliferation:Smartphone and automotive radar manufacturers require finer line widths, forcing fabricators to upgrade lamination precision. South Korea's Gumi corridor leads this capacity expansion.
- GB Standards Compliance:China's updated electronics manufacturing regulations mandate thermal uniformity certification, creating replacement demand across installed base of heated platen systems.
- Automotive Radar Substrates:77GHz radar modules for advanced driver assistance systems use high-frequency CCL requiring specialized vacuum lamination with tighter dielectric control.
Market Restraints
- Steel Price Volatility:Precision-machined platens require specialty alloy steel; input cost swings compress margin predictability for European press manufacturers.
- Heating Element Concentration:Ceramic heater supply concentrates in Japanese and German suppliers, creating single-source risk for thermal system integrators.
- REACH Adhesive Restrictions:ECHA limitations on epoxy hardener chemistries force reformulation of resin systems, extending qualification timelines for European equipment shipments.
Strategic Opportunities
- India PCB Fabrication:Government production-linked incentive schemes attract CCL laminating investments to Gujarat and Tamil Nadu corridors previously dependent on Chinese imports.
- UV Coating Convergence:Decorative panel manufacturers combine UV curing with traditional thermal lamination, opening solvent-free finishing applications in furniture and automotive interiors.
- Leasing Model Expansion:Asset-light project finance structures allow mid-tier fabricators in Vietnam and Thailand to access automated lamination without full capital commitment.
Industry Challenges
- Thermal Control Engineering Gap:PID tuning for multi-zone platen systems requires specialized process engineers scarce outside Japan, Germany, and Taiwan.
- Legacy SCADA Integration:Older vacuum presses use proprietary control architectures that resist Industry 4.0 connectivity retrofits without complete electrical replacement.
- CE-GB Dual Certification:Equipment serving both European and Chinese markets faces conflicting documentation requirements and extended approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CCL Laminating Machine Market |
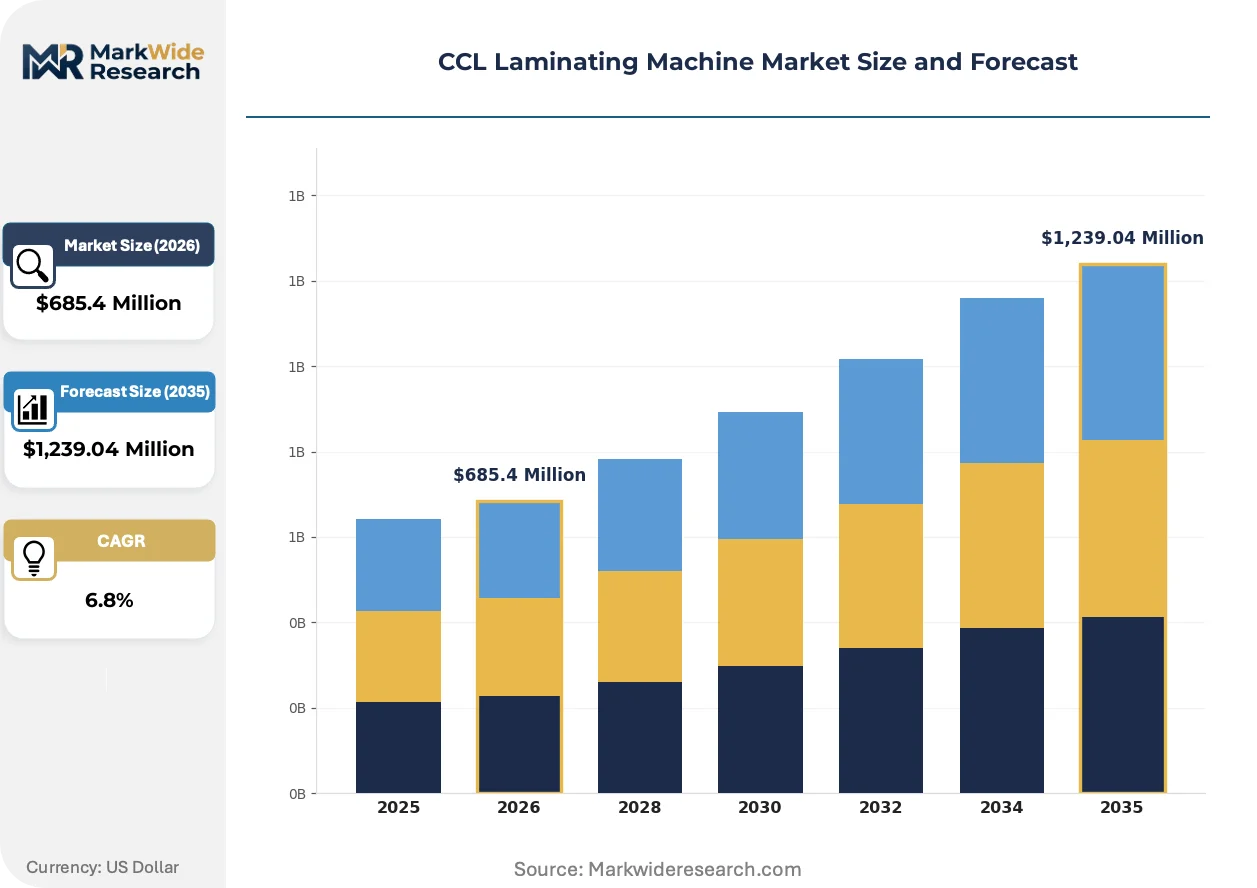
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll-to-Roll Laminators, Sheet Laminators, Hot Laminators, Cold Laminators, Automatic Laminators Technology: UV Coating, Flame Treatment, Corona Discharge, Thermal Lamination, Adhesive Coating Application: Printed Circuit Boards, Decorative Panels, Flexible Packaging, Automotive Interiors, Consumer Electronics End User: PCB Manufacturers, Furniture Makers, Packaging Companies, Automotive Suppliers, Electronics Assemblers |
| Companies Covered | Burkle, Lesta, Lauffer, Birkholz, Heraeus, Seyi Electric, Cipel Italia, Doosan Corporation, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CCL Laminating Machine Market Trends and Innovations
Digital twin architectures are compressing commissioning timelines while regulatory divergence between Chinese GB standards and European CE frameworks forces dual-track engineering investments.
Digital twin simulation is virtualizing thermal profiling and pressure calibration workflows before physical machine assembly. Korean PCB fabricators now require virtual commissioning to reduce on-site installation from six weeks to ten days. This virtualization is compressing project timelines and reducing travel-dependent service revenue for equipment vendors.
REACH compliance is forcing adhesive chemistry substitutions across European lamination lines. ECHA restrictions on bisphenol-A derivatives in epoxy hardeners push resin formulators toward bio-based alternatives with longer cure profiles. German automotive interior suppliers absorb extended cycle times to maintain CE marking eligibility for export equipment.
Outcome-based service contracts are displacing traditional break-fix maintenance in high-volume Asian installations. Korean and Taiwanese fabricators now pay per laminated square meter rather than annual service retainers, transferring uptime risk to equipment vendors. This compression is most visible in Ansan and Taoyuan corridors where 24/7 operations penalize unplanned downtime severely.
CCL Laminating Machine Market Segmentation
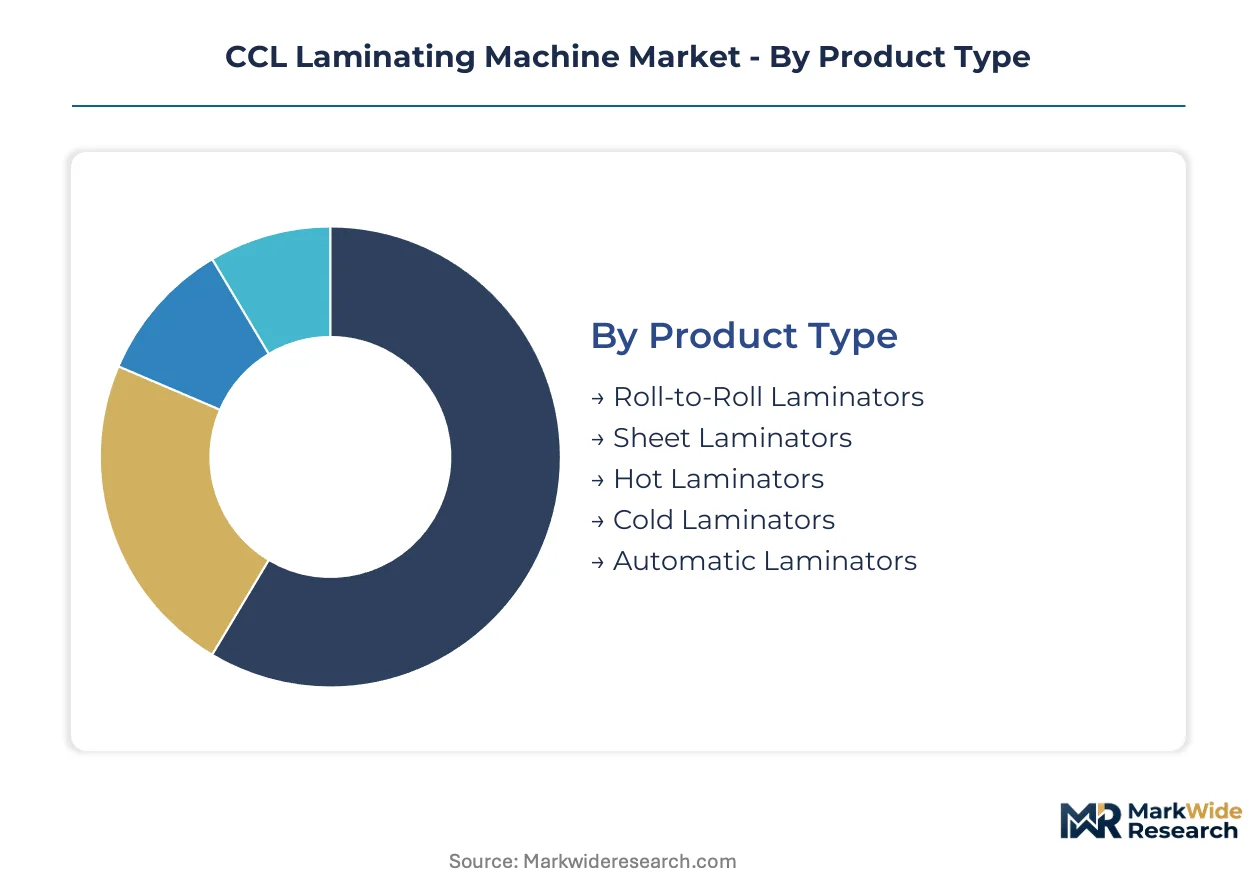
CCL laminating equipment serves divergent precision requirements across electronics fabrication and industrial finishing. Segmentation reveals how thermal control specifications, substrate formats, and end-use certification demands reshape procurement patterns for press system vendors.
Product Type:
Equipment selection tracks the tension between continuous processing efficiency and discrete panel precision across flexible and rigid substrate formats.
- Roll-to-Roll Laminators:Continuous web processing bonds copper foil to flexible polyimide substrates at speeds exceeding 10 meters per minute. Korean PCB fabricators in the Gumi corridor deploy these systems for smartphone flex circuit production where material waste minimization overrides capital intensity concerns.
- Sheet Laminators:Discrete platen pressing accommodates rigid multilayer boards up to 32 layers with ±0.02 mm flatness tolerance. China's updated GB standards for thermal uniformity certification are accelerating replacement demand across installed base units that predate current MIIT mandates.
- Hot Laminators:Heated platen systems operating between 150°C and 200°C dominate standard CCL bonding applications for FR-4 substrates.
- Cold Laminators:Pressure-sensitive adhesive activation without thermal input serves temperature-sensitive decorative films and certain automotive interior veneers.
- Automatic Laminators:Robot-fed pressing systems reduce operator-dependent variation in high-mix PCB manufacturing environments.
The dominant share belongs to sheet laminators, while roll-to-roll systems are closing the gap fastest in East Asian flexible circuit corridors.
Technology:
Process chemistry differentiation separates solvent-based thermal systems from energy-cured alternatives with distinct regulatory compliance profiles.
- Thermal Lamination:Heated platen bonding with epoxy resin systems remains the baseline for electronics-grade CCL production. ECHA restrictions on bisphenol-A derivatives in European installations are forcing reformulation toward bio-based hardeners with extended cure profiles.
- UV Coating:Photoinitiated curing eliminates solvent emissions and enables inline processing speeds. German automotive interior suppliers combine UV finishing with traditional thermal steps to maintain CE marking eligibility while meeting VOC reduction targets.
- Flame Treatment:Surface oxidation pretreatment improves adhesion on polyolefin substrates for packaging applications.
- Corona Discharge:Atmospheric plasma treatment activates polymer surfaces before adhesive bonding in high-volume flexible packaging lines.
- Adhesive Coating:Direct resin deposition systems accommodate specialty substrates requiring custom dielectric formulations.
Thermal lamination retains the largest installed base, though UV coating is gaining share fastest in solvent-sensitive automotive and furniture finishing applications.
Application:
End-use precision requirements range from micron-level dielectric control in electronics to aesthetic uniformity in decorative surfacing.
- Printed Circuit Boards:Multilayer board fabrication demands vacuum lamination with z-axis thermal uniformity within ±2°C across 600 mm platens. HDI proliferation for 5G infrastructure and automotive radar substrates is tightening dielectric thickness tolerances below 5 micrometers.
- Automotive Interiors:Decorative laminating for dashboard and door panel veneers requires scratch-resistant surface finishes and thermal cycling durability. Japanese tier-1 suppliers specify JIS-compliant equipment for Pacific supply chain consistency.
- Decorative Panels:Furniture and architectural surfacing applications prioritize throughput over precision, with tolerance windows an order of magnitude wider than electronics grades.
- Flexible Packaging:Food-grade barrier films employ adhesive lamination with migration-controlled chemistries subject to EFSA compliance.
- Consumer Electronics:Tablet and laptop enclosure finishing combines aesthetic requirements with EMI shielding functionality.
PCB applications command the highest equipment margins, while automotive interiors are expanding most quickly as EV platform differentiation intensifies surface quality competition.
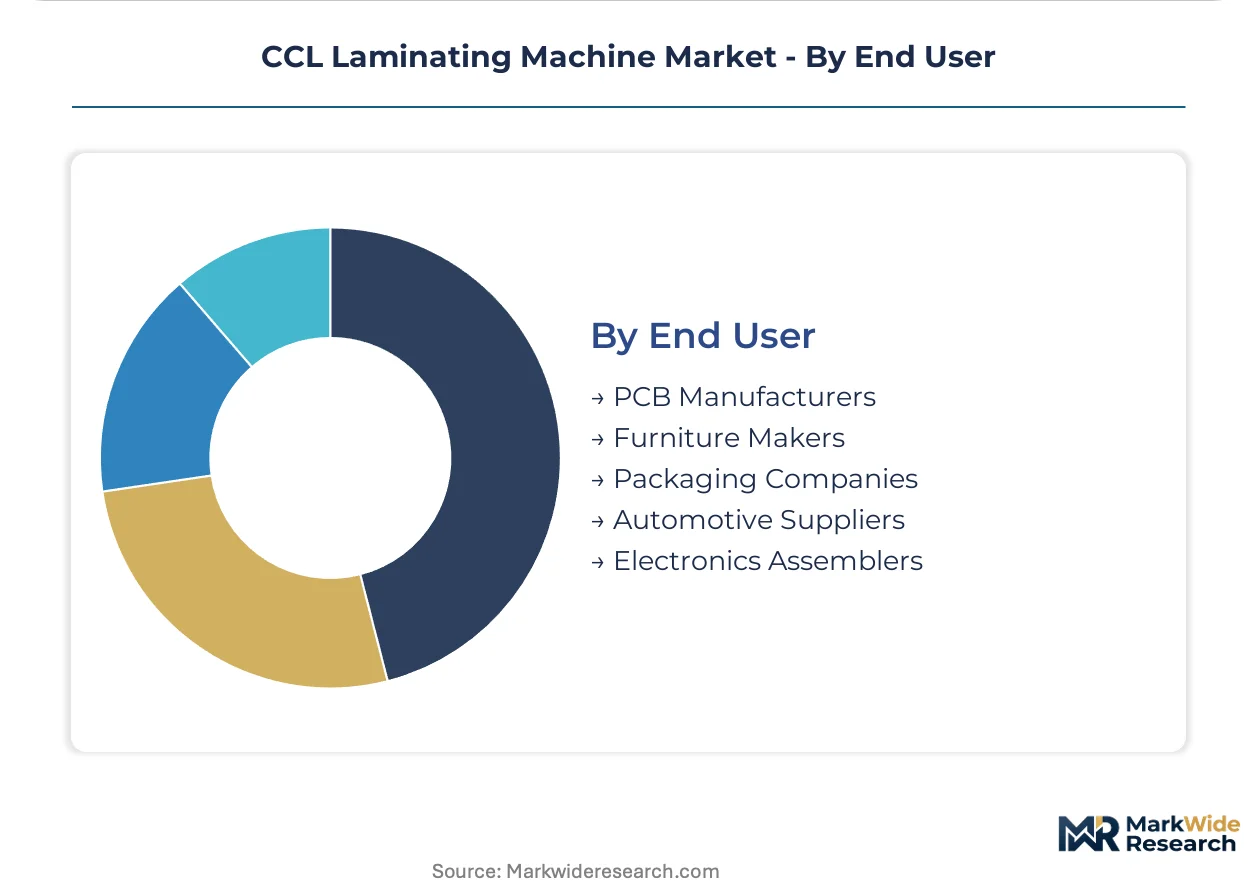
End User:
Customer technical sophistication spans from process-engineering-intensive fabricators to specification-driven assemblers with outsourced lamination.
- PCB Manufacturers:Fabricators in South Korea's Ansan corridor and China's Pearl River Delta operate 24/7 production with outcome-based service contracts replacing traditional maintenance retainers. These customers specify multi-zone PID control systems requiring scarce thermal engineering expertise concentrated in Japan, Germany, and Taiwan.
- Automotive Suppliers:Tier-1 interior module producers demand CE-GB dual certification for equipment serving parallel European and Chinese assembly plants, extending approval timelines.
- Packaging Companies:Converters prioritize capital efficiency and favor leasing structures over outright equipment purchase.
- Furniture Makers:Decorative panel producers show accelerating interest in UV-cured solvent-free finishing systems.
- Electronics Assemblers:Contract manufacturers often outsource CCL lamination to specialized substrate suppliers rather than maintaining captive capacity.
PCB manufacturers represent the most technically demanding customer segment, while packaging companies are adopting asset-light procurement models fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government production-linked incentive schemes are redirecting CCL laminating capacity toward emerging fabrication corridors while established clusters absorb automated systems to serve high-density interconnect contracts.
China
MIIT thermal uniformity mandates under updated GB standards are compressing replacement cycles for heated platen systems. The dual carbon goals are reshaping energy efficiency requirements for electronics-grade equipment. The Pearl River Delta fabrication corridor is absorbing vacuum lamination capacity to maintain dielectric precision for multilayer board exports.
South Korea
Apple and Samsung HDI board contracts are driving precision lamination upgrades in smartphone flex circuit production. The national industrial policy supports advanced PCB manufacturing through tax incentives for automated equipment adoption. The Gumi-Ansan corridor leads regional capacity expansion with 24/7 operations and outcome-based service contracts.
Germany
ECHA restrictions on bisphenol-A derivatives in epoxy hardeners are forcing resin reformulation across European lamination lines. CE marking requirements for thermal equipment maintain stringent documentation standards for export eligibility. Bavarian automotive interior suppliers combine UV curing with traditional thermal steps to meet VOC reduction targets.
Japan
METI-promoted JIS standards influence export equipment specifications across Pacific supply chains. Ceramic heater supply concentration creates single-source risk mitigation priorities for thermal system integrators. Nagoya-area fabricators anchor precision thermal control engineering expertise scarce outside Germany and Taiwan.
India
Production-linked incentive schemes for electronics manufacturing attract CCL laminating investments to Gujarat and Tamil Nadu corridors. BIS certification requirements are developing for imported lamination equipment serving domestic PCB fabrication. Mumbai-Pune and Chennai-Bengaluru industrial belts previously dependent on Chinese substrate imports are establishing captive lamination capacity.
CCL Laminating Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where engineering intensity and manufacturing scale define separable strategic positions. European press system vendors maintain positions through backward integration into precision-machined components. Asian fabricators compete via manufacturing scale and regional market access. Two dominant competitive moves are reshaping positions: asset-light leasing structures fragmenting procurement patterns, and digital twin virtualization compressing commissioning timelines and service revenue models.
Among German-based equipment specialists, Burkle GmbH, Lauffer GmbH, and Birkholz GmbH occupy positions anchored in European engineering traditions for high-precision press systems. These entities exemplify the engineering-intensive archetype where vertical control over thermal system components supports installation complexity across regulated markets. Seyi Electric and Panasonic Corporation represent alternative positioning vectors where manufacturing scale and technology leadership in precision thermal control systems respectively define competitive differentiation in Asian market corridors.
| Leading Market Players |
|---|
| Burkle |
| Lesta |
| Lauffer |
| Birkholz |
| Heraeus |
| Seyi Electric |
| Cipel Italia |
| Doosan Corporation |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
Ceramic heater supply concentrates in Japanese and German manufacturers, concentrating margin capture in thermal system integrators while press fabricators absorb alloy steel volatility. This upstream chokepoint shapes procurement negotiations for European and Korean equipment vendors serving PCB fabrication corridors.
Pricing Analysis
Certification level creates the primary spread, with CE-GB dual-certified equipment commanding premium positioning over single-market units. Three-tier pricing structure across premium, standard, and economy levels tracks thermal uniformity precision, automation density, and after-sales bundling. Cost compression in standard-tier sheet laminators is intensifying because Chinese fabricators prioritize capital efficiency over precision specifications. Packaging converters and furniture makers show highest price sensitivity, while Korean PCB manufacturers in Ansan and Gumi absorb premium positioning for uptime guarantees.
Supply Chain Analysis
Specialty alloy steel feeds from German and Japanese metallurgical suppliers, while ceramic heating elements and precision-machined platens draw from concentrated Japanese and German component vendors. Vacuum pump systems and PID control modules rest on Taiwanese and German automation houses. Single-source vulnerability in ceramic heater supply creates procurement risk for thermal system integrators lacking dual-qualified vendors. Distribution runs through direct OEM sales for large PCB fabricators and regional equipment distributors serving mid-tier decorative panel producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset-light leasing structures and digital twin commissioning are fragmenting procurement patterns, creating niche entry points for specialized vendors. HDI board proliferation and REACH adhesive reformulation are generating demand-side shifts that reward focused positioning over broad portfolio plays.
For Market Incumbents: Build captive service revenue moats through outcome-based contracts per laminated square meter rather than annual retainers. Deepen backward integration into precision-machined platen production to offset alloy steel volatility. Defend against emerging Asian leasing platforms by embedding thermal engineering expertise in long-term service agreements. Prioritize CE-GB dual certification investment to capture automotive supplier procurement consolidation.
For New Entrants and Emerging Players: Build out UV coating system specialization for solvent-sensitive automotive interior applications where German tier-1 suppliers absorb extended cycle times. Target India's Gujarat and Tamil Nadu corridors where production-linked incentive schemes attract first-mover CCL laminating investments. Penetrate through leasing model partnerships with Vietnamese and Thai mid-tier fabricators seeking automated capacity without full capital commitment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across roll-to-roll laminator segments where virtualization compresses commissioning timelines and service revenue. Long-term viability favors equipment vendors with installed base density in Korean and Taiwanese 24/7 fabrication corridors. Acquisition target archetype: thermal control engineering specialists with multi-zone PID expertise concentrated in Japan, Germany, and Taiwan. Monitor digital twin adoption rates as inflection indicator for service contract displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | German press vendors capture margin pools in specialty alloy platen machining. |
| Dual Certification Investment | CE-GB alignment extends approval timelines but unlocks automotive supplier procurement. |
| Outcome-Based Service Contracts | Korean fabricators in Ansan transfer uptime risk to equipment vendors per square meter. |
| Digital Twin Commissioning | Virtual thermal profiling reduces Korean PCB fabricator installation from six weeks to ten days. |
| Leasing Model Expansion | Asset-light structures open Vietnamese and Thai mid-tier markets without capital barriers. |
Research Methodology
Cross-validation between primary interviews with PCB fabrication executives, thermal system engineers, and aftermarket service heads and secondary sources including MIIT regulatory filings, ECHA restriction updates, and customs trade data anchors the qualitative findings. Plant managers at Korean Gumi corridor facilities, procurement leads at German automotive interior suppliers, and distribution channel partners across Southeast Asian markets provided operational validation. Bottom-up equipment shipment tracking and top-down PCB production capacity modeling triangulate market sizing.
Calibration against historical replacement cycle patterns and regulatory compliance timelines shapes the analytical framework across the analysis window. Segmentation dimensions include product type, thermal control technology, end-use application precision requirements, and regional certification clusters. CAGRs derive from installed base turnover rates and HDI board capacity expansion trajectories. Forecast inputs incorporate GB standards enforcement timelines and REACH adhesive reformulation adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-supported equipment vendors or accelerated UV coating convergence would shift outcomes. Cross-checking against PCB fabrication capital expenditure surveys and ceramic heater import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Food Packaging Machinery Market
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Pallet Drum Filler Capper Market
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
Global Blister Packaging Machinery Market
Packaging Machinery
Aerosol Filling Machines Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Pulp Molding Machines Market
Packaging Machinery
Vacuum Chamber Packaging Machines Market
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Injection Blow Molding Machine Market
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Flow Wrap Machines Market