
 North America Automatic Carton Erector Market | 2026-2036
North America Automatic Carton Erector Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automatic Carton Erector Market Analytics
Equipment leasing and managed service contracts are reshaping competitive entry in the North America automatic carton erector landscape. Lantech leverages its vertical integration into stretch wrapping and case handling to bundle erector systems with downstream automation. WestRock Company anchors demand through its captive packaging operations and direct specification of erector technologies across its plant network. Pearson Packaging Systems differentiates through servo-driven electric architectures that appeal to pharmaceutical and food-sector buyers seeking cleanroom-compatible installations.
An automatic carton erector forms rigid corrugated containers from flat blanks using mechanical, pneumatic, or robotic actuation, typically achieving speeds of 10 to 50 cases per minute depending on blank complexity and glue or tape closure methods. The machine serves as the upstream node in end-of-line packaging lines, feeding formed cases to case packers, sealers, and palletizers in continuous-flow manufacturing environments. Horizontal and robotic product types command premium positioning due to their adaptability to variable box sizes and integration with vision-guided pick systems, while electric and hybrid technology segments are capturing margin pools as energy efficiency and predictive maintenance become procurement priorities. Pneumatic systems still dominate installed base volumes but face displacement in new greenfield projects where total cost of ownership calculations favor electric servo architectures.
OSHA machine guarding standards and FDA Title 21 CFR requirements for food-contact surfaces shape erector design specifications and market access conditions for vendors serving North American food and beverage end users. EPA energy efficiency guidelines and state-level California Title 24 building codes indirectly influence electric drive selection and motor efficiency tiers specified in procurement documents. Stakeholders must monitor evolving MDR-equivalent pressure on pharmaceutical packaging validation protocols and decide whether to pre-certify systems for anticipated traceability mandates before competitor lock-in hardens.
Market Dynamics
Electric servo architectures are compressing total cost of ownership calculations across North American fulfillment networks, forcing incumbent pneumatic vendors to defend installed base positions through retrofit upgrade programs.
Growth Catalysts
- OSHA machine guarding mandates:Food and beverage processors in the Midwest manufacturing belt are replacing legacy pneumatic systems with certified electric erectors to satisfy workplace safety audits and reduce injury liability exposure.
- E-commerce fulfillment velocity:California distribution corridors demand throughput rates above 40 cases per minute, pulling robotic and horizontal erector configurations into greenfield warehouse projects.
- Hybrid drive technology:Pharmaceutical packagers seeking cleanroom compatibility specify servo-electric actuation to eliminate compressed air contamination risks while maintaining FDA Title 21 CFR compliance.
Market Restraints
- Steel and aluminum input volatility:Frame fabrication costs fluctuate with commodity pricing, compressing margins for domestic equipment fabricators serving price-sensitive contract packaging segments.
- Control system supplier concentration:Servo motor and drive sourcing concentrates among Japanese and German industrial automation suppliers, exposing North American erector OEMs to extended lead times and currency risk.
- Pneumatic infrastructure lock-in:Existing plant air compressor investments create switching friction for brownfield facilities calculating full electric conversion costs against incremental pneumatic upgrades.
Strategic Opportunities
- Mexican nearshoring expansion:Automotive and electronics manufacturers relocating assembly from Asia are specifying North American-sourced erectors to satisfy USMCA content requirements and reduce trans-Pacific logistics exposure.
- Predictive maintenance convergence:Integration of vibration sensors and edge computing analytics with servo drives enables condition-based service contracts, shifting vendor revenue from equipment sales to recurring monitoring fees.
- California Title 24 building codes:Energy efficiency mandates for industrial facilities create regulatory tailwind for electric erector specification in new construction, particularly across the Central Valley distribution cluster.
Industry Challenges
- Controls engineering talent scarcity:Servo system programming and PLC integration expertise concentrates among aging workforces in the Great Lakes automation corridor, constraining deployment timelines for complex multi-axis erector installations.
- Pharmaceutical validation protocols:FDA 21 CFR Part 11 electronic record requirements extend commissioning timelines for erectors feeding serialized packaging lines, compressing project ROI calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automatic Carton Erector Market |
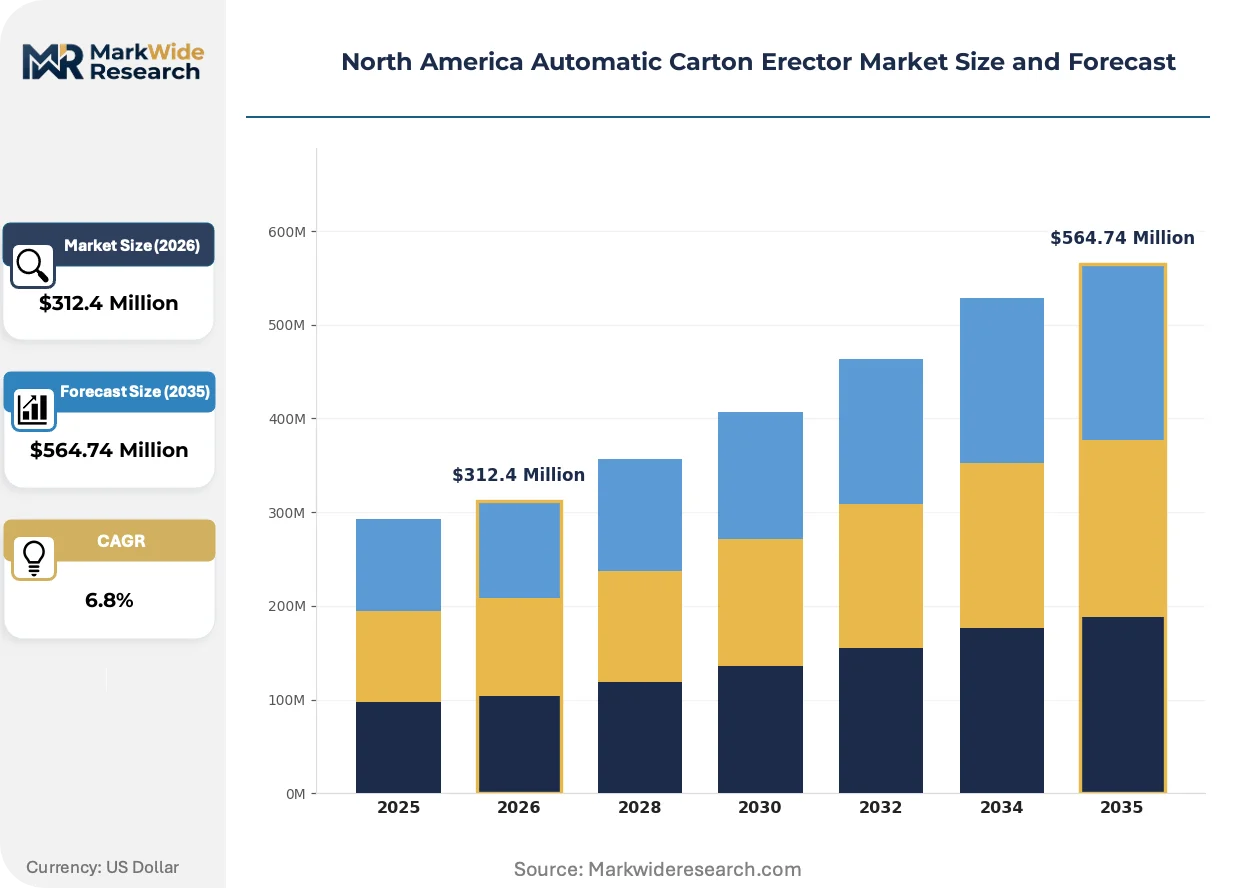
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Robotic, Manual End User: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Technology: Pneumatic, Electric, Hybrid, Mechanical Installation: Onsite, Offsite, Customized, Standard |
| Companies Covered | Lantech, Combi Packaging Systems LLC, Wexxar/BEL Packaging, Wayne Automation Corporation, A-B-C Packaging Machine, Pearson Packaging Systems, WestRock Company, Smurfit Kappa, Premier Tech Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automatic Carton Erector Market Evolving Landscape
Vision-guided blank feeding and adaptive forming mechanisms are collapsing changeover times for variable box size runs, reshaping competitive differentiation around flexibility rather than raw speed metrics.
Collaborative robotic blank loading systems with force-limiting actuators are rendering obsolete fixed-position mechanical magazine feeders in mid-volume pharmaceutical and nutraceutical packaging operations. Contract packagers serving multiple SKUs with daily changeovers adopt these configurations to eliminate dedicated magazine tooling inventories. The technology is rendering obsolete the traditional trade-off between throughput and format flexibility that constrained pneumatic erector deployment.
EPA energy efficiency guidelines and state-level motor efficiency tier requirements are tightening procurement specifications for electric drive selection. End users in food processing and distribution now specify NEMA Premium efficiency motors as baseline requirements, disqualifying lower-tier equipment from bid consideration. California Title 24 compliance documentation has become a standard line item in RFP evaluation scoring matrices.
Equipment-as-a-service contracting is displacing traditional capital purchase models among third-party logistics operators managing variable throughput commitments. Monthly per-case pricing agreements transfer maintenance burden and obsolescence risk to OEMs, aligning vendor incentives with uptime performance. This shift concentrates most visibly in the Midwest contract packaging sector where facility utilization fluctuates with seasonal retail demand cycles.
North America Automatic Carton Erector Market Segmentation
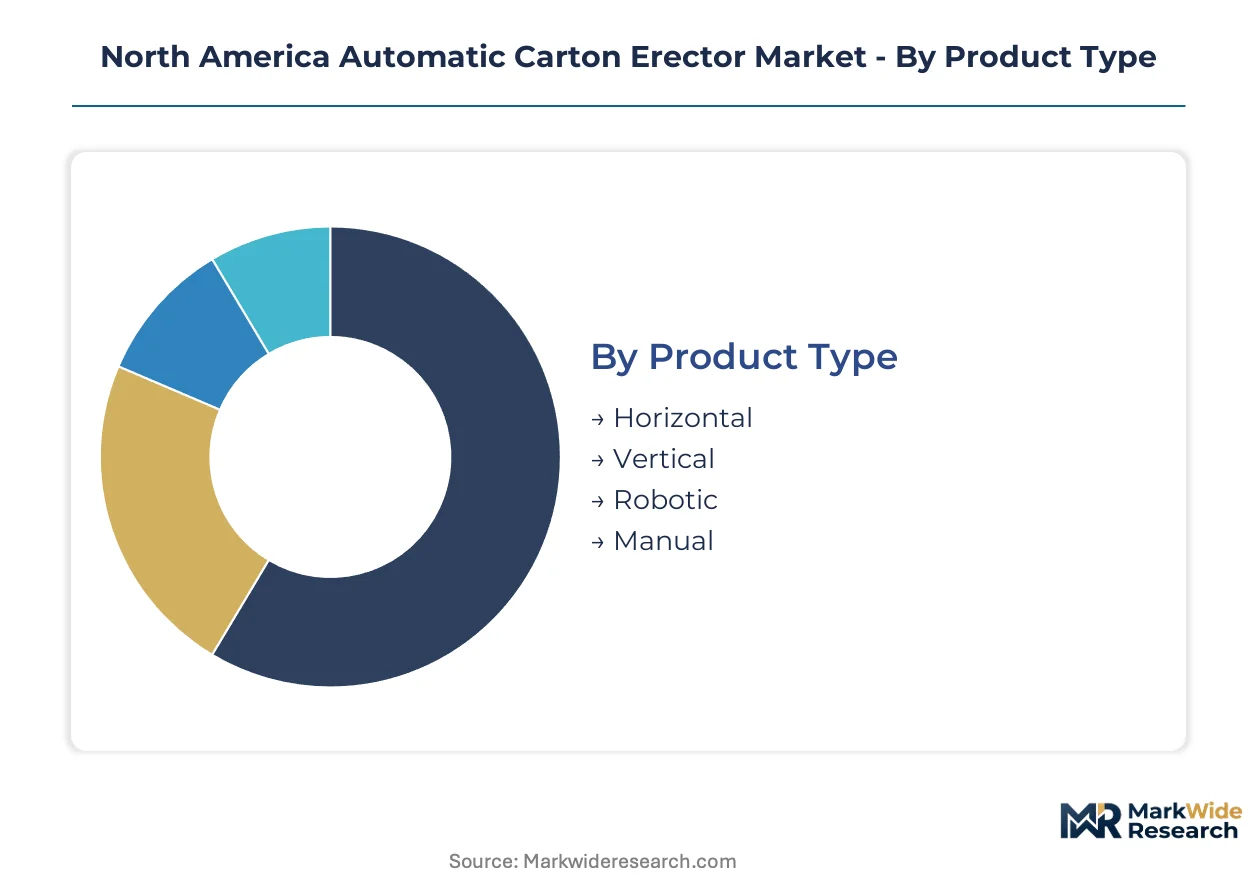
Segmentation in the North America automatic carton erector market reveals how equipment specifications diverge across fulfillment velocity requirements, regulatory exposure, and facility infrastructure constraints. Procurement patterns in Midwest manufacturing clusters versus California distribution corridors show distinct technology preferences that reshape vendor product roadmaps.
Product Type:
Cycle times vary dramatically across configurations, with robotic systems turning over formats in under 3 minutes while vertical erectors require lengthier mechanical changeovers for size adjustments.
- Horizontal:Side-loading blank magazines and reciprocating arm forming mechanisms achieve sustained rates of 35-50 cases per minute. Food and beverage processors across the Midwest manufacturing belt specify these for high-volume cereal and snack packaging lines where SKU proliferation demands rapid size transitions.
- Robotic:Articulated arm configurations with vision-guided blank picking adapt to variable corrugated specifications without mechanical tooling swaps. California e-commerce fulfillment centers deploy these for omnichannel operations handling 50+ box formats daily, absorbing premium capital costs to eliminate changeover labor.
- Vertical:Gravity-fed magazine systems with rotary forming turrets suit operations with stable, high-volume single-SKU runs. Personal care manufacturers favor these for shampoo and detergent bottles where case dimensions remain fixed across production campaigns.
- Manual:Semi-automated stations with operator-assisted blank positioning serve low-volume pharmaceutical packaging and pilot production facilities. Contract packagers in secondary markets deploy these for seasonal overflow capacity.
Horizontal erectors dominate installed base across North American food processing. Robotic configurations are where expansion concentrates in greenfield e-commerce fulfillment projects.
End User:
Margin structures diverge sharply by sector, with pharmaceutical validation requirements adding 30-40% to commissioning costs versus food and beverage deployments.
- Food & Beverage:Washdown-compatible stainless steel construction and FDA Title 21 CFR-compliant food-contact surfaces define procurement specifications. Midwest dairy and meat processors specify electric servo actuation to eliminate compressed air contamination risks in refrigerated environments.
- Pharmaceuticals:Cleanroom-compatible servo architectures with ISO 14644-1 Class 7 validation support serialized packaging lines under FDA 21 CFR Part 11. Northeast corridor biologics manufacturers drive demand for robotic erectors with force-limiting collaborative features.
- Personal Care:Cosmetic and hygiene product packagers prioritize cosmetic finishing and noise reduction for co-located manufacturing and office facilities. Texas and Southeast US operations favor hybrid drive systems balancing capital efficiency with energy compliance.
- Electronics:ESD-safe construction and precision forming for fragile component protection characterize specifications. Mexican nearshoring automotive electronics plants specify North American-sourced equipment to satisfy USMCA content requirements.
Food and beverage anchors volume demand. Pharmaceuticals represents the steepest expansion trajectory as serialization mandates tighten.
Technology:
Total cost of ownership calculations now span 10-year operational horizons, elevating electric and hybrid architectures over legacy pneumatic infrastructure in new capital planning.
- Electric:Servo motor actuation with integrated drive electronics delivers positional accuracy within 0.1mm for precision forming. California Title 24 energy compliance and EPA motor efficiency guidelines push specification toward NEMA Premium efficiency tiers in new construction.
- Hybrid:Combined pneumatic clamping with electric servo forming balances capital cost against operational flexibility. Pharmaceutical and nutraceutical packagers adopt these for cleanroom environments where compressed air quality can be controlled.
- Pneumatic:Cylinder-actuated forming mechanisms leveraging existing plant air infrastructure retain position in brownfield food processing facilities. Legacy installed base across the Great Lakes automation corridor sustains aftermarket service revenue.
- Mechanical:Cam-driven and linkage-based systems with minimal electronic content serve price-sensitive contract packaging segments. Standardized configurations support rapid deployment where customization is unnecessary.
Pneumatic systems dominate legacy installed base. Electric servo architectures are gaining share fastest in greenfield pharmaceutical and food sector projects.
Installation:
Deployment models fragment by customer capital structure, with third-party logistics operators shifting toward operational expenditure frameworks while captive manufacturers retain asset ownership.
- Onsite:Turnkey integration with existing conveyor infrastructure and control system handshaking. Midwest manufacturing belt facilities with dedicated maintenance staff prefer this model for complex multi-vendor line integration.
- Offsite:Pre-commissioned skid-mounted systems delivered as complete subassemblies reduce field installation time. California distribution corridor projects with compressed construction schedules specify these for rapid facility ramp.
- Customized:Application-specific magazine designs, forming head geometries, and control system programming for unique corrugated specifications. Pharmaceutical serialization lines require these configurations for track-and-trace integration.
- Standard:Catalog configurations with fixed mechanical parameters and limited size ranges. Contract packagers with predictable SKU portfolios deploy these to minimize engineering overhead and spare parts complexity.
Standard installations dominate transaction volume. Customized configurations are where margin expansion concentrates as pharmaceutical and specialty food validation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USMCA rules of origin and nearshoring incentives are redirecting capital toward North American manufacturing corridors. OSHA machine guarding mandates and EPA energy efficiency guidelines are accelerating electric erector adoption across food processing and distribution networks. Regional demand clusters around Midwest manufacturing belts, California distribution corridors, and Mexican industrial zones.
United States
E-commerce fulfillment velocity above 40 cases per minute is pulling robotic erector configurations into California distribution centers. OSHA workplace safety audits in Midwest meat and dairy processing plants are displacing legacy pneumatic systems with certified electric architectures. The Great Lakes automation corridor sustains dense concentrations of food and beverage packaging operations requiring rapid format changeover capabilities.
Canada
Pharmaceutical serialization mandates under Health Canada guidance are extending commissioning timelines for track-and-trace integrated erectors in Ontario biologics manufacturing. USMCA compliance documentation is pushing automotive parts packagers in Southern Ontario toward North American-sourced equipment. The Quebec food processing belt favors hybrid drive systems balancing refrigerated environment requirements with energy efficiency targets.
Mexico
Automotive and electronics manufacturers relocating assembly from Asia are specifying erectors satisfying USMCA content requirements to reduce trans-Pacific logistics exposure. Nuevo León and Baja California industrial parks are absorbing greenfield packaging line investments tied to nearshored supply chains. Mexican labor cost advantages are attracting contract packaging operations serving US retail seasonal demand cycles.
North America Automatic Carton Erector Market Competitive Landscape
On the supply side, the industry is consolidating around bundled automation offerings and specialized servo-electric architectures. Equipment fabricators compete through vertical integration into downstream case handling and stretch wrapping, or through cleanroom-compatible electric designs targeting pharmaceutical validation requirements. Dominant competitive moves include strategic bundling of erector systems with complementary automation and predictive maintenance service contracts shifting revenue toward recurring fees.
Within the integrated packaging systems tier, Lantech leverages its position across stretch wrapping and case handling to bundle erector technologies. WestRock Company anchors demand through captive packaging operations and direct equipment specification across its plant network. Pearson Packaging Systems exemplifies the servo-electric specialist archetype, occupying a position aligned with pharmaceutical and food-sector buyers seeking cleanroom-compatible installations.
| Leading Market Players |
|---|
| Lantech |
| Combi Packaging Systems LLC |
| Wexxar/BEL Packaging |
| Wayne Automation Corporation |
| A-B-C Packaging Machine |
| Pearson Packaging Systems |
| WestRock Company |
| Smurfit Kappa |
| Premier Tech Ltd |
| Others |
Value Network & Pricing Analysis
Intermodal freight corridors connecting Nuevo León assembly plants to Texas distribution hubs concentrate logistics cost volatility, compressing margin pools for pneumatic system fabricators while amplifying price premiums for USMCA-compliant electric servo architectures certified to FDA and OSHA standards.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with FDA Title 21 CFR-validated and OSHA-compliant electric servo systems commanding substantial premiums over standard pneumatic configurations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by motor efficiency tier, predictive maintenance bundling, and cleanroom compatibility validation. Cost compression in mid-range hybrid systems is intensifying because Japanese and German servo component sourcing concentrates supply risk. Contract packaging operators in the Midwest manufacturing belt exhibit highest price sensitivity, while pharmaceutical serialization lines in the Northeast corridor demonstrate lowest sensitivity due to validation-driven procurement mandates.
Supply Chain Analysis
Tariff exposure between Japan and Germany for servo motor and drive components dominates supply chain risk planning for North American erector OEMs. Component sourcing draws from Japanese precision motor suppliers, German industrial automation houses, and domestic steel fabricators in Ohio and Indiana. Raw material dependencies span cold-rolled steel for frame fabrication, aluminum for lightweight forming heads, and rare-earth magnets for servo motors. Single-source vulnerability in programmable logic controller supply creates extended lead time exposure. Distribution runs through OEM direct sales forces serving captive manufacturers and third-party logistics operators, with aftermarket parts flowing through regional service depots in Chicago, Dallas, and Ontario.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service contracts and condition-based monitoring subscriptions are expanding faster than hardware unit sales, repositioning vendor economics around recurring revenue attachment rates rather than capital equipment margins.
For Market Incumbents: Harden installed base retention by retrofitting legacy pneumatic systems with electric servo upgrade kits and embedding vibration analytics that lock in long-term service relationships. Expand backward integration into servo drive programming capabilities to reduce dependency on Japanese and German control suppliers. Defend against emerging equipment-as-a-service competitors by pre-emptively offering outcome-based uptime guarantees with embedded maintenance. For New Entrants and Emerging Players: Mexican nearshored automotive electronics plants represent the most penetrable entry point, where USMCA content requirements disqualify Asian-sourced competitors and local service presence remains thin. California Central Valley distribution facilities facing Title 24 energy compliance deadlines offer second-mover advantage for electric-only specialists with rapid deployment capabilities. Pursue skid-mounted offsite pre-commissioning to compress field installation timelines against entrenched turnkey integrators. For Investors and Strategic Acquirers: Servo-electric specialists with pharmaceutical validation expertise and established FDA 21 CFR Part 11 commissioning protocols represent the most defensible acquisition archetype for sustained margin expansion. Long-term viability hinges on recurring service revenue attachment rates exceeding hardware depreciation cycles. Monitor California Title 24 enforcement intensity and Health Canada serialization mandate expansion as inflection indicators for electric architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Electronics | Reduces dependency on Japanese and German control system suppliers facing extended lead times. |
| Condition-Based Service Contract Rollout | Shifts revenue from equipment sales to recurring monitoring fees aligned with uptime performance. |
| USMCA Content Certification Program | Unlocks procurement access in Mexican nearshored automotive and electronics assembly plants. |
| Cleanroom Validation Pre-Certification | Accelerates commissioning timelines for pharmaceutical serialization lines under FDA 21 CFR Part 11. |
| Skid-Mounted Offsite Pre-Commissioning | Compresses field installation schedules for California distribution corridor projects with tight ramp deadlines. |
Research Methodology
The analysis maps electric servo architectures, hybrid drive systems, pneumatic legacy installations, and robotic configurations, each validated through primary interviews with plant engineers, packaging line operators, maintenance directors, and OEM procurement teams across the Midwest manufacturing belt, California distribution corridors, and Mexican industrial zones. Secondary validation draws from OSHA machine guarding enforcement records, FDA Title 21 CFR guidance documents, EPA motor efficiency tier specifications, and USMCA rules of origin compliance databases. Bottom-up equipment shipment tracking and top-down end-use demand modeling triangulate market sizing.
Fixed assumptions include sustained OSHA workplace safety audit intensity, continued California Title 24 energy code enforcement, and stable USMCA content requirement thresholds across the projection horizon. Segmentation dimensions span product type, technology architecture, end-use sector, and installation deployment model. CAGRs derive from equipment replacement cycle analysis, greenfield capital expenditure trajectories, and technology substitution elasticity between pneumatic and electric servo systems. Forecast inputs incorporate e-commerce fulfillment velocity requirements and pharmaceutical serialization mandate expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in steel and aluminum commodity pricing, Japanese yen-Euro currency volatility, or trans-Pacific logistics cost structures would shift the trajectory. Material shifts in FDA validation protocol stringency or OSHA machine guarding enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Kitchen/ Toilet Roll Converting Machines Market
Packaging Machinery
High Vacuum Filling Machine Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Sleeve Wrapping Machine Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Thermal Laminating Machine Market
Packaging Machinery
Blind Box Machine Market
Packaging Machinery
Screw Capping Machines Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
Global Blister Packaging Machinery Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Side Sealer Machines Market
Packaging Machinery
Twist Tie Machines Market