
 Aerosol Filling Machines Market | 2026-2036
Aerosol Filling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Aerosol Filling Machines Market Outlook
The gap between premium fully automatic lines and commodity semi-automatic units is expanding as brand owners demand traceability and throughput guarantees. OPTIMA Packaging Group leverages its integrated vision systems to command positions in pharmaceutical-grade installations. Krones anchors its portfolio through beverage-crossover technologies adapted to aerosol crimping. Coster Tecnologie Speciali differentiates via valve integration expertise that reduces downstream assembly steps.
Aerosol filling machines are precision-engineered systems that meter propellant and product into pressurized containers under controlled temperature and pressure conditions, typically achieving fill tolerances within one percent. These machines serve industries where hermetic sealing, propellant safety, and batch consistency determine product integrity and user safety. Fully automatic lines now capture the dominant share of capital expenditure as labor costs and throughput requirements escalate across cosmetics and pharmaceutical end users. Aluminum container formats are outpacing steel alternatives due to lightweighting trends and recycling infrastructure investments in Europe and North America.
EPA regulations in the United States restrict volatile organic compound emissions during filling operations, compelling upgrades to closed-loop recovery systems. EMA and REACH frameworks in Europe enforce material compatibility documentation and propellant purity thresholds that filter out non-compliant equipment suppliers. Manufacturers must monitor evolving F-Gas Regulation amendments and state-level air quality mandates that will determine eligible machine configurations for cross-border sales.
Market Dynamics
Propellant containment engineering now dictates capital allocation as EPA and REACH frameworks mandate closed-loop recovery architectures, forcing equipment refresh cycles that favor sealed-environment systems over legacy open-filling configurations.
Growth Catalysts
- REACH compliance mandates:ECHA documentation requirements for material compatibility and propellant purity thresholds filter out non-compliant suppliers, elevating demand for certified European installations.
- Aluminum lightweighting:Container format migration from steel to aluminum across cosmetics and pharmaceutical packaging drives retrofit demand for crimping and seaming equipment optimized for thinner-gauge metals.
- India capacity scaling:Domestic aerosol production clusters in Gujarat and Maharashtra under PLI scheme incentives attract greenfield filling line investments from multinational contract manufacturers.
Market Restraints
- Specialized alloy supply concentration:High-grade stainless steel for pressure-rated filling chambers sources predominantly from German and Japanese mills, exposing lead time volatility.
- F-Gas regulatory friction:Evolving EU amendments to fluorinated gas restrictions complicate cross-border equipment certification and propellant handling system configurations.
- Technical throughput ceilings:Hermetic sealing tolerances below one percent impose hard limits on line speed acceleration without vision system upgrades.
Strategic Opportunities
- Pharmaceutical-grade expansion:Sterile aerosol formats for inhalation therapies remain underpenetrated in Southeast Asian manufacturing bases, creating first-mover positioning for validated cleanroom-integrated lines.
- Dual carbon convergence:Integration of renewable energy monitoring with filling line automation aligns with China's MIIT dual carbon goals and attracts state-backed facility financing.
- Service unbundling:Separate contracting for predictive maintenance modules and spare part logistics creates recurring revenue streams distinct from capital equipment sales.
Industry Challenges
- Mechatronics talent scarcity:Cross-functional engineers capable of integrating pneumatic, electronic, and software subsystems command premium compensation and extend commissioning timelines.
- Legacy system interoperability:Retrofitting Industry 4.0 data architectures onto decade-old filling lines requires custom middleware development that strains project budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerosol Filling Machines Market |
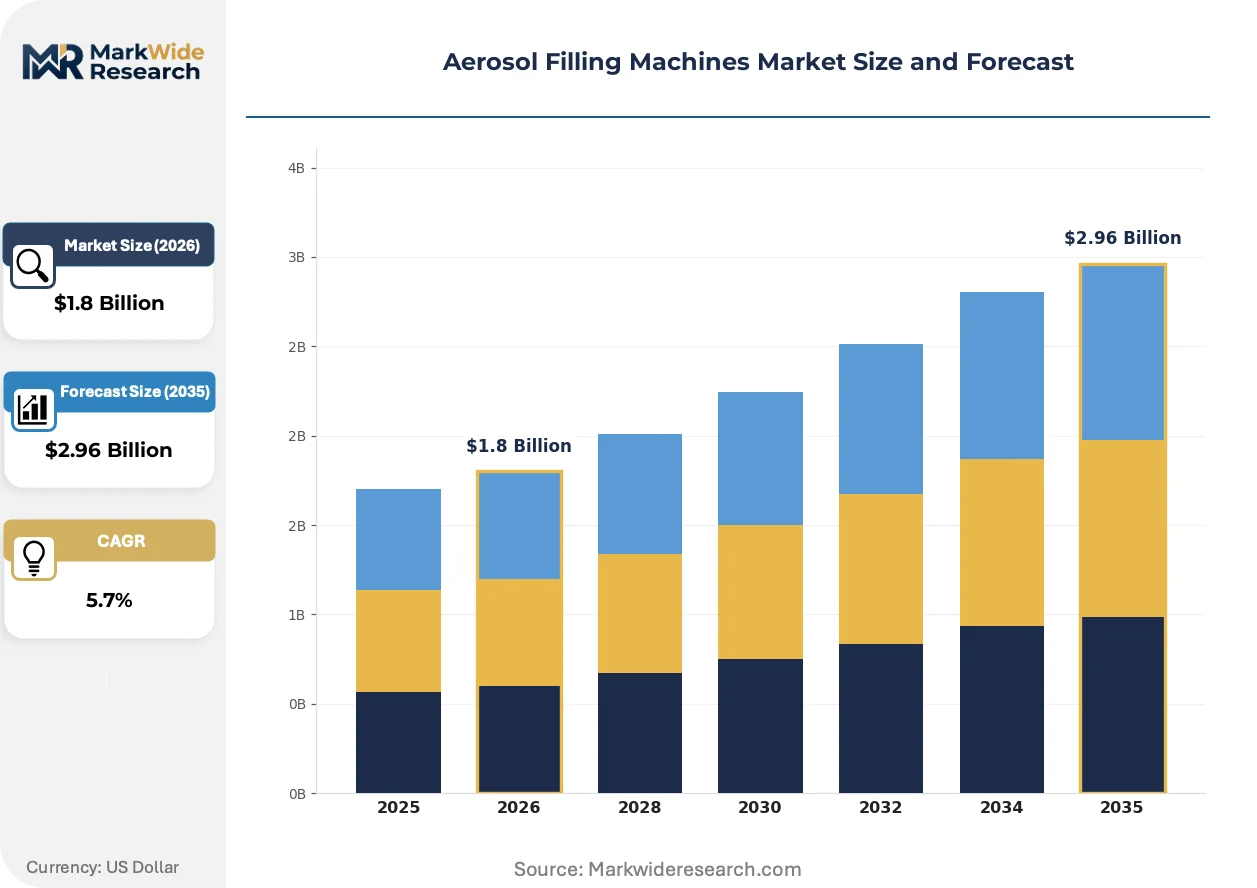
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Fully Automatic, Portable Container Type: Aluminum, Steel, Glass, Plastic End User: Cosmetics, Pharmaceuticals, Household, Industrial Filling Technology: Pressure Filling, Vacuum Filling, Gravity Filling, Crimping |
| Companies Covered | OPTIMA Packaging Group, Coster Tecnologie Speciali, Krones, HITIT Machine, Pneumatic Scale Angelus, MBC Aerosol, Deckerт Maschinenbau, Adolf Illig Maschinenbau, Guangzhou Weijing Intelligent Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerosol Filling Machines Market Strategic Shifts
Vision-guided precision systems and propellant recovery architectures are compressing the capability gap between pharmaceutical and industrial-grade equipment, while procurement patterns favor outcome-guaranteed performance contracts over traditional capital purchase models.
Machine vision integration with real-time seam inspection is expanding into mid-tier cosmetic installations previously served by manual quality stations. Brands in Germany and France now specify vision verification as a contractual throughput guarantee, compressing competitive differentiation around defect detection speed rather than mechanical reliability alone. This technology diffusion is expanding into secondary packaging verification and batch traceability documentation.
EPA volatile organic compound emission restrictions are compelling closed-loop propellant recovery system adoption across US-based contract filling operations. The industrial consequence is elevated capital intensity for equipment upgrades, with smaller regional fillers deferring replacement and ceding volume to integrated multinationals. California and Texas state-level air quality mandates are accelerating this consolidation pattern.
Cosmetics brands now contract for guaranteed output-per-hour metrics rather than equipment ownership, transferring operational risk to machinery suppliers. This performance-based arrangement displaces traditional capex procurement in North American and Western European markets, with suppliers embedding remote monitoring and predictive maintenance to defend margin structures. Pharmaceutical contract manufacturers in Switzerland and Ireland have pioneered this shift, establishing template terms now migrating to personal care applications.
Aerosol Filling Machines Market Segmentation
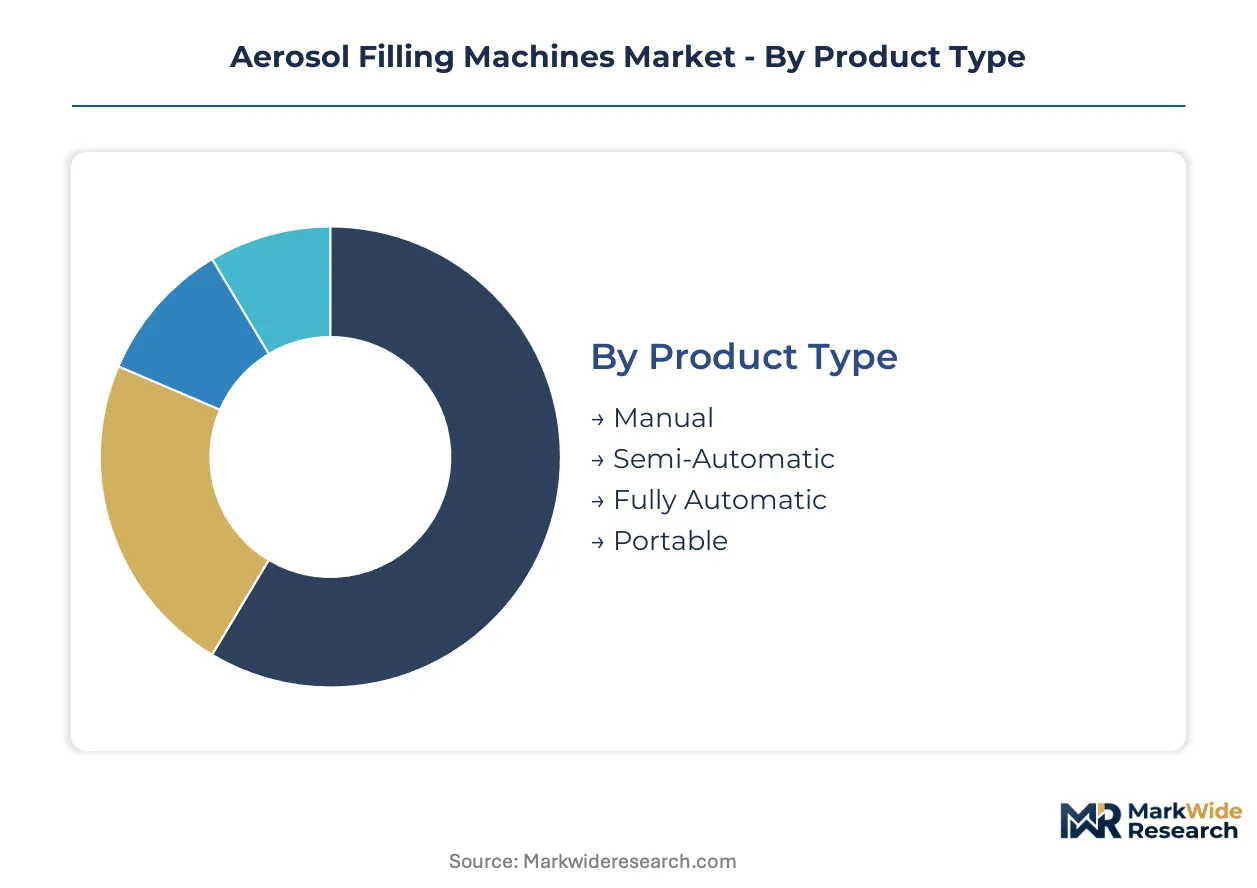
Segmentation in aerosol filling machines reveals how regulatory burden, container material evolution, and end-use precision requirements fragment procurement patterns across equipment categories. Buyers align capital allocation with specific compliance thresholds and throughput guarantees rather than selecting on price alone.
Product Type:
EPA emission controls and REACH material documentation impose divergent certification loads across automation tiers, with pharmaceutical and cosmetics buyers demanding validated documentation packages that only certain configurations can supply.
- Fully Automatic:These lines integrate propellant recovery, vision inspection, and sealed-environment architectures required for EPA volatile organic compound compliance and REACH material purity thresholds. Cosmetics manufacturers in Germany and pharmaceutical contract operators in Switzerland specify these systems for throughput guarantees above 200 units per minute with hermetic sealing tolerances within one percent.
- Semi-Automatic:Units occupy the mid-tier for regional fillers serving household and industrial end uses where labor costs remain manageable and batch sizes fluctuate. Indian domestic manufacturers in Gujarat leverage these configurations under PLI scheme incentives where capital constraints limit full automation investment.
- Manual:Benchtop configurations serve prototyping laboratories and specialty fragrance houses requiring rapid formulation changeover with minimal propellant inventory.
- Portable:Mobile filling stations enable on-site contract manufacturing for event-specific promotional aerosols and limited-run cosmetic launches.
Leading the category by volume: Fully Automatic. Growing fastest: Semi-Automatic in emerging manufacturing clusters.
Container Type:
Material selection drives crimping equipment specification and recycling infrastructure compatibility, with European and North American buyers prioritizing formats aligned with existing collection systems.
- Aluminum:Lightweight, infinitely recyclable, and compatible with thin-gauge seaming equipment optimized for cosmetics and pharmaceutical packaging. European recycling infrastructure investments and North American lightweighting mandates accelerate format migration from steel alternatives.
- Steel:Retains cost advantage for industrial aerosols and household products where container weight matters less than material cost. Legacy filling lines in mature manufacturing bases require minimal retrofit for steel formats.
- Glass:Specialized pharmaceutical applications requiring inert propellant contact surfaces and visual clarity for suspension inspection.
- Plastic:Emerging formats for water-based propellant systems and reduced-pressure applications in personal care where metal elimination supports sustainability claims.
Dominant by installed base: Aluminum. Expanding most quickly: Plastic in experimental personal care formats.
End User:
End-use segmentation separates buyers by validation depth, with pharmaceutical and cosmetics purchasers demanding equipment qualification protocols that industrial and household users rarely require.
- Pharmaceuticals:Inhalation therapies and sterile aerosol formats demand cleanroom-integrated lines with batch traceability documentation and EMA-validated changeover procedures. Swiss and Irish contract manufacturers pioneered performance-based procurement models now migrating to this segment.
- Cosmetics:Fragrance, hair care, and skincare brands specify vision-guided precision systems with real-time seam inspection as contractual throughput guarantees. German and French procurement teams now mandate vision verification for premium positioning.
- Household:Cleaners, air fresheners, and insecticides prioritize throughput over precision, accepting wider fill tolerances in exchange for capital efficiency.
- Industrial:Lubricants, coatings, and adhesives require corrosion-resistant filling chambers and specialized propellant handling for high-pressure formulations.
Highest equipment specification: Pharmaceuticals. Steepest expansion trajectory: Cosmetics as brand owners consolidate contract manufacturing.
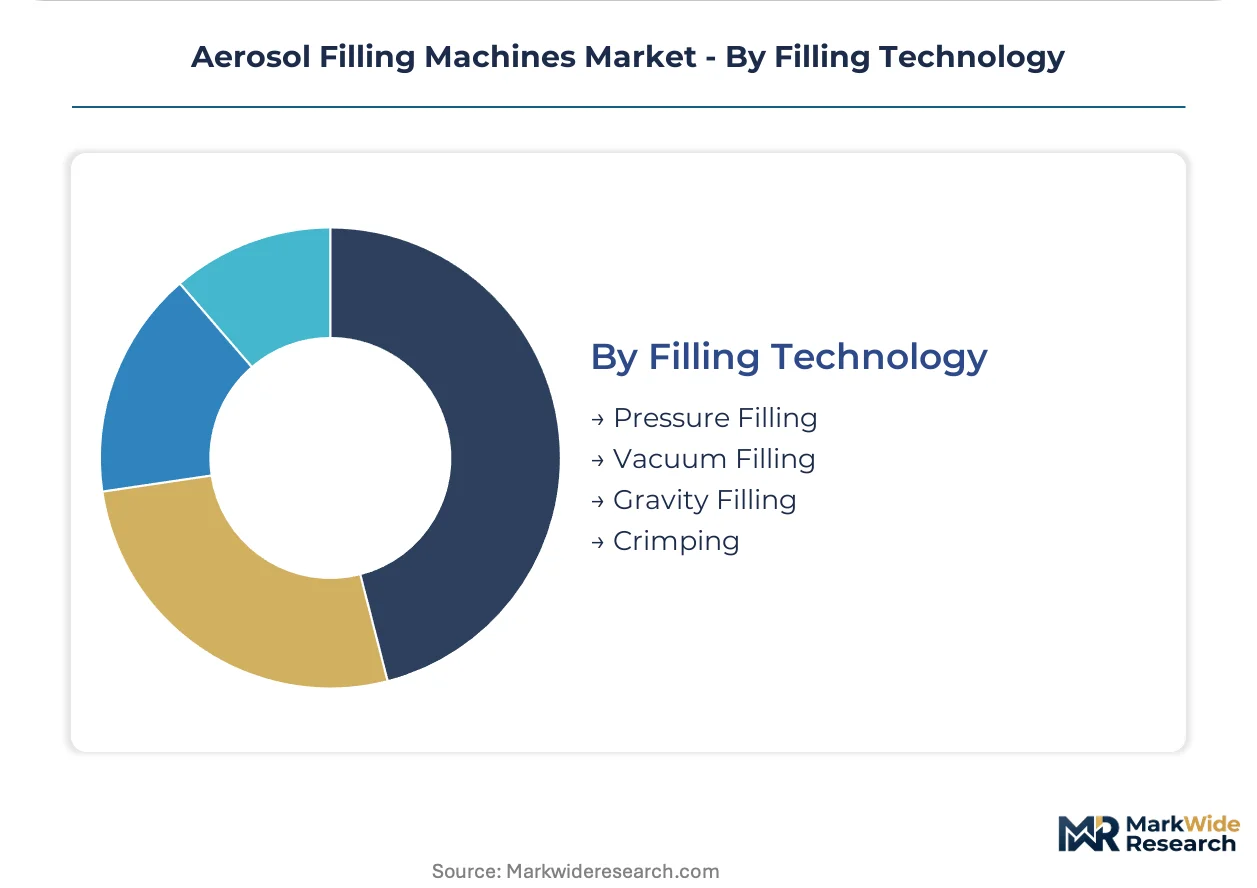
Filling Technology:
Technology selection determines propellant containment architecture and emission control compliance, with regulatory frameworks in the United States and Europe filtering available configurations.
- Pressure Filling:Standard for liquefied gas propellants requiring temperature-controlled metering and sealed-environment recovery systems to meet EPA volatile organic compound restrictions. California and Texas state-level mandates accelerate adoption across US-based operations.
- Vacuum Filling:Enables oxygen-sensitive product integrity for pharmaceutical suspensions and natural cosmetic formulations requiring inert headspace conditions.
- Gravity Filling:Simplified architecture for low-pressure water-based systems and experimental propellant alternatives where precision tolerance requirements relax.
- Crimping:Valve integration expertise reduces downstream assembly steps, with Coster Tecnologie Speciali and comparable suppliers differentiating through one-step sealing validation.
Widest installed base: Pressure Filling. Gaining share fastest: Vacuum Filling for oxygen-sensitive pharmaceutical formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's domestic aerosol production clusters anchor capacity scaling across India under PLI scheme incentives, while Germany's precision engineering corridors and China's Yangtze River Delta manufacturing bases concentrate automated filling line investments.
Germany
Cosmetics manufacturers in the Rhine-Ruhr region specify vision-guided precision systems with contractual throughput guarantees. REACH documentation requirements from ECHA filter equipment suppliers through material compatibility and propellant purity thresholds. Stuttgart's automotive-crossover engineering ecosystem feeds component specialization into pharmaceutical-grade filling architectures.
China
MIIT dual carbon goals attract state-backed facility financing for renewable energy-integrated filling lines in the Yangtze River Delta. Domestic aerosol brands scale automated capacity to serve personal care contract manufacturing demand. Shanghai's port infrastructure enables import substitution for high-grade stainless steel pressure chambers previously sourced from Japanese mills.
India
PLI scheme incentives for domestic aerosol production concentrate greenfield investments in Gujarat and Maharashtra clusters. Regional contract manufacturers leverage semi-automatic configurations where capital constraints limit full automation. Mumbai's pharmaceutical export corridors drive demand for validated cleanroom-integrated lines serving inhalation therapy formats.
United States
EPA volatile organic compound emission restrictions compel closed-loop recovery system adoption across California and Texas contract filling operations. State-level air quality mandates accelerate consolidation toward integrated multinationals with sealed-environment architectures. Chicago's industrial packaging corridor hosts retrofit demand for legacy lines facing regulatory obsolescence.
Switzerland
Pharmaceutical contract manufacturers in Basel and Zurich pioneered performance-based procurement models now migrating to cosmetics applications. Swissmedic validation requirements enforce batch traceability documentation that filters equipment suppliers. The country's precision mechatronics talent pool commands premium compensation for cross-functional integration of pneumatic and software subsystems.
Aerosol Filling Machines Market Competitive Environment
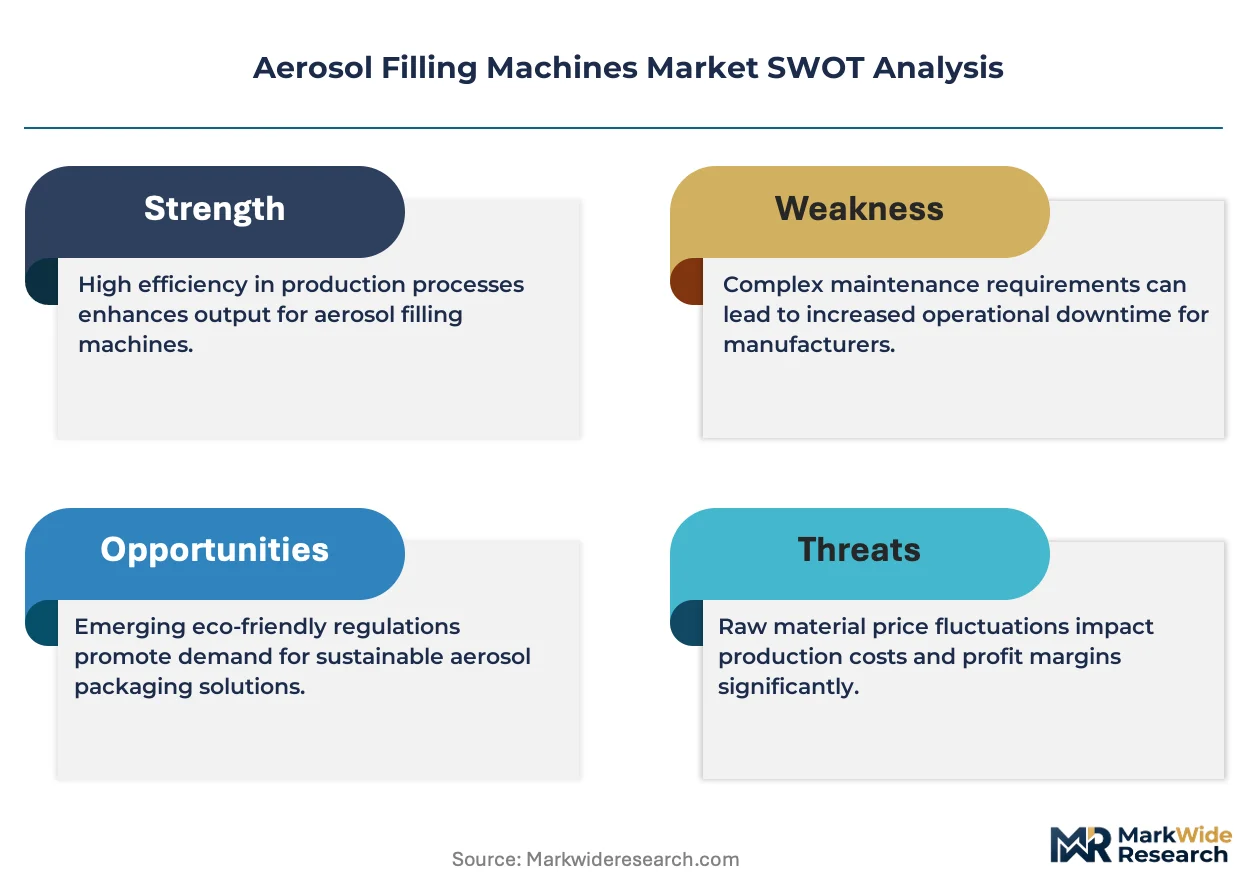
Capital-heavy producers compete with asset-light designers across a bifurcated vendor landscape where integrated packaging groups anchor premium-tier positions while regional fabricators occupy mid-market segments. The market structure concentrates around three strategic archetypes: vision-system integrators serving pharmaceutical-grade specifications, beverage-crossover specialists adapting crimping technologies, and valve-integration experts reducing downstream assembly complexity. Consolidation pressure emanates from M&A activity among European precision engineering groups and capacity expansion programs targeting Indian PLI scheme incentives.
Among German-based engineering groups, OPTIMA Packaging Group and Krones occupy positions representing integrated packaging automation archetypes, while Coster Tecnologie Speciali exemplifies the valve-integration specialist tier. These three anchors demonstrate how geographic proximity to REACH regulatory expertise and precision manufacturing infrastructure shapes competitive positioning across the European vendor base.
| Leading Market Players |
|---|
| OPTIMA Packaging Group |
| Coster Tecnologie Speciali |
| Krones |
| HITIT Machine |
| Pneumatic Scale Angelus |
| MBC Aerosol |
| Decker Maschinenbau |
| Adolf Illig Maschinenbau |
| Guangzhou Weijing Intelligent Equipment |
| Others |
Value Chain & Pricing Dynamics
Backward integration into high-grade stainless steel pressure chamber fabrication anchors supply positioning for European and Japanese equipment builders, compressing pricing power toward mills in Germany and Japan while elevating capital barriers for mid-tier competitors sourcing from spot markets. This captive supply structure permits premium-tier manufacturers to defend margin structures through material certification guarantees that commodity fabricators cannot replicate.
Pricing Analysis
Outcome-guaranteed throughput contracts now dominate capital procurement across cosmetics and pharmaceutical end users, with pricing stratifying across premium, standard, and economy tiers based on vision system integration depth and REACH documentation package completeness. Price differentiation hinges on hermetic sealing tolerance guarantees and propellant recovery architecture certification, with California EPA compliance tiers commanding substantial premiums over baseline configurations. Cost compression in semi-automatic segments is intensifying because Indian PLI scheme incentives attract regional fabricators with lower labor-cost structures. Household and industrial end users exhibit highest price sensitivity, while Swiss pharmaceutical contract manufacturers demonstrate lowest sensitivity due to validation protocol requirements.
Supply Chain Analysis
Mechatronics talent scarcity in Stuttgart and Shanghai manufacturing corridors extends commissioning timelines and elevates labor cost components for cross-functional engineers integrating pneumatic, electronic, and software subsystems. Geographic supply concentration centers on Germany, China, and Japan, with high-grade stainless steel for pressure-rated filling chambers drawing predominantly from German and Japanese mills. Raw material dependencies encompass specialized alloys, precision pneumatic components, and machine vision hardware modules. Single-source vulnerability persists for thin-gauge aluminum seaming equipment optimized for lightweighting trends. Distribution runs through direct OEM sales for fully automatic lines and regional distributor networks for semi-automatic configurations serving emerging manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over valve integration expertise and precision alloy supply chains determines competitive survival. Players are pursuing downstream service unbundling to capture recurring revenue streams distinct from capital equipment sales.
For Market Incumbents: Acquire predictive maintenance software capabilities and spare part logistics networks to defend margin structures against emerging asset-light designers. Consolidate positions through certification investment in EMA-validated cleanroom architectures that filter out non-compliant regional competitors. Capacity addition in Gujarat and Maharashtra under Indian PLI scheme incentives secures volume exposure to fastest-growing demand clusters. For New Entrants and Emerging Players: The premium-to-economy price-point gap in pharmaceutical-grade installations offers white-space entry for validated cleanroom-integrated lines serving Southeast Asian manufacturing bases. Target semi-automatic configurations for domestic Indian manufacturers where capital constraints limit full automation penetration. Pursue outcome-based procurement templates pioneered by Swiss contract manufacturers as the go-to-market angle for cosmetics brand owners seeking throughput guarantees. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated packaging groups seeking valve integration expertise and vision system capabilities. Long-term viability favors suppliers with demonstrated REACH compliance documentation and renewable energy-integrated automation aligned with China's MIIT dual carbon goals. Watch F-Gas Regulation amendment trajectories as the inflection indicator for equipment certification obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Valve Integration Acquisition | Coster Tecnologie Speciali's one-step sealing validation reduces downstream assembly complexity for pharmaceutical lines. |
| Vision System Partnership | OPTIMA Packaging Group leverages integrated vision systems to command positions in pharmaceutical-grade installations. |
| Renewable Energy Integration | MIIT dual carbon goals in China attract state-backed facility financing for cleanroom-integrated filling automation. |
| Service Unbundling Launch | Predictive maintenance modules create recurring revenue streams distinct from capital equipment sales in European markets. |
| PLI Scheme Capacity Expansion | Gujarat and Maharashtra clusters under Indian incentives concentrate greenfield investments from multinational contract manufacturers. |
Study Parameters
Document review covered customs and trade data, EPA emission filings, ECHA REACH registrations, and PLI scheme disclosure documents, complemented by interviews with plant engineers at cosmetics manufacturers, procurement leads at pharmaceutical contract operators, aftermarket service heads at filling line OEMs, and technical R&D directors at valve integration specialists. Secondary validation drew from SEC filings of integrated packaging groups, MIIT facility financing disclosures, and Swissmedic validation requirement publications. Bottom-up equipment shipment tracking and top-down end-use demand estimation were triangulated against regulatory compliance cost modeling.
Historical capacity expansion patterns were cross-referenced against panel input from equipment procurement committees to anchor projection assumptions across the analysis window. Segmentation dimensions modeled encompass automation tier, container material format, end-use industry, filling technology architecture, and regional regulatory cluster. CAGRs were derived through weighted average of demand elasticity coefficients and capital expenditure intention surveys. Industry-specific forecast inputs incorporated aluminum lightweighting migration rates and F-Gas Regulation amendment probability assessments.
Inputs from ECHA documentation databases and MIIT facility financing registries were available through the study window; gaps in real-time propellant handling system cost disclosures introduce uncertainty bands around sealed-environment architecture penetration assumptions. Forecasts reflect documented regulatory trajectories and announced capacity expansion commitments. Material deviation in EPA state-level mandate enforcement intensity or REACH material purity threshold amendments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Global Blow Molding Machine Market
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Automatic Auger Fillers Market
Packaging Machinery
Corrugated Box Machines Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
Tube Sealing Machines Market
Packaging Machinery
Horizontal Strapping Machine Market
Packaging Machinery
Multi-Head Filling Machines Market
Packaging Machinery
Heavy Duty Band Sealer Machine Market
Packaging Machinery
Sanitizer Filling Machine Market
Packaging Machinery
Confectionery Packaging Machine Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Kitchen/ Toilet Roll Converting Machines Market