
 Plastic Blow Molding Machine Market | 2026-2036
Plastic Blow Molding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Blow Molding Machine Market Analytics
Aftermarket service revenue is tilting from break-fix contracts toward predictive maintenance subscriptions and remote monitoring platforms. Krones AG leverages its global installed base to anchor long-term service agreements across beverage bottling corridors. Sidel Group competes through embedded IoT diagnostics that sustain higher attach rates on stretch blow molding lines. Nissei ASB Machine Co., Ltd. differentiates via precision mold refurbishment capabilities that extend machine lifecycles in Asian packaging hubs.
Plastic blow molding machines form hollow thermoplastic articles by inflating heated parisons within cooled mold cavities, typically processing PET, HDPE, or PP at clamp forces ranging from under 50 tons to exceeding 600 tons for automotive fuel tank production. These systems serve primarily the packaging sector, where wall thickness uniformity and neck finish precision determine container performance. Extrusion blow molding occupies the largest installed base due to its versatility with industrial and automotive hollow parts, while stretch blow molding captures expanding share in carbonated and still beverage applications where biaxial orientation yields superior clarity and drop resistance. Injection blow molding retains structural importance in pharmaceutical and healthcare packaging where flash-free necks and tight dimensional tolerances are mandatory.
The US FDA governs contact materials for food and pharmaceutical packaging, compelling machine builders to validate steel grades and lubricant chemistries that eliminate contamination risk. Europe's CE marking and evolving MDR-aligned documentation requirements shape export compliance costs for Asian equipment suppliers accessing EU bottling markets. China's GB standards and SAMR technical regulations enforce energy efficiency thresholds that favor servo-electric over hydraulic architectures in domestic procurement. Stakeholders must weigh regulatory divergence against platform standardization when configuring regional product portfolios.
Market Dynamics
Electric servo architectures are displacing hydraulic systems across beverage bottling corridors as energy efficiency mandates tighten and converter margins compress under lightweighting specifications.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases in cooling circuits redirects capital toward electric blow molding platforms with lower refrigerant dependency.
- Pharmaceutical serialization:Track-and-trace mandates for unit-level coding expand demand for injection blow molding systems delivering flash-free neck finishes and dimensional repeatability.
- China's dual carbon goals:Provincial energy intensity targets favor servo-electric machine procurement in domestic packaging converter tenders, accelerating technology substitution.
Market Restraints
- Steel grade certification costs:FDA validation requirements for food-contact materials elevate tooling qualification expenses and extend new machine commissioning timelines.
- Mold fabrication concentration:Precision cavity machining capacity clusters in German and Japanese supplier bases, creating delivery bottlenecks during demand surges.
- rPET feedstock inconsistency:Recycled polyethylene glycol terephthalate lot-to-lot viscosity variation complicates process window stabilization in high-speed stretch blow lines.
Strategic Opportunities
- India's PLI scheme for packaging machinery:Production-linked incentives for capital goods manufacturing attract greenfield assembly investments serving South Asian beverage markets.
- Remote monitoring convergence:Embedded IoT diagnostics fused with predictive algorithms enable subscription revenue models displacing traditional break-fix service contracts.
- Healthcare barrier packaging:Multilayer co-injection blow molding for oxygen-sensitive pharmaceuticals opens premium machine configurations in regulated European and North American markets.
Industry Challenges
- Servo commissioning expertise:Shortage of technicians proficient in electric drive tuning and regenerative power management extends installation acceptance periods.
- Legacy hydraulic fleet retrofit:Integration of modern control architectures with existing clamp and extrusion subsystems generates compatibility failures and unplanned downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Blow Molding Machine Market |
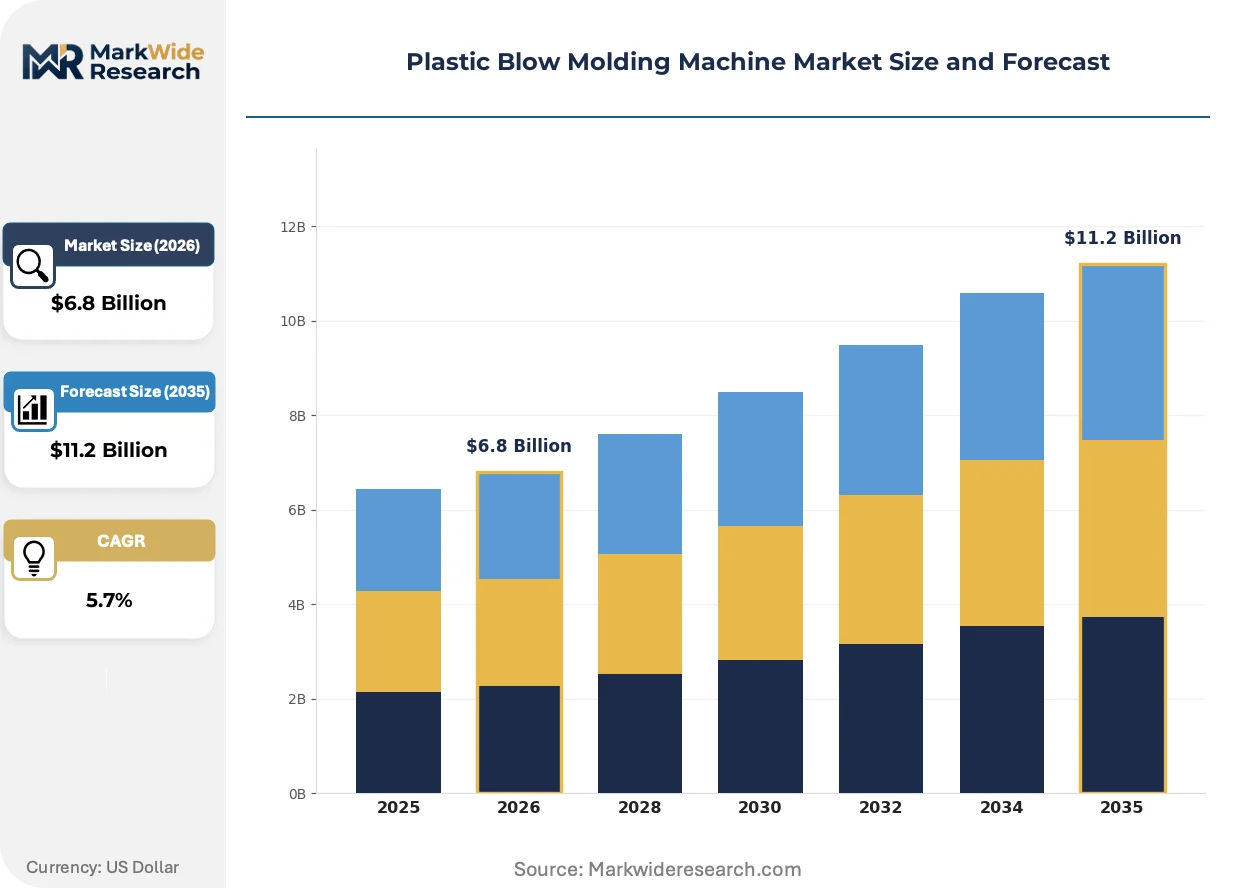
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Blow Molding, Injection Blow Molding, Extrusion Blow Molding, Multi-layer Blow Molding Industry Vertical: Automotive, Consumer Goods, Healthcare, Packaging End User: Manufacturers, OEMs, Retailers, Distributors Technology: Automatic, Semi-Automatic, Manual, Hybrid |
| Companies Covered | Krones AG, Sidel Group, Nissei ASB Machine Co., Ltd., Kautex Maschinenbau GmbH, Bekum Maschinenfabriken GmbH, Uniloy, Jomar Corporation, Sumitomo Heavy Industries, Ltd., SIPA S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Blow Molding Machine Market Evolving Landscape
Digital twin deployment and material circularity requirements are restructuring how machine builders validate designs and how converters justify capital expenditure. These forces are compressing development cycles while elevating service attach rates.
Virtual commissioning software is virtualizing factory acceptance testing protocols for complex multi-cavity stretch blow lines. Tier-one beverage converters in Germany and the United States now require simulation-validated cycle time guarantees before releasing final payments. This capability is virtualizing risk allocation between equipment suppliers and end-users, compressing dispute resolution timelines and accelerating production ramp schedules.
Europe's F-Gas Regulation and evolving MDR-aligned documentation requirements are elevating compliance engineering headcount at Asian equipment suppliers accessing EU bottling markets. CE marking technical file depth now rivals FDA validation dossiers for pharmaceutical packaging configurations. German automotive fuel tank manufacturers face parallel REACH substance restrictions on polymer additives, forcing reformulation of HDPE compounds processed on high-tonnage accumulator blow molding systems.
After-sales service unbundling is fragmenting traditional maintenance contracts into discrete predictive, remote, and on-demand modules. North American beverage converters now procure vibration monitoring and algorithmic failure prediction as standalone subscriptions rather than bundled warranty extensions. This pattern is most pronounced in high-volume PET bottling corridors where unplanned downtime costs exceed preventive service premiums by order-of-magnitude multiples.
Plastic Blow Molding Machine Market Segmentation
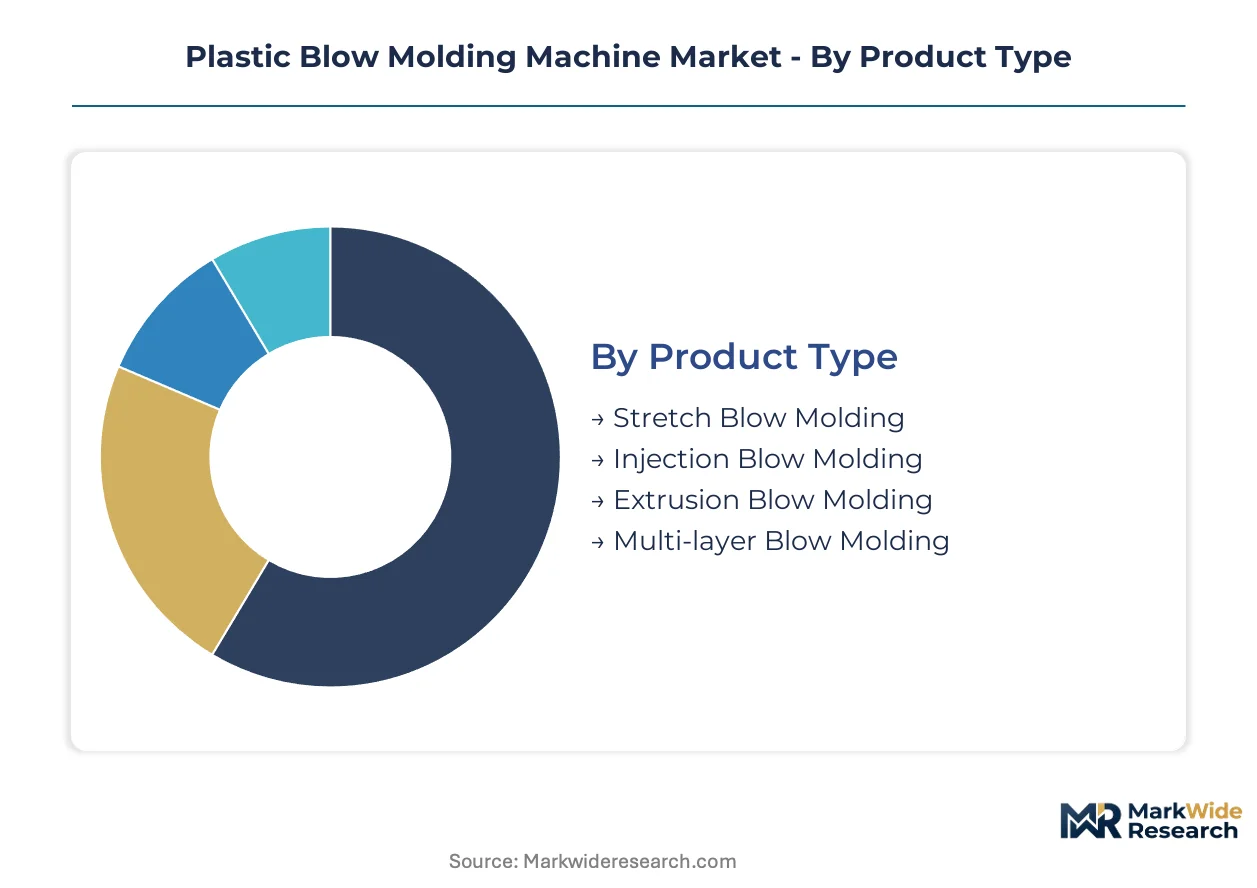
Segmentation in plastic blow molding machines exposes how cycle-time requirements, regulatory complexity, and automation intensity fragment procurement patterns across converter tiers. Machine architecture selection directly determines energy recovery potential, mold changeover velocity, and qualification burden.
Product Type:
Stretch blow molding lines turn over fastest in beverage corridors where lightweighting specifications compress replacement cycles, while accumulator-head extrusion systems for automotive fuel tanks operate on decade-long depreciation schedules.
- Stretch Blow Molding:Biaxial orientation of PET parisons yields superior clarity and drop resistance for carbonated beverage containers. Demand concentrates in Germany and China where bottling line automation rates exceed 90% and converter margins force continuous lightweighting investments.
- Injection Blow Molding:Flash-free neck finishes and dimensional repeatability serve pharmaceutical serialization mandates. European and North American healthcare packaging corridors drive specification tightening as MDR-aligned documentation requirements elevate validation costs.
- Extrusion Blow Molding:Versatility with HDPE and PP industrial hollow parts sustains the largest installed base across automotive and consumer goods applications.
- Multi-layer Blow Molding:Co-injection architectures for oxygen-sensitive pharmaceuticals command premium configurations in regulated markets.
Extrusion blow molding dominates installed base. Stretch blow molding is where expansion concentrates.
Industry Vertical:
Packaging converters operate on 18-36 month equipment refresh cycles, while automotive fuel tank manufacturers amortize high-tonnage systems over 10-15 year horizons, creating divergent margin structures.
- Packaging:PET bottle specifications tighten continuously across beverage and personal care segments. China's dual carbon goals and provincial energy intensity targets favor servo-electric machine procurement in domestic converter tenders.
- Healthcare:Barrier packaging for oxygen-sensitive pharmaceuticals requires multilayer co-injection systems with validated steel grades and lubricant chemistries per FDA contact-material rules.
- Automotive:HDPE fuel tank production on accumulator-head systems faces REACH substance restrictions on polymer additives in German manufacturing clusters.
- Consumer Goods:Industrial hollow parts for household applications sustain demand for versatile extrusion platforms with rapid mold changeover capability.
Packaging commands the highest unit velocity. Healthcare delivers the steepest expansion trajectory.
End User:
Direct manufacturers capture efficiency gains through captive mold refurbishment programs, while distributor networks absorb inventory risk for smaller converters with irregular capital deployment cycles.
- Manufacturers:Tier-one beverage bottlers in the United States and Germany require simulation-validated cycle time guarantees and embedded IoT diagnostics before final payment release.
- OEMs:Automotive fuel tank suppliers integrate blow molding cells into just-in-sequence assembly lines, demanding regenerative power management and electric servo architectures.
- Retailers:Private-label packaging converters procure through equipment financing arrangements that shift technology risk to lessors.
- Distributors:Regional machinery dealers service mid-volume converters in India's emerging beverage corridors under PLI scheme incentives.
Manufacturers anchor technology adoption. OEMs concentrate expansion demand.
Technology:
Servo-electric architectures displace hydraulic systems fastest in high-cavitation beverage lines, while hybrid configurations retain relevance in automotive applications requiring extreme clamp force with moderate precision.
- Automatic:Fully electric stretch blow lines with predictive maintenance subscriptions displace break-fix contracts in high-volume PET corridors where unplanned downtime costs exceed preventive service premiums.
- Hybrid:Electric clamp actuation paired with hydraulic extrusion serves automotive fuel tank production where 600+ ton forces combine with energy recovery requirements.
- Semi-Automatic:Intermediate automation tiers sustain relevance in emerging market converter bases with technician shortages and extended commissioning acceptance periods.
- Manual:Low-volume specialty packaging and prototype development retain limited demand for operator-controlled parison programming.
Automatic systems dominate new order intake. Hybrid architectures gain share fastest in automotive fuel tank replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters in China and Germany absorb premium pricing for electric servo architectures with minimal elasticity, while mid-tier packaging operations in India and Mexico prioritize upfront capital efficiency over lifecycle operating cost optimization.
United States
Tier-one beverage bottlers demand simulation-validated cycle time guarantees and embedded IoT diagnostics before final payment release. FDA validation requirements for food-contact steel grades elevate tooling qualification expenses. Michigan and Ohio automotive clusters drive accumulator-head system demand for HDPE fuel tank production facing NHTSA emissions compliance.
Germany
Bottling line automation rates exceeding 90% force continuous lightweighting investments across PET packaging corridors. REACH substance restrictions on polymer additives compel HDPE compound reformulation for automotive fuel tank manufacturers. Bavarian precision mold machining capacity creates delivery bottlenecks during demand surges.
China
Provincial energy intensity targets under dual carbon goals favor servo-electric machine procurement in domestic converter tenders. SAMR technical regulations enforce energy efficiency thresholds that accelerate technology substitution. Yangtze River Delta packaging hubs concentrate stretch blow molding demand for carbonated beverage exports.
India
Production-linked incentives for capital goods manufacturing attract greenfield assembly investments serving South Asian beverage markets. BIS certification requirements shape equipment import compliance costs for European and Asian suppliers. Maharashtra and Gujarat industrial corridors absorb mid-volume converter demand through regional machinery dealer networks.
Japan
Precision mold refurbishment capabilities extend machine lifecycles in Asian packaging hubs facing technician shortages. METI energy efficiency standards favor hybrid architectures in automotive fuel tank replacement cycles. Kansai manufacturing clusters sustain demand for pharmaceutical-grade injection blow molding systems with flash-free neck finishes.
Plastic Blow Molding Machine Market Competitive Landscape
Capability concentration sits with German and Japanese precision fabricators; scale advantage sits with diversified packaging machinery conglomerates serving global beverage corridors. The market structures around three tiers: integrated line suppliers bundling blow molding with filling and labeling, standalone machine specialists competing on mold changeover velocity, and regional assemblers capturing price-sensitive emerging market demand. Dominant competitive moves include strategic partnerships between equipment builders and resin suppliers for rPET process validation, plus geographic expansion through local assembly licensing to circumvent import duty exposure.
Within the integrated line supplier tier, Krones AG and Sidel Group occupy positions anchoring long-term service agreements across high-volume bottling corridors. Among precision mold specialists, Nissei ASB Machine Co., Ltd. exemplifies the Asian fabrication archetype focused on lifecycle extension capabilities. German GmbH-structured fabricators including Kautex Maschinenfabriken GmbH and Bekum Maschinenfabriken GmbH represent the European engineering-intensive segment serving automotive and industrial hollow part demand.
| Leading Market Players |
|---|
| Krones AG |
| Sidel Group |
| Nissei ASB Machine Co., Ltd. |
| Kautex Maschinenbau GmbH |
| Bekum Maschinenfabriken GmbH |
| Uniloy |
| Jomar Corporation |
| Sumitomo Heavy Industries, Ltd. |
| SIPA S.p.A. |
| Others |
Value Network & Pricing Analysis
Single-source dependency on German and Japanese precision cavity machining capacity concentrates pricing power among tier-one fabricators while compressing margins for regional assemblers facing extended delivery timelines during demand surges. This bottleneck determines both the premium commanded by European engineering-intensive suppliers and the supply chain shape favoring captive mold refurbishment programs over spot procurement.
Pricing Analysis
After-sales service subscriptions now drive lifetime value more than initial equipment sales, with predictive maintenance and remote monitoring modules unbundling from traditional break-fix contracts. Three-tier pricing structure across premium, standard, and economy levels separates simulation-validated stretch blow lines from semi-automatic platforms serving emerging markets. Pricing pressure stems from converter margin compression under lightweighting specifications, while tier-one beverage bottlers in Germany and the United States exhibit minimal price sensitivity for electric servo architectures with embedded IoT diagnostics.
Supply Chain Analysis
Tariff exposure between China and Western markets dominates supply chain risk calculus for equipment builders configuring regional assembly footprints. Precision mold fabrication concentrates in Germany and Japan, while servo-electric drive components draw from Chinese and South Korean supplier bases. Raw material dependencies span certified steel grades for FDA-compliant food-contact surfaces, high-performance aluminum alloys for mold cavities, and rare-earth magnets for electric servo motors. Distribution runs through integrated line suppliers bundling blow molding with filling and labeling, plus standalone machine specialists competing on mold changeover velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
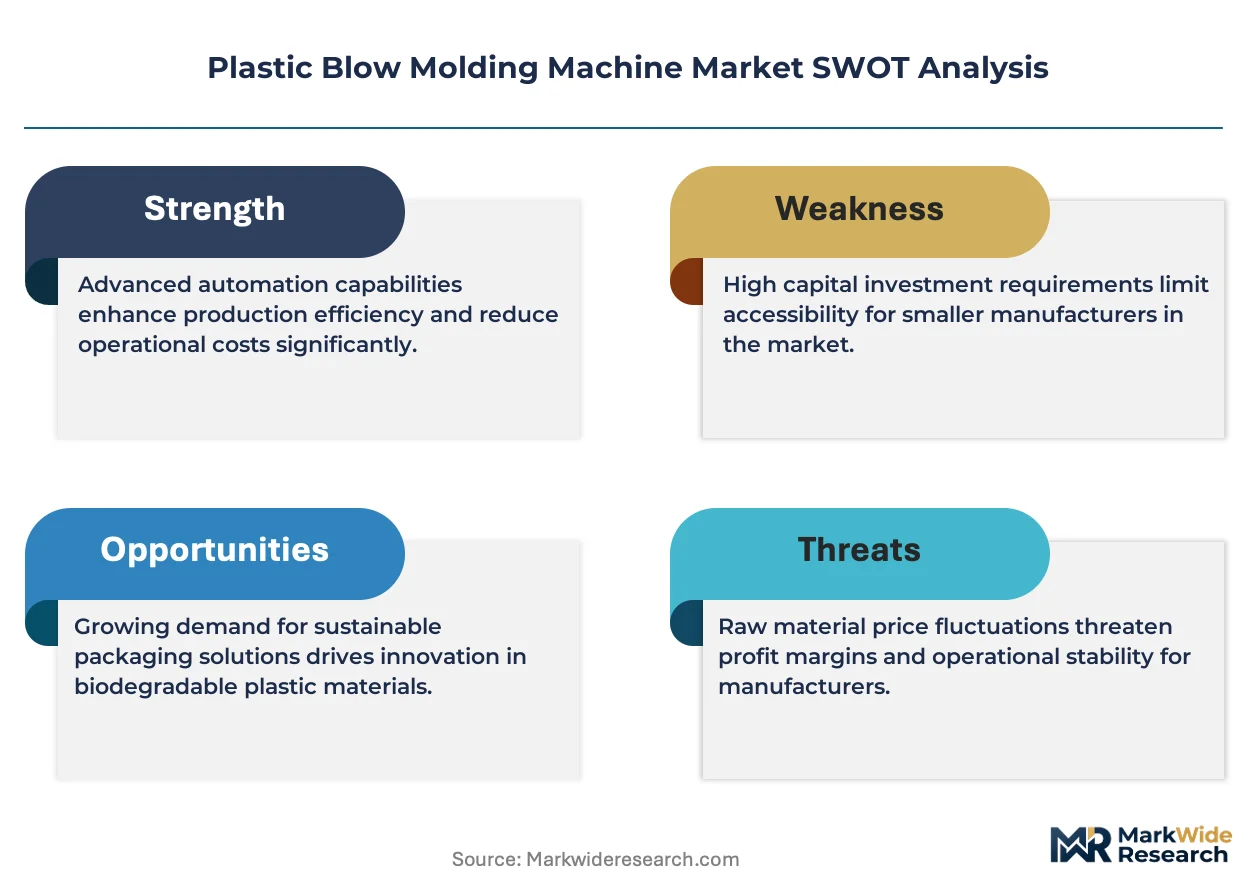
This market operates as a defensive-moat story anchored in regulatory entrenchment: CE marking and FDA validation dossiers create switching costs that lock converters into established supplier relationships across multi-year depreciation cycles.
For Market Incumbents: Build switching-cost moats through embedded IoT diagnostics that raise replacement friction. Deepen vertical integration into precision mold refurbishment capabilities to capture lifecycle extension revenue. Defend against emerging Asian assemblers by accelerating virtual commissioning software deployment that virtualizes factory acceptance testing risk.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized packaging machinery corridors where production-linked incentives reduce capital barriers. Target mid-volume converters in Maharashtra and Gujarat industrial belts underserved by integrated line suppliers. Pursue local assembly licensing to circumvent import duty exposure while building BIS certification competence.
For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors precision fabrication specialists over diversified conglomerates. Long-term viability hinges on servo-electric architecture mastery and predictive maintenance platform scale. Watch for inflection signals in rPET feedstock consistency breakthroughs that stabilize process windows in high-speed stretch blow lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Mold Fabrication | Captures delivery bottleneck premiums and extends machine lifecycle revenue in Asian packaging hubs. |
| Remote Monitoring Platform Deployment | Enables subscription revenue models displacing break-fix contracts in high-volume PET bottling corridors. |
| Virtual Commissioning Software Investment | Compresses dispute resolution timelines and accelerates production ramp schedules for tier-one converters. |
| Local Assembly Licensing in India | Circumvents BIS certification costs and import duty exposure in PLI-subsidized South Asian markets. |
| rPET Process Validation Partnerships | Stabilizes process windows against feedstock viscosity variation in circular packaging mandates. |
Research Methodology
The analysis maps stretch blow molding, injection blow molding, extrusion blow molding, and multi-layer co-injection architectures, each validated through maintenance directors at beverage bottlers, plant engineers at automotive fuel tank manufacturers, aftermarket service heads at packaging converters, and procurement teams at pharmaceutical packaging specialists. Primary interview insights triangulate against customs and trade data, SEC filings from diversified machinery conglomerates, SAMR technical regulation disclosures, and EU F-Gas Regulation implementation documents. Bottom-up equipment shipment tracking reconciles with top-down packaging machinery market sizing across the projection horizon.
Forecast assumptions hold fixed the phase-down trajectory of fluorinated greenhouse gases under EU F-Gas Regulation and China's provincial energy intensity targets under dual carbon goals, while varying rPET feedstock adoption rates and servo-electric technology substitution pace. Segmentation dimensions span machine architecture, end-use vertical, automation tier, and regional regulatory cluster. CAGRs derive from installed base turnover analysis and replacement cycle compression in lightweighting-driven beverage corridors. Industry-specific inputs include blow molding line automation rates and mold changeover velocity benchmarks.
Stress conditions across rPET feedstock viscosity variance, servo commissioning technician availability, and REACH substance restriction expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and converter capital deployment cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Corrugated Box Making Machine Market
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Cartridge Filling System Market
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Sanitizer Filling Machine Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Paper Napkin Converting Lines Market
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
EPS Pre-Expander Machines Market