
 Box Filling Machine Market | 2026-2036
Box Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Box Filling Machine Market Outlook
Germany is tilting toward advanced packaging automation as manufacturers expand capacity to serve European export demand. Bosch Packaging leverages its engineering base in the country to sustain leadership in high-speed filling systems for pharmaceuticals. Krones AG anchors beverage sector demand with specialized carton and bottle handling integration. GEA Group competes through dairy and food processing expertise, extending its reach into aseptic box filling applications.
A box filling machine is an automated or semi-automated industrial device designed to deposit measured quantities of product into corrugated, folding carton, or rigid containers at speeds ranging from 10 to 600 units per minute. These systems employ programmable logic controllers, servo-driven indexing, and vision-guided robotic pick-and-place modules to ensure dimensional accuracy, weight consistency, and seal integrity across batch runs. Fully automatic systems lead installed base value due to labor substitution economics in high-volume food and beverage plants, while robotic configurations represent the fastest-expanding technology segment as e-commerce warehouses adopt adaptive handling for variable box sizes. Pneumatic technology retains cost-sensitive share in emerging manufacturing economies, though electric actuation is displacing compressed-air systems where energy efficiency and precision control command priority.
EU machinery safety directives and CE marking requirements shape product design standards for equipment sold across member states, while FDA regulations in the United States govern sanitary construction and material contact surfaces for pharmaceutical and food-grade box fillers. China's SAMR enforces GB standards for electrical safety and electromagnetic compatibility on imported packaging machinery. Stakeholders must monitor diverging energy efficiency mandates and traceability requirements as these regulatory frameworks tighten compliance thresholds for cross-border equipment sales.
Market Dynamics
Electric actuation is displacing pneumatic systems across high-volume food and beverage plants, driven by EU energy efficiency mandates and compressed-air cost volatility. This technology rotation compresses operating expenditure while demanding upfront capital reconfiguration from incumbent installed bases.
Growth Catalysts
- EU Green Deal packaging waste rules:German food producers are expanding automated lines to meet circular economy compliance deadlines, creating immediate equipment replacement cycles.
- Robotic pick-and-place modules:E-commerce fulfillment centers in China are integrating vision-guided systems to handle variable parcel dimensions at throughput rates exceeding 400 units per minute.
- Aseptic dairy processing:Extended shelf-life milk and plant-based beverage categories are requiring sterile box filling infrastructure that eliminates post-packaging contamination risk.
Market Restraints
- Servo motor and drive cost volatility:Rare earth magnet supply concentration in China creates input price instability for precision motion control components.
- CE marking complexity:EU machinery safety directives impose extended certification timelines that delay revenue recognition for non-European equipment suppliers.
- Used equipment arbitrage:Secondary market availability of refurbished pneumatic systems competes against new electric actuation sales in cost-sensitive emerging manufacturing economies.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO quality mandates and FSSAI traceability requirements are accelerating demand for validated box filling systems in bulk drug and formulation facilities.
- Cell-cultured protein handling:Aseptic filling protocols developed for dairy are transferring to alternative protein production, opening new end-use verticals for incumbent suppliers.
- Retrofit electric conversion kits:Modular actuator replacement packages allow pneumatic system owners to upgrade installed bases without full line replacement, capturing stranded asset value.
Industry Challenges
- PLC programming and servo tuning expertise:Food and beverage plants face acute shortages of automation engineers capable of integrating multi-axis robotic modules with legacy line control architectures.
- FDA 21 CFR Part 11 validation:Pharmaceutical box filling deployments require extensive documentation and qualification protocols that extend project timelines and inflate commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Box Filling Machine Market |
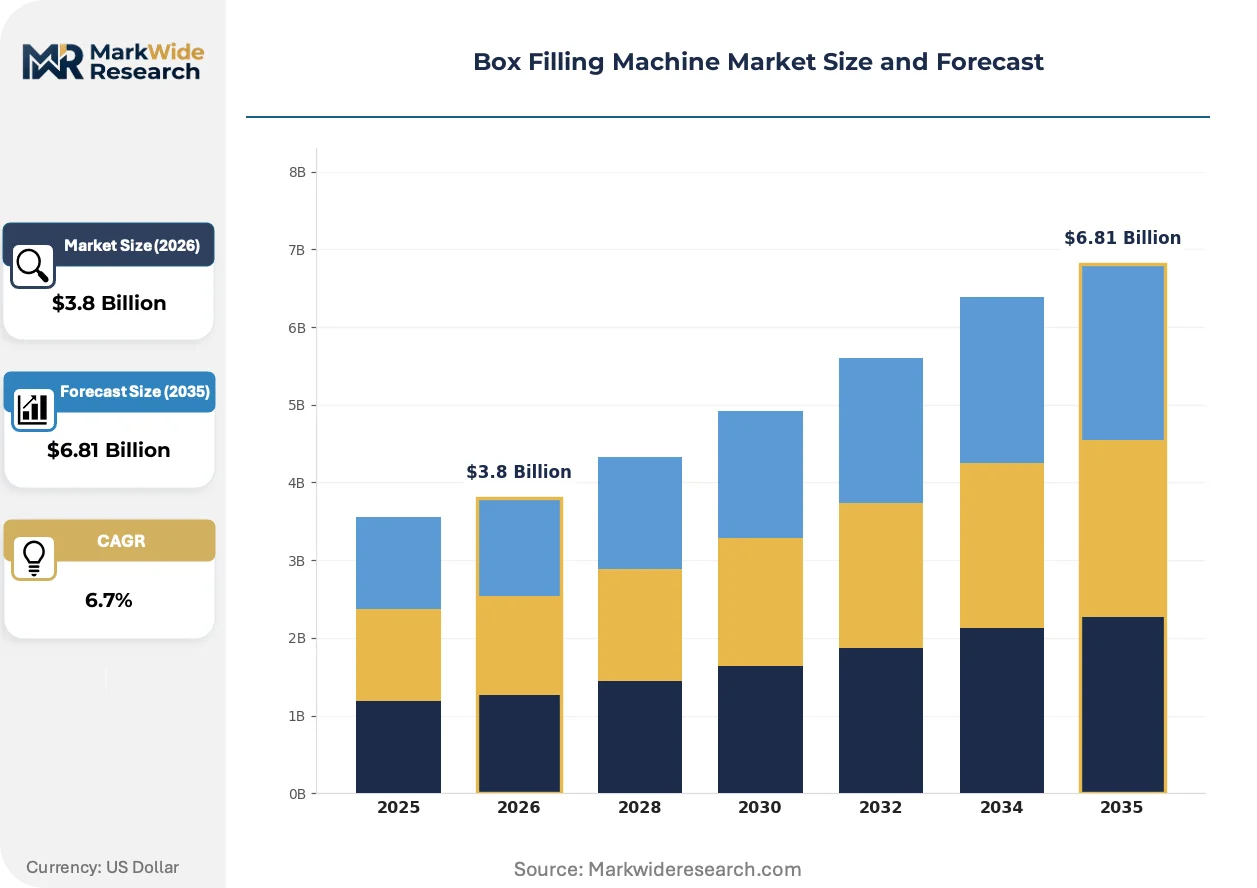
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Fully Automatic, Robotic End User: Food & Beverage, Pharmaceuticals, Consumer Goods, E-Commerce Technology: Pneumatic, Electric, Mechanical, Hybrid Capacity: Low, Medium, High, Custom |
| Companies Covered | Ishida Co., Ltd., Tetra Pak, Bosch Packaging, IMA Group, Viking Masek, Krones AG, GEA Group, ProMach LLC, All-Fill Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Box Filling Machine Market Strategic Shifts
Adaptive handling architectures are redefining equipment specifications as single-SKU production runs give way to high-mix, low-volume fulfillment patterns. This shift compresses mechanical changeover windows while elevating software control sophistication.
Collaborative robotic arms with force-torque sensing are migrating from automotive assembly into food-grade box filling cells. Mid-sized contract packagers in the Netherlands and Denmark are deploying these systems for mixed-case palletizing. The technology is migrating from fixed-gantry configurations toward mobile platforms that reconfigure warehouse layouts without structural modification.
China's GB standards for electromagnetic compatibility are tightening test thresholds for imported packaging machinery, effective across all customs districts. This elevates shielding and filtering costs for European and Japanese equipment suppliers. Pharmaceutical exporters to China are responding by pre-certifying designs through SAMR-recognized testing laboratories in Shanghai and Tianjin.
Equipment-as-a-service contracting is displacing traditional capital purchase models among third-party logistics operators. Monthly fee structures bundle maintenance, software updates, and throughput guarantees. This pattern is most visible in German and US e-commerce fulfillment networks where balance sheet flexibility outweighs ownership preference.
Box Filling Machine Market Segmentation
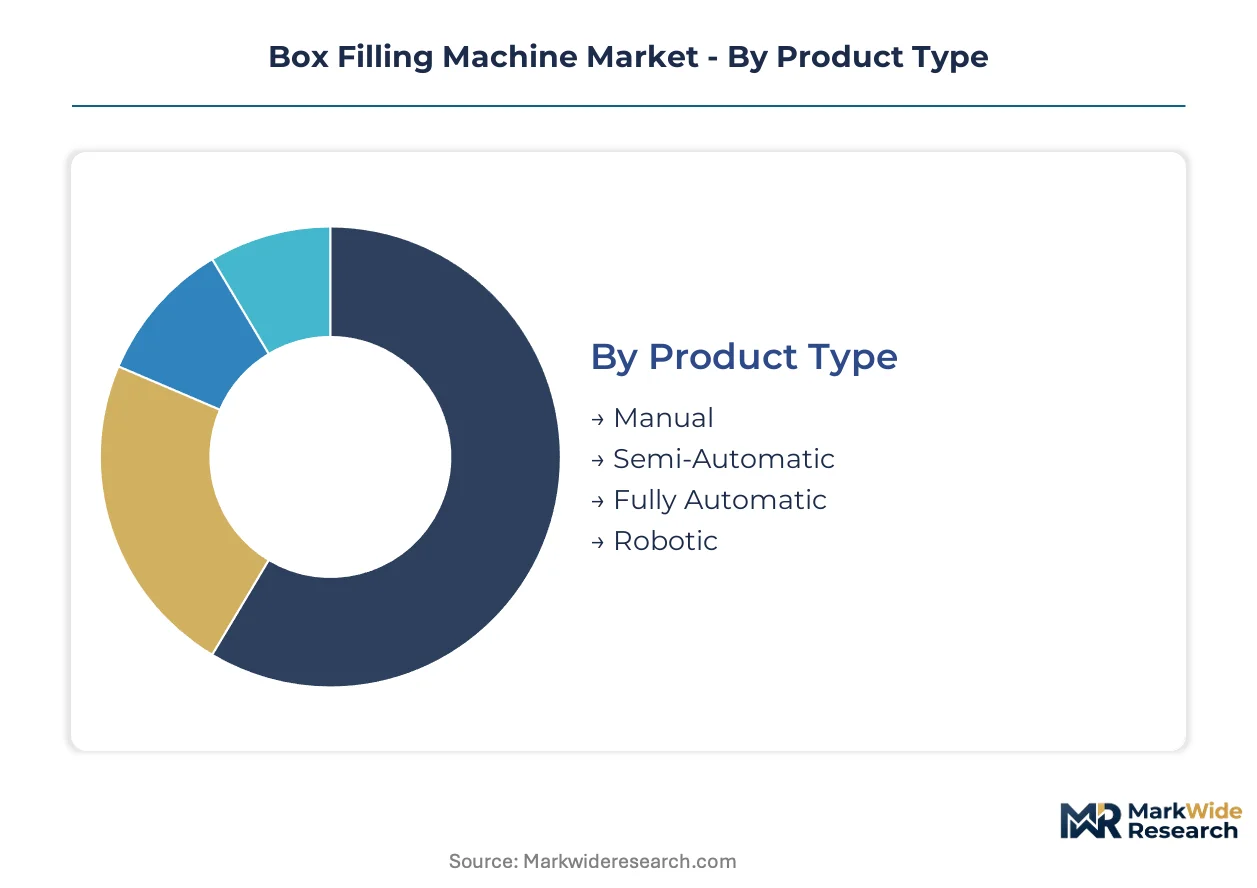
Box filling machine procurement patterns diverge sharply across operational scales and regulatory exposure. Food and beverage plants prioritize throughput velocity while pharmaceutical facilities emphasize validation documentation and aseptic construction.
Product Type:
Automation intensity determines capital deployment, labor substitution economics, and integration complexity for production line architects.
- Manual:Hand-fed systems with operator-controlled product placement suit micro-batch artisan food producers and pilot-scale pharmaceutical facilities. Demand clusters in India's specialty food sector where FSSAI traceability mandates still permit limited automation for small-batch traditional products.
- Semi-Automatic:Operator-assisted machines with automated indexing and filling cycles bridge cost-sensitive emerging manufacturing economies. These units dominate Vietnam's contract packaging sector where garment-to-packaging industrial diversification requires intermediate automation without full PLC infrastructure.
- Fully Automatic:PLC-controlled systems with servo-driven indexing achieve 200-600 units per minute with minimal operator intervention. German dairy processors deploy these for aseptic carton filling under EU Green Deal packaging waste compliance deadlines.
- Robotic:Vision-guided pick-and-place modules with adaptive gripping handle variable box dimensions without mechanical changeover. E-commerce fulfillment centers in China's Yangtze River Delta integrate these for parcel volumes exceeding 400 units per minute.
Fully automatic systems command the established base. The steepest expansion runs through robotic configurations.
End User:
Regulatory stringency and contamination risk tolerance shape equipment specification priorities across vertical applications.
- Food & Beverage:Sanitary stainless steel construction with CIP/SIP capability handles dairy, beverages, and prepared foods. EU energy efficiency mandates accelerate electric actuation adoption in German beverage bottling plants.
- Pharmaceuticals:FDA 21 CFR Part 11 validation documentation, isolator integration, and sterile filling protocols govern equipment selection. CDSCO quality mandates in India drive validated system demand for bulk drug and formulation facilities.
- Consumer Goods:Flexible handling accommodates cosmetics, personal care, and household products with frequent SKU rotation. Dutch contract packagers deploy collaborative robotic cells for mixed-case palletizing of premium beauty products.
- E-Commerce:Adaptive dimension handling and throughput velocity dominate specification criteria over precision dosing. US third-party logistics operators favor equipment-as-a-service contracting for balance sheet flexibility.
Food and beverage commands the established base. The steepest expansion runs through e-commerce.
Technology:
Actuation methodology determines energy consumption profiles, precision control capabilities, and maintenance intervals.
- Pneumatic:Compressed-air cylinders and valves deliver cost-effective linear motion for low-complexity filling cycles. Secondary market refurbishment extends equipment life in Indonesia's emerging manufacturing corridor where capital constraints outweigh efficiency priorities.
- Electric:Servo motors with rare-earth magnets enable programmable motion profiles and regenerative braking. EU F-Gas Regulation and energy efficiency directives accelerate displacement of pneumatic systems in high-volume European plants.
- Mechanical:Cam-driven linkages and gear trains provide deterministic motion without electronic control complexity. These systems persist in legacy confectionery packaging lines where product characteristics remain stable across decades.
- Hybrid:Combined pneumatic-electric architectures optimize cost-performance for mid-speed applications with intermittent precision requirements. Brazilian food processors adopt these for regional snack packaging where full electric conversion remains capital-prohibitive.
Electric actuation commands the established base. The steepest expansion runs through hybrid configurations.
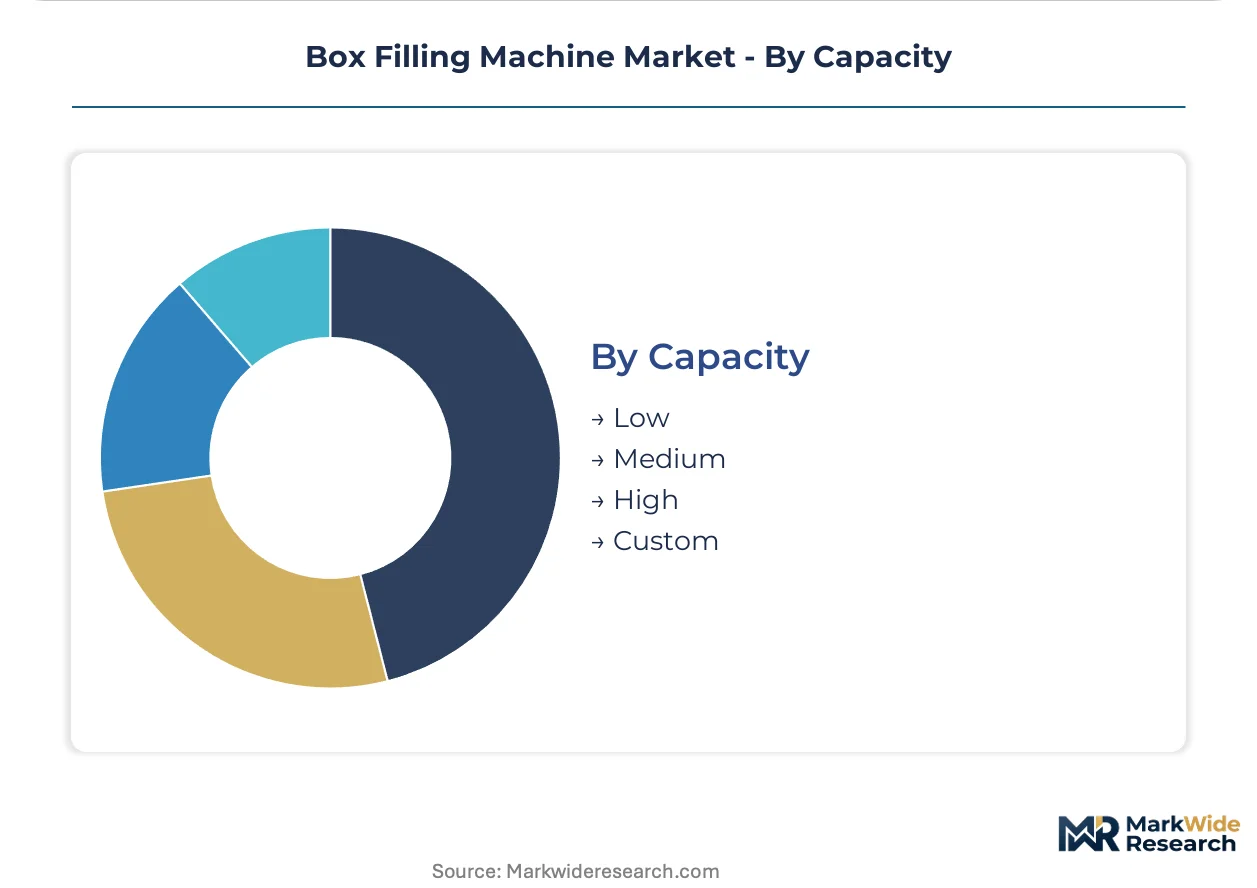
Capacity:
Throughput tier selection reflects production volume requirements, SKU diversity, and facility footprint constraints.
- Low:Systems operating below 50 units per minute serve pilot plants, seasonal production, and ultra-premium positioning. Japan's craft sake producers specify these for limited-edition releases where manual quality inspection remains integral.
- Medium:50-200 units per minute accommodates regional distribution and multi-SKU contract manufacturing. South Korea's cosmetics OEM sector clusters procurement here for flexible response to K-beauty trend cycles.
- High:Exceeding 200 units per minute with continuous motion mechanics and minimal dwell time. Saudi Arabia's dairy processors under SFDA oversight deploy these for UHT milk aseptic filling at desert-adjacent production parks.
- Custom:Engineered-to-order systems for oversized containers, hazardous materials, or extreme environmental conditions. UAE pharmaceutical free zones commission these for temperature-sensitive biologic packaging under MOHAP cold chain mandates.
Medium capacity commands the established base. The steepest expansion runs through high-capacity systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters concentrate in Germany, China, and the United States, with assembly and integration capabilities dispersing toward demand centers in India and Southeast Asia. Regulatory divergence across FDA, EU machinery safety directives, and China's SAMR GB standards shapes cross-border equipment certification strategies.
United States
FDA 21 CFR Part 11 validation requirements drive pharmaceutical box filling procurement in New Jersey and Massachusetts biotech corridors. EPA energy efficiency guidelines influence electric actuation adoption in Midwest dairy processing plants. Chicago-area contract packagers deploy high-speed systems for e-commerce fulfillment networks serving domestic distribution.
Germany
EU Green Deal packaging waste rules accelerate automated line expansion across Bavarian and North Rhine-Westphalian food processing hubs. CE marking requirements under machinery safety directives extend certification timelines for imported components. Stuttgart-area engineering clusters specialize in servo-driven indexing systems for aseptic dairy applications.
China
SAMR GB standards for electromagnetic compatibility tighten shielding requirements on imported packaging machinery entering Yangtze River Delta ports. E-commerce fulfillment demand concentrates in Shanghai and Suzhou logistics parks where robotic pick-and-place systems exceed 400 units per minute. MIIT industrial upgrading programs subsidize electric actuation retrofits in provincial food processing zones.
India
CDSCO quality mandates and FSSAI traceability requirements accelerate validated box filling demand in Maharashtra and Gujarat pharmaceutical clusters. BIS electrical safety standards govern imported machinery acceptance at Mumbai and Ahmedabad customs points. Bangalore-area contract manufacturers adopt semi-automatic systems for regional snack packaging diversification.
Japan
METI energy efficiency directives displace pneumatic systems in Kanto region beverage bottling plants. PMDA pharmaceutical manufacturing standards require isolator-integrated filling protocols for Tokyo-Osaka biologic production networks. Nagoya-area machinery builders specialize in compact electric actuation for limited-footprint urban food processing facilities.
Box Filling Machine Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying servo drives, vision systems, and robotic end-effectors. The vendor base organizes around three archetypes: diversified packaging conglomerates with cross-sector filling portfolios, pure-play automation houses focused on robotic adaptive handling, and regional fabricators serving cost-sensitive emerging manufacturing economies. Competitive moves concentrate on M&A for software control capabilities and strategic partnerships between European machinery builders and Chinese system integrators for local certification support.
Among diversified packaging conglomerates, Tetra Pak and Krones AG exemplify the integrated system-provider archetype with beverage-sector specialization depth. Bosch Packaging occupies a position bridging pharmaceutical validation expertise with food-grade sanitary construction standards. These three anchors represent contrasting geographic origins and structural forms—Swiss-Swedish cooperative, German Aktiengesellschaft, and German GmbH engineering heritage—while collectively illustrating the tier-one competitive dynamic of specification-engineered solutions versus configurable platform sales.
| Leading Market Players |
|---|
| Ishida Co., Ltd. |
| Tetra Pak |
| Bosch Packaging |
| IMA Group |
| Viking Masek |
| Krones AG |
| GEA Group |
| ProMach LLC |
| All-Fill Inc. |
| Others |
Value Chain & Pricing Dynamics
Rare earth magnet supply concentration in China compresses servo motor availability and forces tiered equipment pricing that separates pharmaceutical-validated systems from standard food-grade configurations. This input chokepoint simultaneously widens price spreads between electric and pneumatic actuation technologies and reshapes procurement geography toward dual-source component strategies.
Pricing Analysis
EU machinery safety directives and CE marking requirements dictate the pricing tier structure across European equipment sales, separating isolator-integrated pharmaceutical systems from standard food-grade sanitary construction. Three-tier pricing structure across premium, standard, and economy levels reflects validation documentation depth, with FDA 21 CFR Part 11 compliance adding substantial documentation costs to pharmaceutical tiers. Pricing pressure stems from used equipment arbitrage in Southeast Asian emerging manufacturing economies where refurbished pneumatic systems compete against new electric sales. Contract packagers in Vietnam and Indonesia exhibit highest price sensitivity, while German dairy processors under EU Green Deal deadlines show lowest sensitivity to capital outlay for energy-efficient electric retrofits.
Supply Chain Analysis
Export control restrictions on precision motion control components limit servo drive and rare earth magnet flows from China to European and Japanese equipment builders. Component manufacturing concentrates in China, Germany, and Japan, with final assembly dispersing toward demand centers in India and Southeast Asia. Supply chains draw from rare earth processing facilities, servo motor winding operations, and stainless steel sanitary fabrication. Single-source vulnerability runs through Chinese neodymium magnet supply, which feeds precision motion systems. Distribution runs through OEM direct sales for large pharmaceutical accounts and regional machinery distributors for mid-tier food and beverage plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acute shortages of PLC programming and servo tuning engineers constrain deployment velocity for robotic box filling integrations, creating a bottleneck that separates equipment suppliers with captive automation expertise from component assemblers dependent on external system integrators.
For Market Incumbents: Insulate market position by deepening backward integration into servo drive and vision system development, reducing exposure to Chinese rare earth price volatility. Acquire specialized software control capabilities to differentiate from pneumatic-era competitors facing stranded asset risk. Expand certification support infrastructure in Shanghai and Tianjin to preempt SAMR electromagnetic compatibility enforcement tightening on imported machinery. For New Entrants and Emerging Players: Mid-market semi-automatic systems for India's pharmaceutical contract packaging sector represent the most penetrable entry point, where CDSCO quality mandates accelerate validated equipment demand without requiring full robotic integration complexity. Target Brazilian food processors seeking hybrid pneumatic-electric architectures as a beachhead for regional snack packaging diversification. Pursue equipment-as-a-service contracting models to bypass capital purchase barriers among US third-party logistics operators prioritizing balance sheet flexibility. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors electric actuation specialists with established pharmaceutical validation credentials over legacy pneumatic incumbents. Long-term viability over the next decade hinges on software control differentiation and regional certification capabilities rather than mechanical fabrication scale. Acquisition targets should demonstrate proven FDA 21 CFR Part 11 documentation protocols and SAMR pre-certification relationships. The signal to watch is MIIT subsidy disbursement velocity for provincial electric retrofit programs, which would accelerate displacement timelines and compress pneumatic equipment residual values.| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Electric Conversion Kit Development | Captures stranded pneumatic asset value in German dairy plants facing EU F-Gas Regulation compliance deadlines. |
| SAMR Pre-Certification Laboratory Partnership | Accelerates customs clearance for European equipment entering Yangtze River Delta e-commerce fulfillment parks. |
| Equipment-as-a-Service Platform Launch | Addresses balance sheet flexibility priorities among US third-party logistics operators in Chicago-area fulfillment networks. |
| Collaborative Robotic Cell Integration | Targets Dutch and Danish contract packagers deploying mixed-case palletizing for premium beauty product lines. |
| Aseptic Dairy Protocol Transfer | Opens cell-cultured protein verticals by adapting sterile filling infrastructure from extended shelf-life milk applications. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of trade association filings, customs machinery import records, and regulatory certification databases. Interviews with plant engineers at dairy and beverage processors, OEM procurement teams, aftermarket service heads, and automation system integrators provided operational deployment perspectives. Secondary validation drew from EU machinery safety directive implementation reports, FDA 510(k) and 21 CFR Part 11 guidance documents, SAMR GB standard enforcement notices, and MIIT industrial upgrading program disclosures. Bottom-up equipment shipment analysis triangulated against top-down production capacity estimates across German, Chinese, and US manufacturing clusters.
Forecast inputs span automation intensity tier, actuation technology type, end-use vertical regulatory exposure, and regional certification complexity across the projection horizon. Segmentation modeling incorporated product type, capacity tier, technology architecture, and end-user contamination risk tolerance. CAGRs derived from regression analysis of historical equipment replacement cycles, regulatory compliance deadline clustering, and e-commerce fulfillment volume trajectories. Industry-specific inputs included EU Green Deal packaging waste rule implementation timelines and rare earth magnet price volatility indices.
Macroeconomic conditions sit as an overlay; deviation in capital equipment investment cycles, cross-border tariff regimes, or commodity input costs would shift the trajectory. Forecasts embed assumptions regarding regulatory enforcement consistency and technology substitution elasticity. Material shifts in Chinese export control enforcement on precision motion components or sudden acceleration of EU energy efficiency mandate timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Thermal Film Laminating Machines Market
Packaging Machinery
Multi-Head Filling Machines Market
Packaging Machinery
Bagging Machine Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Slitter Rewinder Machines Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
North America Printing Machinery Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Packaging Machinery Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Pre-Made Pouch Packaging Machines Market
Packaging Machinery
Tray Forming Machine Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Powder Packing Machine Market