
 Vertical Bagging Machine Market | 2026-2036
Vertical Bagging Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Bagging Machine Market Insights
REACH compliance is pivoting the cost-of-entry calculus for European equipment buyers, forcing redesigns of pneumatic sealing systems to eliminate restricted substances. Syntegon Technology leverages its vertical integration into servo-electric drives to sustain margin advantage across pharmaceutical lines. Viking Masek anchors its competitive position through specialized hygienic designs that dominate Nordic dairy packaging applications. Bosch Packaging Technology competes on manufacturing scale, operating multiple assembly plants that control lead times for high-volume food clients.
A vertical bagging machine forms, fills, and seals pre-made or formable bags in an upright orientation, typically handling film widths from 100 mm to 600 mm at speeds reaching 120 cycles per minute depending on product density and bag geometry. Its primary industrial purpose centers on automating the final packaging stage for free-flowing powders, granules, and small solid items across food, pharmaceutical, and chemical processing plants. Automatic product types command the dominant share of value as labor cost differentials widen between European and Southeast Asian manufacturing bases, while hybrid pneumatic-electric technology represents the fastest-growing configuration as processors seek to retrofit existing compressed air infrastructure with precision servo controls. Manual and semi-automatic segments remain entrenched in artisan food and small-batch cosmetic applications where changeover flexibility outweighs throughput economics.
FDA's 21 CFR Part 11 electronic records requirements shape pharmaceutical demand by mandating audit-trail capabilities in all packaging equipment software, while EMA's Annex 1 revision on sterile manufacturing pushes upgrade cycles for bagging lines in European drug facilities. Japan's PMDA enforces Good Manufacturing Practice inspections that extend to packaging machinery validation, creating compliance barriers for non-JIS-certified imports. Stakeholders must monitor how China's NMPA alignment with PIC/S standards reshapes qualification protocols for equipment destined for Asia-Pacific pharmaceutical markets.
Market Dynamics
Pharmaceutical serialization mandates under FDA's Drug Supply Chain Security Act and the EU Falsified Medicines Directive are forcing packaging line overhauls, accelerating replacement of legacy pneumatic baggers with servo-electric systems that deliver the precision and data capture required for unit-level traceability.
Growth Catalysts
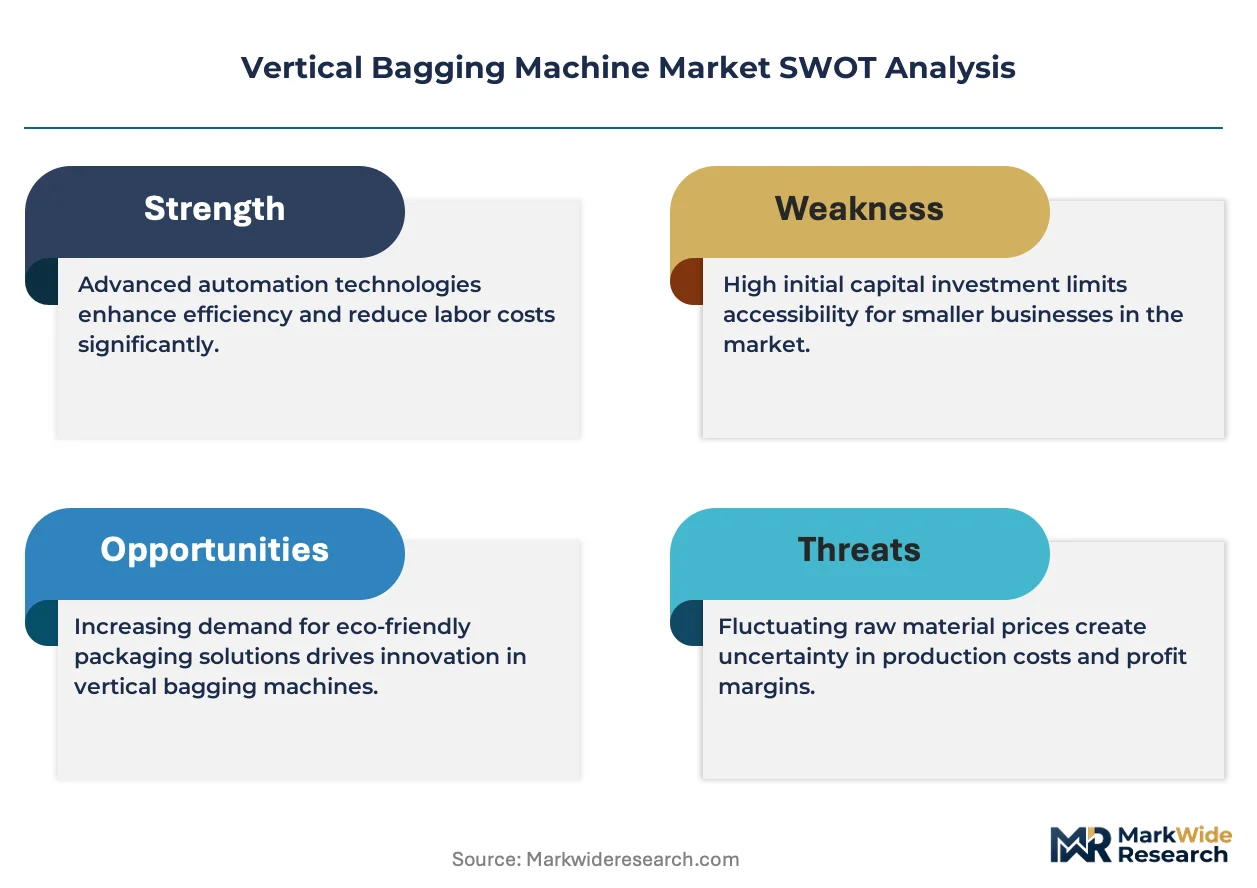
- REACH substance restrictions:ECHA's tightening limits on phthalates in pneumatic seals are compelling European processors to upgrade to servo-electric actuation, creating replacement demand across dairy and pharmaceutical installations.
- Contract manufacturing expansion:Pharmaceutical CDMOs in Germany, the United States, and Japan are scaling automated packaging capacity to secure multi-product facility certifications, concentrating orders for validated bagging systems.
- Servo-electric precision:Closed-loop motion control is displacing pneumatic positioning in high-value pharmaceutical applications where seal integrity directly impacts product stability and regulatory acceptance.
Market Restraints
- Stainless steel input volatility:Grade 316L sheet and tubular component costs fluctuate with nickel pricing, compressing margins for hygienic machine builders serving dairy and pharmaceutical sectors.
- Controller supply concentration:Servo drive and PLC sourcing concentrates among German and Japanese automation suppliers, exposing lead time risks for bagger OEMs outside these supply clusters.
- Compressed air infrastructure lock-in:Food plants with extensive legacy pneumatic networks face high retrofit capital burdens when evaluating full servo-electric conversion, slowing upgrade cycles.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's alignment with PIC/S standards and the PLI scheme for active pharmaceutical ingredients are driving packaging equipment qualification demand among domestic and multinational drug producers.
- Biologics containment integration:Convergence between vertical bagging and isolator technology creates white space for systems that combine aseptic filling with single-use bag containment for cell therapy products.
- Secondary packaging automation:E-commerce fulfillment requirements for case-ready pharmaceutical and nutritional products are opening demand for bagging-to-cartoning integrated lines that reduce manual handling.
Industry Challenges
- Servo commissioning expertise:Shortage of technicians qualified in motion control tuning and safety integration is extending installation timelines and inflating service costs for pharmaceutical validation projects.
- 21 CFR Part 11 software validation:Documentation burden for electronic records compliance in FDA-regulated facilities stretches procurement cycles and requires specialized vendor support capabilities.
- Legacy MES integration:Connecting new servo-electric baggers to existing manufacturing execution systems in established pharmaceutical plants demands costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Bagging Machine Market |
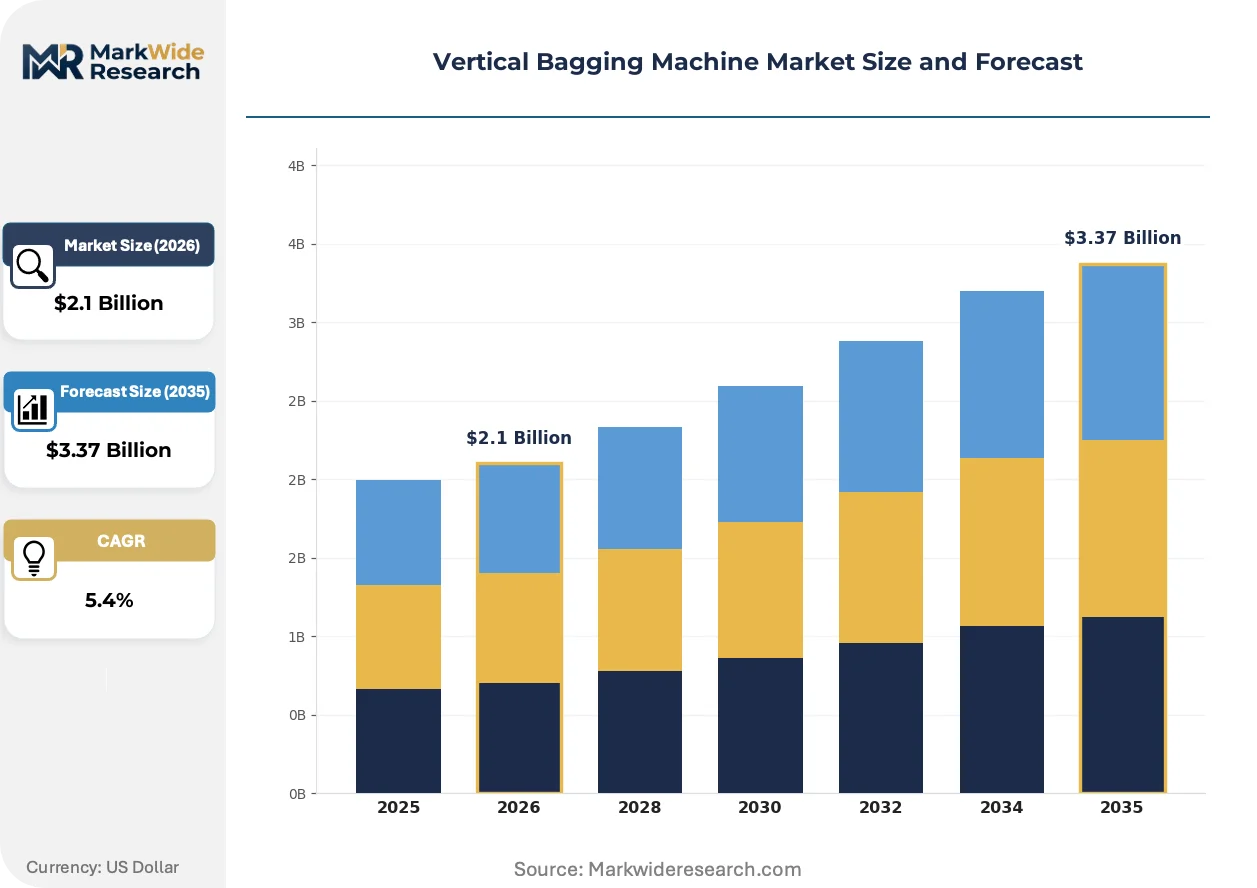
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Customized Application: Food Packaging, Pharmaceuticals, Cosmetics, Chemicals End User: Retail, Wholesale, Manufacturing, Distribution Technology: Pneumatic, Electric, Hybrid, Others |
| Companies Covered | Syntegon Technology, IMA Group, Viking Masek, Triangle Package Machinery, FUJI Machinery, Barry-Wehmiller, Hayssen Flexible Systems, Bosch Packaging Technology, Concetti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Bagging Machine Market Trends and Innovations
Servo-electric actuation is displacing pneumatic systems as the dominant technology platform, while regulatory data integrity requirements and shifting procurement models are restructuring how packaging equipment is specified, validated, and maintained across pharmaceutical and food processing operations.
Brushless servo motors with integrated safety encoders are expanding into high-speed pharmaceutical bagging applications where precise jaw positioning ensures seal strength consistency across temperature-sensitive biologic products. German and Japanese drug manufacturers are adopting these systems fastest, driven by METI and KBA machinery safety enforcement. The technology is expanding into mid-speed food applications as dairy processors seek to reduce compressed air energy consumption while maintaining hygienic design ratings.
EMA's Annex 1 revision on sterile manufacturing is mandating barrier isolation and continuous monitoring for packaging lines handling parenteral products, forcing bagger redesigns to accommodate glove ports and environmental sensors. This regulatory pressure is compressing the viable supplier base to firms with documented aseptic integration experience. European pharmaceutical facilities are responding with accelerated replacement timelines for open-frame equipment installed before the 2022 revision.
Pharmaceutical procurement departments are unbundling equipment purchase from validation support, creating separate contracting streams for mechanical supply, software qualification, and ongoing compliance documentation. This pattern is displacing traditional turnkey vendor relationships in favor of specialized service partnerships. The shift is most visible in United States contract manufacturing, where FDA inspection intensity has elevated documentation quality to a primary selection criterion alongside machine performance specifications.
Vertical Bagging Machine Market Segmentation
Vertical bagging machine purchasing decisions hinge on throughput requirements, regulatory exposure, and existing plant infrastructure. Capital allocation patterns diverge sharply between processors retrofitting legacy pneumatic lines and greenfield facilities specifying servo-electric platforms from commissioning.
Product Type:
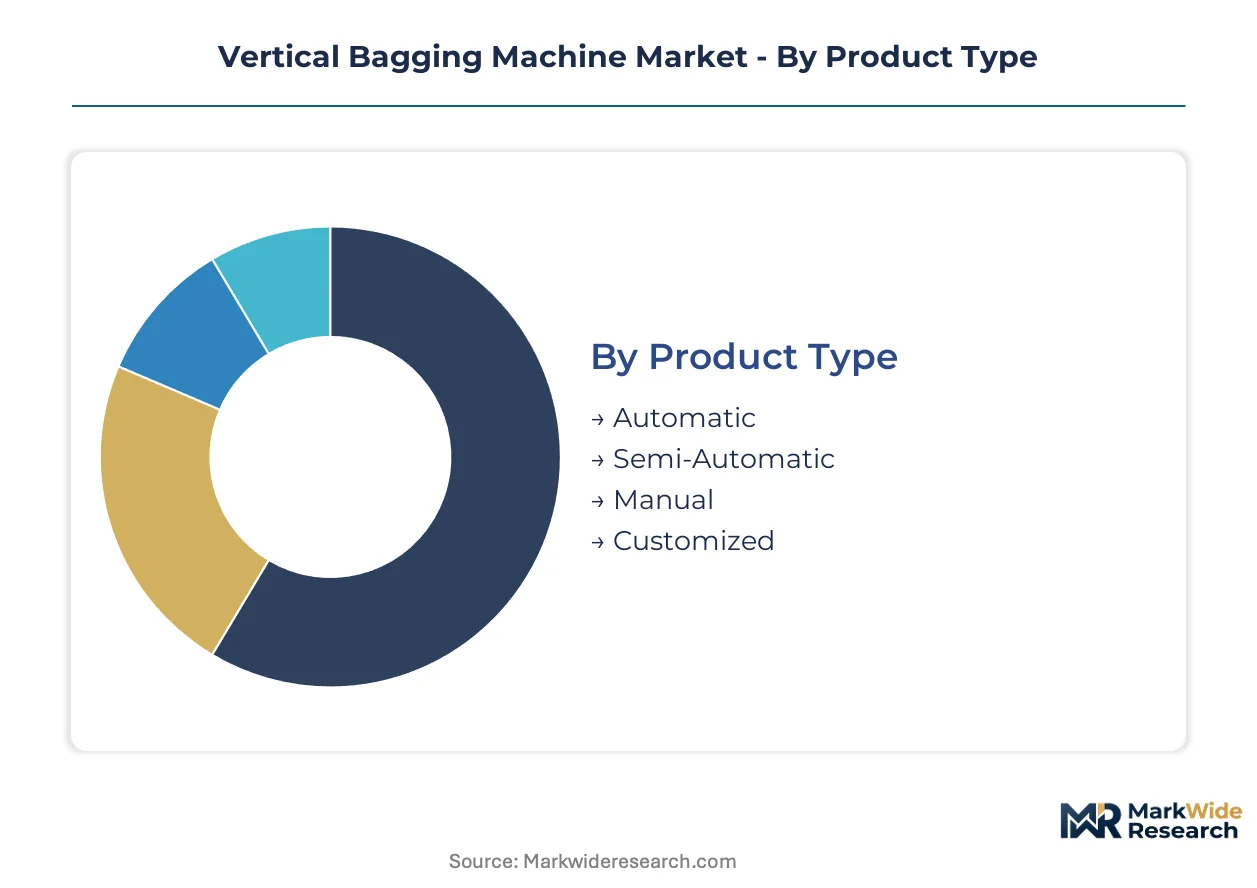
Automatic systems demand the highest upfront capital outlay, requiring integrated servo drives, safety-rated PLCs, and validated software architectures. Semi-automatic and manual alternatives minimize initial investment but impose ongoing labor costs that widen total cost of ownership gaps across extended operating horizons.
- Automatic:Fully integrated systems with closed-loop motion control and audit-trail software dominate pharmaceutical contract manufacturing in Germany, Japan, and the United States. FDA's 21 CFR Part 11 mandates and EMA's Annex 1 sterile manufacturing revisions are accelerating replacement of open-frame pneumatic equipment with sealed servo-electric architectures.
- Semi-Automatic:Hybrid configurations blending operator-fed product loading with automated sealing cycles serve mid-volume food processors in Italy and Spain. REACH substance restrictions on phthalate-containing pneumatic seals are pushing these users toward electric actuation during scheduled upgrade windows.
- Manual:Foot-pedal or hand-lever operated units persist in artisan cheese operations and small-batch cosmetic compounding where changeover flexibility outweighs throughput economics.
- Customized:Engineered-to-order systems accommodate non-standard bag geometries or integrated printing modules for specialty pharmaceutical labeling requirements.
Most installed capacity flows through Automatic systems. Expansion is steepest in Semi-Automatic configurations as processors bridge compressed air infrastructure with precision sealing demands.
Application:
Regulatory intensity varies dramatically across end-use sectors, with pharmaceutical and food packaging facing the most stringent equipment qualification protocols. Cosmetic and chemical applications tolerate broader design tolerances but impose distinct material compatibility requirements.
- Food Packaging:Dairy processors in Denmark and the Netherlands specify hygienic designs with 316L stainless steel contact surfaces and clean-in-place capability. EFSA traceability mandates are forcing integration of vision systems and weight verification modules into bagging line controls.
- Pharmaceuticals:Sterile parenteral product lines require isolator-compatible bagging systems with glove ports and continuous environmental monitoring. Germany's KBA machinery safety enforcement and Japan's METI standards are compressing supplier qualification timelines.
- Cosmetics:Batch-flexible equipment serves fragrance and skincare contract manufacturers in France and Switzerland where frequent changeovers between SKUs prioritize quick-release tooling over raw speed.
- Chemicals:Explosion-proof configurations with ATEX certification handle solvent-based granules and powder formulations in industrial chemical plants.
Food Packaging retains the largest operational footprint. Pharmaceuticals are climbing the fastest as serialization mandates and biologics containment requirements reshape equipment specifications.
End User:
Procurement authority and technical specification depth differ substantially between integrated manufacturers and distribution intermediaries. Direct manufacturing ownership enables longer validation horizons and tighter integration with upstream process equipment.
- Retail:Private-label food and nutritional product packagers in the United Kingdom and Germany specify validated systems with electronic records capability to support downstream supermarket chain audits.
- Wholesale:Ingredient and bulk commodity distributors in the United States prioritize throughput velocity and bag size flexibility over regulatory documentation depth.
- Manufacturing:Captive packaging operations within pharmaceutical and food production facilities demand the tightest MES integration and maintenance service contracts.
- Distribution:Third-party logistics providers handling e-commerce fulfillment for nutritional supplements require rapid case-ready bagging-to-cartoning integration.
Manufacturing end users command the deepest technical engagement. Distribution channels are expanding most quickly as direct-to-consumer pharmaceutical and nutritional shipments proliferate.
Technology:
Actuation platform selection determines energy consumption profiles, maintenance intervals, and positioning precision. Pneumatic legacy infrastructure creates switching costs that hybrid architectures are engineered to mitigate.
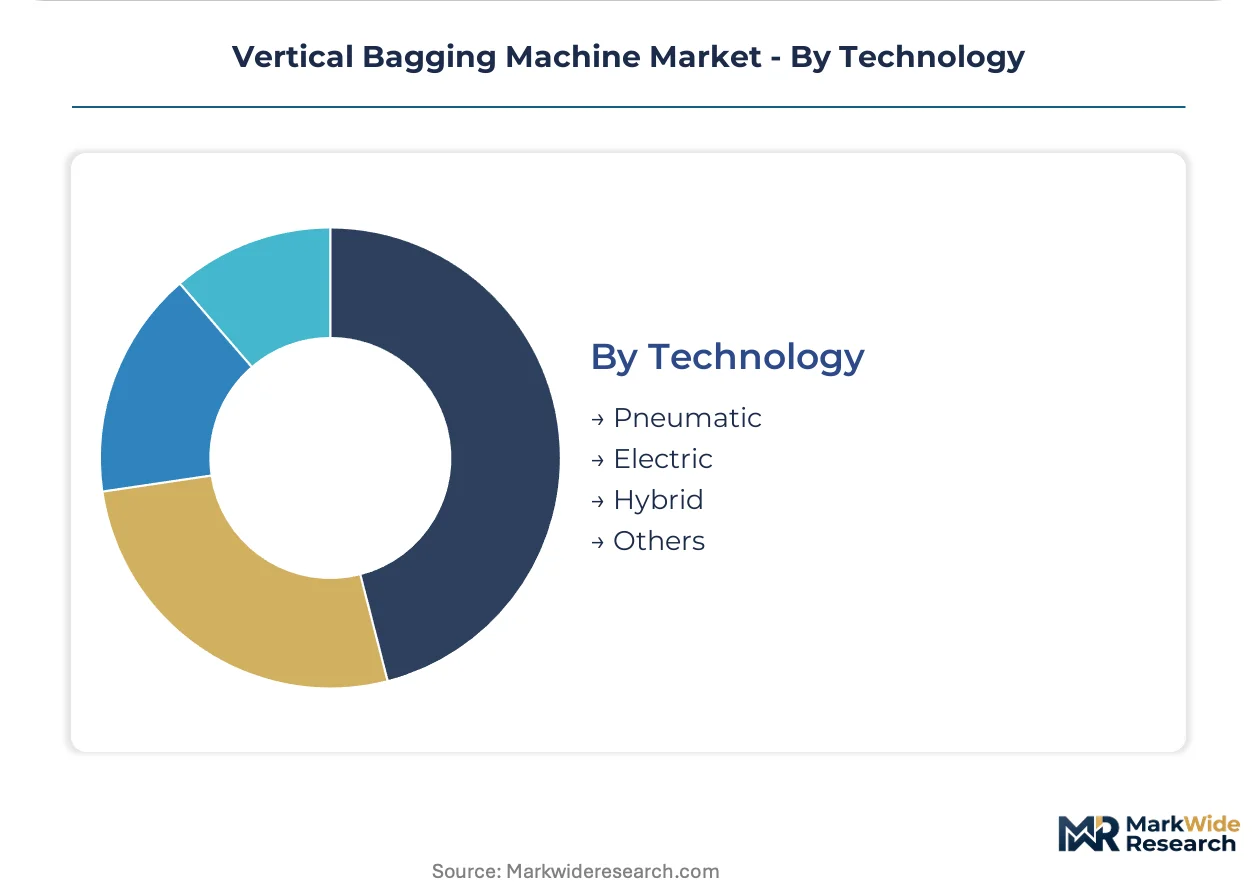
- Pneumatic:Compressed air systems with cylinder-driven jaw actuation retain installed base dominance in mature food plants. ECHA's tightening phthalate limits in seals are accelerating scheduled replacement cycles across European dairy operations.
- Electric:Brushless servo motors with integrated safety encoders deliver the precision required for pharmaceutical seal integrity validation. German and Japanese automation suppliers concentrate controller and drive sourcing, exposing lead time risks for OEMs outside these clusters.
- Hybrid:Pneumatic bag forming combined with electric sealing actuation allows retrofit of existing compressed air infrastructure while achieving regulatory precision requirements. This configuration is expanding most quickly among mid-capacity processors seeking compliance without full line replacement.
- Others:Hydraulic actuation persists in heavy-duty chemical applications requiring extreme clamping forces for multi-ply industrial bags.
Pneumatic technology retains the largest installed base. Hybrid systems are gaining share fastest as processors balance infrastructure reuse against tightening precision mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision packaging machinery during the post-war industrial expansion, establishing technical standards that still govern European equipment qualification. Japanese manufacturers subsequently developed servo-electric architectures that redefined pharmaceutical bagging precision. These dual lineages now compete across regulatory jurisdictions where FDA, EMA, and METI enforcement patterns diverge sharply.
United States
Contract pharmaceutical manufacturers in New Jersey and North Carolina are retrofitting legacy pneumatic lines to meet FDA's Drug Supply Chain Security Act serialization deadlines. The agency's 21 CFR Part 11 electronic records mandates force audit-trail capabilities into all new equipment specifications. Boston-area biologics facilities are integrating vertical baggers with isolator technology for cell therapy containment.
Germany
KBA machinery safety enforcement accelerates replacement cycles for pneumatic sealing systems across Bavarian dairy processing clusters. REACH substance restrictions on phthalate-containing seals compel servo-electric upgrades in Baden-Württemberg pharmaceutical plants. Stuttgart-based automation suppliers concentrate controller sourcing, exposing lead time vulnerabilities for OEMs outside these supply clusters.
Japan
METI standards and PMDA Good Manufacturing Practice inspections create compliance barriers for non-JIS-certified imports into Osaka pharmaceutical corridors. Domestic manufacturers dominate precision servo applications serving Tokyo-area biologics producers. Yokohama packaging equipment clusters specialize in hybrid pneumatic-electric configurations that retrofit existing compressed air infrastructure.
India
CDSCO alignment with PIC/S standards and the PLI scheme for active pharmaceutical ingredients drive equipment qualification demand in Maharashtra and Gujarat. Domestic and multinational drug producers in Hyderabad's Genome Valley are scaling automated packaging capacity. Mumbai-based contract manufacturers concentrate orders for validated bagging systems with electronic records capability.
China
NMPA pharmaceutical regulations are reshaping qualification protocols for equipment destined for Shanghai and Suzhou biopharma manufacturing zones. Yangtze River Delta packaging machinery clusters are developing servo-electric platforms to substitute for German and Japanese controller imports. Beijing's dual carbon goals pressure food processors to abandon compressed air systems for electric actuation.
Vertical Bagging Machine Market Competitive Landscape
The competitive structure tilts toward diversified machinery conglomerates with captive pharmaceutical validation expertise. Tier-one suppliers concentrate in Germany and Japan where METI and KBA enforcement creates regulatory moats. Three archetypes dominate: precision servo-electric specialists serving biologics containment, hygienic design leaders capturing Nordic dairy share, and scale-driven manufacturers controlling lead times for high-volume food clients. Competitive moves center on backward integration into motion control components and geographic expansion through pharmaceutical CDMO partnerships.
Among Germany-based diversified packaging technology groups, Syntegon Technology and Bosch Packaging Technology exemplify contrasting scale strategies. Syntegon anchors the precision-tier through in-house production of servo-electric drive systems that sustain margin advantage across pharmaceutical lines. Bosch occupies a position emphasizing manufacturing footprint breadth with multiple assembly plants controlling delivery timelines. Viking Masek represents the specialized hygienic design archetype, with its competitive position rooted in Nordic dairy packaging applications where clean-in-place capability determines procurement decisions. These three patterns—captive component supply, distributed manufacturing scale, and application-specific engineering—structure competitive rivalry across regulatory jurisdictions.
| Leading Market Players |
|---|
| Syntegon Technology |
| IMA Group |
| Viking Masek |
| Triangle Package Machinery |
| FUJI Machinery |
| Barry-Wehmiller |
| Hayssen Flexible Systems |
| Bosch Packaging Technology |
| Concetti |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical CDMO procurement concentration in Germany, the United States, and Japan anchors project-based equipment pricing with validation support unbundled from mechanical supply. This buyer archetype's technical specification depth compresses margin elasticity for OEMs while amplifying price premiums for audit-trail software and regulatory documentation packages.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales service bundling. Premium tiers command substantial markups for FDA-validated software architectures and METI-compliant safety systems, while economy configurations serve artisan food processors with minimal regulatory exposure. Cost compression in standard-tier pneumatic equipment is intensifying because REACH substance restrictions force redesign investments. Wholesale ingredient distributors exhibit highest price sensitivity; biologics manufacturers show least.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese automation suppliers concentrating servo drive and PLC production. Controller hardware feeds from Baden-Württemberg and Yokohama manufacturing clusters, while 316L stainless steel contact surfaces draw from nickel-price-tethered metallurgical suppliers. Tariff exposure on precision motion components creates procurement risk for OEMs outside these supply clusters. Distribution runs through direct pharmaceutical CDMO contracts and regional equipment distributor networks serving mid-cap food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European REACH compliance costs and Asian manufacturing scale economics, with India's PLI scheme narrowing the regulatory gap.
For Market Incumbents: Acquire motion control component suppliers to secure controller sourcing against German and Japanese supply concentration. Captive servo drive production defends margin position against emerging electric-actuation specialists. Invest in isolator-integration engineering capabilities before EMA Annex 1 enforcement compresses the qualified supplier base. For New Entrants and Emerging Players: Mid-cap dairy processors in Italy and Spain represent an underserved buyer archetype seeking hybrid pneumatic-electric retrofits without full line replacement. Contract manufacturers in Hyderabad's Genome Valley offer penetrable white space with CDSCO PIC/S alignment creating qualification demand. Lead with rapid commissioning expertise to offset incumbent validation service advantages. For Investors and Strategic Acquirers: Diversified packaging conglomerates with pharmaceutical validation expertise are the most active acquirer in this space, consolidating precision-tier capabilities. Five-to-ten-year viability hinges on servo-electric platform ownership and isolator-integration track records. Watch NMPA-PIC/S convergence in China as the inflection signal for Asia-Pacific qualification protocol reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drives | Syntegon's captive production of motion controllers sustains pharmaceutical margin advantage against Bosch's distributed manufacturing scale. |
| Isolator Technology Partnership | Boston biologics facilities demand glove-port-compatible bagging systems as EMA Annex 1 sterile manufacturing revisions compress supplier timelines. |
| Hybrid Configuration Development | Yokohama equipment clusters specialize in pneumatic-electric retrofits that bridge existing compressed air infrastructure with METI precision mandates. |
| Indian CDMO Qualification Push | Mumbai contract manufacturers concentrate orders for validated systems as CDSCO alignment with PIC/S standards drives packaging equipment demand. |
| Software Validation Service Unbundling | United States pharmaceutical procurement departments separate mechanical supply from 21 CFR Part 11 compliance documentation, elevating specialized service partnerships. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from packaging equipment OEM engineering directors, pharmaceutical CDMO procurement managers, dairy plant maintenance supervisors, and aftermarket service heads. Secondary validation drew from FDA 483 inspection observations, EMA GMP inspection databases, KBA machinery safety bulletins, and METI industrial equipment standards. Bottom-up equipment shipment tracking and top-down end-use demand estimation were cross-referenced for triangulation.
Segment-weighting across product type, application, technology platform, and end-user procurement authority structured the analytical framework. Pharmaceutical serialization mandates and biologics containment requirements were modeled as demand accelerants over the projection horizon. CAGRs were derived from installed base replacement cycles and greenfield capacity expansion patterns. Stainless steel input cost volatility and controller lead time fluctuations were incorporated as sensitivity parameters.
Underlying measurement precision varies by segment; automatic pharmaceutical systems carry tighter precision than manual artisan food equipment due to documented procurement data availability. Forecasts reflect assumptions about regulatory enforcement continuity and raw material cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Toilet Roll Converting Lines Market
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
Thermal Film Laminating Machines Market
Packaging Machinery
Meal Tray Sealing Machines Market
Packaging Machinery
Cosmetic Packaging Machinery Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Medicine Decoction and Packing Machines Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Pulp Molding Machines Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Form-Fill-Seal (FFS) Packaging Machine Market
Packaging Machinery
Envelope Sealing Machines Market