
 Folding Gluing Machines Market | 2026-2036
Folding Gluing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Folding Gluing Machines Market Analysis
CE marking under the EU Machinery Directive is redrawing competitive access across European folding gluing equipment supply. Bobst Group leverages its Swiss engineering heritage to sustain premium positioning in high-speed carton finishing. Heidelberg anchors German-speaking markets through integrated press-to-finisher workflows. Koenig & Bauer Duran competes via specialized pharmaceutical-grade validation systems.
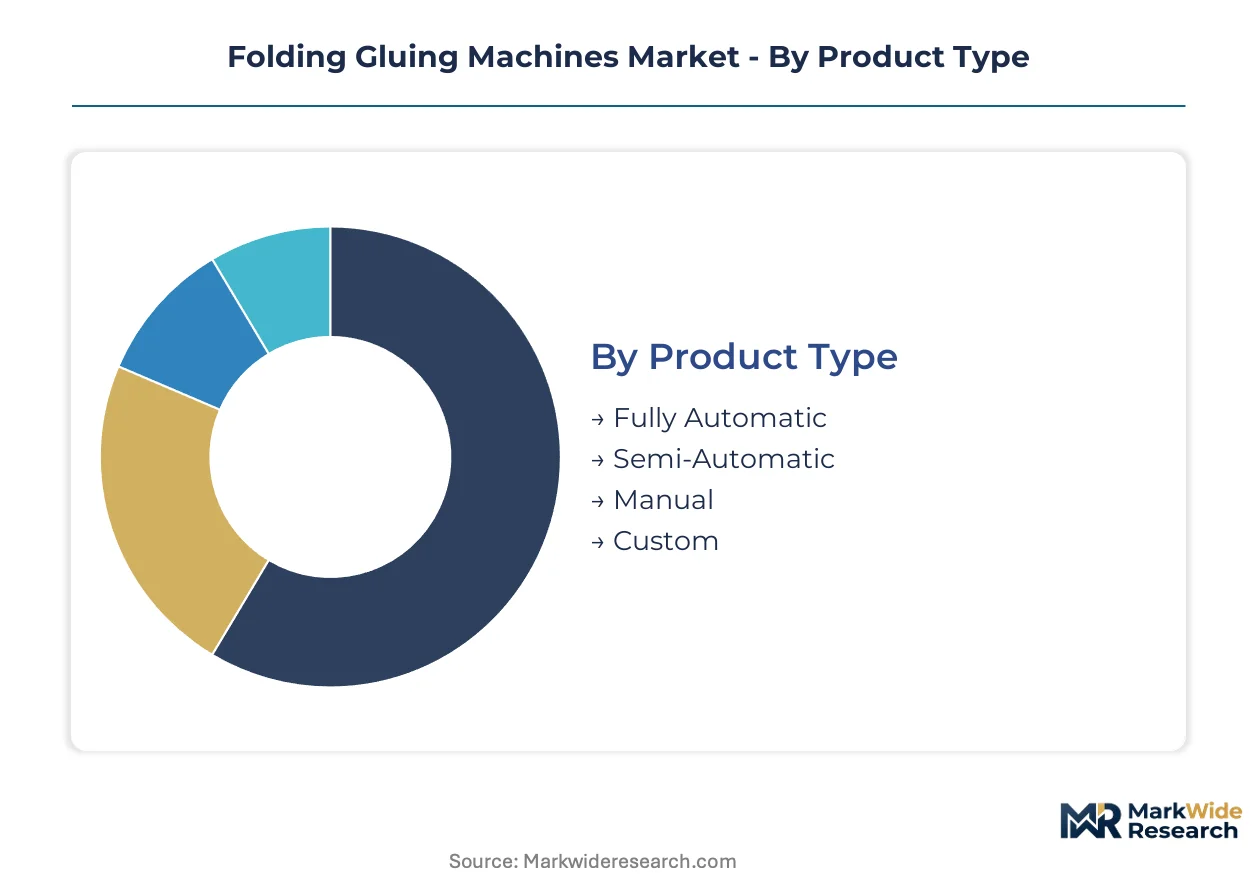
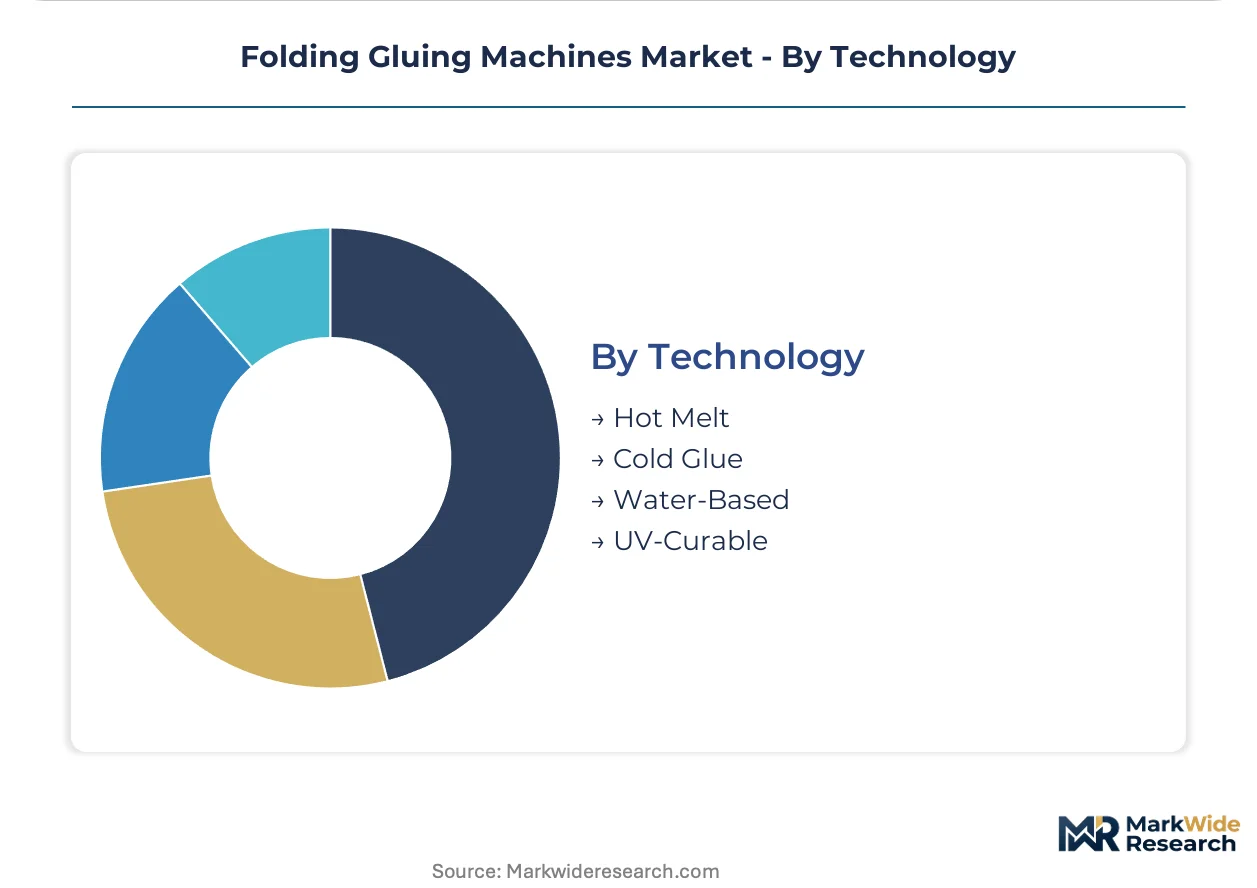
Folding gluing machines mechanically convert flat die-cut carton blanks into finished boxes through sequential folding, adhesive application, and compression stages, operating at speeds from 50 to 600 meters per minute depending on configuration. The equipment serves primary and secondary packaging across consumer goods, with hot melt technology dominating throughput-intensive food and beverage lines while UV-curable systems capture pharmaceutical serialization demands. Fully automatic configurations occupy the bulk of capital deployment as labor costs rise, yet custom machinery for short-run luxury packaging commands disproportionate margin pools. Water-based adhesive technology leads corrugated applications where recyclability certifications gate retailer acceptance.
EMA packaging validation requirements and FDA 21 CFR Part 11 electronic records standards shape pharmaceutical end-use specifications, forcing machine builders to integrate audit-trail software and lot-tracking modules. REACH chemical restrictions and EU Green Deal circular economy targets progressively constrain solvent-based adhesive formulations, redirecting R&D toward bio-derived hot melt polymers. Stakeholders must monitor how China's GB standards evolution and India's BIS machinery safety certifications reshape export qualification burdens for Western equipment suppliers.
Market Dynamics
Europe's F-Gas Regulation is compressing solvent-based adhesive formulations across carton converting operations, forcing machinery OEMs to revalidate water-based and hot melt application systems for existing installed bases. This regulatory compression cascades through equipment specification cycles, spare parts inventories, and operator training protocols.
Growth Catalysts
- Recyclable carton mandates:Retailer sustainability scorecards in Germany and France now require fiber-based secondary packaging, pulling demand for folding gluing lines compatible with uncoated recyclable substrates.
- EMA serialization rules:Pharmaceutical packaging lines across Europe must integrate tamper-evident carton folding with track-and-trace data matrix verification, expanding machine specification requirements.
- Food contact compliance:Hot melt adhesive systems meeting EU 10/2011 food contact standards are displacing solvent alternatives in dairy and ready-meal carton production.
Market Restraints
- Stainless steel input volatility:Machine frames and glue tank assemblies rely on austenitic grades whose price swings compress quoted equipment margins during contract negotiation windows.
- Precision component concentration:Servo motors and linear drives for high-speed folder sections concentrate among Japanese and German suppliers, exposing delivery timelines to single-source bottlenecks.
- Adhesive formulation lag:Bio-derived hot melt polymers validated for high-speed application remain limited, constraining converters' ability to meet EU Green Deal circular economy targets without throughput penalties.
Strategic Opportunities
- Modular retrofit architectures:Equipment designs permitting in-field glue system swaps between hot melt, cold glue, and UV configurations capture converter demand for format flexibility without full line replacement.
- Indian pharmaceutical packaging:CDSCO serialization mandates and domestic vaccine production scale-up create demand for validated folding gluing systems with integrated inspection modules.
- China GB standards evolution:Draft machinery safety certifications for packaging equipment align with ISO 12100 principles, easing export qualification burdens for European OEMs with existing CE documentation.
Industry Challenges
- Mechatronics technician scarcity:Folder-gluer maintenance requires combined mechanical, pneumatic, and PLC troubleshooting skills that vocational pipelines in Western Europe and North America undersupply.
- Legacy system integration:Brownfield carton plants running mechanical folder-gluers from the 1990s face compressed downtime windows for digital control retrofits without disrupting just-in-time customer commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folding Gluing Machines Market |
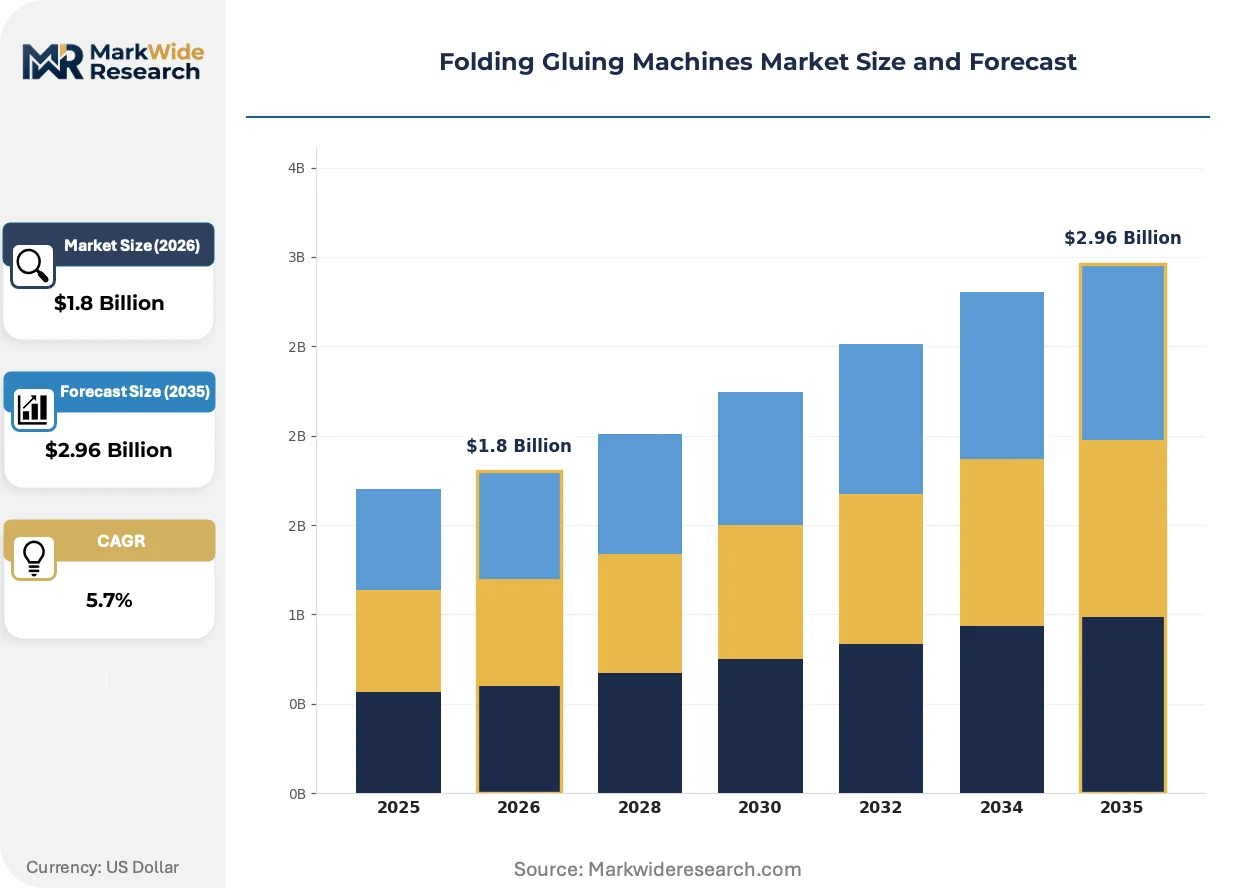
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automatic, Semi-Automatic, Manual, Custom Application: Packaging, Labeling, Cardboard, Corrugated End User: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Technology: Hot Melt, Cold Glue, Water-Based, UV-Curable |
| Companies Covered | Bobst Group, Heidelberg, Koenig & Bauer Duran, Masterwork Group, Zhejiang New Luolan Machinery Co., Ltd., Baumer hhs, Vega Group, B&R Moll Inc., Anhui Gude Machinery Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folding Gluing Machines Market Emerging Trajectories
Machine intelligence and adhesive chemistry are converging to redefine equipment specification criteria. Real-time viscosity monitoring, predictive maintenance algorithms, and substrate-adaptive folding sequences now differentiate competitive offerings from baseline mechanical systems.
Vision-based quality inspection is decomposing traditional offline sampling protocols in pharmaceutical and food packaging lines. High-resolution camera arrays mounted at folder-gluer delivery points detect adhesive skip, fold misregistration, and print defects at production speeds. Major contract packers in Germany and Switzerland now mandate 100% inspection capability as a tender qualification, compressing demand for uninstrumented legacy equipment.
REACH chemical restrictions are progressively constraining solvent-based adhesive formulations across European converting operations. ECHA substance evaluation processes have flagged several conventional carton sealing chemistries for authorization listing, forcing adhesive suppliers to accelerate bio-polymer development. Water-based and UV-curable alternatives are capturing specification share in cosmetic and pharmaceutical applications where odor and migration limits are tightest.
Converters are consolidating vendor relationships around full-line responsibility models that bundle folder-gluer hardware, adhesive supply contracts, and performance-based maintenance agreements. This procurement compression displaces the traditional pattern of separate equipment, consumables, and service sourcing. The shift is most visible in Nordic markets where centralized purchasing functions at multinational packaging groups negotiate multi-site framework agreements.
Folding Gluing Machines Market Segmentation
Folding gluing equipment specification diverges sharply across regulatory environments, with EU F-Gas Regulation and FDA validation requirements forcing distinct machine architectures. Segmentation reveals where capital deployment concentrates and which technology pathways face compliance compression.
Product Type:
Regulatory differentiation in CE marking and FDA 21 CFR Part 11 compliance separates capital-intensive automatic configurations from labor-dependent manual systems.
- Fully Automatic:These systems integrate servo-driven folder sections with PLC-controlled adhesive application and real-time quality monitoring. Food and beverage packaging lines across Germany and France deploy these configurations to meet retailer sustainability scorecards demanding recyclable carton throughput without labor scaling. EMA serialization rules and tamper-evident folding requirements in pharmaceutical applications further pull specification toward fully instrumented automatic architectures.
- Semi-Automatic:Mid-volume converters in Italy and Spain favor these systems for format flexibility across short-run cosmetic and specialty food packaging. The configuration balances capital efficiency against rising labor costs while accommodating water-based adhesive transitions mandated by REACH chemical restrictions.
- Manual:Entry-level operations and prototype development facilities utilize these systems for ultra-short runs and custom structural sampling.
- Custom:Luxury packaging specialists commission bespoke folder-gluer architectures for rigid box and complex carton geometries.
Fully Automatic handles the majority of throughput; Custom is the fastest mover on share.
Application:
Cost tier separation between high-volume corrugated infrastructure and precision pharmaceutical packaging dictates machine specification and margin structure.
- Packaging:Primary and secondary consumer goods carton production dominates equipment utilization, with hot melt systems serving dairy and ready-meal lines under EU 10/2011 food contact standards. Swiss and German contract packers now mandate 100% vision-based inspection capability as tender qualification, compressing demand for uninstrumented legacy equipment in this application tier.
- Corrugated:Water-based adhesive technology leads this segment where recyclability certifications gate retailer acceptance across Nordic and Benelux markets. Brownfield plants running mechanical folder-gluers from prior decades face compressed downtime windows for digital retrofits without disrupting just-in-time commitments.
- Labeling:Pressure-sensitive and wet-glue label finishing applications require specialized folder-gluer adaptations for booklet and promotional label structures.
- Cardboard:Folding carton applications for cosmetics and electronics emphasize precision registration and cosmetic defect rejection at production speeds.
Packaging commands the capital deployment majority; Corrugated is climbing the fastest on specification share.
End User:
Volume concentration in food processing contrasts against margin-rich pharmaceutical validation requirements.
- Food & Beverage:Recyclable carton mandates from German and French retailers drive demand for lines compatible with uncoated fiber substrates. Hot melt adhesive systems meeting EU food contact standards displace solvent alternatives in dairy and ready-meal production.
- Pharmaceuticals:EMA packaging validation and FDA 21 CFR Part 11 electronic records standards force integration of audit-trail software and lot-tracking modules. CDSCO serialization mandates in India and domestic vaccine production scale-up create incremental demand for validated systems with integrated inspection.
- Personal Care:Cosmetic carton applications emphasize odor control and migration limits, favoring UV-curable and water-based adhesive systems.
- Electronics:Anti-static carton specifications and ESD-sensitive handling requirements differentiate equipment for semiconductor and consumer electronics packaging.
Food & Beverage absorbs the volume base; Pharmaceuticals delivers the steepest margin expansion trajectory.
Technology:
Supply concentration in Japanese and German servo motor and linear drive components constrains delivery timelines across all adhesive application architectures.
- Hot Melt:Thermoplastic polymer adhesive systems dominate throughput-intensive food and beverage lines, with bio-derived polymer development constrained by validation timelines for high-speed application. EU Green Deal circular economy targets progressively redirect R&D investment toward renewable feedstock alternatives.
- Water-Based:Europe's F-Gas Regulation compresses solvent-based formulations, accelerating water-based system revalidation for existing installed bases. Corrugated applications in Germany and France favor this technology for recyclability certification compliance.
- Cold Glue:Starch and dextrin-based formulations serve specific food contact and cost-sensitive corrugated applications.
- UV-Curable:Pharmaceutical serialization demands and cosmetic odor restrictions drive specification in Switzerland and German pharmaceutical corridors.
Hot Melt retains the installed base majority; Water-Based is gaining share fastest on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract packaging groups and multinational brand owners concentrate equipment procurement in manufacturing corridors with established machinery ecosystems and stringent regulatory enforcement. Regional demand patterns diverge sharply between mature markets with replacement cycles and emerging markets with greenfield pharmaceutical investments.
Germany
Food and beverage contract packers in the Baden-Württemberg and Bavaria corridors drive replacement demand for high-throughput automatic configurations compatible with retailer sustainability scorecards. The F-Gas Regulation accelerates water-based adhesive system revalidation across existing installed bases. Stuttgart and Munich host dense clusters of machinery OEMs and adhesive suppliers coordinating on EU Green Deal compliance roadmaps.
China
Domestic vaccine production scale-up and export pharmaceutical packaging expansion pull specification toward validated systems with integrated track-and-trace modules. Draft GB standards evolution for packaging equipment safety aligns machinery certification requirements with ISO 12100 principles. The Yangtze River Delta concentration around Shanghai absorbs the majority of imported European folding gluing line deployments.
India
CDSCO serialization mandates for pharmaceutical secondary packaging create demand for folding gluing systems with integrated vision inspection and audit-trail software. Domestic carton converting capacity expansion in Gujarat and Maharashtra targets export markets requiring EU 10/2011 food contact compliance. The BIS machinery safety certification framework progressively tightens import qualification requirements for Western OEMs.
Switzerland
Pharmaceutical packaging validation requirements under Swissmedic oversight sustain premium positioning for equipment with FDA 21 CFR Part 11 electronic records integration. Precision manufacturing clusters around Basel and Zurich coordinate with German adhesive suppliers on UV-curable system development for odor-sensitive cosmetic applications. Swiss contract packers mandate 100% vision-based inspection capability as standard tender qualification.
United States
FDA serialization requirements for pharmaceutical distribution security sustain demand for tamper-evident carton folding with data matrix verification. Food contact compliance enforcement under FDA and EPA frameworks redirects dairy and ready-meal packaging lines toward hot melt systems with validated migration limits. The Midwest manufacturing belt concentrates brownfield retrofit activity as mechanical folder-gluers from prior decades face compressed downtime windows for digital control upgrades.
Folding Gluing Machines Market Vendor Landscape
Player mix skews toward integrated packaging machinery conglomerates with century-long engineering heritage alongside specialized mid-tier fabricators serving regional format-flexibility demands. Market structure exhibits tiered concentration with premium-tier OEMs commanding specification influence at multinational packaging groups while price-sensitive procurement at independent converters fragments volume across second-tier suppliers. Strategic archetypes separate into full-line responsibility bundlers, pharmaceutical validation specialists, and modular retrofit architects. Competitive moves center on adhesive chemistry partnerships for regulatory compliance and in-field configuration flexibility without full line replacement.
Within the heritage engineering tier, Bobst Group and Heidelberg occupy positions defined by Swiss and German manufacturing lineage respectively, with Koenig & Bauer Duran representing the specialized pharmaceutical-grade validation archetype. Chinese fabricators including Zhejiang New Luolan Machinery Co., Ltd. and Anhui Gude Machinery Manufacturing Co., Ltd. exemplify the cost-optimized regional supply tier targeting domestic and emerging market volume. Masterwork Group sits within the integrated printing-to-finishing workflow segment. These named entities serve as anchors for understanding how geographic origin and corporate structure map onto competitive positioning without asserting specific product or strategic claims beyond what their nomenclature reveals.
| Leading Market Players |
|---|
| Bobst Group |
| Heidelberg |
| Koenig & Bauer Duran |
| Masterwork Group |
| Zhejiang New Luolan Machinery Co., Ltd. |
| Baumer hhs |
| Vega Group |
| B&R Moll Inc. |
| Anhui Gude Machinery Manufacturing Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Swiss OEM assembly plants shapes both supply concentration and price floors across the folding gluing equipment market. High fixed-cost structures in precision mechatronics production tether quoted equipment margins to stainless steel input volatility and servo motor delivery timelines.
Pricing Analysis
Cost-plus contracts with austenitic steel indexation dominate equipment quotations across European and North American procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade validation systems from food-contact compliant lines and entry-level corrugated configurations. Pricing pressure stems from Japanese and German precision component bottlenecks that compress quoted margins during contract negotiation windows. Independent converters in Southern Europe exhibit highest price sensitivity, while multinational packaging groups in Germany and Switzerland prioritize specification compliance over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German and Swiss contract packers, while strategic stockpiling of servo motors and linear drives concentrates among Japanese suppliers buffering against semiconductor foundry constraints. Component sourcing draws from Germany, Japan, and China for precision motion systems, adhesive application modules, and control electronics respectively. Single-source vulnerability in high-torque servo motors exposes delivery timelines to automotive sector demand spikes. Distribution runs through machinery OEM direct sales teams and specialized packaging equipment distributors serving regional converter clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Folding gluing equipment sits in early-cycle expansion as pharmaceutical serialization mandates and recyclable carton regulations drive replacement demand across European and Indian packaging corridors.
For Market Incumbents: Fortify aftermarket service revenue through performance-based maintenance agreements bundling adhesive supply and spare parts logistics. Deepen captive production of glue application modules to offset precision component cost volatility from Japanese suppliers. CE marking documentation investments defend specification access as China's GB standards evolve toward ISO 12100 alignment. For New Entrants and Emerging Players: Differentiate on modular retrofit architectures permitting in-field glue system swaps without full line replacement. Target mid-volume converters in India's Gujarat and Maharashtra corridors facing CDSCO serialization deadlines with validated systems priced below premium-tier OEM offerings. Go-to-market through adhesive supplier partnerships bundling equipment and consumables procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical validation specialists with audit-trail software and lot-tracking module integration. Long-term viability favors equipment OEMs with backward integration into control electronics and adhesive chemistry partnerships. Watch for inflection when bio-derived hot melt polymer validation timelines compress, enabling premium pricing for EU Green Deal compliant configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Retrofit Architecture Development | Captures converter demand for format flexibility without capital-intensive line replacement across brownfield plants. |
| Adhesive Chemistry Partnership | Accelerates bio-polymer validation for high-speed application under REACH and EU Green Deal compliance timelines. |
| Pharmaceutical Validation Specialization | Secures specification at multinational packaging groups facing EMA and FDA 21 CFR Part 11 electronic records mandates. |
| Indian Market Localization | Addresses CDSCO serialization requirements and BIS machinery safety certification tightening for Western OEM export access. |
| Vision-Based Inspection Integration | Meets 100% quality verification tender qualifications now standard among Swiss and German contract packers. |
Methodological Framework
Initial hypotheses were tested against primary input from maintenance directors at carton converting plants, OEM procurement teams, adhesive supplier technical directors, and aftermarket service heads, then refined through secondary validation. Bottom-up equipment shipment data from machinery OEMs combined with top-down packaging production capacity estimates across Germany, China, India, and Switzerland. Secondary sources included EU F-Gas Regulation implementation reports, EMA packaging validation guidelines, FDA 21 CFR Part 11 compliance documentation, and BIS machinery safety certification frameworks.
Variance decomposition across product type, application tier, end-use industry, adhesive technology, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level volume trajectories weighted by average selling price evolution. Industry-specific forecast inputs incorporated pharmaceutical serialization mandate timelines and EU Green Deal circular economy target compliance curves.
Material uncertainties — adhesive formulation validation delays, stainless steel price volatility, and precision component supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and converter capital expenditure cycles. Revision becomes warranted when bio-derived polymer application speeds cross throughput parity thresholds with conventional hot melt systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Corrugated Box Machines Market
Packaging Machinery
Liquid Capsule Filling Machines Market
Packaging Machinery
Cosmetic Filling Machines Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Slitter Rewinder Machines Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Twist Tie Machines Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Lamination Systems Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Pouch Sealing Machine Market
Packaging Machinery
Product Dispensing Machinery Market