
 Magnetic Closure Box Market | 2026-2036
Magnetic Closure Box Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Closure Box Market Foresight
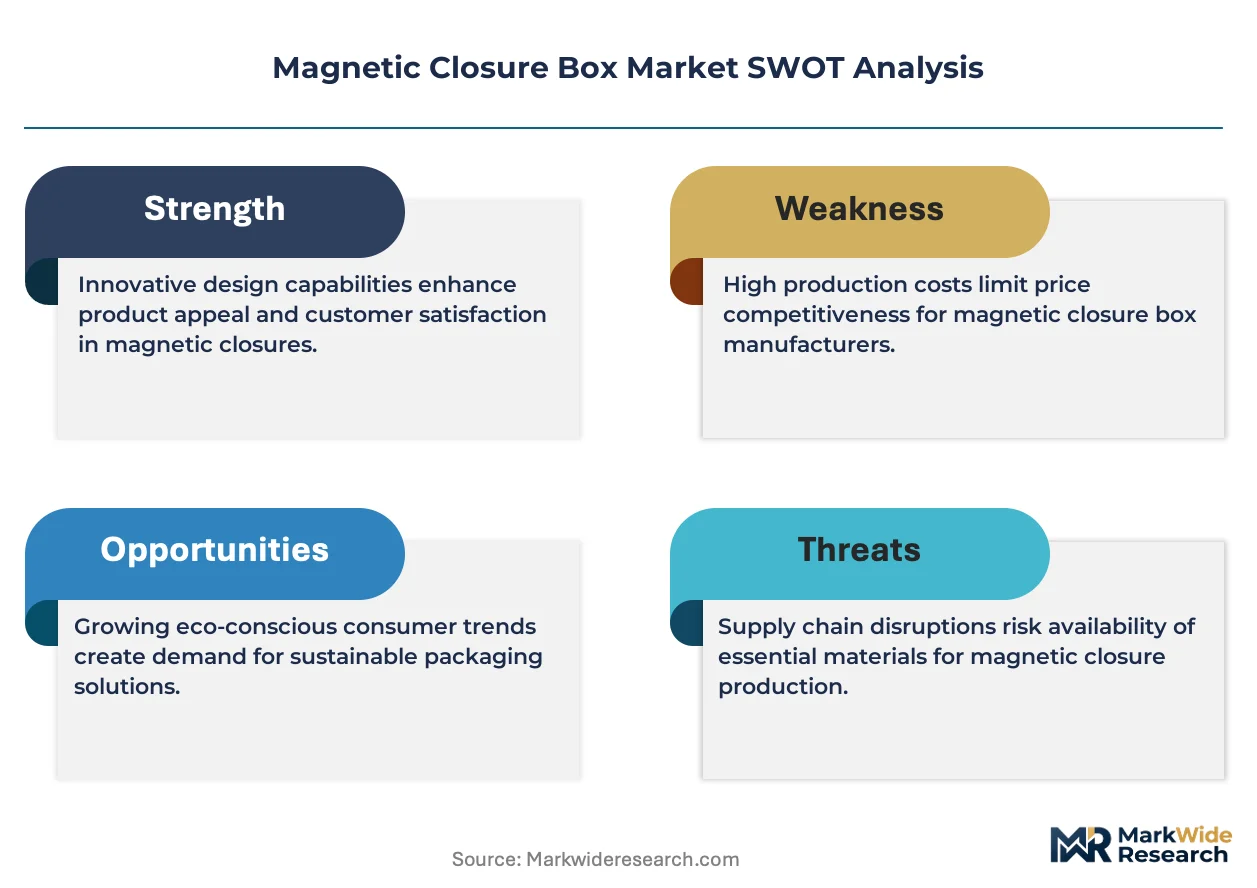
Buyer concentration in the luxury cosmetics and spirits sectors is decoupling from traditional mid-market retail procurement, fragmenting demand across direct-to-consumer subscription services and boutique gift channels. WestRock Company leverages its North American containerboard integration to supply high-volume retail programs with consistent magnetic closure specifications. Smurfit Kappa Group anchors European demand through its specialized display and premium packaging division, while DS Smith competes aggressively in the UK premium drinks segment with bespoke structural design capabilities.
A magnetic closure box is a rigid or semi-rigid packaging structure incorporating neodymium or ferrite magnet pairs embedded within folded paperboard walls, enabling repeated opening and closing without mechanical fasteners; manufacturers typically employ die-cutting, V-groove scoring, and automated magnet insertion to achieve alignment tolerances within 0.5 millimeters. These structures serve primarily to elevate perceived product value, protect contents during transit, and extend functional reuse by end consumers. Luxury Boxes command the deepest margin pools due to brand-specific customization requirements and low price elasticity among prestige cosmetics and watchmakers, while Custom Boxes represent the fastest-expanding segment as e-commerce merchants seek differentiated unboxing experiences at moderate volumes. Paperboard dominates material consumption by tonnage, though Leather formats sustain premium positioning in the Middle East and East Asian gift markets where tactile quality signals status.
REACH compliance governs chemical content in European-sourced adhesives and coatings, while FDA regulations in the United States stipulate migration limits for substances contacting food-grade magnetic closures in premium confectionery applications. China's GB standards for packaging materials, administered by SAMR, increasingly reference recyclability metrics that pressure converters toward mono-material paperboard constructions. Stakeholders must monitor evolving extended producer responsibility frameworks across the European Union, Japan, and California to anticipate redesign costs and material substitution timelines before compliance deadlines crystallize competitive disadvantage.
Market Dynamics
EU Packaging and Packaging Waste Regulation recyclability mandates are forcing converters toward mono-material paperboard constructions, eliminating laminated films and metalized layers that previously secured magnetic retention strength.
Growth Catalysts
- Direct-to-consumer subscription channels:Boutique beauty and spirits merchants in France and South Korea specify magnetic closures for unboxing content creation, driving specification pull-through at moderate volumes.
- REACH adhesive compliance:European converters achieving full chemical disclosure certification capture premium positioning among cosmetics houses requiring supply chain transparency documentation.
- Zhejiang folding carton clustering:China's specialized export manufacturing base offers integrated die-cutting, magnet insertion, and finishing within 50-kilometer supplier radii, compressing lead times for luxury goods clients.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing capacity clusters in China's Inner Mongolia and Jiangxi provinces, exposing converters to export quota volatility and price spikes.
- GB standards recyclability thresholds:SAMR-administered packaging regulations in China increasingly restrict multi-material constructions, complicating magnetic closure designs that embed metal within paperboard walls.
- Rigid box automation limits:Magnetic alignment tolerances below 0.5 millimeters resist full automation, constraining throughput scalability versus folding carton alternatives.
Strategic Opportunities
- Middle East leather-format expansion:Tactile gift packaging in UAE and Saudi Arabia sustains premium positioning where paperboard lacks status signaling power.
- California extended producer responsibility frameworks:Advance compliance with SB 54 mandates positions suppliers for preferential procurement by brands anticipating 2032 recycling rate targets.
- Mono-material magnetic systems:Ferrite-paperboard composites and printable magnetic inks converge to eliminate separate magnet insertion, enabling full recyclability certification.
Industry Challenges
- Precision die-cutting skill scarcity:V-groove scoring and magnet pocket formation require specialized tooling expertise concentrated in aging European and Japanese technician populations.
- EU Green Deal compliance timeline compression:Rapidly crystallizing 2025-2030 packaging redesign deadlines force simultaneous capital deployment across multiple facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Closure Box Market |
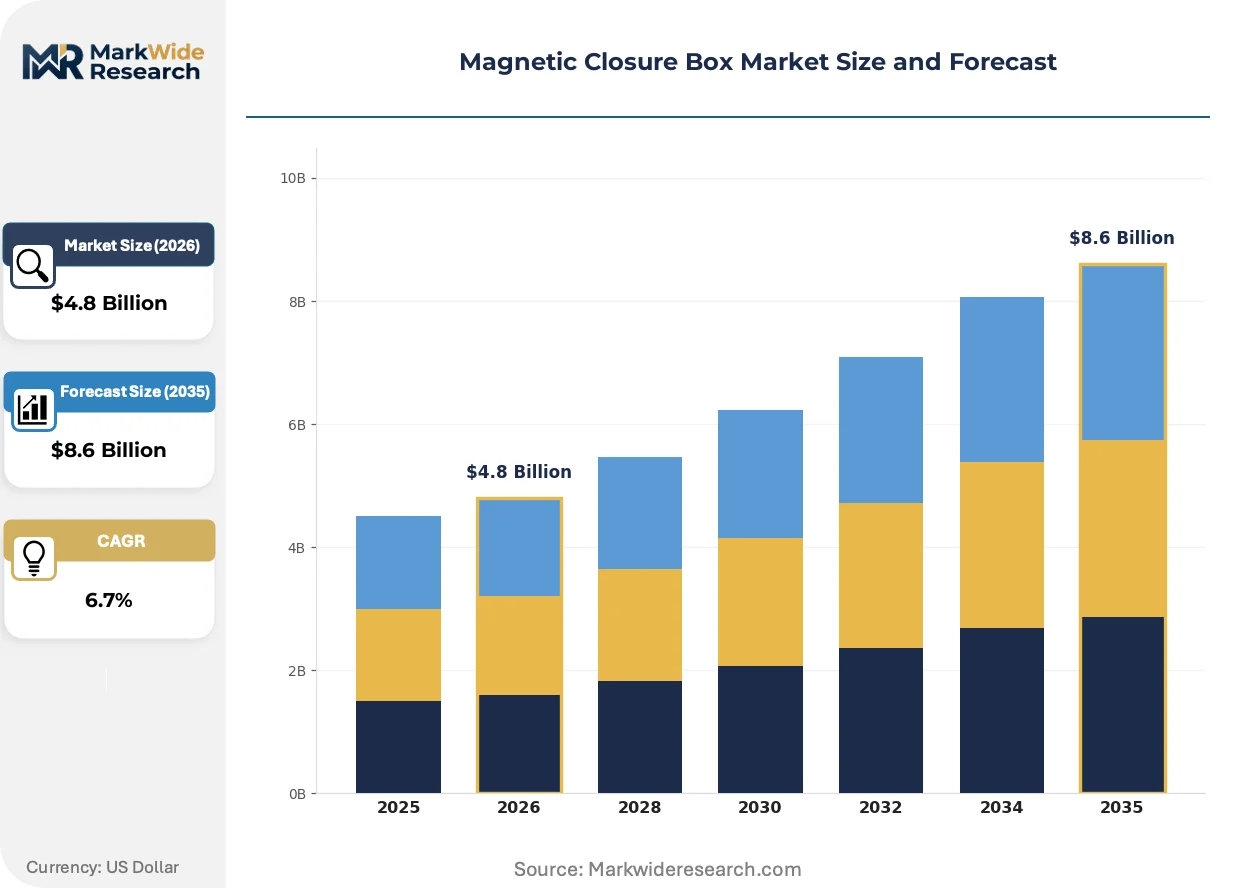
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Boxes, Custom Boxes, Gift Boxes, Retail Packaging Material: Paperboard, Wood, Plastic, Leather End User: Retailers, E-Commerce, Gift Shops, Packaging Manufacturers Design Style: Minimalist, Vintage, Modern, Themed |
| Companies Covered | Blue Box Packaging, PakFactory, Emenac Packaging, Sunrise Packaging, Claws Custom Boxes, WestRock Company, Smurfit Kappa Group, DS Smith, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Closure Box Market Shifts & Advancements
Magnetic closure manufacturing is bifurcating between luxury customization at low volume and standardized platforms for e-commerce scalability, with material science and regulatory compliance as the decisive vectors.
Printable ferrite magnetic inks are integrating directly into paperboard substrates during roll-to-roll coating operations, eliminating discrete magnet insertion steps. High-end watchmakers and jewelry houses in Switzerland and Japan pilot these systems for ultra-thin rigid boxes below 3 millimeter wall thickness. The technology is integrating formerly separate converting stages, compressing capital requirements for mid-tier entrants.
REACH SVHC candidate list expansion is tightening adhesive and coating substance restrictions across European supply chains. Converters face reformulation cycles every 18-24 months as ECHA adds new substances of very high concern. Premium confectionery applications in Germany and France experience the most acute compliance pressure, with brands demanding full material passports upstream to tier-three suppliers.
Subscription box merchants now specify magnetic closures for retention and reuse rather than single-use presentation, extending functional lifespan expectations. Direct-to-consumer spirits and beauty channels in South Korea and the United States displace traditional retail gift packaging procurement. This behavioral pivot concentrates volume among fewer, larger subscription platform buyers with standardized specifications.
Magnetic Closure Box Market Segmentation
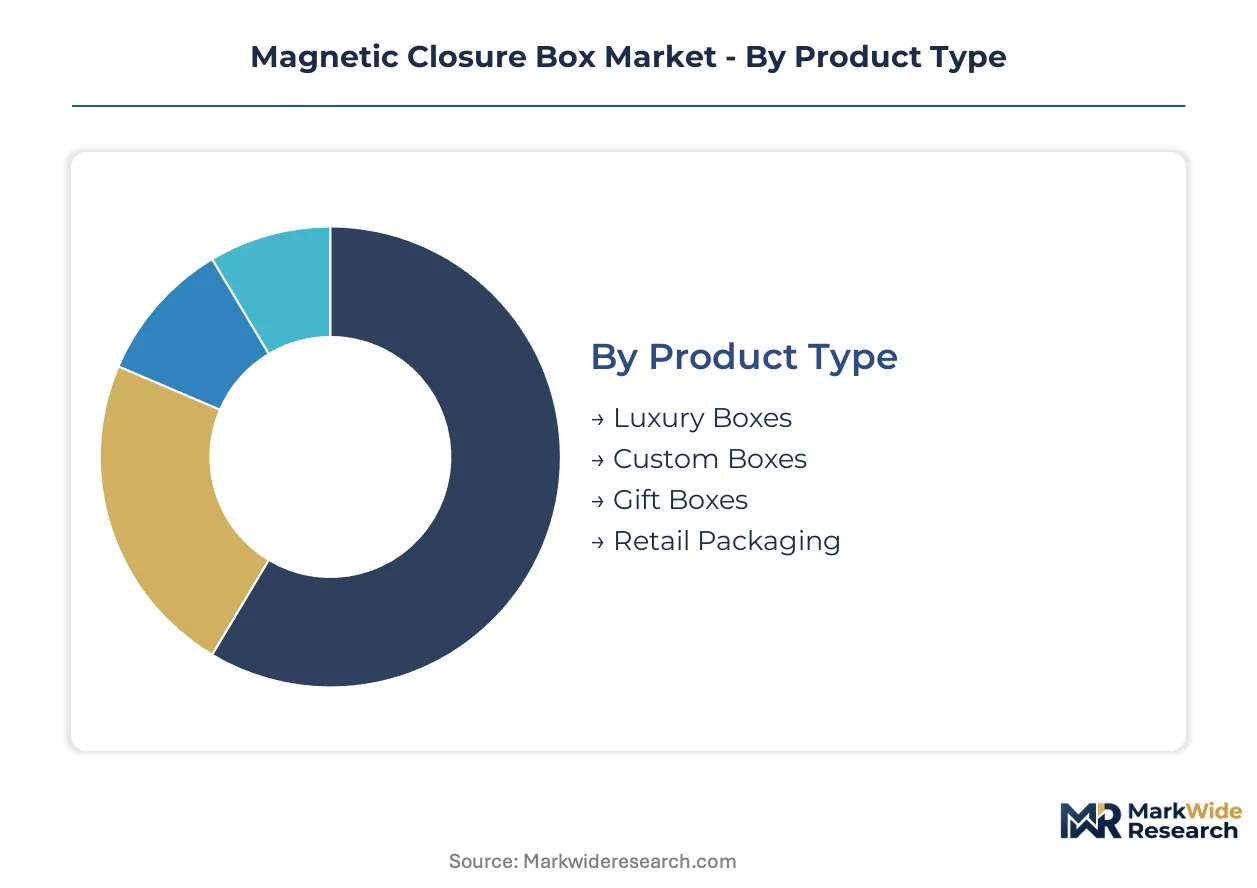
Magnetic closure box procurement splits sharply between prestige cosmetics houses demanding bespoke certification trails and e-commerce merchants optimizing for standardized unboxing scalability. Regulatory burdens vary dramatically by segment, with food-contact applications triggering FDA migration limits and European luxury formats requiring REACH SVHC documentation across tier-three adhesive suppliers.
Product Type:
FDA migration thresholds govern premium confectionery applications in the United States, while REACH SVHC disclosure obligations dominate European cosmetics procurement. Luxury formats face the steepest compliance burden.
- Luxury Boxes:Rigid constructions with neodymium magnet pairs embedded in V-groove scored walls, typically 2-4 millimeter thickness. Swiss watchmakers and French prestige cosmetics houses concentrate specification authority here, demanding batch-level material passports and sub-millimeter alignment tolerances that resist automation.
- Custom Boxes:Moderate-volume formats with standardized magnet insertion patterns enabling digital print personalization. South Korean subscription beauty platforms and US direct-to-consumer spirits merchants drive specification pull-through, prioritizing unboxing content creation over structural novelty.
- Gift Boxes:Seasonal formats with ferrite magnet systems balancing retention strength against cost.
- Retail Packaging:High-volume standardized specifications for mass-market cosmetics and electronics accessories.
Leading the category by volume: Retail Packaging. Growing fastest: Custom Boxes.
Material:
Cost tiers stratify sharply, with paperboard commanding mid-market volumes and leather sustaining premium positioning in status-conscious gift cultures.
- Paperboard:Folding carton and rigid board grades dominate tonnage consumption, with mono-material constructions gaining preference under EU Packaging and Packaging Waste Regulation recyclability mandates. Zhejiang province converters integrate die-cutting, magnet insertion, and finishing within compressed supplier radii.
- Leather:Full-grain and bonded leather formats sustain premium positioning in UAE and Saudi Arabian gift markets where tactile quality signals recipient status. Middle East procurement patterns favor these formats for Ramadan and Eid corporate gifting cycles.
- Wood:Hardwood and veneer constructions for ultra-premium spirits and cigar presentations.
- Plastic:Acrylic and PET formats for transparent display applications in electronics retail.
Cost concentration sits with Paperboard. Margin expansion concentrates in Leather.
End User:
Procurement authority is shifting from traditional retail buyers toward platform-controlled subscription merchants with standardized specifications.
- E-Commerce:Subscription box merchants in South Korea and the United States now specify magnetic closures for retention and reuse, displacing traditional gift packaging procurement. These buyers consolidate volume behind fewer, larger platform relationships with rigid specification templates.
- Retailers:Department store cosmetics counters and boutique spirits merchants in France maintain bespoke procurement relationships, fragmenting demand across multiple converter relationships.
- Gift Shops:Seasonal and occasion-driven procurement with high SKU fragmentation.
- Packaging Manufacturers:Converter-to-converter trade for specialized magnet insertion and finishing services.
Volume authority is shifting fastest toward E-Commerce. Bespoke complexity remains with Retailers.
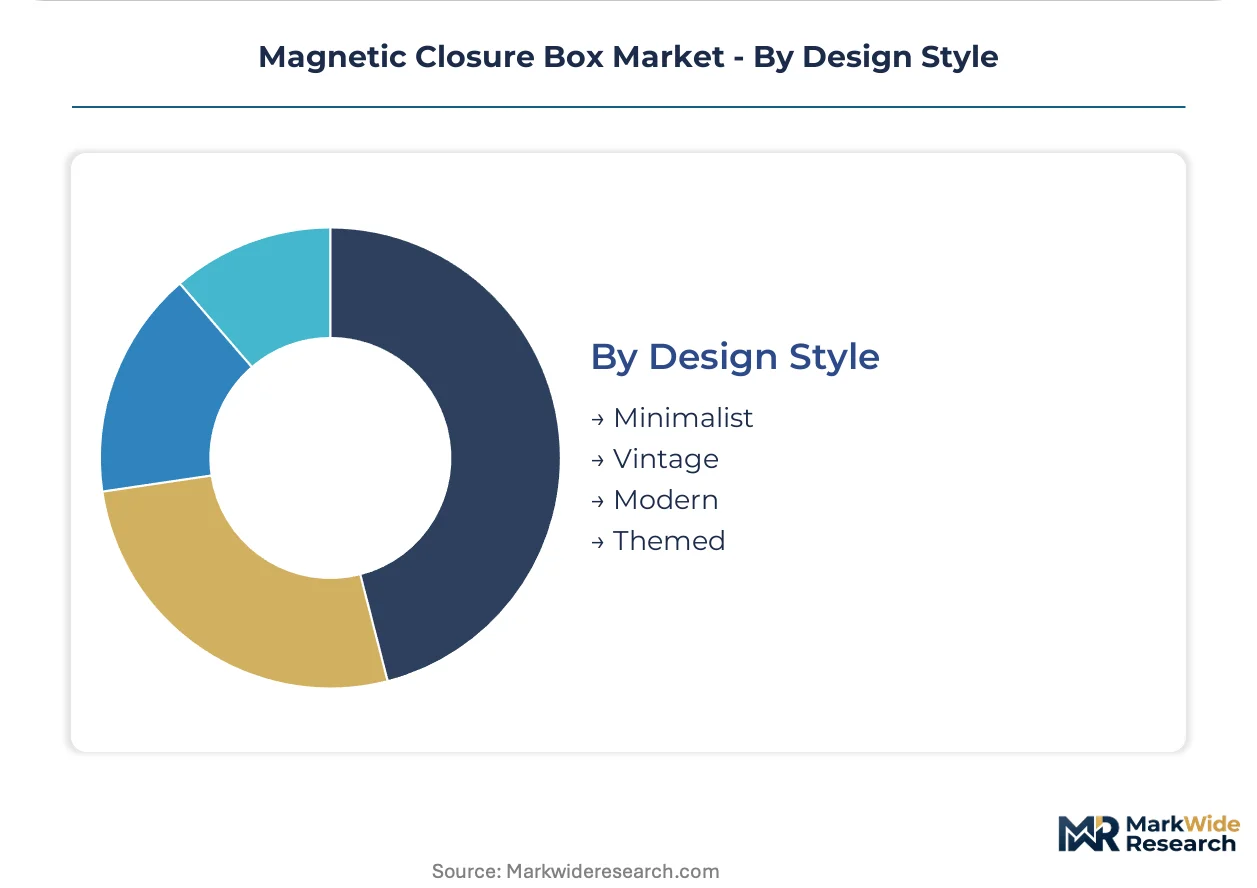
Design Style:
Customer type determines specification priority, with content-creation merchants favoring photogenic formats and heritage brands demanding archival authenticity.
- Minimalist:Clean lines, uncoated paperboard, and concealed magnet placement dominate South Korean beauty subscription specifications. These formats optimize for smartphone unboxing content with neutral backgrounds and shadow control.
- Vintage:Distressed finishes, brass hardware accents, and visible stitching serve heritage cosmetics houses in France and Switzerland seeking archival authenticity cues.
- Modern:Geometric forms and metallic foil blocking for contemporary electronics and accessories presentations.
- Themed:Seasonal and collaboration-specific formats with limited production runs.
Specification frequency runs highest for Minimalist. Premium pricing attaches to Vintage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium magnet processing capacity in China's Inner Mongolia and Jiangxi provinces anchors raw-material availability for magnetic closure converters worldwide. France and South Korea drive specification innovation through luxury cosmetics unboxing requirements. The EU Packaging and Packaging Waste Regulation and China's GB standards reshape material choices across manufacturing clusters.
China
Zhejiang province folding carton clusters integrate die-cutting, magnet insertion, and finishing within compressed supplier radii for export-oriented luxury goods clients. SAMR-administered GB standards increasingly restrict multi-material constructions, pressuring converters toward mono-material paperboard designs. Inner Mongolia and Jiangxi rare earth processing facilities supply neodymium magnet feedstock, exposing converters to export quota volatility.
France
Prestige cosmetics houses in Paris and Lyon concentrate specification authority for bespoke luxury formats demanding batch-level material passports. REACH SVHC candidate list expansions tighten adhesive and coating substance restrictions, forcing reformulation cycles every 18-24 months. Alsace and Normandy converting facilities specialize in V-groove scoring and precision magnet alignment for Swiss watchmaker clients.
South Korea
Seoul-based subscription beauty platforms specify minimalist magnetic closures optimized for smartphone unboxing content creation. MFDS regulations govern food-contact packaging migration limits for premium confectionery applications. Busan-Ulsan manufacturing corridors supply standardized formats to direct-to-consumer spirits merchants displacing traditional retail procurement.
Germany
Premium confectionery brands in Bavaria and North Rhine-Westphalia demand full REACH chemical disclosure certification across tier-three adhesive suppliers. EU Green Deal compliance timelines compress 2025-2030 packaging redesign deadlines across multiple facility upgrades. Baden-Württemberg precision tooling specialists concentrate scarce V-groove scoring expertise for sub-millimeter magnet alignment tolerances.
United States
Direct-to-consumer subscription merchants in California and New York consolidate volume behind standardized specification templates for retention-focused packaging. FDA migration limits govern substances contacting food-grade magnetic closures in premium confectionery applications. California SB 54 extended producer responsibility frameworks position advance-compliant suppliers for preferential procurement ahead of 2032 recycling rate targets.
Magnetic Closure Box Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue mono-material recyclable formats and printable magnetic ink technologies. The vendor base spans integrated paperboard converters, specialized rigid box manufacturers, and regional folding carton specialists. Three archetypes dominate: North American containerboard-integrated suppliers, European premium packaging specialists with display and design capabilities, and Chinese export-focused clusters with compressed lead times. Competitive moves concentrate on strategic partnerships for magnet supply security and portfolio diversification into leather and wood formats.
Among North American integrated producers, WestRock Company exemplifies the containerboard-anchored archetype serving high-volume retail programs. European specialists Smurfit Kappa Group and DS Smith occupy positions on the premium-format vector, with the former anchoring display and packaging division capabilities and the latter representing bespoke structural design competitiveness in drinks segments.
| Leading Market Players |
|---|
| Blue Box Packaging |
| PakFactory |
| Emenac Packaging |
| Sunrise Packaging |
| Claws Custom Boxes |
| WestRock Company |
| Smurfit Kappa Group |
| DS Smith |
| Mondi Group |
| Others |
Supply & Pricing Matrix
Captive magnet insertion capabilities within Zhejiang province converters anchor both supply security and pricing power for export-oriented luxury formats, insulating premium tier suppliers from neodymium price volatility while forcing mid-market competitors into spot-market magnet procurement. This backward integration into rare earth-adjacent processing creates margin asymmetry that pricing structures amplify rather than compress.
Pricing Analysis
Extended alignment warranties and batch-level material passport documentation are bundled into luxury tier contracts while standard formats trade unassured. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified European production from Zhejiang export formats and spot-market generic specifications. Cost compression in the standard tier is intensifying because subscription merchants consolidate volume behind rigid specification templates. E-commerce subscription platforms exhibit highest price sensitivity; Swiss watchmakers and French prestige cosmetics houses demonstrate lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Dubai, and Singapore enable hub-and-spoke fulfillment patterns that compress lead times for European and Middle Eastern luxury clients. Manufacturing gravity draws from China's Zhejiang and Guangdong provinces, Germany's Baden-Württemberg tooling corridor, and South Korea's Busan-Ulsan corridor. Raw material dependencies rest on Inner Mongolia and Jiangxi rare earth processing, European REACH-compliant adhesive formulations, and Nordic paperboard pulp grades. Single-source vulnerability concentrates in neodymium magnet feedstock. Distribution runs through converter-direct relationships for bespoke formats and platform-aggregated procurement for standardized subscription specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Printable ferrite magnetic ink technology is displacing discrete neodymium insertion across mid-volume segments, compressing capital barriers for entrants while forcing legacy converters toward certification-differentiated positioning.
For Market Incumbents: To counter printable magnetic ink commoditization in the standard tier, deepen captive magnet supply relationships through offtake agreements with Jiangxi and Inner Mongolia processors, and accelerate REACH SVHC certification depth to capture cosmetics house procurement authority in France and Germany. For New Entrants and Emerging Players: Mono-material recyclable format specialization offers the most penetrable wedge for mid-tier volume capture, targeting California SB 54 advance compliance positioning and South Korean subscription platform specifications with ferrite-paperboard composite platforms that eliminate separate magnet insertion stages. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to North American containerboard-integrated suppliers seeking European premium-format capabilities, with long-term viability hinging on regulatory compliance depth rather than scale alone. Precision die-cutting tooling specialists in Germany and Japan represent priority acquisition archetypes. The signal to watch is ECHA SVHC list expansion velocity as a proxy for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing from Jiangxi processors insulates margin against export quota volatility. |
| REACH SVHC Certification Investment | Full chemical disclosure certification captures procurement authority from French prestige cosmetics houses. |
| Printable Magnetic Ink Platform Development | Ferrite-paperboard composite technology eliminates discrete magnet insertion for mid-volume scalability. |
| California SB 54 Advance Compliance Positioning | Mono-material recyclability certification secures preferential procurement from subscription platform buyers. |
| Leather Format Manufacturing Partnership | UAE and Saudi Arabian gift market access sustains premium positioning where tactile quality signals status. |
Research Methodology
Multi-period observation of magnet price indices, converter capacity utilization, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with Zhejiang export manufacturing managers, European prestige cosmetics packaging procurement leads, South Korean subscription platform supply chain directors, and German precision tooling specialists. Secondary validation drew from SAMR GB standards documentation, ECHA SVHC candidate list publications, FDA migration limit guidance, and customs trade data for paperboard and rare earth magnet categories. Bottom-up volume estimates triangulated against top-down spending projections across end-use segments.
Segment-weighting approaches applied product type, material composition, end-user channel, and design style dimensions across the modeling period. CAGRs were derived from trend extrapolation of historical volume patterns adjusted for regulatory phase-in schedules and technology substitution curves. Forecast inputs incorporated neodymium price volatility scenarios and EU Packaging and Packaging Waste Regulation compliance cost assumptions.
Several conditions sit outside the modeled scope, including geopolitical disruption to rare earth export flows, unanticipated ECHA substance restrictions, and breakthrough alternatives to magnetic closure mechanisms. Forecasts reflect documented assumptions around regulatory timeline adherence and technology adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Lug Caps Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
Reverse Cap Bottles Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Case Closures and Sealers Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Box Latch Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Brush Caps Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Drum Plugs Market
Caps and Closures
Continuous Thread Metal Cap Market