
 Benelux Container Glass Market | 2026-2036
Benelux Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Benelux Container Glass Market Insights
Buyer concentration among Benelux beverage multinationals is hardening as craft distillers and private-label mineral water brands fragment the customer base alongside consolidated dairy and sauce processors. Konings NV anchors its position through captive filling lines and regional distribution density. Gerresheimer AG differentiates via pharmaceutical-grade borosilicate capacity that commands premium positioning in vaccine and injectable packaging. Vetropack Group sustains cost leadership through furnace scale and recycled glass integration at its Belgian operations.
Container glass denotes hollow glassware formed by blow-and-blow or press-and-blow processes from silica sand, soda ash, and limestone melts, typically achieving wall thicknesses of 2–5 millimeters and thermal shock resistance up to 40°C for standard soda-lime formulations. Its primary purpose is hermetic, chemically inert storage for consumable and medicinal products requiring UV protection and oxygen barrier properties. Bottles retain the dominant volume share across the Benelux market, though pharmaceutical vials and cosmetic jars capture disproportionate margin pools due to stricter pharmacopeial compliance and smaller batch runs. Recycled glass feedstock is displacing virgin soda-lime as the fastest-growing input category, driven by furnace energy savings and EPR compliance thresholds.
Belgium's Federal Public Service Health enforces food-contact migration limits through EU Regulation 10/2011, while the Netherlands' Rijksdienst voor Ondernemend Nederland administers packaging waste recovery targets under the EU Packaging and Packaging Waste Directive. REACH compliance and the EU Green Deal's carbon border adjustments are reshaping furnace fuel choices and cullet sourcing requirements. Stakeholders must monitor whether Dutch and Belgian regulators accelerate mandatory recycled content minimums ahead of the broader EU timeline.
Market Dynamics
The EU Green Deal's carbon border adjustments are compressing furnace fuel choices across Benelux, forcing container glass producers to reconfigure cullet sourcing and natural gas substitution strategies ahead of 2026 compliance deadlines.
Growth Catalysts
- Extended Producer Responsibility schemes:Belgium and the Netherlands mandate escalating packaging waste recovery targets, pulling investment toward closed-loop cullet processing infrastructure.
- Rotterdam port logistics:Dense container shipping routes reduce inbound silica sand and soda ash landed costs for Dutch glassworks versus inland European competitors.
- Pharmaceutical-grade borosilicate demand:Vaccine packaging requirements from Benelux health authorities expand premium vial production capacity.
Market Restraints
- Natural gas price volatility:Furnace energy costs constitute 25-30% of production expenses, exposing margins to TTF hub fluctuations.
- High-purity silica sand concentration:Belgian and Dutch producers depend on limited Nordic and Ukrainian quarry suppliers for low-iron feedstock.
- Lightweighting technical ceiling:Soda-lime bottles below 180 grams fail impact resistance tests for carbonated beverage applications.
Strategic Opportunities
- Luxembourg distribution nodes:Underdeveloped relative to Belgium and the Netherlands, offering logistics arbitrage for premium cosmetic jar exports.
- Electrified melting pilots:Hybrid furnace trials combining renewable hydrogen with electric boosting align with EU Green Deal trajectory.
- Direct-to-craft-distiller channels:Small-batch spirit brands bypass traditional beverage multinational procurement gates.
Industry Challenges
- Furnace rebuild cycles:Ten-year refractory lifespans lock capital allocation decisions ahead of confirmed hydrogen infrastructure rollout.
- Pharmacopeial certification timelines:USP and EP compliance for injectable glass requires 18-24 month validation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benelux Container Glass Market |
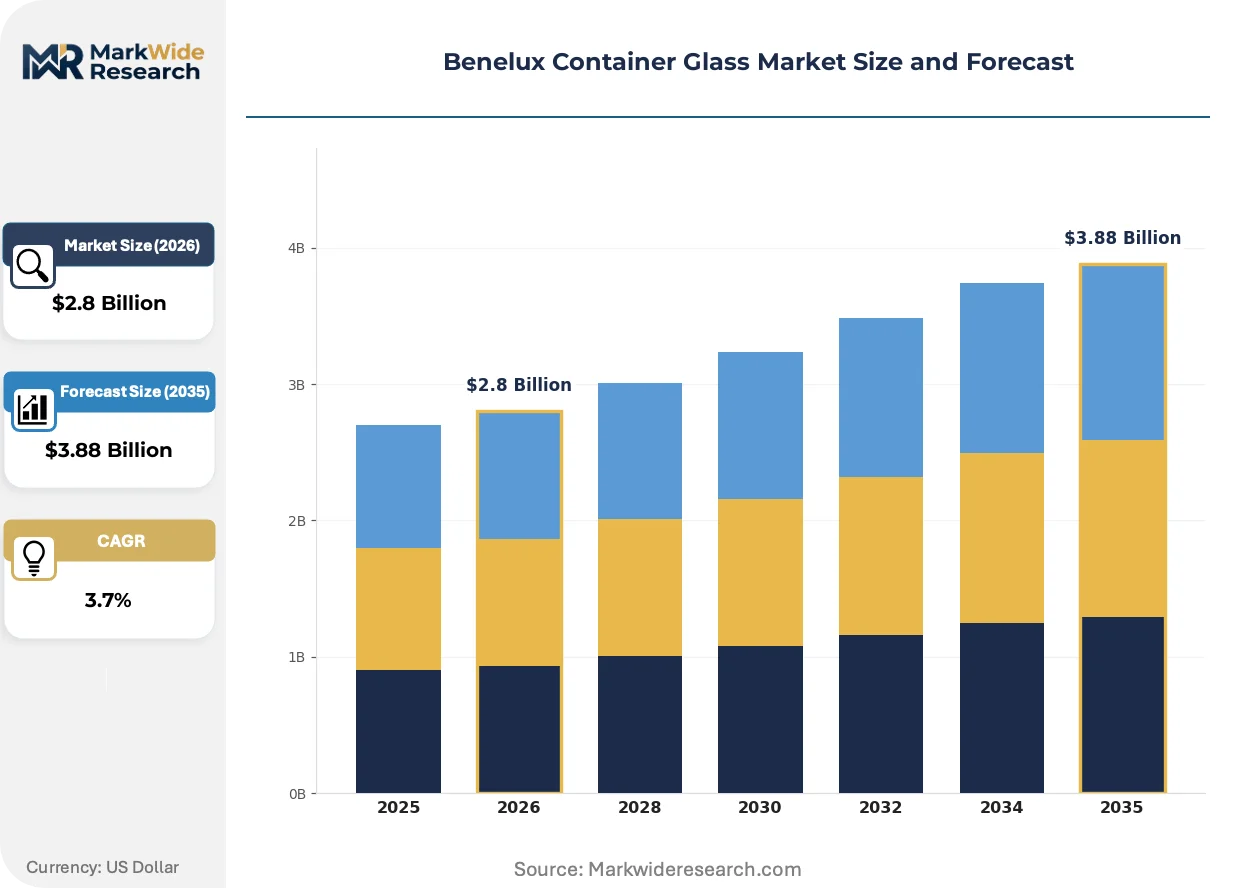
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.88 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Canisters, Tumblers End User: Beverage, Food, Pharmaceuticals, Cosmetics Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesalers Glass Type: Recycled, Soda-Lime, Borosilicate, Lead Glass |
| Companies Covered | Konings NV, AYANO HOLLAND BV, Ciner Glass Belgium NV, Gerresheimer AG, AXA GLASS bv/srl, Saverglass, AGC Glass Europe SA/NV, Bormioli Rocco, Vetropack Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benelux Container Glass Market Trends and Innovations
Active furnace technology trials and procurement model fragmentation are compressing traditional supply relationships across Belgian, Dutch, and Luxembourg glass markets.
Oxy-fuel combustion retrofitting is integrating plasma-assisted melting controls to reduce NOx emissions by 40-60% versus regenerative air-fuel systems. Konings NV and Vetropack Group pilot these installations at Belgian sites. The technology is integrating carbon capture readiness into furnace design specifications demanded by EU carbon border adjustment phase-in.
REACH compliance deadlines for Substances of Very High Concern in packaging coatings are forcing reformulation of external glass treatments. ECHA's 2025 sunset dates for certain chromate pigments impact decorative bottle segments. Dutch dairy processors accelerate migration to untreated amber glass to preempt authorization bottlenecks.
Consolidated beverage multinational procurement is fragmenting as craft distillers and private-label mineral water brands establish direct mill relationships. Rotterdam-based traders lose volume to producer-direct contracts. This pattern concentrates in the Netherlands where Amsterdam food processing clusters anchor alternative sourcing networks.
Benelux Container Glass Market Segmentation
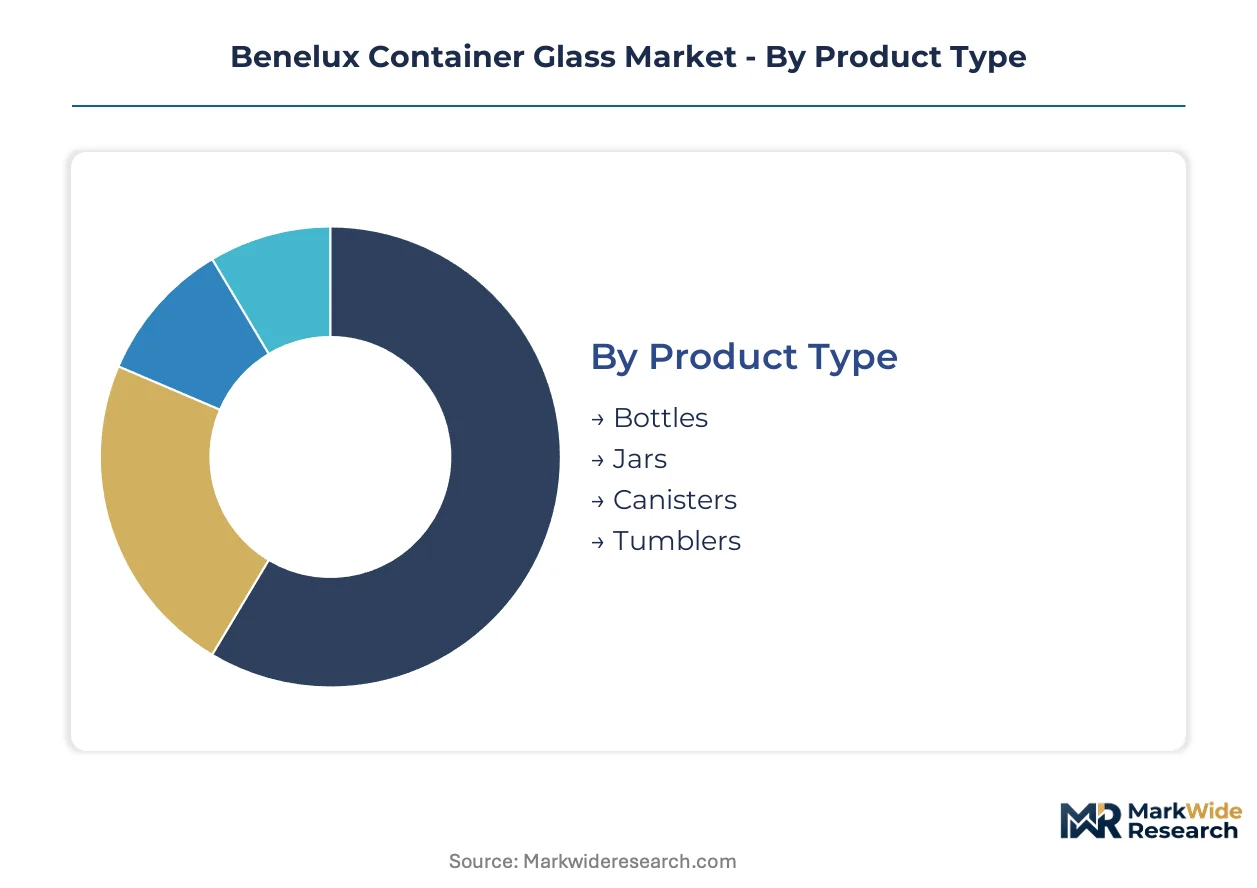
Benelux container glass procurement patterns diverge sharply across product formats and end-use specifications, with furnace economics and regulatory compliance thresholds fragmenting traditional supply relationships. Upgrade cycles in beverage packaging and pharmaceutical-grade capacity expansion are reshaping segment prioritization among Dutch and Belgian producers.
Product Type:
Replacement cycles in beverage packaging and premium cosmetics are accelerating format-specific capacity investments across Belgian and Dutch glassworks.
- Bottles:Soda-lime formulations dominate carbonated beverage and mineral water applications, with wall thicknesses calibrated to 2–4 millimeters for pressure resistance. Rotterdam port logistics anchor procurement for Dutch beverage multinationals, while Amsterdam craft distillers drive small-batch amber and flint variants. Volume placements concentrate in Bottles; the faster expansion belongs to Jars.
- Jars:Wide-mouth configurations serve sauce, preserve, and cosmetic cream segments requiring hermetic seal integrity. Belgian dairy processors and Dutch condiment manufacturers specify lightweighted designs below 200 grams to meet EPR compliance thresholds.
- Canisters:Large-format storage vessels for bulk food ingredients and pharmaceutical intermediates, typically exceeding 500 milliliters capacity. Dutch food processing clusters around Amsterdam source these for ingredient staging.
- Tumblers:Drinking glasses and non-hermetic serveware, generally excluded from premium packaging margin pools. Luxembourg hospitality distributors represent a niche outlet for branded promotional runs.
Cost tiering separates commodity bottles from value-added pharmaceutical and cosmetic formats.
End User:
Application-specific compliance requirements create divergent margin structures across Benelux container glass demand.
- Beverage:Carbonated soft drinks, beer, spirits, and mineral water represent the volume anchor. Dutch craft distillers and private-label water brands are fragmenting traditional multinational procurement channels through direct mill relationships.
- Food:Dairy, sauces, preserves, and ready-meal packaging face stringent EU Regulation 10/2011 migration limits enforced by Belgium's Federal Public Service Health. Amber glass adoption is climbing fastest among Dutch dairy processors seeking untreated alternatives to REACH-restricted coatings.
- Pharmaceuticals:Injectable vials and vaccine packaging command pharmacopeial-grade borosilicate specifications with 18–24 month USP and EP validation timelines. Benelux health authority procurement is expanding premium capacity at specialized producers.
- Cosmetics:Premium jars and bottles for skincare and fragrance segments require decorative surface treatments now pressured by ECHA sunset dates for chromate pigments. Luxembourg distribution nodes offer logistics arbitrage for export-oriented cosmetic packaging.
Pharmaceutical and cosmetic segments capture disproportionate margin pools despite smaller batch volumes.
Distribution Channel:
Channel configuration determines order granularity and inventory velocity for Benelux glass container fulfillment.
- Online Retail:Direct-to-brand platforms serving craft distillers and niche cosmetic startups with minimum order quantities below traditional wholesale thresholds. Rotterdam-based traders are losing volume to producer-direct contracts.
- Supermarkets:Private-label mineral water and store-brand sauce procurement concentrated among Belgian and Dutch retail chains with consolidated annual tenders.
- Convenience Stores:Single-serve beverage and impulse food packaging with higher frequency, lower volume replenishment cycles.
- Wholesalers:Traditional intermediaries for food service and hospitality glassware, facing margin compression from direct sourcing trends.
Direct channels are gaining share fastest among small-batch beverage and cosmetic brands.
Glass Type:
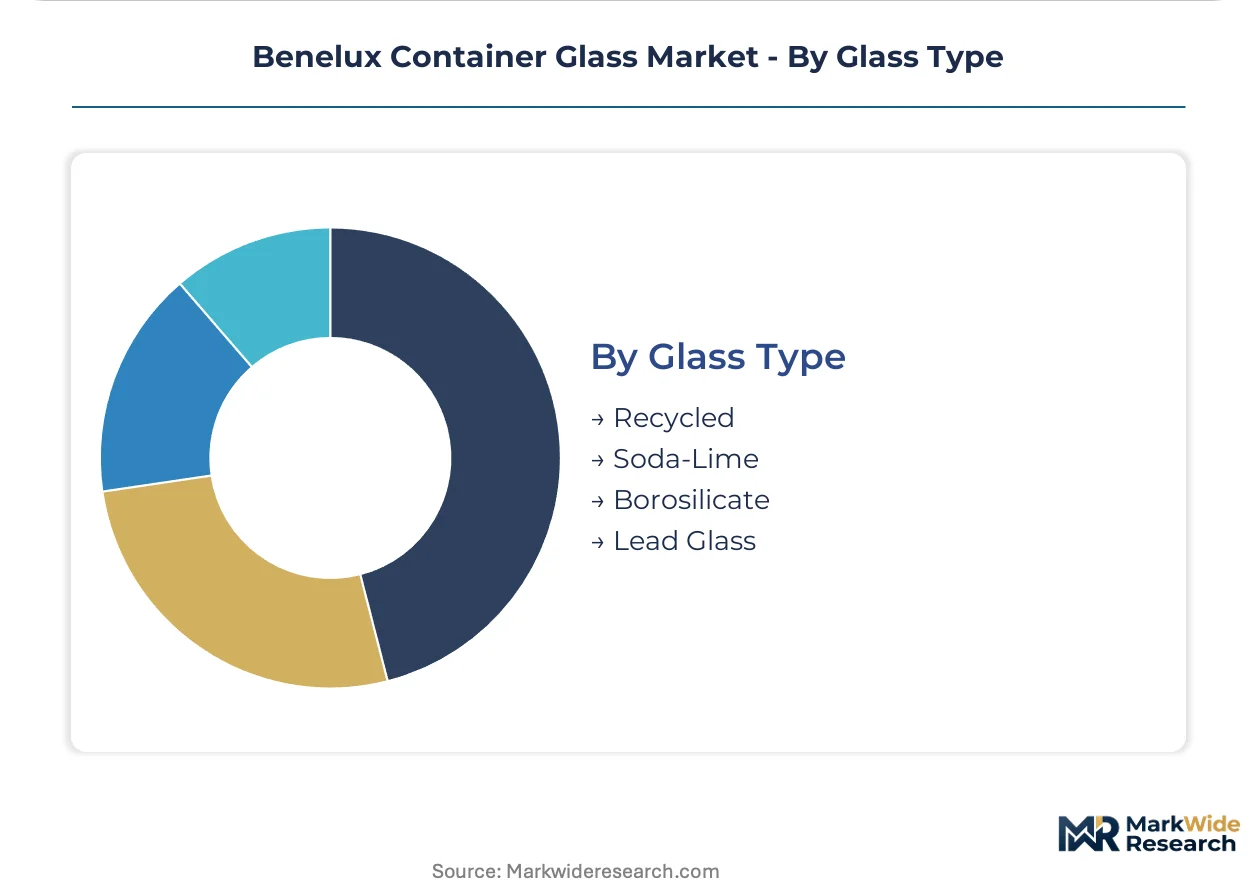
Feedstock specifications are shifting under EU Green Deal carbon border adjustments and Extended Producer Responsibility mandates.
- Recycled:Post-consumer cullet displaces virgin soda-lime as furnace input of choice, delivering energy savings and EPR compliance. Belgian and Dutch recovery targets are pulling investment toward closed-loop processing infrastructure.
- Soda-Lime:Standard silica-soda-lime formulations for general-purpose packaging, facing lightweighting technical ceilings below 180 grams for carbonated applications. Nordic and Ukrainian low-iron sand dependencies create supply concentration risks.
- Borosilicate:Thermal shock-resistant formulations for pharmaceutical vials and premium laboratory glassware. Vaccine packaging demand from Benelux health authorities is expanding specialized production capacity.
- Lead Glass:High-refractive-index decorative and crystal applications, now restricted in food-contact uses under REACH. Remaining demand concentrates in luxury cosmetic and giftware segments.
Recycled feedstock integration is climbing the fastest, though borosilicate maintains the steepest premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in the Netherlands drives procurement patterns across the Benelux cluster, with Rotterdam's port infrastructure and Amsterdam's food processing anchors pulling container glass volumes. Belgian furnace capacity and Luxembourg's underdeveloped logistics nodes complete the sub-regional mosaic.
Netherlands
Rotterdam's dense container shipping routes reduce landed costs for silica sand and soda ash, anchoring procurement for Dutch beverage multinationals. The Rijksdienst voor Ondernemend Nederland administers packaging waste recovery targets under the EU Packaging and Packaging Waste Directive. Amsterdam's food processing clusters host alternative sourcing networks that bypass traditional trader intermediaries.
Belgium
Federal Public Service Health enforces EU Regulation 10/2011 food-contact migration limits, tightening compliance thresholds for dairy and sauce processors. Extended Producer Responsibility schemes mandate escalating recovery targets that pull investment toward closed-loop cullet infrastructure. Vetropack Group's Belgian operations leverage furnace scale and recycled glass integration to sustain cost leadership positions.
Luxembourg
Underdeveloped distribution nodes relative to Belgium and the Netherlands create logistics arbitrage opportunities for premium cosmetic jar exports. REACH compliance deadlines for Substances of Very High Concern reshape decorative coating formulations across the Grand Duchy's limited processing footprint. Luxembourg City-based hospitality distributors represent niche outlets for branded promotional glassware runs.
Benelux Container Glass Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-craft channels and electrified melting pilots. The vendor base clusters around three archetypes: integrated beverage processors with captive filling lines, pharmaceutical-grade specialists commanding pharmacopeial premiums, and scale-driven furnace operators optimizing cullet integration. Competitive moves concentrate on oxy-fuel combustion retrofitting and carbon capture readiness investments ahead of EU carbon border adjustment phase-in.
Among Benelux-based fabricators, Konings NV and Vetropack Group exemplify the integrated-scale archetype, while Gerresheimer AG occupies a position within the premium pharmaceutical-grade tier. Konings NV represents the beverage-processor integration model through regional distribution density. Vetropack Group anchors cost leadership through furnace scale and Belgian recycled glass operations. Gerresheimer AG exemplifies the specialist path via borosilicate capacity serving vaccine and injectable packaging requirements.
| Leading Market Players |
|---|
| Konings NV |
| AYANO HOLLAND BV |
| Ciner Glass Belgium NV |
| Gerresheimer AG |
| AXA GLASS bv/srl |
| Saverglass |
| AGC Glass Europe SA/NV |
| Bormioli Rocco |
| Vetropack Group |
| Others |
Pricing and Supply Chain Analysis
Oxy-fuel combustion retrofitting across Belgian and Dutch furnace fleets is compressing operating cost differentials while concentrating procurement leverage among early adopters. This technology transition simultaneously raises capital barriers for laggard producers and shifts buyer power toward glassworks with integrated carbon capture readiness.
Pricing Analysis
Volume placements in commodity soda-lime bottles trade at thin margins while pharmaceutical-grade borosilicate vials capture substantial premiums due to USP and EP certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates pharmacopeial-certified formats from general-purpose packaging and untreated amber glass alternatives. Cost compression in standard bottles is intensifying because lightweighting investments and recycled cullet integration are narrowing cost advantages between Belgian furnace operators and Dutch port-proximate competitors. Private-label mineral water brands and craft distillers exhibit the highest price sensitivity, whereas vaccine packaging procurement from Benelux health authorities shows minimal elasticity.
Supply Chain Analysis
Low-iron silica sand feedstock rests on concentrated Nordic and Ukrainian quarry suppliers, creating geographic dependency for Belgian and Dutch soda-lime production. Furnace operations draw from soda ash sourced from Solvay's remaining European production and limestone from regional Benelux deposits, with recycled cullet displacing virgin materials fastest under EPR compliance thresholds. Single-source vulnerability in high-purity sand creates exposure to transport disruption through Rotterdam port congestion. Distribution runs through Rotterdam-based traders for bulk beverage contracts, though direct mill relationships are fragmenting traditional wholesale channels among Amsterdam craft distillers and Dutch dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Benelux container glass sector is executing a furnace technology transition, with electrified melting pilots and hydrogen-ready designs replacing legacy natural-gas-dependent infrastructure. This shift reconfigures capital allocation priorities and competitive positioning across the forecast horizon.
For Market Incumbents: Anticipate furnace rebuild cycles locking in technology choices ahead of confirmed hydrogen infrastructure rollout by securing carbon capture readiness in current oxy-fuel retrofits. Prioritize backward integration into closed-loop cullet processing infrastructure to defend margin position against EPR compliance cost pass-through. Scale pharmaceutical-grade borosilicate capacity to offset commodity bottle margin erosion from lightweighting technical ceilings. For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Belgium and the Netherlands open a window for electrified melting pilot operators to establish first-mover positioning ahead of incumbent furnace replacement cycles. Target Luxembourg distribution nodes for premium cosmetic jar exports where logistics arbitrage remains underdeveloped relative to Belgian and Dutch corridors. Pursue direct-to-craft-distiller channel relationships bypassing Rotterdam trader intermediaries. For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical-grade specialists given vaccine packaging demand expansion from Benelux health authorities. Long-term viability over a five-to-ten-year window favors operators with integrated recycled glass processing and carbon capture readiness. The signal to watch is accelerated mandatory recycled content minimums from Dutch and Belgian regulators ahead of broader EU timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Combustion Retrofit | Konings NV and Vetropack Group pilots reduce NOx emissions 40-60% versus regenerative air-fuel systems. |
| Closed-Loop Cullet Infrastructure | Belgian EPR recovery targets pull investment toward integrated recycled glass processing at furnace sites. |
| Pharmaceutical-Grade Capacity Expansion | Gerresheimer AG borosilicate operations capture vaccine packaging premiums with 18-24 month validation timelines. |
| Direct-to-Craft Channel Development | Amsterdam craft distillers and private-label water brands fragment traditional multinational procurement gates. |
| Electrified Melting Pilot Investment | Hybrid furnace trials combining renewable hydrogen with electric boosting align with EU Green Deal trajectory. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across furnace operations managers, beverage procurement leads at Dutch multinationals, pharmaceutical packaging engineers, and EPR compliance officers. Belgian Federal Public Service Health enforcement records, Dutch Rijksdienst voor Ondernemend Nederland waste recovery reports, and EU ECHA substance restriction databases provided regulatory validation. Bottom-up production capacity assessments and top-down end-use demand estimates were triangulated against furnace operating rate disclosures.
Segment-level modeling addressed product type, end-use application, glass feedstock category, and distribution channel across the analysis window. CAGRs were derived from production volume trajectories indexed to EPR compliance thresholds and carbon border adjustment phase-in schedules. Forecast inputs incorporated furnace rebuild cycle timing, pharmacopeial certification pipeline visibility, and Rotterdam port logistics cost indices.
Caveats apply where natural gas price volatility, Nordic sand supply disruption, or accelerated regulatory recycled content mandates could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Uzbekistan Container Glass Market
Glass Packaging
Middle East and Africa Pharmaceutical Glass Packaging Market
Glass Packaging
United Kingdom Container Glass Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Global Glass Bottles and Containers Market