
 Bagging Machine Market | 2026-2036
Bagging Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Bagging Machine Market Analysis
Biodegradable polymer films are decoupling bagging machine economics from conventional polyethylene cost cycles. Syntegon Technology leverages its vertical integration into servo-driven sealing systems to command premium positioning in pharmaceutical cleanroom applications. ULMA Packaging anchors its competitiveness through extensive customization capabilities for fresh produce formats across Iberian and Latin American operations. Ishida Co., Ltd. differentiates via precision weighing integration that reduces giveaway ratios in granular product lines.
A bagging machine is an automated or semi-automated packaging system that forms, fills, and seals flexible pouches or bags using heat-sealing jaws, form-fill-seal collars, and programmable logic controllers managing film tension and product dosing. These systems process rollstock films at speeds from 30 to 200 cycles per minute depending on product density and bag geometry, serving industries where shelf-ready packaging, portion control, and contamination prevention are critical. Horizontal bagging configurations retain dominance in bakery and confectionery flows where product fragility demands gentle handling through pillow-pack or gusseted formats. Pneumatic technology segments face margin compression as electronic servo architectures displace air-cylinder actuation for cleaner operation and tighter seal repeatability. The liquid application category is attracting engineering investment as spouted pouch formats displace rigid containers in personal care and household chemical segments.
FDA cGMP guidelines and EU MDR traceability requirements are elevating validation documentation burdens for pharmaceutical bagging installations, while REACH compliance on film substrates is redirecting R&D budgets toward mono-material sealant layers. OSHA lockout/tagout standards and EU Machinery Directive safety protocols are extending machine design cycles and inflating engineering costs for North American and European OEMs. Stakeholders must monitor how packaging Extended Producer Responsibility frameworks in Germany, France, and Italy reshape film specification requirements and retrofit demand for existing installed bases.
Market Dynamics
Food & Beverage processors are expanding automated bagging lines to meet throughput targets while the EU Green Deal tightens packaging waste rules, pushing converters toward recyclable film-compatible equipment and reshaping capital allocation across the value chain.
Growth Catalysts
- EU Green Deal packaging mandates:The framework's Extended Producer Responsibility requirements are forcing converters to retrofit lines for mono-material films, generating replacement demand for seal-compatible machinery across German and French plants.
- Pharmaceutical serialization requirements:FDA cGMP and EU MDR traceability rules are elevating validation documentation burdens, driving premium demand for cleanroom-validated bagging systems with integrated track-and-trace modules.
- Servo-driven actuation:Electronic servo architectures are displacing pneumatic systems in high-throughput applications, delivering tighter seal repeatability and cleaner operation that pharmaceutical and dairy processors prioritize.
Market Restraints
- Engineering cost inflation:OSHA lockout/tagout standards and EU Machinery Directive safety protocols are extending machine design cycles and inflating development costs for North American and European OEMs.
- Film substrate compliance costs:REACH restrictions on multi-layer sealant chemistries are redirecting R&D budgets toward mono-material alternatives, compressing margins for equipment makers dependent on legacy film specifications.
- Steel and aluminum price volatility:Input cost swings for frame construction materials are destabilizing quoted equipment pricing and eroding backlog certainty for mid-cap machinery builders.
Strategic Opportunities
- Spouted pouch liquid formats:Personal care and household chemical segments are displacing rigid containers with flexible spouted pouches, creating white space for liquid-dedicated bagging lines with precision dosing heads.
- Biodegradable polymer film compatibility:Equipment retrofits enabling processing of PLA and starch-based films offer first-mover positioning as Italian and German retailers mandate sustainable packaging.
- Central European machinery exports:German OEMs are capturing rising demand from Polish and Czech packaging plants modernizing lines for EU single-market compliance.
Industry Challenges
- Validation timeline compression:Pharmaceutical installations face elongated FAT/SAT protocols under FDA cGMP guidelines, stretching project delivery schedules and working capital cycles.
- Legacy system integration friction:Brownfield food plants struggle to synchronize new servo-driven baggers with existing SCADA and MES architectures without custom middleware development.
- Mono-material seal engineering:Equipment designers lack standardized test protocols for heat-seal performance on novel recyclable substrates, delaying product certification and commercial rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bagging Machine Market |
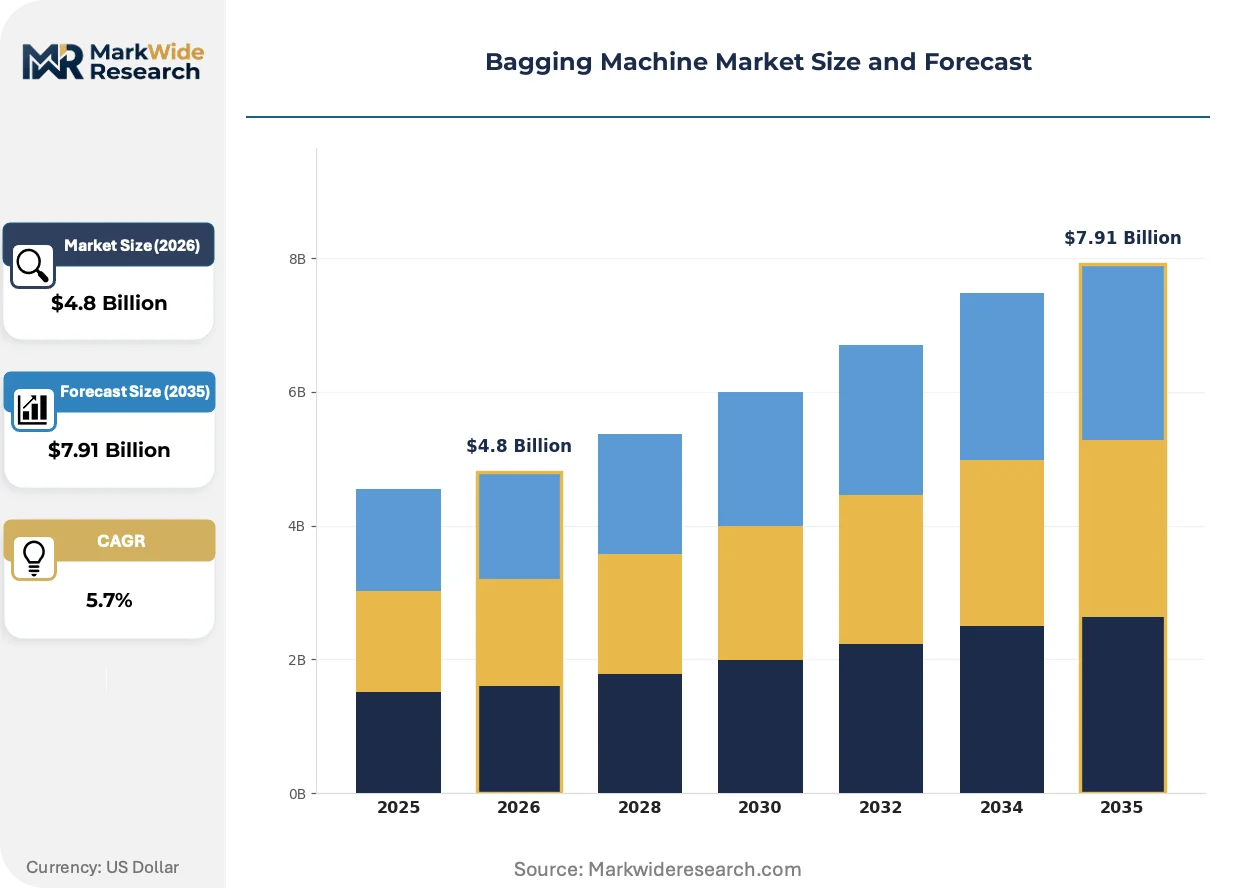
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Bagging, Horizontal Bagging, Automatic Bagging, Semi-Automatic Bagging End User: Food & Beverage, Pharmaceuticals, Chemicals, Personal Care Technology: Pneumatic, Mechanical, Electronic, Manual Application: Granular, Powder, Liquid, Solid |
| Companies Covered | Syntegon Technology, Bosch Packaging Technology, Tetra Pak International, BEUMER Group, Autobag (Sealed Air), PAC Machinery, ULMA Packaging, Ishida Co., Ltd., GEA Group Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bagging Machine Market Emerging Trajectories
Active developments across three vectors are compressing equipment replacement cycles and redefining competitive differentiation in bagging machinery.
Vision-guided robotic pick-and-place modules are integrating with form-fill-seal collars to handle irregular product geometries previously excluded from automated lines. Bakery and fresh produce processors in Iberian operations are adopting these configurations to reduce manual feeding stations. The technology is integrating previously separate handling and sealing operations into unified cells that cut floor-space requirements and labor touchpoints.
REACH compliance on film substrates is redirecting engineering resources toward heat-seal system redesigns compatible with mono-material sealant layers. Industrial consequence includes accelerated obsolescence of legacy jaw designs optimized for multi-layer polyethylene structures. Pharmaceutical and food verticals in Germany and France are responding with pilot programs testing equipment retrofits against forthcoming packaging waste framework deadlines.
Outcome-based service contracting is displacing traditional break-fix maintenance arrangements in large-scale dairy and snack processing installations. Equipment utilization guarantees and uptime-based fee structures are replacing component-margin service models. This shift is most visible in North American and German operations where processor procurement functions centralize vendor performance metrics under total cost of ownership frameworks.
Bagging Machine Market Segmentation
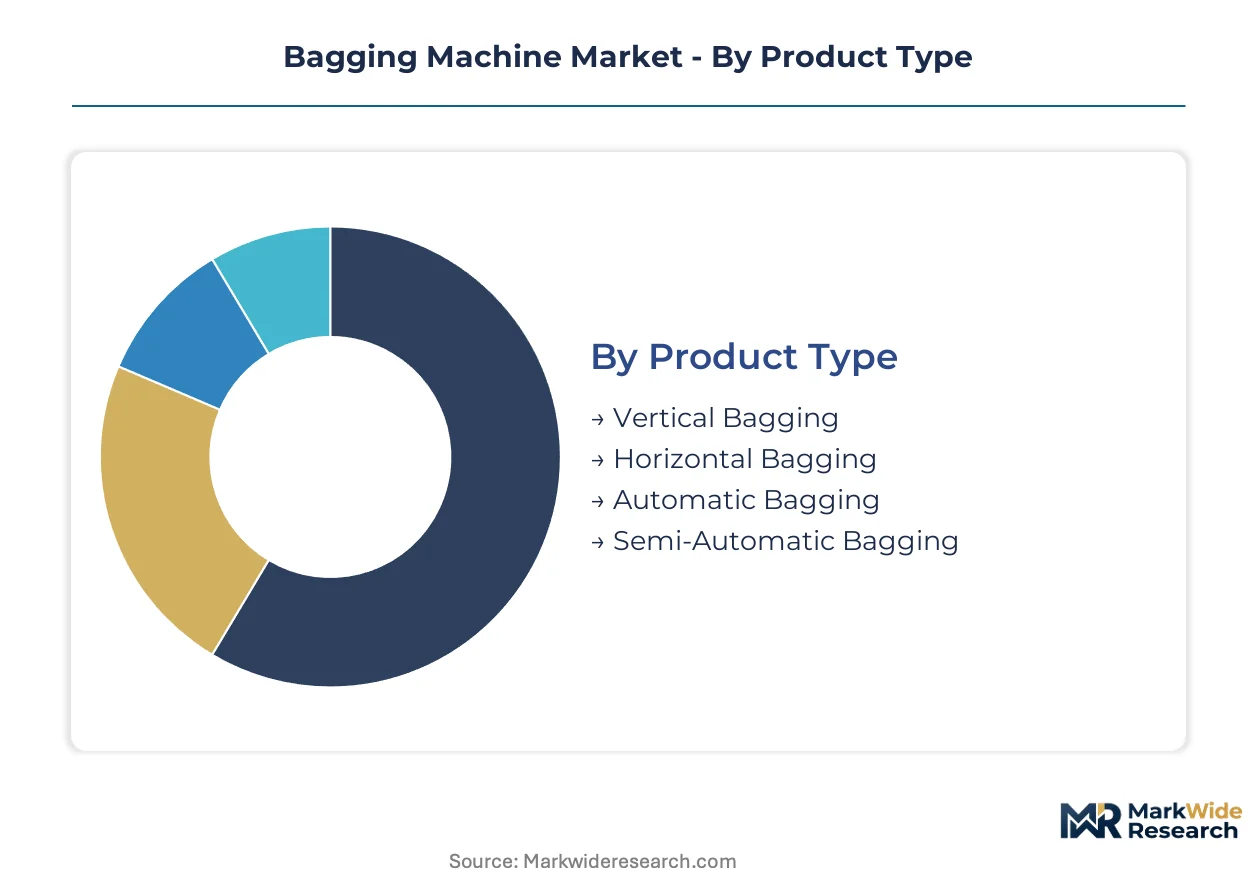
Bagging machine procurement patterns diverge sharply between high-volume commodity processors seeking throughput optimization and precision-oriented sectors prioritizing validation documentation. Equipment specification varies by product fragility, contamination risk, and film substrate compatibility requirements.
Product Type:
Horizontal configurations dominate premium bakery and confectionery lines where gentle handling commands price premiums, while vertical systems anchor high-throughput snack and frozen food operations.
- Horizontal Bagging:Pillow-pack and gusseted formats utilize form-fill-seal collars with reduced drop heights to preserve product integrity. Demand concentrates in Iberian bakery clusters and German confectionery exporters where EU Green Deal packaging mandates are accelerating mono-material film retrofits.
- Vertical Bagging:Gravity-fed product streams achieve cycle speeds exceeding 150 per minute for dense granular materials. Polish and Czech packaging plants are modernizing vertical lines to meet EU single-market compliance, driving German OEM export volumes.
- Automatic Bagging:Servo-driven sealing architectures with integrated PLCs manage film tension across variable product densities.
- Semi-Automatic Bagging:Operator-fed configurations serve mid-cap processors with batch flexibility requirements and limited capital budgets.
Mature deployment sits with Horizontal Bagging in established European confectionery. Newer deployment is concentrated in Automatic Bagging as pharmaceutical and dairy processors eliminate pneumatic actuation.
End User:
Food & Beverage processors account for baseline volume demand, while pharmaceutical installations generate premium pricing through validation complexity and cleanroom requirements.
- Food & Beverage:Automated lines handle portion-controlled packaging for shelf-ready retail formats. German and French plants are retrofitting equipment for recyclable film compatibility under Extended Producer Responsibility frameworks.
- Pharmaceuticals:FDA cGMP and EU MDR traceability rules mandate integrated track-and-trace modules with exhaustive FAT/SAT documentation. Cleanroom-validated systems command substantial price premiums over standard food-grade configurations.
- Chemicals:Corrosion-resistant sealing jaws and explosion-rated electrical enclosures process aggressive formulations.
- Personal Care:Spouted pouch formats are displacing rigid containers, requiring liquid-dedicated lines with precision dosing heads.
Procurement intensity runs highest in Pharmaceuticals where regulatory compliance extends design cycles. Food & Beverage delivers the steepest expansion trajectory as automation replaces manual feeding stations.
Technology:
Electronic architectures are displacing legacy pneumatic systems in applications where seal repeatability and contamination control justify capital premiums.
- Electronic:Servo motors deliver positional accuracy within 0.1 millimeters for heat-seal jaw alignment. Pharmaceutical and dairy processors in North America and Germany prioritize electronic actuation to eliminate compressor oil contamination risks.
- Pneumatic:Air-cylinder systems retain installed base dominance in legacy snack processing lines but face margin compression from maintenance-intensive compressor infrastructure.
- Mechanical:Cam-driven linkages serve cost-sensitive markets with limited product changeover requirements.
- Manual:Foot-pedal or hand-lever operation persists in artisanal food production and small-batch chemical compounding.
Technology migration favors Electronic systems in new pharmaceutical installations. Pneumatic retention is strongest in brownfield food plants with amortized compressor infrastructure.
Application:
Granular and solid applications anchor current installed base, while liquid formats are attracting disproportionate engineering investment.
- Liquid:Spouted pouch processing requires precision dosing heads and specialized film tension control to prevent seal contamination. Personal care and household chemical segments in North America are driving format conversion from rigid containers.
- Granular:Precision weighing integration reduces giveaway ratios in snack and ingredient packaging. Ishida's load-cell configurations dominate high-value granular lines where portion accuracy directly impacts margin.
- Powder:Dust containment systems and nitrogen flush capabilities address oxidation sensitivity in pharmaceutical and food ingredients.
- Solid:Irregular product geometries increasingly integrate vision-guided robotic pick-and-place modules with form-fill-seal collars.
Application complexity peaks with Liquid formats requiring novel seal engineering. Solid handling is gaining share fastest through robotic integration that expands automation to previously excluded product shapes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for bagging machinery concentrates in Germany, where machinery exports to Central European packaging plants are accelerating. Food and beverage processors across multiple geographies are retrofitting automated lines to meet throughput targets while navigating tightening packaging waste regulations.
Germany
Pharmaceutical serialization requirements under EU MDR rules are driving premium demand for cleanroom-validated systems with integrated track-and-trace modules. The EU Green Deal's Extended Producer Responsibility framework is forcing converters toward mono-material film-compatible equipment. Machinery builders in Bavaria and Baden-Württemberg are capturing rising export orders from Polish and Czech plants modernizing for EU single-market compliance.
United States
FDA cGMP guidelines are elevating validation documentation burdens for pharmaceutical bagging installations, stretching project delivery schedules. OSHA lockout/tagout standards are extending machine design cycles and inflating engineering costs for domestic OEMs. Dairy and snack processing operations in the Midwest and California's Central Valley are centralizing procurement under total cost of ownership frameworks that prioritize uptime-based service contracting.
China
Domestic food processors are expanding automated bagging capacity to replace manual feeding stations in high-volume snack and frozen food operations. The country's national packaging standards are tightening film substrate specifications, redirecting equipment R&D toward recyclable-compatible seal systems. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta are scaling vertical bagging lines for dense granular materials at cycle speeds exceeding 150 per minute.
France
EU Green Deal packaging mandates are accelerating pilot programs testing equipment retrofits against forthcoming waste framework deadlines. REACH compliance on multi-layer sealant chemistries is compressing margins for equipment makers dependent on legacy film specifications. Fresh produce processors in the Provence-Alpes-Côte d'Azur region are adopting vision-guided robotic pick-and-place modules to reduce labor touchpoints in irregular product handling.
Japan
Precision weighing integration in granular product lines is reducing giveaway ratios for high-value ingredient packaging. The country's national pharmaceutical regulator is enforcing traceability requirements that mirror EU MDR standards, driving demand for validated cleanroom systems. Industrial machinery specialists in the Chubu region around Nagoya are advancing servo-driven sealing architectures that displace pneumatic actuation in contamination-sensitive applications.
Bagging Machine Market Vendor Landscape
Capacity expansion dominates the current landscape as established fabricators scale servo-driven production lines to capture pharmaceutical and dairy processor demand. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with packaging divisions, specialized machinery pure-plays with vertical integration into sealing systems, and regional fabricators serving cost-sensitive emerging markets. M&A activity and technology licensing agreements represent the dominant competitive moves, with larger groups acquiring niche servo-control specialists to consolidate electronic actuation expertise.
Among Germany-based industrial groups, GEA Group Aktiengesellschaft and BEUMER Group occupy positions anchored in diversified process engineering portfolios. Syntegon Technology exemplifies the specialized pure-play archetype through its captive supply of servo-driven sealing systems. These three entities represent distinct competitive positioning vectors: conglomerate scale, component integration depth, and application-specific engineering focus.
| Leading Market Players |
|---|
| Syntegon Technology |
| Bosch Packaging Technology |
| Tetra Pak International |
| BEUMER Group |
| Autobag (Sealed Air) |
| PAC Machinery |
| ULMA Packaging |
| Ishida Co., Ltd. |
| GEA Group Aktiengesellschaft |
| Others |
Supply Flow & Price Mechanics
Servo-driven sealing architectures are simultaneously compressing pneumatic system margins and concentrating production capability among German and Japanese component specialists with captive motor-controller manufacturing. This technological displacement reshapes cost economics across equipment tiers while tightening supply access for mid-cap builders lacking backward integration into motion-control subsystems.
Pricing Analysis
Volume-driven food-grade configurations trade at compressed margins against pharmaceutical cleanroom-validated systems capturing substantial premiums through FAT/SAT documentation bundling. Price differentiation hinges on EU MDR traceability certification and servo-actuation precision grades. Cost compression in mid-tier pneumatic equipment is intensifying as steel and aluminum input volatility destabilizes quoted pricing. Brownfield food processors exhibit highest price sensitivity; pharmaceutical procurement functions prioritize total cost-of-ownership metrics over upfront capital outlay.
Supply Chain Analysis
Precision servo motor supply rests on German and Japanese industrial automation specialists with in-house encoder manufacturing. Heat-seal jaw alloys draw from Swedish specialty steel producers and Chinese tungsten carbide fabricators. Single-source vulnerability concentrates in high-resolution linear encoder chips subject to export control restrictions. Distribution runs through machinery builders' direct sales organizations and specialized packaging equipment distributors serving regional processor clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Extended Producer Responsibility framework transforms packaging equipment procurement into a compliance-driven capital allocation decision, elevating retrofit-capable OEMs with validated mono-material film handling into sustainable competitive positions.
For Market Incumbents: Cement market position through captive production of servo-driven sealing controllers and accelerated certification of recyclable-film-compatible jaw designs. Emerging competition from Chinese vertical bagging specialists with cost-optimized electronic architectures threatens mid-tier snack processing accounts. Prioritize R&D investment in liquid-format spouted pouch dosing heads where application complexity sustains margin protection. For New Entrants and Emerging Players: Begin with biodegradable polymer film retrofit services for Italian and German food processors facing retailer-mandated packaging deadlines. Personal care liquid bagging offers the most penetrable white space, with precision dosing head engineering representing a defensible specialization angle against generalized equipment portfolios. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking packaging automation exposure. Long-term viability favors pure-plays with demonstrated FDA cGMP validation track records and installed base density in pharmaceutical verticals. Watch German OEM export order backlogs to Polish and Czech plants as early indicator of Central European modernization cycle strength.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-System Backward Integration | Captive motor-controller production insulates margin from supply disruption and enables customization for pharmaceutical cleanroom specifications. |
| Mono-Material Film Certification | Validated heat-seal performance on recyclable substrates unlocks retrofit demand from German and French converters under EU Green Deal timelines. |
| Liquid-Format Dosing Head Development | Precision spouted pouch engineering captures format conversion demand from North American personal care and household chemical segments. |
| Central European Export Expansion | Machinery sales to Polish and Czech packaging plants modernizing for EU single-market compliance drive volume growth for German OEMs. |
| Outcome-Based Service Contracting | Uptime-guarantee fee structures align vendor incentives with processor operational metrics and displace break-fix maintenance models. |
Methodological Framework
Trade association filings, EU regulatory guidance documents, and machinery builder technical specifications formed the secondary backbone, cross-referenced against primary interviews with plant engineers, OEM procurement teams, aftermarket service directors, and packaging line operators. Bottom-up equipment shipment analysis triangulated with top-down processor capital expenditure tracking across food, pharmaceutical, and chemical verticals.
Historical trendline analysis of installed base replacement cycles and retrofit demand patterns informed projection modeling across product type, technology architecture, end-use industry, application format, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market boundary conditions, incorporating film substrate compliance cost trajectories and servo-actuation adoption curves as industry-specific inputs.
Underlying measurement precision varies by segment; pharmaceutical and food-grade equipment categories carry tighter precision than emerging liquid-format applications. Forecasts reflect documented assumptions on regulatory implementation timelines and material substitution rates. Trade policy shifts, commodity price spikes, and validation protocol changes represent specific risk factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Lipstick Molding Machines Market
Packaging Machinery
Cutter-Box Packaging Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Global Tissue Paper Converting Machines Market
Packaging Machinery
Tray Former Machines Market
Packaging Machinery
Blind Box Machine Market
Packaging Machinery
Thermoform Fill Sealing Machine Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Pallet Strapping Machines Market
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Plastic Vacuum Forming Machinery Market
Packaging Machinery
Flow Pack Machine Market