
 Vacuum Chamber Packaging Machines Market | 2026-2036
Vacuum Chamber Packaging Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Chamber Packaging Machines Market Analytics
A shift from single-source to multi-source component procurement is realigning how vacuum chamber packaging machine builders manage supply risk. MULTIVAC anchors its position through captive manufacturing of sealing systems and control modules. Sealed Air competes on film and equipment integration, leveraging its polymer science base to bundle consumables with hardware. ULMA Packaging differentiates through modular architectures that let food processors reconfigure lines without full replacement.
Vacuum chamber packaging machines are enclosed systems that extract air from a sealed chamber before heat-sealing flexible film around a product, typically achieving residual oxygen levels below one percent to inhibit microbial growth and oxidation. Industrial units operate at cycle speeds exceeding sixty packages per minute with chamber depths reaching two hundred millimeters for bulk meat and cheese blocks. Rollstock configurations lead capital deployment among high-volume protein processors due to continuous-web efficiency and lower per-package film cost. Gas flushing technology is gaining fastest in ready-meal and pharmaceutical applications where modified atmosphere packaging extends stability windows. Tabletop units occupy the long tail of artisanal and small-batch cosmetics segments where batch flexibility outweighs throughput.
FDA food contact substance notifications and USDA FSIS sanitation standards shape machine design for North American meat and poultry applications, mandating open-frame construction and tool-free disassembly for daily washdown. EU MDR and CE marking requirements for pharmaceutical packaging lines enforce validated seal integrity testing and electronic batch recording. Stakeholders must weigh regulatory divergence against platform standardization as they allocate R&D budgets across regional product variants.
Market Dynamics
Automated packaging lines in protein processing facilities are forcing equipment replacement cycles as labor costs rise and throughput requirements tighten. This structural pressure is compressing the upgrade window for vacuum chamber systems across North American and European food manufacturing clusters.
Growth Catalysts
- EU Green Deal packaging mandates:Sustainable film requirements are accelerating equipment upgrades as processors retrofit lines for biodegradable barrier materials.
- Ready-meal segment expansion:Modified atmosphere packaging demand is pulling gas-flushing vacuum chamber installations into prepared food facilities.
- USDA FSIS sanitation protocols:Tool-free disassembly requirements are driving replacement of legacy open-frame designs in poultry processing plants.
Market Restraints
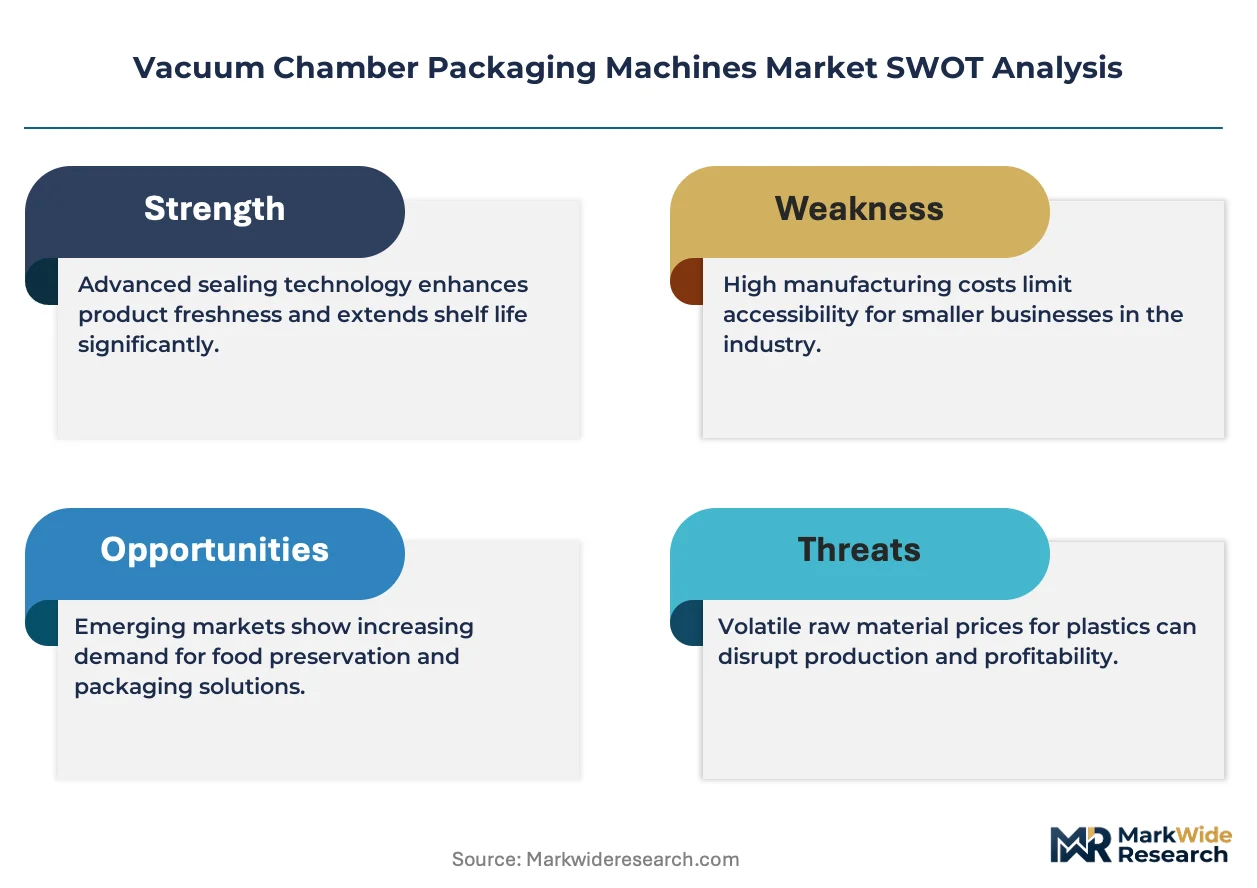
- Stainless steel input volatility:Chamber fabrication costs fluctuate with nickel and chromium price swings, squeezing OEM margins on fixed-price contracts.
- Sealing component supply concentration:Precision silicone gasket manufacturing clusters in Germany create single-source vulnerability for mid-tier builders.
- Pharmaceutical validation timelines:EU MDR seal integrity testing extends qualification periods, delaying revenue recognition on capital sales.
Strategic Opportunities
- Artisanal cosmetics tabletop segment:Small-batch flexibility requirements in skincare manufacturing create white space below industrial throughput thresholds.
- India cold-chain infrastructure buildout:FSSAI food safety modernization is opening vacuum packaging demand in dairy and spice processing.
- IoT-enabled predictive maintenance convergence:Sensor-embedded chambers bundled with uptime guarantees are displacing traditional service contracts.
Industry Challenges
- Electromechanical technician scarcity:Servo-driven sealing systems require skills bridging mechanical and software competencies that vocational pipelines undersupply.
- Legacy PLC integration friction:Retrofitting new vacuum chambers into 1990s-era packaging lines demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Chamber Packaging Machines Market |
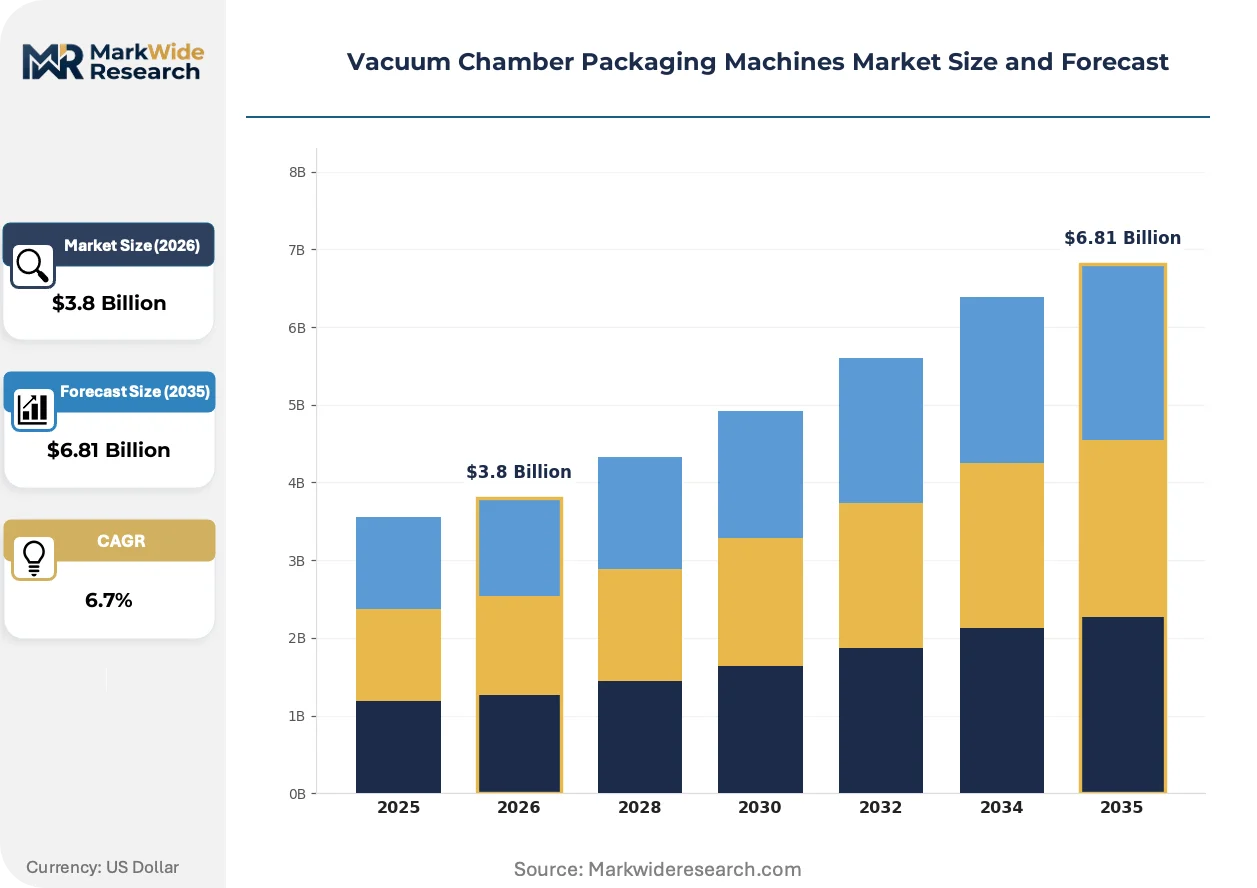
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop, Industrial, Rollstock, Automatic End User: Food Processing, Pharmaceuticals, Electronics, Cosmetics Technology: Heat Sealing, Cold Sealing, Gas Flushing, Multi-Vacuum Capacity: Small Scale, Medium Scale, Large Scale, Custom |
| Companies Covered | Henkelman, Boss Vakuum, AMAC Technologies, MULTIVAC, Sealed Air, Supervac, Minipack, ULMA Packaging, Syntegon Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Chamber Packaging Machines Market Evolving Landscape
Packaging equipment architecture is pivoting toward modular reconfigurability as food processors demand line flexibility without full capital replacement. This shift is compressing product development cycles and rewiring competitive advantage around software-enabled adaptation.
Brushless DC servo motors are replacing pneumatic actuators in high-speed sealing stations. Premium protein processors in the United States and Germany are specifying all-electric drive trains for precision control and energy recovery. This technology convergence is electrifying competitive positioning as OEMs with captive motor control expertise capture specification authority.
REACH restrictions on per- and polyfluoroalkyl substances are forcing film formulation changes that alter heat-sealing parameters. Chamber OEMs must recalibrate temperature profiles and dwell times to accommodate new barrier layers without compromising seal integrity. Pharmaceutical packaging lines under EU MDR face the steepest revalidation burden as they migrate to PFAS-free films.
Food processors are unbundling after-sales service from capital purchases and contracting directly with regional maintenance specialists. This channel disintermediation is compressing OEM service margins while opening independent technician networks in Midwest US meatpacking corridors and Bavarian dairy clusters. Equipment financing structures are adapting to separate hardware from uptime performance obligations.
Vacuum Chamber Packaging Machines Market Segmentation
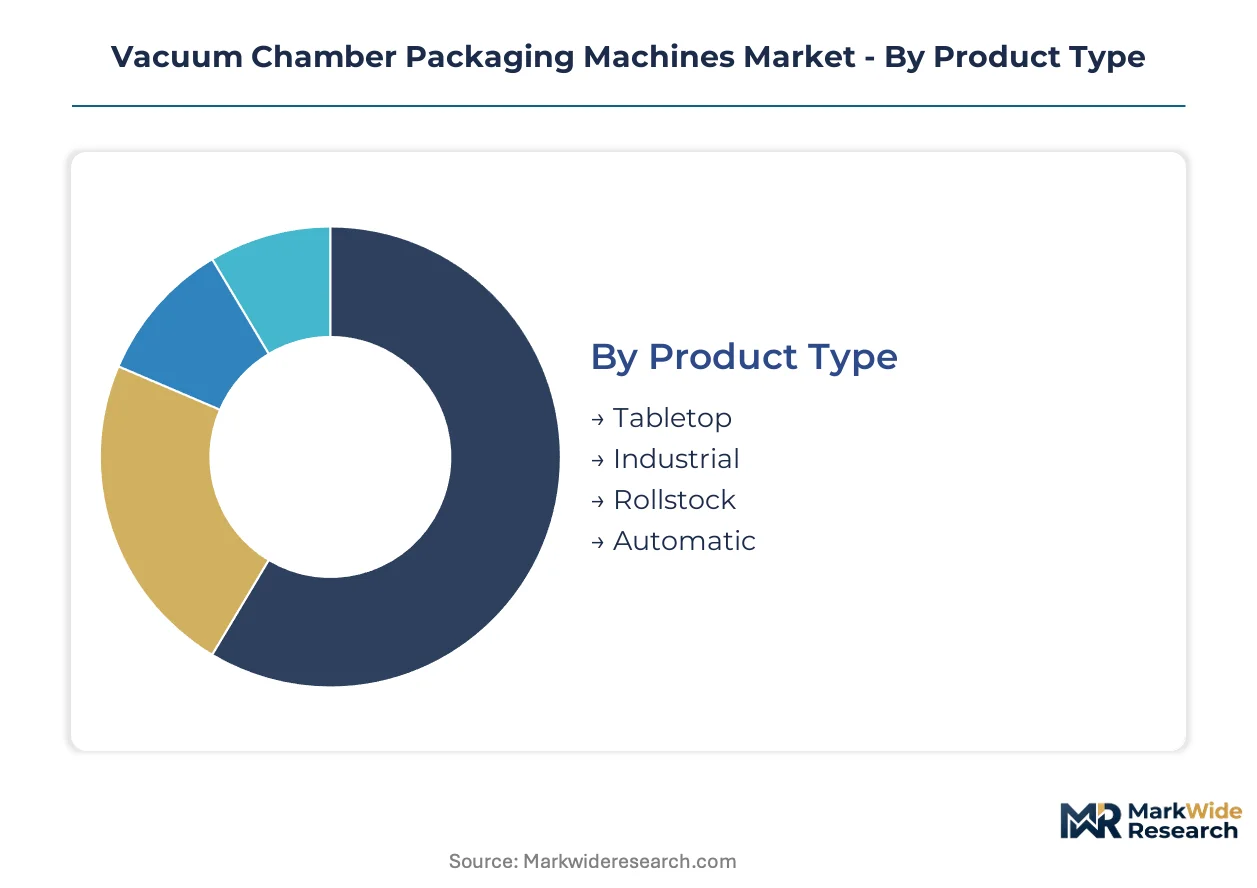
Vacuum chamber packaging machines serve divergent operational regimes—from artisanal cosmetics batching to pharmaceutical cleanroom validation—requiring segmentation that maps technical specifications to regulatory burden tiers. Equipment buyers prioritize chamber depth, cycle speed, and seal integrity protocols based on end-use contamination sensitivity and throughput economics.
Product Type:
FDA 21 CFR Part 177 food contact notifications govern Industrial and Rollstock units destined for meat and dairy facilities, while Tabletop systems fall under lighter OSHA electrical safety scrutiny unless deployed in pharmaceutical compounding.
- Industrial:Enclosed stainless-steel chambers with 200mm+ depth accommodate bulk protein blocks and cheese wheels. Demand concentrates in German meatpacking corridors where USDA-equivalent hygiene mandates drive replacement of open-frame legacy systems. CE marking and EU MDR compliance extend qualification timelines for pharmaceutical deployments.
- Rollstock:Continuous-web configurations achieve 60+ packages per minute with lower per-unit film cost. High-volume US poultry processors specify these for breast portioning lines where gas-flushing integration extends shelf life. REACH-compliant barrier film compatibility now dominates specification discussions.
- Tabletop:Compact 300-400mm footprint units serve small-batch cosmetics manufacturers in Bavarian skincare clusters.
- Automatic:Servo-driven sealing stations with PLC integration target mid-tier food processors automating previously manual operations.
Leading the category by volume: Rollstock. Growing fastest: Industrial units with gas-flushing modules.
End User:
Customer procurement authority varies sharply—pharmaceutical quality units validate seal integrity per EU MDR Annex I, while food processors prioritize USDA FSIS tool-free disassembly for daily sanitation.
- Food Processing:Protein, dairy, and ready-meal facilities drive capital deployment. German processors under EU Green Deal sustainable film mandates retrofit chambers for biodegradable barrier compatibility. US poultry plants replace legacy open-frame designs to meet updated FSIS sanitation protocols.
- Pharmaceuticals:Sterile packaging lines require validated seal integrity testing and electronic batch recording per EU MDR. Swissmedic and EMA inspections enforce chamber surface finish specifications below Ra 0.8 micrometers.
- Electronics:Moisture-sensitive semiconductor components demand residual oxygen below 0.1% with nitrogen backfill.
- Cosmetics:Artisanal skincare manufacturers in Midwest US urban clusters specify tabletop units for batch flexibility.
Food Processing commands the largest installed base. Pharmaceuticals show the steepest expansion trajectory as biologics packaging demand accelerates.
Technology:
Sealing methodology selection determines energy consumption, cycle speed, and compatibility with next-generation PFAS-free barrier films.
- Heat Sealing:Impulse and constant-temperature bar systems dominate protein packaging. Temperature profile recalibration is now mandatory as REACH restrictions force migration from fluorinated film chemistries.
- Gas Flushing:Modified atmosphere packaging extends ready-meal stability windows through nitrogen and carbon dioxide mixtures. US prepared food facilities lead installation growth.
- Cold Sealing:Pressure-sensitive adhesive systems protect heat-sensitive pharmaceuticals and electronics.
- Multi-Vacuum:Pulsed evacuation cycles achieve sub-0.5% residual oxygen for oxygen-sensitive APIs and high-value dried fruits.
Heat Sealing retains dominant share. Gas Flushing gains share fastest on ready-meal segment expansion.
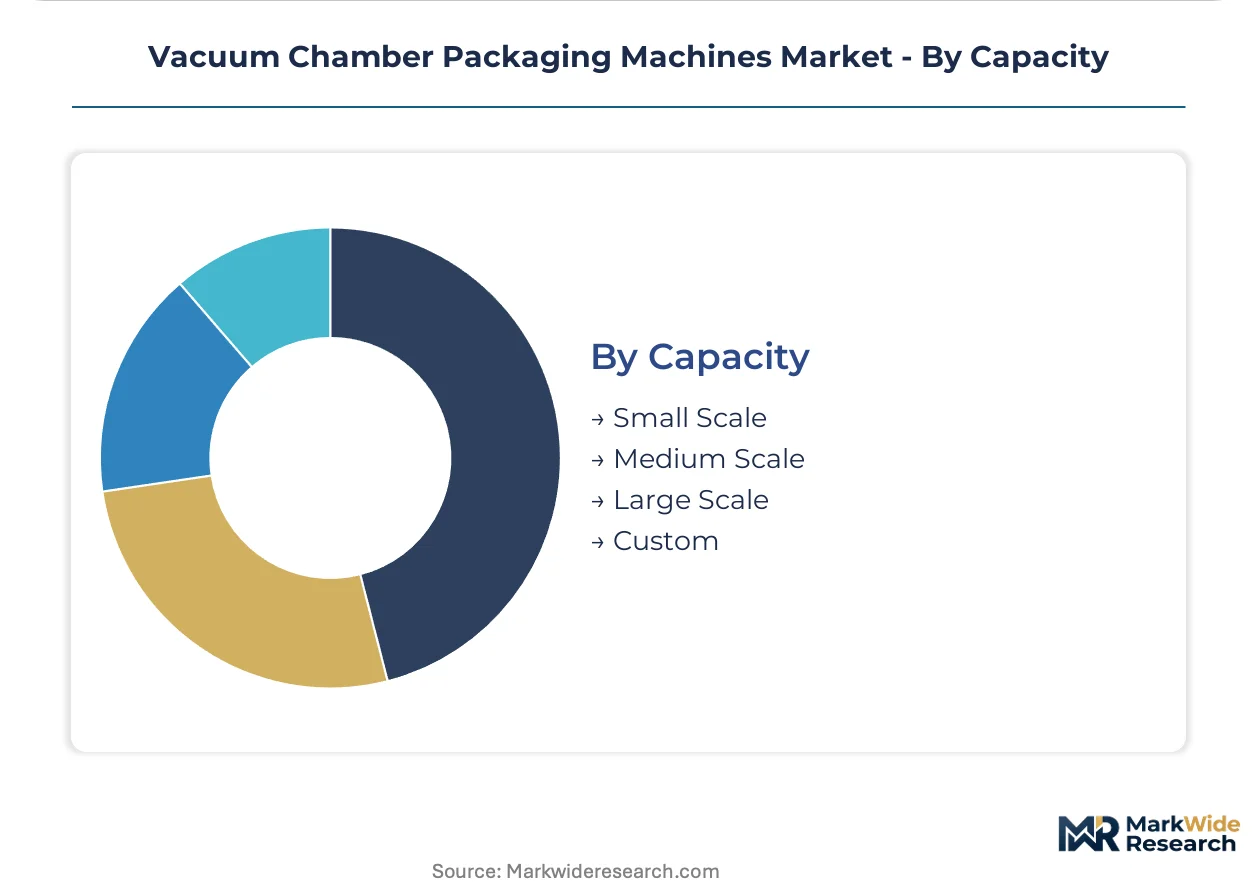
Capacity:
Scale selection correlates with labor cost pressure and line integration complexity rather than absolute production volume alone.
- Large Scale:Integrated lines exceeding 100 packages per minute serve US and German protein processing conglomerates. These configurations demand captive maintenance teams and compressed air infrastructure.
- Medium Scale:30-60 package per minute systems target regional dairy processors in Bavaria and Wisconsin upgrading from manual operations.
- Small Scale:Standalone chambers serve startup cosmetics brands and specialty spice packers in Indian FSSAI modernization zones.
- Custom:Pharmaceutical contract manufacturers specify chamber geometries accommodating irregular biologic container shapes.
Medium Scale leads current procurement volume. Custom configurations climb fastest on pharmaceutical outsourcing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision gasket manufacturing clusters supply sealing components to vacuum chamber builders worldwide. Nickel and chromium price volatility in stainless steel markets reshapes regional equipment procurement timelines. Food safety modernization programs across multiple jurisdictions accelerate replacement cycles for legacy open-frame systems.
United States
USDA FSIS sanitation protocols mandate tool-free disassembly for daily washdown in poultry processing plants. The Food Safety Modernization Act enforcement tightens equipment qualification standards. Midwest meatpacking corridors in Iowa and Nebraska retrofit aging vacuum chambers to meet updated hygiene mandates.
Germany
EU Green Deal packaging mandates accelerate equipment upgrades for biodegradable barrier film compatibility. REACH restrictions on PFAS chemicals force recalibration of heat-sealing temperature profiles. Bavarian dairy clusters around Munich and cheese processing facilities in Allgäu specify modular chamber architectures for line flexibility.
India
FSSAI food safety modernization opens vacuum packaging demand in dairy and spice processing sectors. The Production Linked Incentive scheme for food processing infrastructure subsidizes capital equipment imports. Gujarat dairy cooperatives and Tamil Nadu spice export zones deploy medium-scale chambers for shelf-life extension.
China
Dual carbon goals drive energy-efficient servo-driven sealing system adoption in protein processing facilities. SAMR food contact material standards align with international hygiene protocols. Yangtze River Delta ready-meal manufacturers integrate gas-flushing modules for modified atmosphere packaging expansion.
Switzerland
Swissmedic pharmaceutical packaging inspections enforce chamber surface finish specifications below Ra 0.8 micrometers. EU MDR seal integrity testing requirements extend qualification timelines for capital sales. Basel-area biologics contract manufacturers specify custom chamber geometries for irregular container shapes.
Vacuum Chamber Packaging Machines Market Competitive Landscape
Capacity expansion dominates the current landscape as OEMs respond to compressed upgrade windows in protein processing facilities. The vendor base organizes around three tiers: diversified packaging conglomerates with captive film supply, specialized machinery builders with modular platform expertise, and regional fabricators serving artisanal segments. Strategic differentiation converges on two vectors: backward integration into sealing component manufacturing, and geographic expansion through regional assembly partnerships.
Among diversified packaging conglomerates, MULTIVAC and Sealed Air occupy positions anchoring premium-tier specification authority through integrated consumables bundling. ULMA Packaging exemplifies the modular architecture specialist tier, while Henkelman represents the regional precision fabricator archetype serving below-industrial throughput thresholds. These three patterns illustrate how competitive positioning stratifies across captive supply control, software-enabled reconfigurability, and batch-flexibility specialization.
| Leading Market Players |
|---|
| Henkelman |
| Boss Vakuum |
| AMAC Technologies |
| MULTIVAC |
| Sealed Air |
| Supervac |
| Minipack |
| ULMA Packaging |
| Syntegon Technology |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators in Bavaria and Wisconsin anchor regional pricing discipline through captive service networks and long-tenured customer relationships. Their refusal to unbundle maintenance contracts from capital sales creates a buffer against commodity-driven price erosion in stainless steel chamber fabrication.
Pricing Analysis
Warranty and service-bundling configurations now dominate specification negotiations, with premium-tier OEMs bundling predictive maintenance sensors while mid-tier competitors strip service to hit capital expenditure targets. Three-tier pricing structure across premium, standard, and economy levels separates MULTIVAC's integrated consumables bundles from ULMA's modular hardware and Henkelman's tabletop specialists. Cost compression in economy-tier tabletop units is intensifying because regional fabricators absorb nickel price volatility rather than pass through to artisanal cosmetics buyers. Protein processors in Iowa and Nebraska show lowest price sensitivity due to FSIS-mandated replacement urgency, while Indian dairy cooperatives under PLI subsidies negotiate hardest on upfront capital.
Supply Chain Analysis
Dual-sourcing requirements from US poultry processors and German meatpacking conglomerates now mandate qualified secondary suppliers for precision silicone gaskets and brushless DC servo motors. Geographic supply concentration centers on Germany for sealing components, China for servo drive assemblies, and Italy for stainless steel chamber fabrication. Raw material dependencies rest on nickel-chromium alloy pricing for chamber construction, precision-milled aluminum for sealing bars, and rare-earth magnets for motor systems. Single-source vulnerability in German gasket manufacturing clusters creates qualification bottlenecks extending procurement timelines. Distribution runs through OEM-direct sales for large-scale integrated lines and regional equipment distributors for mid-tier automatic units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision silicone gasket manufacturing capacity in Southern Germany operates at effective utilization ceilings, propping pricing power for chamber OEMs with captive sealing supply.
For Market Incumbents: Cement specification authority by deepening backward integration into servo motor control systems and sensor-embedded chamber architectures. Defend against disintermediation threats from independent maintenance networks in Midwest US meatpacking corridors by binding customers through uptime-guarantee financing structures rather than traditional service contracts. For New Entrants and Emerging Players: Capture white space in Indian FSSAI modernization zones where medium-scale dairy and spice processors lack qualified local service infrastructure. Target tabletop configurations for artisanal cosmetics manufacturers in Bavarian skincare clusters below industrial throughput thresholds. Lead with IoT-enabled predictive maintenance bundles to differentiate against legacy OEMs selling hardware-only. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular architecture specialists with reconfigurable platform expertise in German precision manufacturing clusters. Long-term viability hinges on software-enabled adaptation capability rather than pure hardware fabrication scale. Watch REACH enforcement timelines on PFAS-free film compatibility as the inflection signal for revalidation service demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sealing Components | German OEMs with captive gasket supply capture specification authority from multi-source dependent rivals. |
| IoT-Enabled Predictive Maintenance Bundling | Sensor-embedded chambers displace traditional service contracts in US protein processing facilities. |
| Modular Platform Reconfigurability | Software-enabled line adaptation without full replacement compresses development cycles for Bavarian dairy processors. |
| Regional Assembly Partnership Expansion | Local fabrication in India PLI zones reduces import duty exposure for medium-scale chamber deployments. |
| PFAS-Free Film Compatibility Certification | EU MDR validation for barrier layer recalibration opens pharmaceutical requalification service revenue streams. |
Research Methodology
Independent corroboration across equipment procurement directors at US poultry processors, maintenance heads in German meatpacking facilities, and FSSAI compliance officers in Indian dairy cooperatives underwrites the qualitative findings. Primary interviews with plant engineers, OEM sales executives, and aftermarket service specialists combined with secondary validation from SEC 10-K filings of diversified packaging conglomerates, EU MDR submission databases, and USDA FSIS equipment qualification guidance. Bottom-up triangulation across regional installation data and top-down reconciliation against stainless steel input cost indices anchored volume estimates.
Comparable-period anchoring to pre-pandemic capital expenditure baselines and post-FSIS-mandate replacement waves structured the forecast window. Segmentation dimensions modeled include product type, end-use industry, technology configuration, and capacity tier across the projection horizon. CAGRs derived from equipment shipment trajectories weighted by regional regulatory enforcement intensity and film formulation transition timelines. Forecast inputs incorporated nickel-chromium price volatility bands and REACH compliance deadline clustering effects.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal packaging mandate acceleration and India PLI scheme extension decisions. Deviation in German silicone gasket manufacturing capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market
Packaging Machinery
Robotic Carton Loading Machine Market
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Filling Machinery Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
Thermal Film Laminating Machines Market
Packaging Machinery
Corrugated Box Printer Slotter Machine Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Tray Packing Machine Market
Packaging Machinery
Sliding Injection Molding Machine Market
Packaging Machinery
Post Press Machine Market