
 Wicketed Bagging Machines Market | 2026-2036
Wicketed Bagging Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Wicketed Bagging Machines Market Analytics
Aftermarket service revenue is tilting toward predictive maintenance contracts and remote diagnostics platforms. Robert Bosch GmbH leverages its industrial software backbone to offer condition-monitoring subscriptions for installed wicketed bagging lines. GEA Group anchors its aftermarket position through regionally stocked spare-part hubs and certified technician networks. HAVER & BOECKER differentiates by specializing in heavy-duty wicketed systems for mineral and chemical applications, competing on durability metrics rather than speed.
Wicketed bagging machines are automated packaging systems that draw pre-opened bags from a wicketed stack, fill them with product, and seal the package through mechanical, pneumatic, or electronic actuation cycles operating at speeds typically exceeding 30 bags per minute. These machines serve industrial and commercial operations requiring high-throughput, consistent bag presentation for food, agricultural, and chemical products. Fully automatic electronic systems command the premium tier as food processors replace pneumatic models to meet traceability mandates, while semi-automatic units retain share in small-batch chemical and agricultural operations where capital constraints limit automation investment. Biodegradable packaging compatibility represents the fastest-growing configuration requirement, driven by European supermarket chain procurement standards and North American state-level plastic reduction policies.
FDA food-contact material regulations and USDA equipment sanitation standards shape machine design specifications for North American food processing deployments, while REACH and EU F-Gas Regulation compliance in Europe restricts pneumatic refrigerant choices and mandates material disclosure for plastic contact surfaces. ISO 9001 quality management and CE marking frameworks govern market access across developed economies, with emerging market entrants facing certification gaps that incumbent European and North American suppliers exploit. Stakeholders must monitor evolving state-level plastic packaging bans in the United States and pending EU packaging waste regulation amendments that could accelerate biodegradable film adoption timelines.
Market Dynamics
Food processors across developed economies are retiring pneumatic wicketed bagging lines in favor of electronic control architectures that satisfy traceability mandates from FDA and EFSA. This hardware refresh cycle concentrates capital deployment among multi-site bakery and protein operations.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on hydrofluorocarbon refrigerants in pneumatic systems accelerate electronic actuator adoption in Central European packaging clusters.
- Biodegradable film mandates:Supermarket procurement standards in Germany and France require wicketed machines compatible with PLA and starch-based films.
- Protein processing automation:North American poultry and red meat facilities deploy high-speed wicketed lines to replace manual bagging stations.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress margins for machine builders sourcing hygienic contact surfaces.
- Servo motor supply concentration:Japanese and German motion control suppliers create procurement bottlenecks for electronic wicketed system manufacturers.
- Legacy pneumatic infrastructure:Installed base of compressed air systems in Midwestern US food plants slows electronic upgrade cycles.
Strategic Opportunities
- Indian food processing expansion:FSSAI modernization and cold chain investment create first-mover advantage for wicketed bagging OEMs establishing local assembly.
- Remote diagnostics convergence:Integration of IoT sensors with predictive maintenance platforms enables subscription revenue models for aftermarket service.
- US state plastic bans:California and New York legislation accelerates demand for biodegradable-compatible machine configurations.
Industry Challenges
- Controls engineering talent scarcity:Shortage of PLC programmers and motion control specialists delays commissioning timelines for electronic wicketed installations.
- Multi-certification burden:Simultaneous FDA, USDA, and CE compliance requirements extend product development cycles for universal machine platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wicketed Bagging Machines Market |
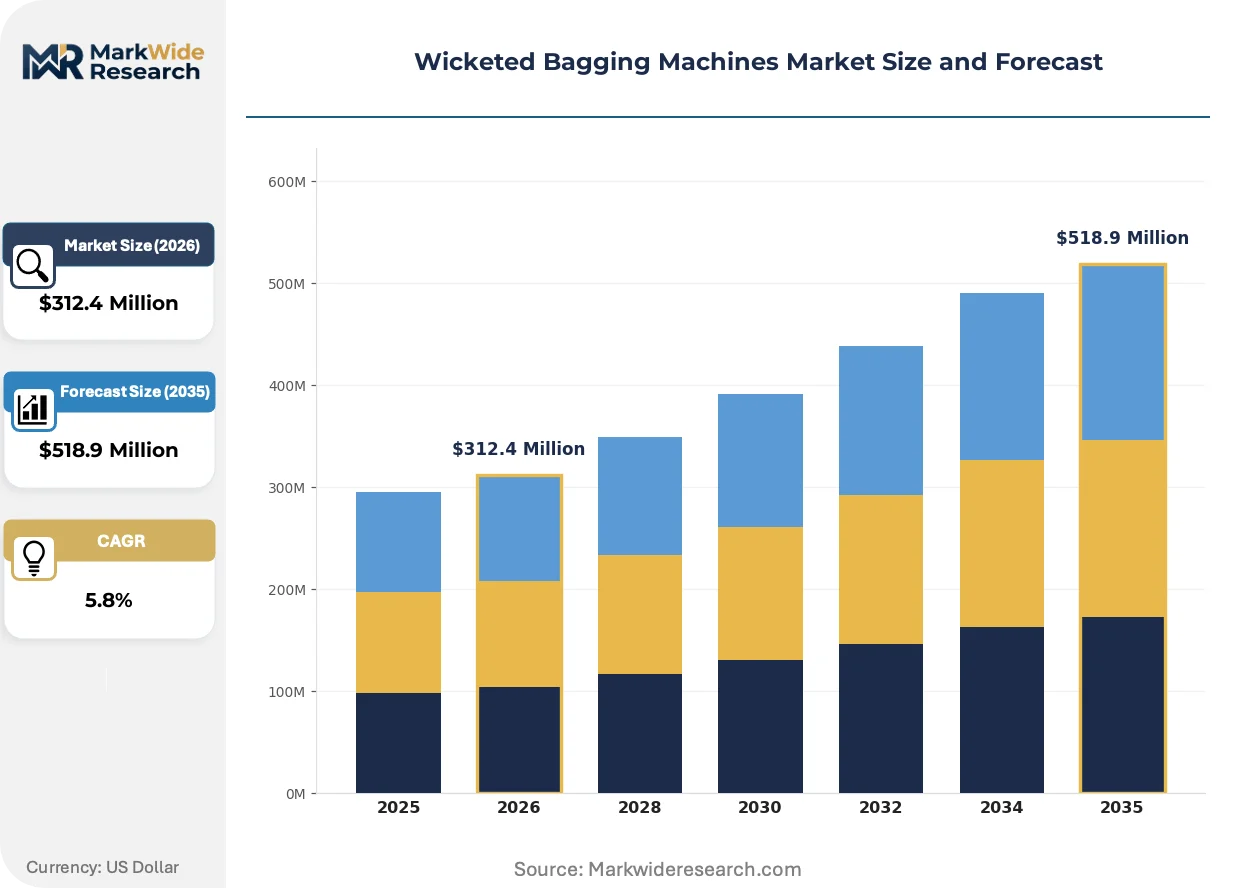
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Semi-Automatic, Fully Automatic Technology: Mechanical, Pneumatic, Electronic, Hydraulic End User: Agriculture, Food Processing, Chemicals, Pharmaceuticals Packaging Type: Plastic, Paper, Composite, Biodegradable |
| Companies Covered | WeighPack Systems, Paxiom Group, Euro Machinery, Triangle Package Machinery Company, All-Fill, Robert Bosch GmbH, NEWTEC, GEA Group, HAVER & BOECKER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wicketed Bagging Machines Market Evolving Landscape
Electronic control architectures are supplanting pneumatic actuation as the dominant wicketed bagging technology. Three developments are compressing the transition timeline and reshaping supplier capabilities.
Brushless servo motors with integrated safety encoders are rendering obsolete traditional pneumatic cylinder-and-valve configurations in high-throughput bakery applications. European OEMs are shipping electronic wicketed lines as standard configurations, while North American retrofit demand accelerates among multi-plant snack food operators. The shift compresses maintenance intervals and enables real-time cycle data capture for traceability compliance.
REACH substance disclosure requirements are forcing material specification changes across European wicketed machine supply chains. Manufacturers must document plastic contact surface compositions and certify absence of SVHC candidates above threshold limits. Food-contact belt and seal materials face particular scrutiny, driving substitution toward silicone and PTFE alternatives in German and Benelux installations.
Outcome-based service contracts are displacing traditional break-fix maintenance arrangements in large-scale protein processing deployments. Equipment users in the US Midwest and Southeast now specify uptime guarantees and remote diagnostic access as procurement criteria. This preference shift favors suppliers with industrial software backbones over pure mechanical specialists.
Wicketed Bagging Machines Market Segmentation
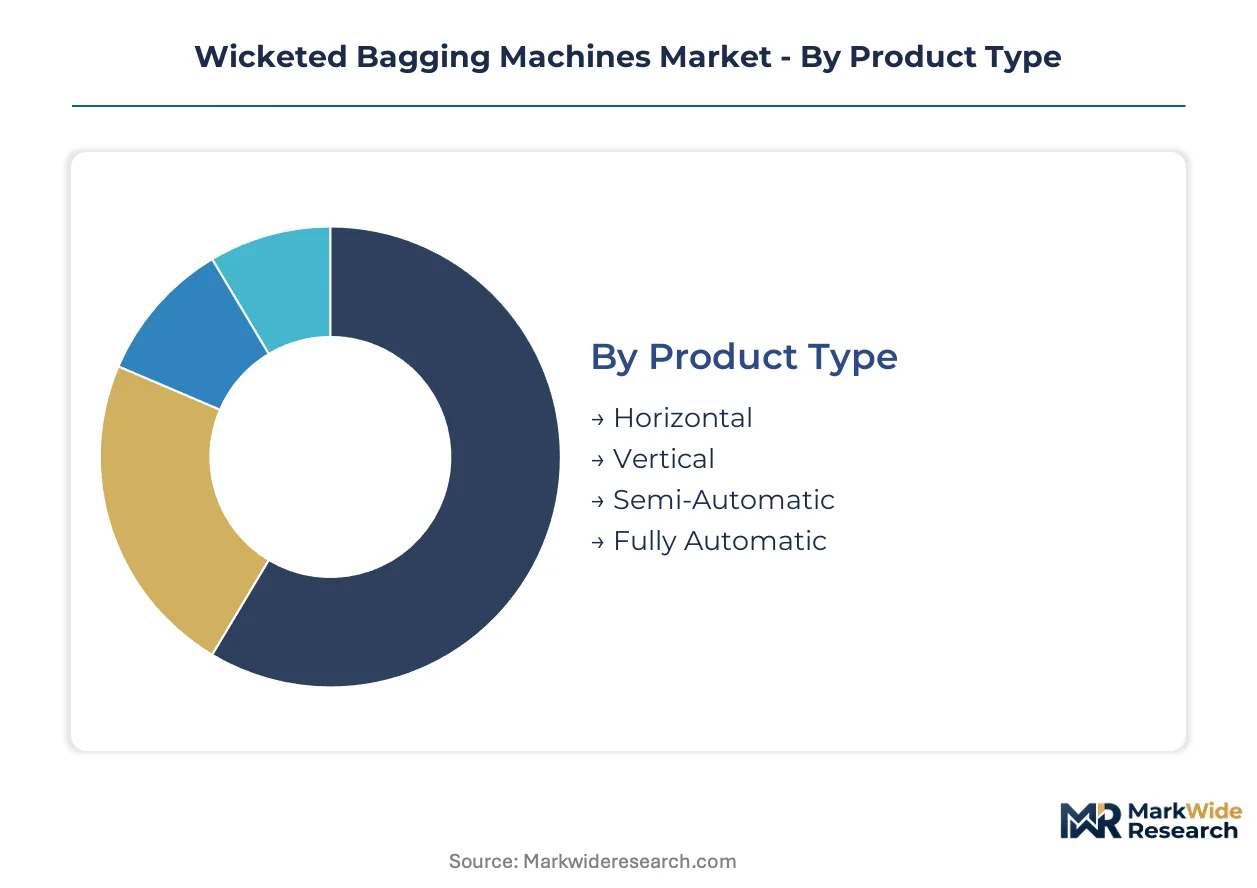
Wicketed bagging machine segmentation reflects divergent capital deployment patterns across food safety tiers, chemical hazard classes, and biodegradable film compatibility requirements. Procurement specifications vary sharply between protein processors demanding electronic traceability and agricultural cooperatives prioritizing throughput economics.
Product Type:
The use-case spectrum spans high-volume continuous operations requiring synchronized filling and intermittent batch processing where flexibility dominates speed requirements.
- Fully Automatic:Electronic servo architectures enable cycle speeds exceeding 60 bags per minute with integrated checkweighing and metal detection. North American poultry processors deploy these lines to satisfy USDA-FSIS traceability mandates while minimizing labor exposure to cold-chain environments.
- Horizontal:Side-seal configurations accommodate irregular product geometries in frozen bakery and prepared meal applications. German snack food manufacturers favor horizontal wicketed systems for their compatibility with high-clarity film structures required by supermarket private-label specifications.
- Vertical:Gravity-fed filling suits free-flowing granular products in agricultural seed and feed operations where dust containment takes priority over speed optimization.
- Semi-Automatic:Operator-present bag presentation reduces capital outlay for small-batch chemical repackagers and specialty food startups with irregular production schedules.
Established volume favors Fully Automatic; emerging adoption favors Semi-Automatic among contract packagers serving fragmented specialty food brands.
Technology:
Cost tier stratification separates premium electronic architectures from legacy pneumatic installations with divergent maintenance economics and regulatory compliance trajectories.
- Electronic:Brushless servo motors with integrated safety PLCs deliver programmable motion profiles and real-time cycle data logging. REACH F-Gas Regulation restrictions on hydrofluorocarbon refrigerants accelerate electronic displacement of pneumatic systems in EU-27 packaging clusters.
- Pneumatic:Compressed air actuation retains installed base dominance in Midwestern US meat processing plants where legacy infrastructure amortization delays capital refresh cycles despite higher energy intensity.
- Mechanical:Cam-driven timing mechanisms persist in mineral and aggregate bagging where environmental contamination tolerance exceeds precision requirements.
- Hydraulic:High-force actuation serves heavy-gauge woven polypropylene applications in chemical and construction material sectors.
Procurement momentum concentrates in Electronic for traceability-mandated segments; Mechanical retains cost advantage in non-food bulk commodity handling.
End User:
Application severity dictates stainless steel grade specifications, washdown protocol compatibility, and validation documentation requirements across divergent regulatory jurisdictions.
- Food Processing:USDA equipment sanitation standards and FDA food-contact material regulations mandate 316L stainless steel contact surfaces with sanitary clamp connections. Protein and dairy operations drive specification intensity for clean-in-place compatibility.
- Chemicals:ATEX and IECEx hazardous area classifications require explosion-proof electrical enclosures and conductive grounding paths for solvent and powder handling applications.
- Agriculture:Seed treatment and grain bagging prioritize throughput over precision, with pneumatic systems dominating cooperatives and regional elevators.
- Pharmaceuticals:cGMP validation protocols and FDA 21 CFR Part 11 electronic records requirements constrain supplier qualification to established OEMs with documented IQ/OQ/PQ capabilities.
Margin concentration favors Food Processing; steepest expansion trajectory favors Chemicals as specialty polymer and additive packaging automation accelerates.
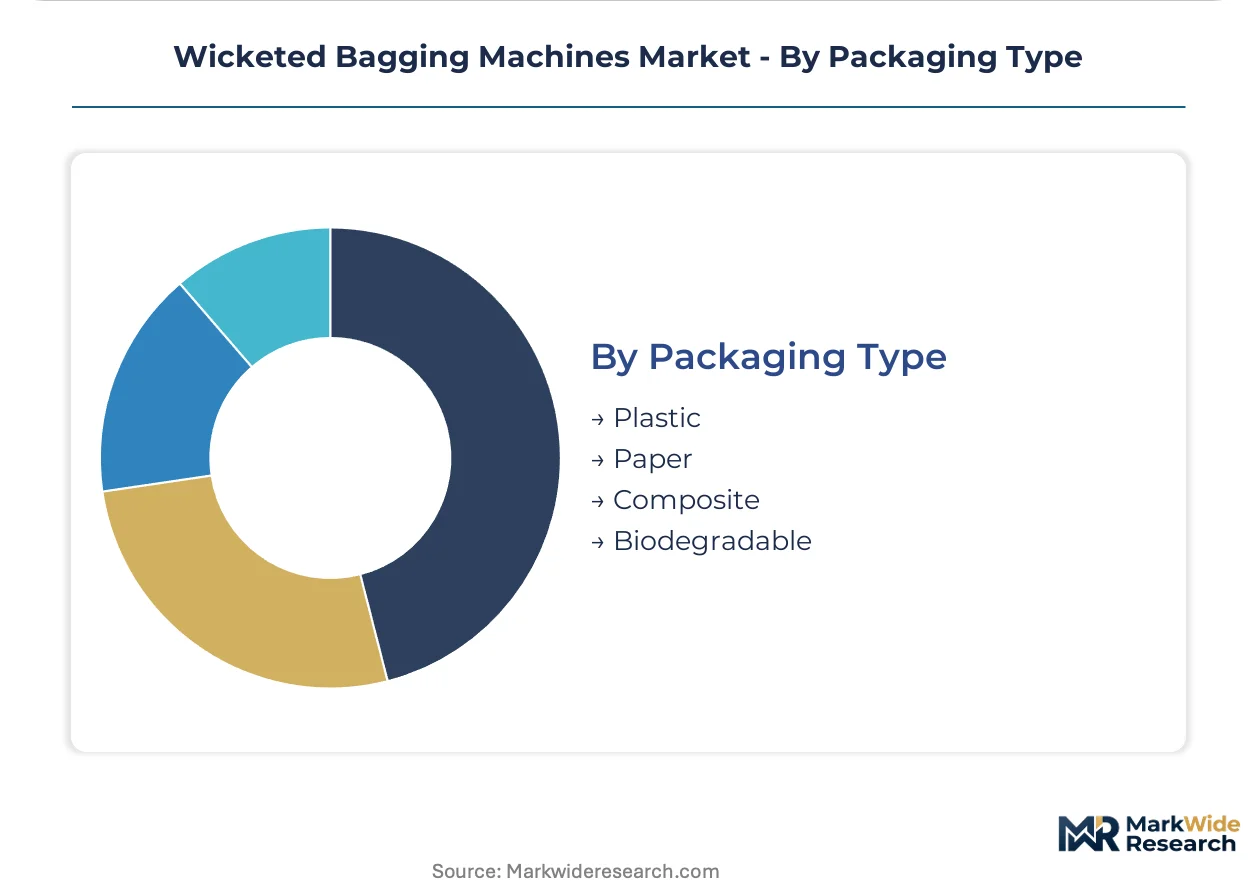
Packaging Type:
Customer procurement standards and state-level policy vectors are restructuring film compatibility requirements faster than machine replacement cycles can absorb.
- Biodegradable:PLA and starch-based films demand modified sealing temperature profiles and dwell time extensions. California and New York plastic packaging bans compel retrofit investments in heat-seal calibration and tension control systems.
- Plastic:Conventional polyethylene and polypropylene structures retain cost advantage in export-oriented agricultural markets with limited extended producer responsibility enforcement.
- Paper:Fiber-based wicketed bags gain traction in European bakery and produce segments as supermarket chains eliminate single-use plastic targets.
- Composite:Multi-layer barrier structures with aluminum or EVOH cores serve oxygen-sensitive snack and pharmaceutical applications requiring hermetic seal integrity.
Near-term volume anchors in Plastic; policy-driven conversion favors Biodegradable as EU packaging waste regulation amendments advance through legislative process.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for wicketed bagging machines diverges sharply across geographies. European protein processors absorb premium pricing for electronic traceability systems, while Indian agricultural cooperatives prioritize capital efficiency over speed specifications.
Germany
Protein processing automation and bakery line modernization drive procurement intensity. The EU F-Gas Regulation restricts hydrofluorocarbon refrigerants in pneumatic systems, pushing packagers toward electronic actuator architectures. Stuttgart and Munich engineering clusters host OEM development centers serving Central European packaging automation demand.
United States
Poultry and red meat facilities deploy high-speed wicketed lines to replace manual bagging stations in cold-chain environments. USDA equipment sanitation standards and FDA food-contact material regulations mandate 316L stainless steel contact surfaces with sanitary clamp connections. Midwestern meatpacking corridors in Iowa and Nebraska concentrate installed base expansion.
India
FSSAI modernization and cold chain investment create first-mover positioning for wicketed bagging OEMs establishing local assembly. The PLI scheme for food processing machinery reduces import duty burdens on capital equipment. Maharashtra and Gujarat industrial corridors attract contract packaging investments serving domestic snack food brands.
China
Dual carbon goals accelerate energy efficiency mandates for packaging machinery, favoring servo-driven electronic systems over compressed air infrastructure. GB standards for food machinery safety align with international hygienic design protocols. Yangtze River Delta manufacturing zones concentrate domestic OEM production capacity for export markets.
France
Supermarket procurement standards requiring PLA and starch-based film compatibility reshape machine specification criteria. REACH substance disclosure requirements force material certification documentation across plastic contact surfaces. Lyon and Paris packaging automation clusters serve pan-European dairy and prepared meal processors.
Wicketed Bagging Machines Market Competitive Landscape
Diversified industrial conglomerates and specialized packaging machinery fabricators split the market along capability depth versus portfolio breadth lines. Consolidation pressure concentrates among mid-scale European specialists seeking scale economies in electronic control development. Three archetypes dominate: full-line automation conglomerates with industrial software backbones, regional machinery builders with strong aftermarket technician networks, and niche specialists competing on application-specific durability metrics. Dominant competitive moves include geographic expansion through distribution partnerships and technology licensing agreements for biodegradable film handling systems.
Within the diversified industrial tier, Robert Bosch GmbH and GEA Group exemplify the convergence of mechanical packaging expertise with predictive maintenance software platforms. HAVER & BOECKER occupies a position among heavy-duty application specialists, anchoring the durability-focused segment for mineral and chemical handling requirements. These three entities represent distinct strategic postures: software-enabled service monetization, integrated process line engineering, and extreme-environment mechanical reliability.
| Leading Market Players |
|---|
| WeighPack Systems |
| Paxiom Group |
| Euro Machinery |
| Triangle Package Machinery Company |
| All-Fill |
| Robert Bosch GmbH |
| NEWTEC |
| GEA Group |
| HAVER & BOECKER |
| Others |
Value Network & Pricing Analysis
Japanese and German servo motor suppliers anchor upstream motion control concentration, funneling margin capture toward electronic wicketed system OEMs who bundle predictive maintenance subscriptions into lifetime contracts. Stainless steel grade volatility and certified technician scarcity downstream redistribute pricing power toward aftermarket service tiers with regional spare-part hub coverage.
Pricing Analysis
Predictive maintenance subscriptions and condition-monitoring service contracts drive lifetime value capture for electronic wicketed line OEMs. Three-tier pricing structure across premium electronic traceability systems, mid-tier pneumatic retrofits, and economy mechanical units separates food processors from agricultural cooperatives. Cost compression in stainless steel contact surfaces intensifies because grade 304 and 316 price swings compress builder margins. Small-batch chemical repackagers exhibit highest price sensitivity; multi-site protein processors absorbing USDA compliance costs show lowest.
Supply Chain Analysis
Stainless steel feedstock draws from Chinese, Indonesian, and South African ore processing clusters before European and North American mill finishing. Brushless servo motors rest on Japanese and German motion control supplier concentration; food-contact belts and seals hinge on silicone and PTFE substitution trends under REACH scrutiny. Single-source vulnerability in semiconductor-dependent safety encoder chips threatens electronic system lead times. Distribution runs through OEM-direct regional technician networks and certified third-party aftermarket service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
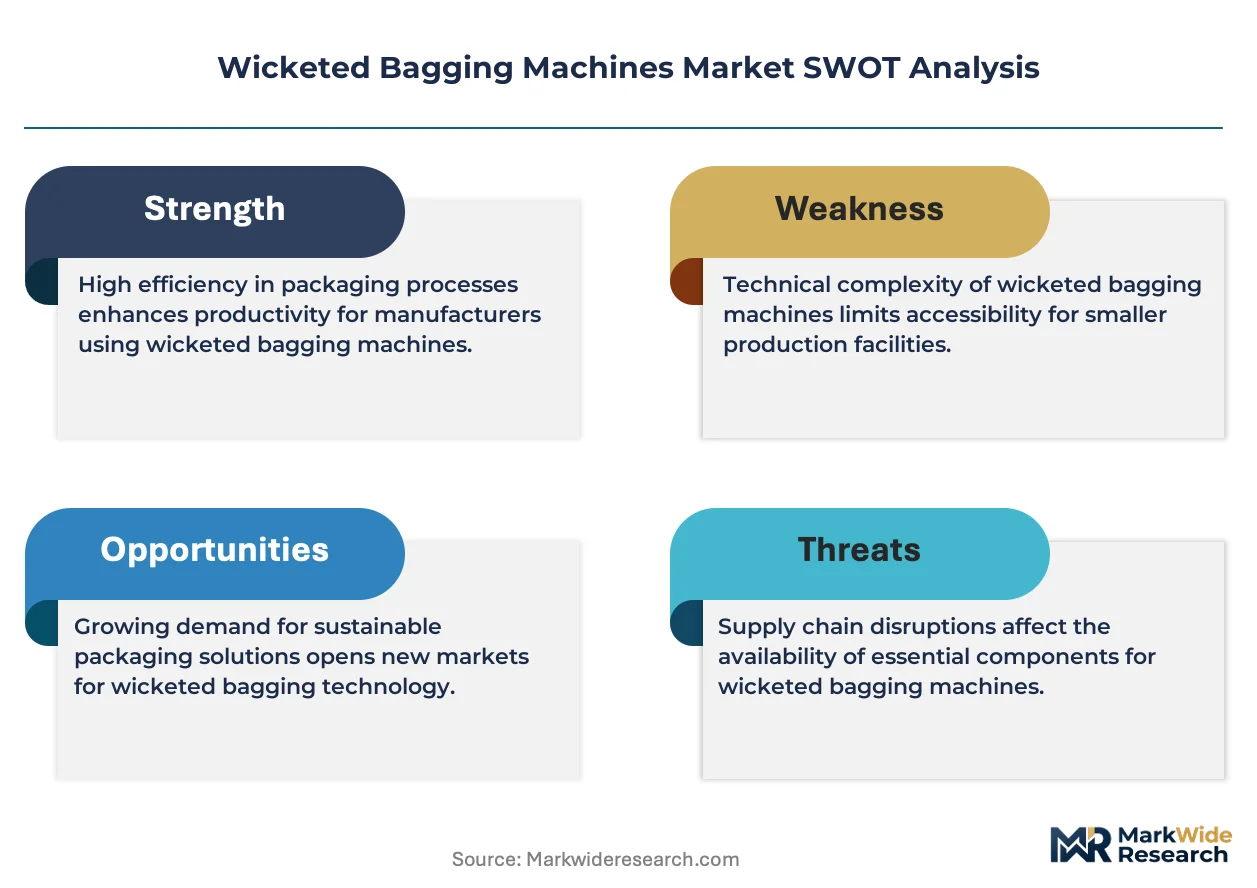
Wicketed bagging machine market fragmentation creates niche capture opportunities as biodegradable film mandates split procurement specifications between PLA-compatible electronic systems and legacy pneumatic infrastructure.
For Market Incumbents: Build predictive maintenance software moats through IoT sensor integration and remote diagnostic platform development. Consolidate regional spare-part hub coverage to defend against emerging OEMs with leaner technician networks. Anchor defensive positioning in FDA 21 CFR Part 11 validation documentation for pharmaceutical segment lock-in. For New Entrants and Emerging Players: Mid-market Indian food processing corridors represent the most penetrable entry point as FSSAI modernization accelerates capital deployment. Specialty chemical contract packagers in Southeast Asia offer second white-space target with lower certification burden than protein processing. Pursue technology licensing partnerships with established biodegradable film handling system developers rather than in-house R&D buildout. For Investors and Strategic Acquirers: Capital is best deployed toward electronic control specialists with documented IQ/OQ/PQ capabilities and installed base expansion runway across protein processing verticals. Long-term viability centers on software-enabled service monetization convergence with hardware durability metrics. Monitor EU packaging waste regulation amendment progression as inflection signal for biodegradable-compatible machine configuration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Film Compatibility Certification | REACH compliance documentation unlocks German and French supermarket procurement channels. |
| Predictive Maintenance Platform Development | Bosch and GEA subscription models demonstrate recurring revenue capture from condition-monitoring data. |
| Regional Spare-Part Hub Establishment | Certified technician density in Midwestern US meatpacking corridors reduces customer downtime exposure. |
| Electronic Actuator Architecture Migration | EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants accelerate pneumatic displacement timelines. |
| Indian Local Assembly Investment | PLI scheme duty reductions position first-mover OEMs for FSSAI modernization contract capture. |
Research Methodology
The analysis maps electronic control architectures, pneumatic legacy installations, and biodegradable film handling configurations, each validated through packaging automation engineers, plant maintenance directors, and aftermarket service heads. Primary interview triangulation with OEM procurement teams and food safety compliance officers combined secondary validation through SEC 10-K filings, EU F-Gas regulatory documentation, and FSSAI modernization circulars. Bottom-up unit deployment estimates and top-down capital expenditure patterns were reconciled across the projection horizon.
Fixed assumptions held stainless steel input cost volatility bands and REACH substance disclosure timelines constant across the modeling period, while biodegradable film adoption curves and electronic traceability mandate enforcement intensity were varied. Segmentation dimensions span automation level, actuation technology, end-use regulatory tier, and film compatibility requirement. CAGRs were derived from installed base replacement cycles and greenfield capacity expansion pipelines. Industry-specific inputs include poultry processing line commissioning data and cold chain infrastructure investment trajectories.
Stress conditions across servo motor supply concentration, grade 316 stainless steel price bands, and EU packaging waste regulation amendment timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against USDA equipment sanitation standard revision schedules and state-level plastic ban legislative tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Automatic Banding Machine Market
Packaging Machinery
Palletizing Machines Market
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
Stacking Machine Market
Packaging Machinery
Precision Dispensing Machine Market
Packaging Machinery
CCL Laminating Machine Market
Packaging Machinery
Bubble Wrap Machine Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Packaging Conveyors Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Screw Capping Machines Market
Packaging Machinery
Thermal Film Laminating Machines Market