
 Global Hand Wrapping Machine Market | 2026-2036
Global Hand Wrapping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hand Wrapping Machine Market Analysis
Third-party logistics providers are reorganizing equipment procurement around semi-automatic hand wrapping machines that bridge manual labor gaps without full automation capital outlays. Lantech leverages its North American manufacturing footprint to sustain rapid fulfillment timelines for regional distributors. Robopac competes through specialized pallet wrapping configurations tailored to irregular load geometries. Muller anchors its position with heat-sealing technology leadership in European food processing corridors.
Hand wrapping machines apply stretch film or shrink film around palletized goods, individual cartons, or bundled products using manual force, mechanical assistance, or motorized film carriage systems with pre-stretch ratios typically ranging from 150% to 300%. These devices secure loads for transit stability, moisture protection, and tamper evidence across warehouse and distribution environments. Semi-automatic wrappers command the largest installed base among product types due to their balance of throughput and capital efficiency, while stretch film wrappers represent the fastest-growing category as pre-stretch technology reduces material consumption per pallet. Food processing end users generate concentrated demand for heat-sealing variants that maintain hygienic barriers, whereas logistics providers prioritize pressure-sealing systems for speed-sensitive dock operations.
FDA regulations on food-contact materials shape film specification requirements for U.S. food processing installations, while EU REACH and RoHS frameworks restrict phthalate-based additives in European-sourced stretch films. OSHA ergonomic standards influence machine design specifications for U.S. warehouse operators, particularly regarding handle height and film carriage weight limits. Stakeholders must monitor evolving bio-based film certification protocols across multiple jurisdictions to anticipate equipment compatibility requirements and avoid stranded asset risk.
Market Dynamics
Warehouse throughput pressures are compressing the viable equipment spectrum toward semi-automatic hand wrapping machines that balance labor substitution with capital restraint, while bio-based stretch film mandates are forcing equipment recalibration across multiple jurisdictions.
Growth Catalysts
- E-commerce logistics expansion:Third-party fulfillment providers in Germany, China, and the United States are scaling palletized freight operations that demand faster film application without full automation capital deployment.
- EU REACH compliance:Phthalate restrictions on stretch film additives are redirecting equipment R&D toward heat-sealing and bio-compatible film carriage systems that maintain seal integrity with alternative chemistries.
- Pre-stretch technology maturation:Film carriage systems achieving 300% pre-stretch ratios are reducing material consumption per pallet, creating operational savings that accelerate replacement cycles in high-volume distribution centers.
Market Restraints
- Steel and aluminum input volatility:Machine frame and carriage component costs fluctuate with commodity metal markets, compressing margin stability for equipment fabricators serving price-sensitive logistics segments.
- Film supply concentration:Specialty stretch film production clusters in select Asian manufacturing zones create geographic dependency risk for European and North American equipment operators seeking qualified material inputs.
- Manual wrapper substitution persistence:Low-cost handheld dispensers retain economic viability in micro-fulfillment and last-mile operations, limiting addressable market expansion for powered equipment categories.
Strategic Opportunities
- India warehouse modernization:BIS certification pathways and PLI scheme incentives for logistics infrastructure are creating first-mover advantage for semi-automatic wrapper suppliers establishing local assembly or distribution partnerships.
- Food processing hygiene mandates:FDA food-contact material specifications and EU EFSA barrier requirements are expanding demand for heat-sealing variants that maintain sanitary enclosures in protein and dairy processing corridors.
- IoT-enabled film monitoring:Integration of consumption sensors with warehouse management systems is creating service-attachment revenue streams for equipment vendors serving data-driven logistics operators.
Industry Challenges
- Ergonomic certification complexity:OSHA handle-height specifications and EU machinery directive safety assessments impose divergent design requirements that fragment product development resources across regulatory jurisdictions.
- Legacy dock equipment integration:Retrofitting semi-automatic wrappers into existing conveyor configurations requires custom mounting fabrication, extending installation timelines and inflating project costs for facility operators.
- Bio-film equipment compatibility:Emerging bio-based stretch films exhibit variable tensile properties that challenge pre-stretch mechanism calibration, demanding iterative testing protocols before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hand Wrapping Machine Market |
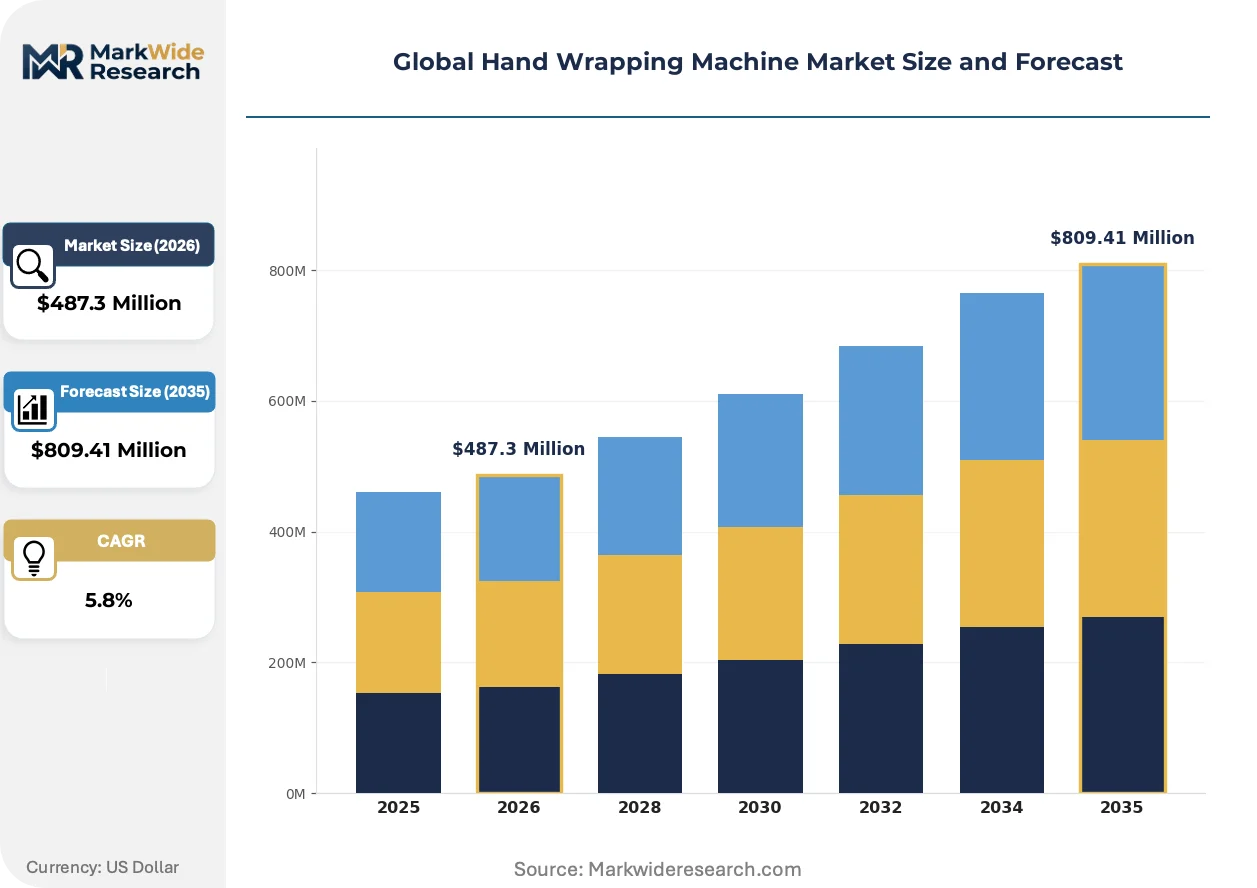
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
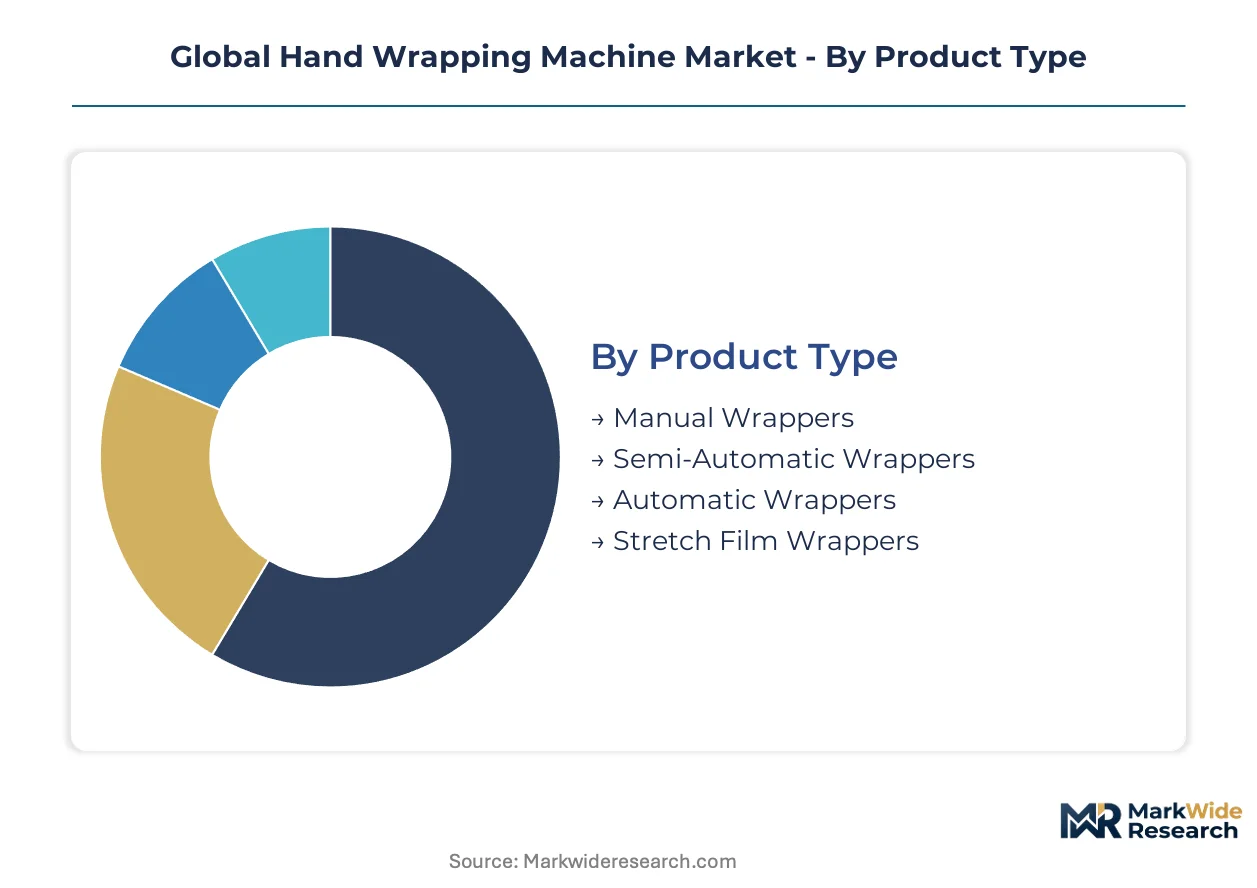
| Segmentation | Product Type: Manual Wrappers, Semi-Automatic Wrappers, Automatic Wrappers, Stretch Film Wrappers End User: Food Processing, Packaging Companies, Logistics Providers, Retail Stores Technology: Heat Sealing, Pressure Sealing, Pallet Wrapping, Hand Stretching Packaging Form: Rolls, Sheets, Bags, Pallets |
| Companies Covered | M.J. Maillis, Lantech, Robopac, TAM, ARPAC, Reiser, Muller, Orion, Nitechiipm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hand Wrapping Machine Market Emerging Trajectories
Equipment design is converging around modularity and sensor integration, with film application technology and regulatory compliance frameworks reshaping competitive differentiation across warehouse and food processing installations.
Pre-stretch film carriage systems are miniaturizing. These motorized units apply mechanical force to elongate stretch film before wrapping, reducing material usage per pallet. Food processing facilities in the United States and Germany are adopting compact carriage configurations that fit within constrained production floor footprints. The technology is miniaturizing equipment dimensions while maintaining throughput rates, enabling deployment in legacy facilities previously excluded from powered wrapper installation.
EU REACH substance restrictions are tightening film additive specifications. The framework limits phthalate-based plasticizers in stretch films sold across European Economic Area markets. Equipment manufacturers serving EU food processing corridors are redesigning heat-sealing components to accommodate bio-based film alternatives with different thermal sealing profiles. German and French packaging equipment distributors report extended qualification timelines as film suppliers reformulate compositions to maintain seal integrity under compliance constraints.
Third-party logistics providers are consolidating equipment procurement around regional distributor networks with rapid parts availability. Large warehouse operators in China and the United States are abandoning direct manufacturer relationships in favor of authorized service partners that bundle equipment, consumables, and maintenance under unified contracts. This channel compression is elevating distributor technical certification requirements while reducing equipment brand visibility in end-user purchasing decisions.
Global Hand Wrapping Machine Market Segmentation
Hand wrapping machine procurement decisions cluster around throughput requirements, labor substitution economics, and film compatibility constraints that vary sharply across end-use environments. Segment boundaries are blurring as semi-automatic systems absorb features from both manual and automatic categories.
Product Type:
Manual wrappers face the most acute substitution pressure from low-cost handheld dispensers in micro-fulfillment operations, while semi-automatic systems defend their position through capital efficiency in mid-volume warehouses.
- Semi-Automatic Wrappers:Motorized film carriage systems with pre-stretch ratios between 150% and 300% reduce material consumption per pallet while preserving operator control. Third-party logistics providers in Germany and the United States concentrate procurement here to bridge labor gaps without full automation capital deployment. OSHA ergonomic standards influence handle height and carriage weight specifications for warehouse installations.
- Stretch Film Wrappers:Pre-stretch technology miniaturization is shrinking equipment footprints for legacy facility retrofitting. Food processing corridors in the United States adopt compact carriage configurations to fit constrained production floors while maintaining throughput rates. EU REACH compliance on film additives is forcing heat-sealing component recalibration for bio-based alternatives.
- Manual Wrappers:Handheld dispensers retain economic viability in last-mile operations with low pallet volumes.
- Automatic Wrappers:Full automation commands premium positioning for high-throughput distribution centers with dedicated conveyor integration.
Semi-automatic wrappers retain volume leadership; stretch film wrappers hold the steepest expansion curve.
End User:
Cost tier stratification separates food processing installations with hygiene mandates from logistics operations prioritizing speed over sanitary enclosure.
- Logistics Providers:Third-party fulfillment operators in China and the United States drive palletized freight scaling that demands faster film application. These users prioritize pressure-sealing systems for dock speed and bundle equipment, consumables, and maintenance under unified distributor contracts.
- Food Processing:Protein and dairy corridors require heat-sealing variants that maintain hygienic barriers under FDA food-contact material specifications. German and French equipment distributors report extended qualification timelines as film suppliers reformulate compositions for EU EFSA barrier compliance.
- Packaging Companies:Contract packagers serve diverse end-use requirements with flexible equipment configurations.
- Retail Stores:Back-of-store operations favor compact semi-automatic units for irregular shipment volumes.
Logistics providers dominate unit shipments; food processing commands the highest average equipment values.
Technology:
Application environment dictates sealing method selection, with thermal and mechanical approaches diverging on speed, hygiene, and film compatibility dimensions.
- Heat Sealing:Thermal bonding systems maintain sanitary enclosures in protein and dairy processing. EU REACH phthalate restrictions are redirecting R&D toward heat-sealing components compatible with bio-based film alternatives exhibiting different thermal profiles.
- Pressure Sealing:Mechanical compression enables rapid dock operations without thermal cycle delays. Logistics providers in China prioritize these systems for throughput-sensitive freight consolidation.
- Pallet Wrapping:Load stabilization configurations address irregular geometries through specialized carriage movement patterns.
- Hand Stretching:Manual force application persists in low-volume operations with minimal capital availability.
Pressure sealing leads logistics adoption; heat sealing maintains the premium technology position.
Packaging Form:
Supply concentration in Asian film manufacturing zones creates geographic dependency risk that equipment operators mitigate through qualified material input diversification.
- Rolls:Continuous film feeds dominate stretch film application with pre-stretch carriage systems. Warehouse operators in Germany and the United States standardize on roll formats for pallet wrapping efficiency.
- Pallets:Unit load containment drives equipment specification for freight stability in e-commerce fulfillment. Indian warehouse modernization under PLI scheme incentives is expanding demand for pallet-focused semi-automatic systems.
- Sheets:Cut-size film formats serve intermittent wrapping needs in retail and light industrial settings.
- Bags:Pre-formed enclosures address specialized containment requirements outside mainstream pallet logistics.
Rolls dominate film consumption; pallets drive equipment purchase decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment fabricators export pallet-wrapping systems to North American logistics corridors, while Chinese manufacturers supply compact semi-automatic units to Southeast Asian warehouse operators modernizing under infrastructure investment programs.
United States
Third-party fulfillment providers in Georgia and Texas are scaling palletized freight operations that demand faster film application without full automation capital deployment. OSHA ergonomic standards influence handle height and carriage weight specifications for warehouse installations. The Chicago-Milwaukee industrial corridor concentrates demand for heat-sealing variants serving protein processing facilities under FDA food-contact material regulations.
Germany
EU REACH phthalate restrictions on stretch film additives are redirecting equipment R&D toward heat-sealing components compatible with bio-based alternatives. The Baden-Württemberg packaging machinery cluster hosts fabricators redesigning thermal sealing systems for reformulated film compositions. Bavarian dairy processors are extending qualification timelines as suppliers adjust compositions to maintain seal integrity under EFSA barrier requirements.
China
E-commerce logistics providers in Jiangsu and Zhejiang provinces are expanding semi-automatic wrapper procurement as warehouse throughput requirements intensify. GB standards on machinery safety shape equipment certification pathways for domestic and export markets. The Yangtze River Delta manufacturing zone concentrates stretch film production, creating geographic supply advantages for equipment operators seeking qualified material inputs.
India
BIS certification pathways and PLI scheme incentives for logistics infrastructure are creating first-mover advantage for semi-automatic wrapper suppliers establishing local assembly partnerships. The Maharashtra warehouse corridor around Mumbai and Pune is modernizing pallet handling systems under freight volume growth. Gujarat-based food processors are adopting heat-sealing variants to meet FSSAI hygiene mandates in dairy and protein operations.
Global Hand Wrapping Machine Market Vendor Landscape
Player mix skews toward diversified packaging machinery conglomerates with stretch-wrapping divisions alongside specialized pallet-equipment fabricators. The structure concentrates around three strategic tiers: North American manufacturers with regional fulfillment advantages, European specialists in heat-sealing technology, and Asian producers serving cost-sensitive warehouse segments. Competitive moves center on distributor network consolidation for rapid parts availability and pre-stretch carriage miniaturization for legacy facility retrofitting.
Within the diversified machinery tier, Lantech and Muller occupy positions that exemplify regional manufacturing footprint strategies, while Robopac represents specialization in irregular load geometry configurations. M.J. Maillis anchors the European heat-sealing technology vector alongside TAM, which sits within the Italian packaging machinery cluster. These named entities illustrate how competitive positioning fragments across geographic manufacturing bases and application-specific technical capabilities rather than converging on unified product architectures.
| Leading Market Players |
|---|
| M.J. Maillis |
| Lantech |
| Robopac |
| TAM |
| ARPAC |
| Reiser |
| Muller |
| Orion |
| Nitechiipm |
| Others |
Supply Flow & Price Mechanics
Sixty-day component lead times for pre-stretch carriage motors concentrate pricing power with German and Chinese fabricators holding regional inventory buffers, while spot aluminum pricing volatility feeds directly into semi-automatic wrapper quotations.
Pricing Analysis
Current-generation 300% pre-stretch carriage systems command premium positioning over legacy 150% configurations and emerging IoT-enabled next-gen units still in qualification. Three-tier pricing structure across premium, standard, and economy levels segments by pre-stretch ratio, OSHA ergonomic certification grade, and after-sales service bundling. Pricing pressure stems from steel and aluminum commodity volatility compressing margin stability for mid-tier fabricators. Third-party logistics providers in the United States exhibit highest price sensitivity due to unified distributor contract consolidation, whereas German food processors accept premium tiers for EU REACH-compliant heat-sealing variants.
Supply Chain Analysis
China and Germany anchor stretch film wrapper fabrication, with Italy hosting specialized heat-sealing component production for European food processing corridors. Machine frames draw from steel mills in Jiangsu province and aluminum extruders in Baden-Württemberg, while pre-stretch motors source from Japanese precision manufacturers. Single-source vulnerability concentrates in specialty film carriage bearings produced at limited Asian facilities. Distribution runs through authorized regional service partners bundling equipment, consumables, and maintenance under unified contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT-enabled film consumption sensors are expanding service-attachment revenue faster than hardware unit growth, converting equipment vendors into recurring-revenue platforms.
For Market Incumbents: Compound distributor technical certification requirements to elevate switching costs for logistics providers consolidating procurement around unified service contracts. Deepen backward integration into pre-stretch motor assembly to insulate margin position from Japanese supplier concentration. Prioritize heat-sealing R&D for bio-based film compatibility as EU REACH phthalate restrictions threaten legacy equipment stranded asset risk.
For New Entrants and Emerging Players: BIS certification fast-track partnerships with Maharashtra warehouse operators exploit PLI scheme infrastructure incentives before incumbent local assembly scale-up. Target India's Gujarat dairy corridor with compact semi-automatic heat-sealing configurations addressing FSSAI hygiene mandates. Pursue private-label OEM supply relationships with established European distributors seeking Asian cost structures without direct China exposure.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because distributor network density determines parts-availability competitive advantage in an equipment category with 15-year installed base lifecycles. Acquisition targets should concentrate on regional service partners with certified technical workforces rather than manufacturing assets. The signal to watch is distributor contract renewal rates in third-party logistics segments as procurement consolidation accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Stretch Carriage Miniaturization | Shrinks equipment footprints for legacy facility retrofitting in Germany and United States. |
| Bio-Based Film Compatibility Certification | Qualifies heat-sealing systems for EU REACH-compliant stretch film alternatives. |
| IoT Sensor Integration | Enables consumption monitoring revenue attachment with warehouse management systems. |
| Regional Assembly Partnership | Captures PLI scheme incentives in India while reducing logistics cost to Southeast Asian markets. |
| Distributor Technical Certification Program | Elevates switching costs for logistics providers consolidating procurement under unified contracts. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, packaging machinery association reports, and SEC filings from diversified industrial conglomerates. Primary interviews engaged warehouse operations directors, third-party logistics procurement leads, OEM equipment distributors, and aftermarket service heads across Germany, China, the United States, and India. Secondary validation drew from OSHA ergonomic standards documentation, EU REACH substance restriction updates, and BIS machinery certification pathways. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segmentation dimensions modeled include product type, end user vertical, sealing technology, and packaging form across the analysis window. CAGRs derived from logistic curve penetration modeling for semi-automatic wrappers and elasticity-adjusted replacement cycle analysis for pre-stretch technology upgrades. Forecast inputs incorporated e-commerce freight volume trajectories in Jiangsu and Zhejiang provinces, EU EFSA barrier requirement implementation timelines, and PLI scheme infrastructure disbursement schedules in Maharashtra.
Underlying assumptions cover sustained e-commerce logistics expansion, stable aluminum and steel commodity bands, and gradual bio-based film adoption curves, with deviation risk concentrated in tariff escalation affecting Chinese component sourcing and accelerated EU REACH substance restriction enforcement. Recalibration cycles align with material shifts in warehouse automation investment rates and bio-based film commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Blister Packaging Machinery Market
Packaging Machinery
Cutter-Box Packaging Market
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Global Wrapping Machine Market
Packaging Machinery
Banding Machine Market
Packaging Machinery
Screw Capping Machines Market
Packaging Machinery
Corrugated Box Printer Slotter Machine Market
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market
Packaging Machinery
Global Paper Napkin Making Machine Market
Packaging Machinery
Pallet Strapping Machines Market
Packaging Machinery
Extrusion Press Market
Packaging Machinery
Hand-Held Capping Machines Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Triangle Tea Bag Packaging Machinery Market