
 Bottle Blowing Machine Market | 2026-2036
Bottle Blowing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Bottle Blowing Machine Market Analysis
Project finance and operating lease structures for blow molding lines is narrowing the competitive field to suppliers with balance-sheet capacity. Krones AG leverages captive financing subsidiaries to place turnkey stretch blow systems with mid-sized beverage co-packers. Sidel Group anchors its competitiveness through long-term service contracts bundled with machine deployments. Nissei ASB Machine Co. Ltd differentiates by specializing in niche pharmaceutical-grade injection blow platforms.
A bottle blowing machine forms hollow plastic containers by inflating heated preforms or parisons inside metal molds, typically achieving cycle speeds of 2,000 to 2,400 bottles per hour on rotary stretch blow systems. These machines serve primarily the beverage, personal care, and pharmaceutical sectors where PET, HDPE, and PP containers replace glass and metal formats. Stretch blow molding dominates value capture in carbonated soft drink and bottled water applications where clarity and pressure resistance command premium placement. Extrusion blow molding retains structural relevance in household product and industrial chemical segments where handleware and wide-mouth designs predominate. High-capacity systems above 50,000 bottles per hour concentrate margin pools among turnkey integrators serving Coca-Cola and PepsiCo bottling networks.
FDA cGMP standards govern pharmaceutical blow molding validation protocols in the United States, while the EU MDR tightens traceability requirements for medical-grade PET containers. China's GB standards and SAMR circular economy mandates push domestic OEMs toward all-electric servo-driven architectures. Stakeholders must monitor how carbon border adjustment mechanisms and recycled content mandates reshape equipment specification criteria across their installed base planning cycles.
Market Dynamics
Electric servo-driven architectures are displacing hydraulic blow molding systems as the EU's F-Gas Regulation and national carbon pricing schemes penalize energy-intensive equipment across installed bases.
Growth Catalysts
- EU F-Gas Regulation:Mandatory phase-down of hydrofluorocarbon refrigerants in cooling systems forces beverage packagers toward all-electric stretch blow lines that eliminate pneumatic cooling circuits.
- India's dairy conversion wave:Edible oil and milk cooperatives are retiring glass bottle lines in favor of HDPE and PET formats, requiring new extrusion and injection blow capacity.
- Lightweighting protocols:Preform design software coupled with high-pressure recovery systems enables sub-8 gram PET bottles for still water, cutting resin costs per unit.
Market Restraints
- Copper and rare-earth magnet costs:All-electric servo motors depend on neodymium and copper windings, exposing OEMs to price volatility from concentrated Chinese refining capacity.
- Validation timelines:FDA cGMP protocols for pharmaceutical-grade blow molding extend equipment commissioning by 14-18 months versus standard beverage configurations.
- Second-hand equipment arbitrage:Depreciated rotary stretch blow systems from Western European bottlers flood secondary markets, compressing new equipment pricing in North Africa and Southeast Asia.
Strategic Opportunities
- Indonesia's bottled water expansion:Danone-Aqua and local challengers are adding capacity in Sulawesi and Papua where per-capita consumption remains below Malaysian levels.
- Recycled-content mandates:California's SB 54 and the EU's Packaging and Packaging Waste Regulation create pull for rPET-compatible blow molding systems with advanced decontamination integration.
- Pharma-aesthetic convergence:Cosmeceutical brands demand pharmaceutical-grade clarity and barrier properties in personal care packaging, opening hybrid injection-stretch blow applications.
Industry Challenges
- Electromechanical technician scarcity:Servo-driven architectures require programming skills in PLC and motion control that legacy hydraulic technicians rarely possess, extending commissioning timelines.
- Legacy line integration:Brownfield beverage plants running 1990s-era Sidel or Krones rotary systems face protocol mismatches when adding modern preform feeding and quality inspection modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottle Blowing Machine Market |
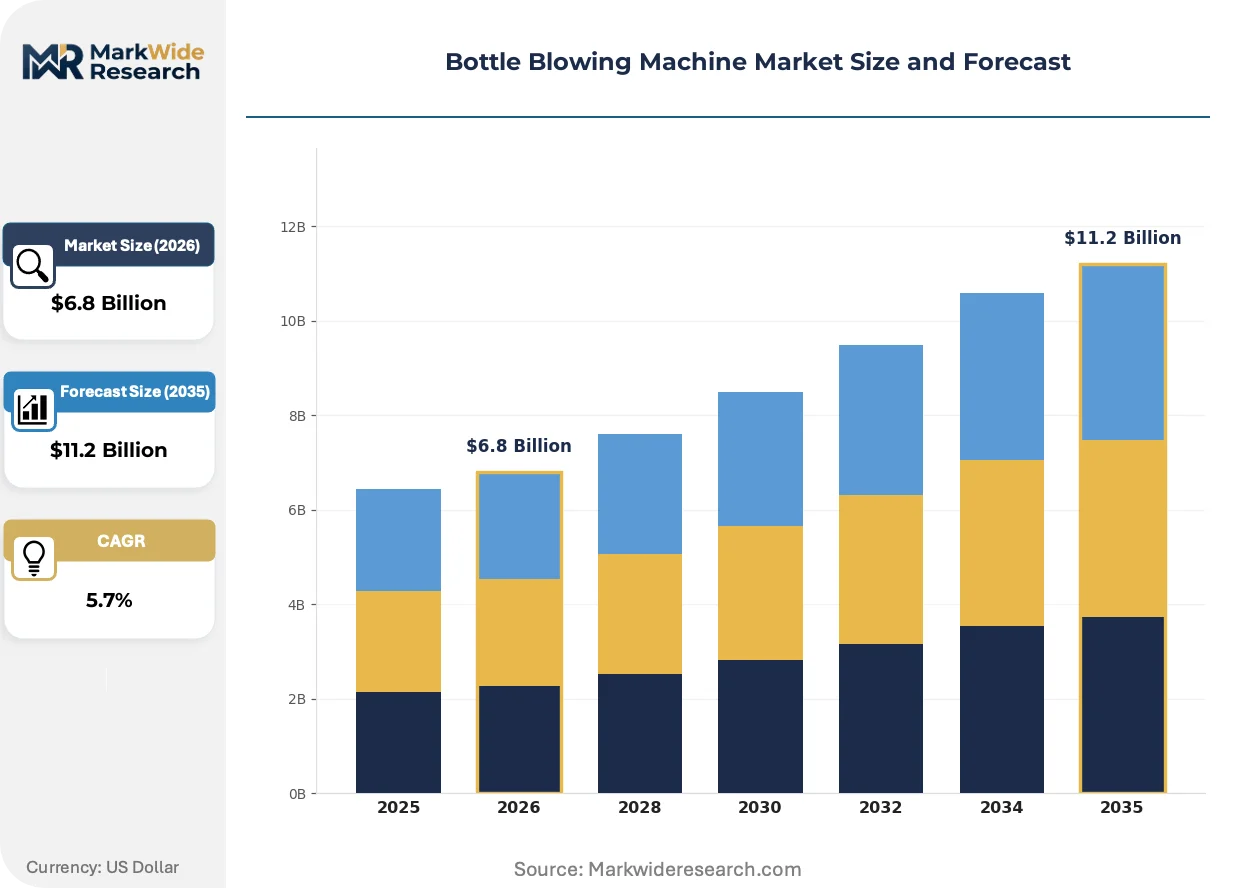
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Hybrid Technology: Stretch Blow Molding, Extrusion Blow Molding, Injection Blow Molding, Reheat Blow Molding End User: Beverage Industry, Personal Care, Household Products, Pharmaceuticals Capacity: Low Capacity, Medium Capacity, High Capacity, Extra High Capacity |
| Companies Covered | Krones AG, Sidel Group, KHS GmbH, Sacmi Imola S.C., SIPA S.p.A., Nissei ASB Machine Co. Ltd, SMI S.p.A., Aoki Technical Laboratory, Graham Packaging Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottle Blowing Machine Market Emerging Trajectories
Digital twin architectures and closed-loop quality systems are redefining how blow molding lines achieve uptime targets and material efficiency in high-volume beverage operations.
Digital twin platforms are virtualizing machine commissioning and fault diagnosis by mirroring mechanical, thermal, and pneumatic behaviors in cloud-based simulation environments. Tier-one beverage co-packers in Germany and Mexico deploy these systems to reduce physical trial runs by 60 percent before factory acceptance tests. The technology is virtualizing traditional field service models as remote diagnostics replace on-site technician dispatches for calibration and troubleshooting.
The EU's F-Gas Regulation tightens leakage monitoring requirements on cooling circuits, compelling OEMs to redesign heat exchangers with hermetic scroll compressors or abandon vapor compression entirely. Machine builders in Italy and France now specify air-cooled electric drives as default configurations for systems under 40,000 bottles per hour. Pharmaceutical blow molding lines face parallel pressure from the EU MDR's Unique Device Identification mandates, which require laser-etched traceability codes on every container.
Beverage brand owners are unbundling after-sales service contracts from initial equipment purchases, creating standalone multi-vendor maintenance agreements. Coca-Cola bottling partners in Brazil and Nigeria now procure spare parts and technical support through third-party industrial service platforms rather than captive OEM networks. This pattern is most visible in emerging markets where foreign exchange constraints make long-term dollar-denominated service contracts unsustainable for local franchisees.
Bottle Blowing Machine Market Segmentation
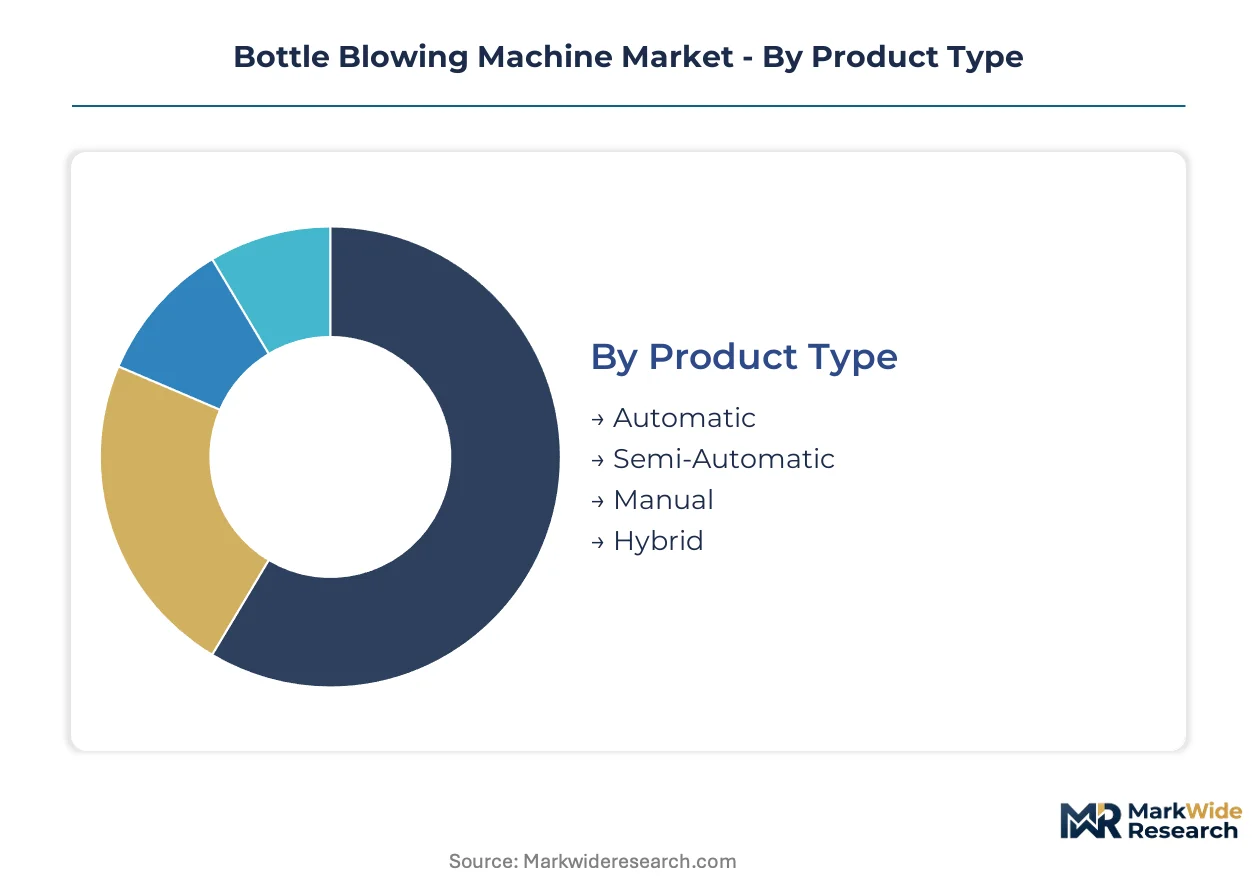
Segmentation in the bottle blowing machine market reveals divergent equipment lifecycles and capital deployment patterns across automation tiers and molding technologies. Understanding these cycles helps suppliers align service contracts with replacement demand and helps buyers time capacity additions against regulatory windows.
Product Type:
Automatic systems turn over fastest as beverage co-packers chase efficiency gains, while manual units linger longest in artisanal and pilot-line settings.
- Automatic:Rotary stretch blow systems with servo-driven preform handling achieve 2,000-2,400 bottles per hour with minimal operator intervention. Coca-Cola and PepsiCo bottling networks in India and Brazil standardize on these lines to meet rPET integration mandates from California's SB 54 and the EU's Packaging and Packaging Waste Regulation.
- Semi-Automatic:Systems requiring manual preform loading and bottle removal occupy the mid-tier for regional dairy cooperatives and edible oil packagers converting from glass in Maharashtra and Gujarat. These machines bridge the gap between artisanal production and full automation where capital constraints or volume uncertainty persist.
- Manual:Foot-pedal or hand-lever operated units serve prototype development and ultra-small-batch cosmetics in European craft distilleries and pharmaceutical pilot facilities.
- Hybrid:Configurations blending automatic preform feeding with manual quality inspection adapt to emerging market labor cost structures in Indonesia and Nigeria.
Automatic systems dominate installed base. Semi-Automatic is where expansion concentrates in India's dairy conversion wave.
Technology:
Cost tier stratification separates premium stretch blow platforms from utility-grade extrusion systems serving commodity chemical packaging.
- Stretch Blow Molding:Biaxial orientation of PET preforms creates pressure-resistant containers with glass-like clarity. The EU's F-Gas Regulation accelerates replacement of pneumatic cooling circuits with all-electric architectures in German and Italian beverage plants.
- Extrusion Blow Molding:Continuous parison extrusion suits HDPE handleware for household cleaners and wide-mouth industrial chemical containers. Demand clusters in India's edible oil sector as cooperatives retire glass lines for plastic formats.
- Injection Blow Molding:Single-stage preform molding and blowing delivers pharmaceutical-grade precision for FDA cGMP validation protocols. Extended commissioning timelines of 14-18 months constrain deployment velocity in US and EU markets.
- Reheat Blow Molding:Two-stage process separating preform injection from blow molding optimizes logistics for centralized preform supply to distributed bottling facilities.
Stretch Blow Molding captures the highest value per installed unit. Injection Blow Molding is climbing the fastest as pharma-aesthetic convergence drives hybrid applications.
End User:
Volume concentration and margin profile split sharply between high-throughput beverage operations and validation-intensive pharmaceutical lines.
- Beverage Industry:Carbonated soft drink and bottled water producers demand 50,000+ bottles per hour from turnkey integrators. Danone-Aqua's expansion into Sulawesi and Papua exemplifies capacity additions in underpenetrated Indonesian markets.
- Personal Care:Cosmeceutical brands require pharmaceutical-grade clarity and barrier properties, opening hybrid injection-stretch blow applications for premium skincare packaging.
- Household Products:HDPE handleware for detergents and cleaners relies on extrusion blow molding with lower cycle speed requirements than beverage applications.
- Pharmaceuticals:FDA cGMP and EU MDR traceability mandates enforce laser-etched Unique Device Identification codes and extended validation protocols, compressing supplier margins through compliance burden.
Beverage Industry dominates installed base. Pharmaceuticals is gaining share fastest on regulatory tightening and aesthetic convergence.
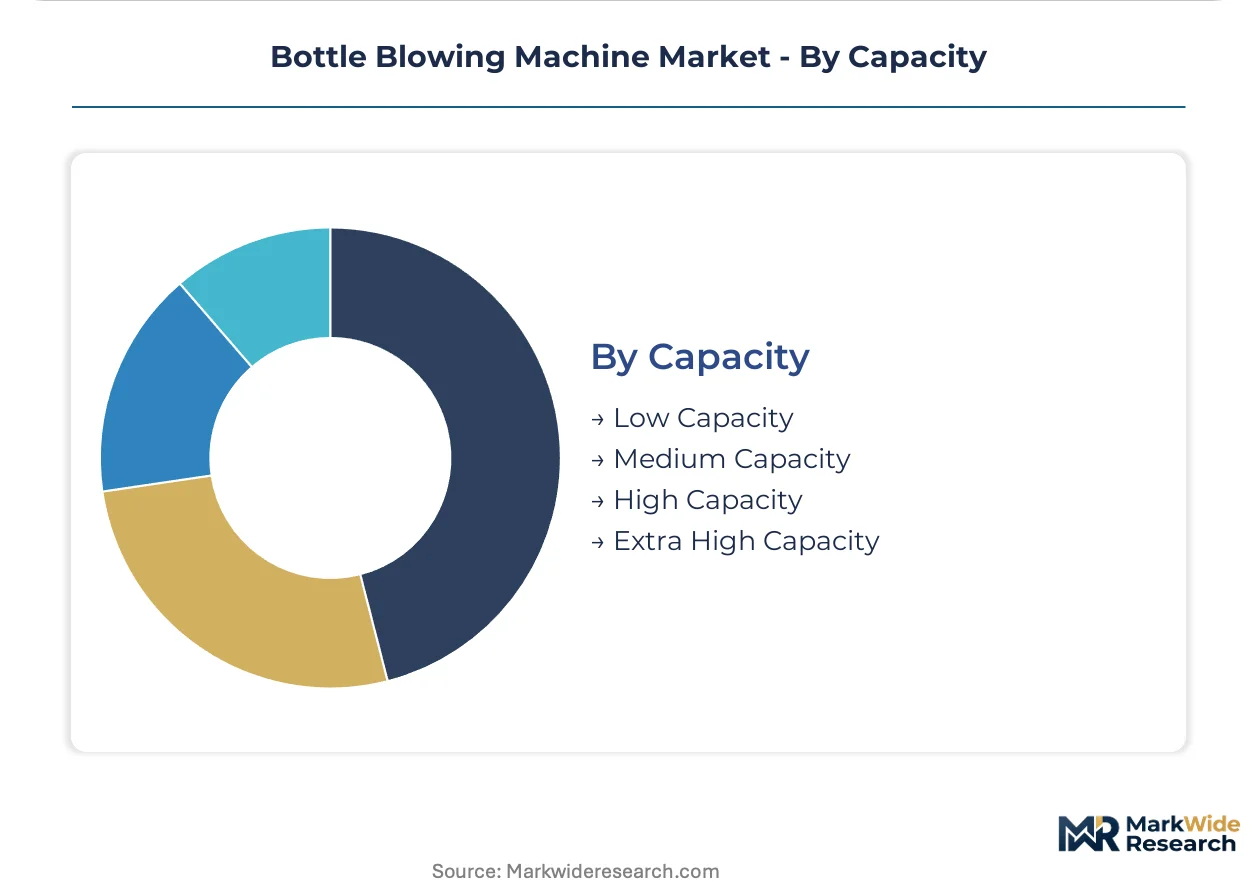
Capacity:
Customer type and geography determine capacity tier selection, with emerging market franchisees favoring scalable medium-capacity platforms over maximum-throughput systems.
- Low Capacity:Sub-10,000 bottles per hour serves craft beverages, pilot pharmaceutical lines, and regional dairy cooperatives in India's tier-2 cities.
- Medium Capacity:10,000-30,000 bottles per hour balances capital efficiency with growth optionality for Nigerian and Brazilian Coca-Cola franchisees facing foreign exchange constraints on dollar-denominated equipment purchases.
- High Capacity:30,000-50,000 bottles per hour concentrates among European bottlers replacing hydraulic systems with electric servo architectures under carbon pricing schemes.
- Extra High Capacity:50,000+ bottles per hour remains the province of turnkey integrators serving megabrand networks, with margin pools concentrating among suppliers offering captive financing and bundled service contracts.
Medium Capacity dominates new order intake in emerging markets. Extra High Capacity is where technology leadership concentrates among integrated suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage co-packers and dairy cooperatives concentrate equipment procurement in manufacturing clusters where carbon regulations and resin cost pressures intersect. Germany, India, China, Brazil, and Indonesia anchor regional demand patterns through distinct regulatory and industrial logics.
Germany
Bavarian bottling corridors drive replacement demand for all-electric stretch blow systems as the EU F-Gas Regulation phases down hydrofluorocarbon refrigerants. The KBA enforces strict energy efficiency standards on industrial cooling equipment, accelerating hydraulic-to-electric conversions. Stuttgart-area machine builders supply turnkey lines to carbonated soft drink producers seeking rPET integration under the EU Packaging and Packaging Waste Regulation.
India
Maharashtra and Gujarat dairy cooperatives are retiring glass bottle lines for HDPE and PET formats, requiring new extrusion and injection blow capacity. BIS certification mandates for food-contact plastics shape equipment specification criteria. The Mumbai-Pune industrial belt concentrates edible oil packager conversions, with local OEMs scaling all-electric servo architectures to meet SAMR-equivalent efficiency benchmarks.
China
Yangtze River Delta beverage producers deploy high-throughput rotary stretch blow systems to serve sparkling water and ready-to-drink categories. GB standards and SAMR circular economy mandates push domestic OEMs toward energy-efficient electric architectures. The Suzhou-Wuxi corridor hosts the densest concentration of preform injection and blow molding integration facilities serving both domestic brands and export markets.
Brazil
São Paulo-state Coca-Cola franchisees face foreign exchange constraints on dollar-denominated equipment purchases, favoring medium-capacity platforms with scalable upgrade paths. ANVISA pharmaceutical packaging regulations create parallel demand for FDA-cGMP-compatible injection blow systems. The Campinas industrial cluster concentrates aftermarket service platforms unbundling spare parts procurement from captive OEM networks.
Indonesia
Sulawesi and Papua bottled water expansion drives rotary stretch blow deployments where per-capita consumption remains below Malaysian levels. Danone-Aqua and local challengers add capacity in underpenetrated eastern provinces. The Surabaya manufacturing corridor supplies medium-capacity systems to emerging market franchisees seeking growth optionality without maximum-throughput capital commitments.
Bottle Blowing Machine Market Vendor Landscape
Channel-controlling players compete with product-specialist players across financing capability, service bundling, and niche certification tiers. The market structure concentrates margin pools among turnkey integrators offering captive project finance, while mid-tier fabricators compete on equipment flexibility and regional aftermarket proximity. Three archetypes dominate: balance-sheet-heavy systems integrators, long-term service contract bundlers, and pharmaceutical-grade precision specialists. Competitive moves center on M&A to secure financing subsidiaries and strategic partnerships to embed decontamination modules for rPET compliance.
Among German-based systems integrators, Krones AG exemplifies the channel-control archetype through captive financing structures. Sidel Group anchors the service-bundling tier with multi-year maintenance agreements. Nissei ASB Machine Co. Ltd occupies the precision-specialist position, representing pharmaceutical-grade injection blow platform expertise. These three companies illustrate how competitive positioning stratifies across financing depth, service integration, and regulatory certification intensity rather than unit volume alone.
| Leading Market Players |
|---|
| Krones AG |
| Sidel Group |
| KHS GmbH |
| Sacmi Imola S.C. |
| SIPA S.p.A. |
| Nissei ASB Machine Co. Ltd |
| SMI S.p.A. |
| Aoki Technical Laboratory |
| Graham Packaging Company |
| Others |
Supply Flow & Price Mechanics
The Suzhou-Wuxi corridor concentrates preform injection and blow molding integration capacity, creating asymmetric pricing power for turnkey integrators serving Coca-Cola and PepsiCo bottling networks while compressing margins for mid-tier fabricators lacking captive financing subsidiaries.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and beverage-standard equipment tiers. Three-tier pricing structure across FDA-validated, CE-marked, and baseline industrial configurations reflects validation timeline differentials of 14-18 months for pharma lines versus standard beverage commissioning. Cost compression in the semi-automatic tier is intensifying because second-hand rotary stretch blow systems from Western European bottlers flood North African and Southeast Asian secondary markets. Regional dairy cooperatives in Maharashtra and Gujarat exhibit highest price sensitivity, while pharmaceutical contract manufacturers absorb premium pricing for cGMP-compliant injection blow platforms.
Supply Chain Analysis
Neodymium and copper winding feedstock draws from concentrated Chinese refining capacity, exposing OEMs to rare-earth magnet price volatility that feeds into servo motor costs for all-electric architectures. Component manufacturing clusters in Germany, Italy, and China supply hermetic scroll compressors and precision molds to machine builders. Single-source vulnerability concentrates in neodymium supply chains subject to export licensing shifts. Distribution runs through turnkey integrators with captive project finance arms and third-party industrial service platforms unbundling spare parts procurement in Brazil and Nigeria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from refurbished equipment arbitrage and digital twin-enabled remote diagnostics that erode traditional field service revenue streams.
For Market Incumbents: Insulate installed base relationships by embedding predictive maintenance modules and extending long-term service contracts with performance-based uptime guarantees. Deepen backward integration into preform injection molding to capture margin pools from rPET integration mandates under California SB 54 and the EU Packaging and Packaging Waste Regulation. Counter second-hand equipment arbitrage through certified rebuild programs with warranty parity to new machines.
For New Entrants and Emerging Players: Medium-capacity rotary stretch blow systems for Indonesian bottled water expansion in Sulawesi and Papua represent the most penetrable entry point, where per-capita consumption gaps against Malaysian levels justify capacity additions without megabrand network dependencies. Target hybrid injection-stretch blow configurations for cosmeceutical brands demanding pharmaceutical-grade clarity in personal care packaging. Lead with pay-per-output financing structures that sidestep foreign exchange constraints plaguing dollar-denominated equipment purchases in Nigerian and Brazilian markets.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-bundling specialists with multi-year maintenance agreements and spare parts platforms. Long-term viability hinges on exposure to regulatory-driven replacement cycles rather than greenfield capacity expansion. Acquisition focus should center on precision-specialist fabricators with FDA cGMP validation capabilities and decontamination module integration for rPET compliance. Monitor F-Gas Regulation phase-down timelines and carbon border adjustment mechanism developments as inflection indicators for electric servo architecture demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Financing Subsidiary Expansion | Krones AG structures project finance to place turnkey stretch blow systems with mid-sized beverage co-packers facing capital constraints. |
| Decontamination Module Integration | rPET-compatible blow molding systems embed advanced decontamination to meet California SB 54 and EU Packaging and Packaging Waste Regulation mandates. |
| Digital Twin Platform Deployment | Cloud-based simulation environments virtualize commissioning and reduce physical trial runs by 60 percent before factory acceptance tests. |
| Pharmaceutical-Grade Certification Investment | Injection blow platforms achieve FDA cGMP validation to capture cosmeceutical packaging demand with 14-18 month commissioning timelines. |
| Aftermarket Service Platform Unbundling | Third-party industrial service platforms in Brazil and Nigeria decouple spare parts procurement from captive OEM networks. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with blow molding OEM technical directors, beverage co-packer plant engineers, pharmaceutical packaging compliance officers, and aftermarket service platform operators; and secondary validation through customs trade databases, SEC filings of listed equipment manufacturers, EU F-Gas Regulation implementation reports, and BIS certification records for Indian food-contact plastics. Bottom-up capacity assessments across Germany, India, China, Brazil, and Indonesia triangulated against top-down market sizing from equipment shipment tracking and preform demand modeling.
Forecast inputs span technology type, automation tier, end-use vertical, capacity segment, and regional regulatory cluster across the projection horizon. Segment-level CAGRs were derived from replacement cycle analysis, regulatory window timing, and greenfield capacity announcement tracking. Specific forecast inputs include F-Gas Regulation phase-down schedules, India's dairy cooperative conversion timelines, and Indonesian per-capita bottled water consumption convergence patterns.
Practitioners should monitor rare-earth magnet export licensing shifts, carbon border adjustment mechanism implementations, and second-hand equipment flow volumes for early signals of pricing and demand revisions. Forecasts embed assumptions regarding regulatory enforcement consistency and resin cost stability that material deviations could invalidate. Cross-checking against equipment utilization rates reported by major PET resin producers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Automatic Auger Fillers Market
Packaging Machinery
Filling Machinery Market
Packaging Machinery
Granule Filling Machine Market
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Asia-Pacific Pharmaceutical Packaging Machinery Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
CCL Laminating Machine Market
Packaging Machinery
Glue Machine Market
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Molded Pulp Packaging Machines Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Paper Napkin Converting Lines Market
Packaging Machinery
Pick Fill Seal Machines Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Aseptic Filling Machines Market