
 Paper Napkin Converting Lines Market | 2026-2036
Paper Napkin Converting Lines Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Napkin Converting Lines Market Analytics
Skilled technician availability in automated machinery maintenance is rotating from a bottleneck into a competitive differentiator for equipment vendors. Fabio Perini S.p.A. leverages its Italian engineering base to sustain high-margin customized line configurations. PCMC anchors North American demand through extensive field service networks and rebuild capabilities. Körber Business Area Tissue differentiates via integrated digital controls and data analytics platforms across its converting portfolio.
Paper napkin converting lines are industrial machinery systems that transform parent tissue rolls into folded, printed, and packaged napkin products through processes including unwinding, embossing, printing, folding, cutting, and stack formation; typical line speeds range from 300 to 1,000 meters per minute depending on configuration and product format. These systems serve commercial and consumer markets requiring consistent product dimensions, print registration accuracy, and hygienic packaging. Automatic lines command the largest installed base among product types due to labor cost pressures and throughput requirements in high-volume operations. Flexographic printing technology retains dominant share in technology segmentation because of its cost efficiency on long runs, though digital printing is gaining traction for shorter, variable-data production cycles.
CE marking under EU machinery directives and FDA food-contact material regulations shape equipment design standards and market access requirements for suppliers targeting European and North American buyers. ISO 9001 quality management and ISO 14001 environmental management certifications increasingly function as baseline qualification criteria in procurement processes. Buyers must evaluate total cost of ownership models that balance capital expenditure against energy consumption, changeover flexibility, and aftermarket parts availability when selecting converting line configurations.
Market Dynamics
Food service operators across Germany, Italy, and the United States are retiring mechanical converting equipment installed in the 1990s and early 2000s, creating replacement demand for servo-driven lines with inline quality inspection and automated changeover capabilities.
Growth Catalysts
- Servo motor integration:Precision motion control reduces setup times from hours to minutes, enabling tissue converters to run shorter production batches profitably.
- EU Machinery Directive compliance:CE marking requirements for safety interlocks and ergonomic design push European operators toward certified new equipment rather than used machinery imports.
- Quick-service restaurant expansion:Chains in the United States are adding automated napkin dispensing systems that require consistent fold geometry only high-speed converting lines can deliver.
Market Restraints
- Parent roll supply concentration:Tissue machine capacity clusters with Procter & Gamble, Essity, and Georgia-Pacific, exposing converters to input allocation constraints during demand spikes.
- Steel and aluminum price volatility:Frame structures and drying cylinders depend on commodity metals whose cost swings compress equipment margin buffers.
- Skilled technician scarcity:Maintenance of servo drives, programmable logic controllers, and vision systems requires training pipelines that vocational programs in Italy and Germany have not scaled to match equipment deployment rates.
Strategic Opportunities
- Digital printing module retrofits:Converters with existing flexographic lines can add inkjet heads for variable-data short runs serving event catering and private-label customization.
- India food service modernization:Quick-service pizza and burger chains are expanding beyond Tier-1 cities, creating first-time demand for automated napkin supply chains.
- ISO 14001 certification premium:Environmental management credentials are becoming mandatory in European retail procurement, rewarding suppliers with verified energy and water efficiency metrics.
Industry Challenges
- Electromechanical integration complexity:Retrofitting servo axes onto legacy mechanical lines often requires custom mechanical adapters that extend commissioning timelines.
- FDA food-contact compliance documentation:Ink formulations and packaging films must carry complete migration testing records, creating administrative overhead for converters serving North American food service accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Napkin Converting Lines Market |
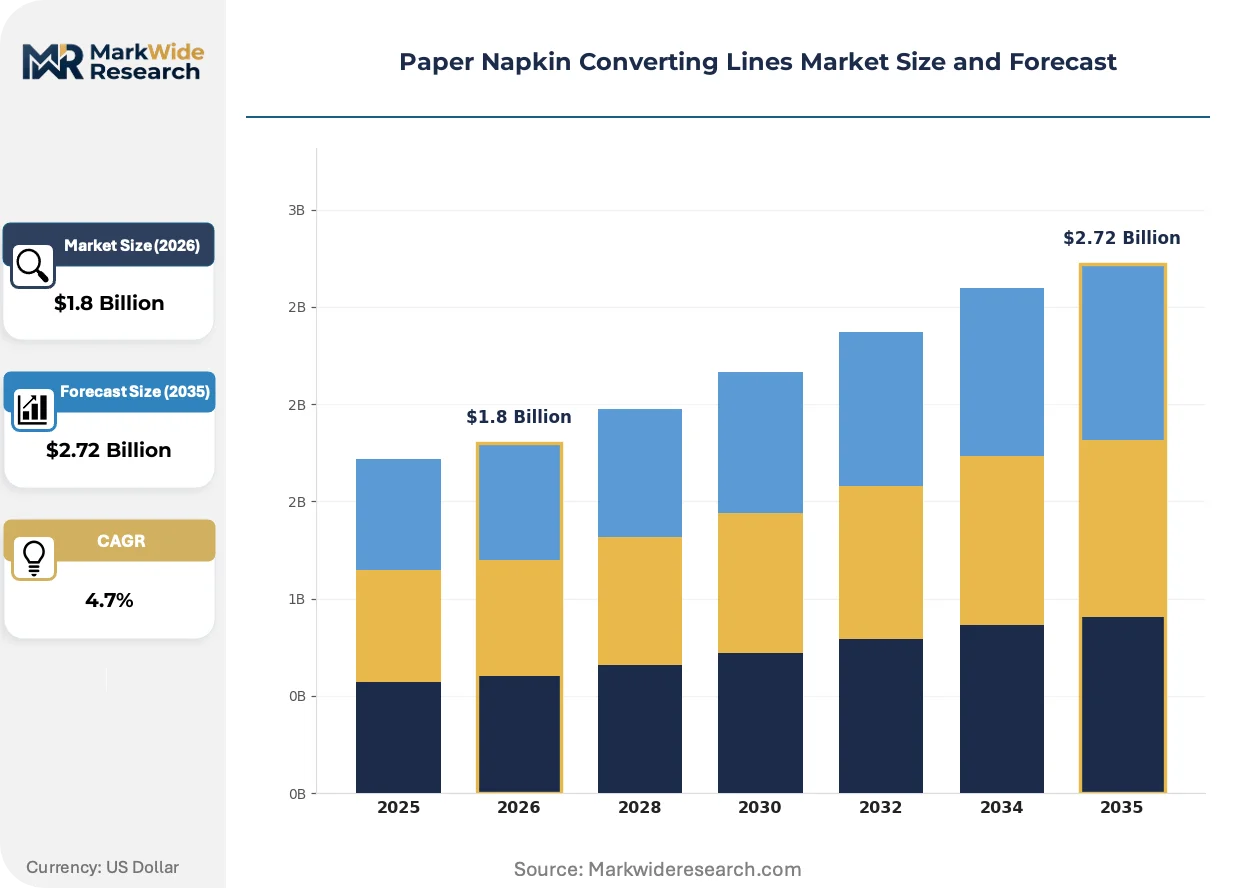
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Lines, Semi-Automatic Lines, Manual Lines, Specialized Lines Technology: Flexographic Printing, Digital Printing, Offset Printing, Inline Converting End User: Food Service, Retail, Household, Hospitality Packaging Type: Biodegradable, Recyclable, Plastic-Wrapped, Bulk Packaging |
| Companies Covered | Fabio Perini S.p.A., PCMC (Paper Converting Machine Company), Körber Business Area Tissue, BaoSuo Paper Machinery, Futura S.p.A., Gambini S.p.A., Dechangyu Paper Machinery, Kawanoe Zoki Co., Ltd., Bretting Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Napkin Converting Lines Market Evolving Landscape
Converting line architecture is pivoting from mechanical cam-driven systems toward modular electromechanical platforms that reconfigure through software rather than hardware change parts.
Vision-based inline inspection is displacing manual quality sampling at line speeds above 600 meters per minute. High-volume tissue converters in Germany and the United States are installing camera arrays that detect fold defects, print registration errors, and contamination in real time. This technology is displacing offline laboratory testing and enabling immediate ejection of non-conforming product without stopping production.
REACH chemical restrictions on certain ink solvents and biocidal treatments are forcing reformulation of consumables used in napkin production. The European Chemicals Agency's substance evaluation process has flagged several legacy flexographic ink components, compelling equipment suppliers to qualify alternative chemistries. Converting lines delivered to EU buyers now require closed-loop solvent recovery systems or water-based ink compatibility as standard configuration.
After-sales service unbundling is altering how tissue converters procure maintenance and spare parts. Large operators in the United States are negotiating component-level service contracts directly with servo drive and controller manufacturers, bypassing traditional OEM service departments. This pattern concentrates in regions with dense installed bases where third-party technical competence has developed around specific automation platforms.
Paper Napkin Converting Lines Market Segmentation
Paper napkin converting line buyers segment procurement by automation level, print technology, and end-use hygiene requirements. Equipment specifications diverge sharply between quick-service restaurant suppliers and retail private-label converters.
Product Type:
Manual and semi-automatic configurations face acute substitution pressure from servo-driven alternatives as labor costs climb across tissue-producing regions.
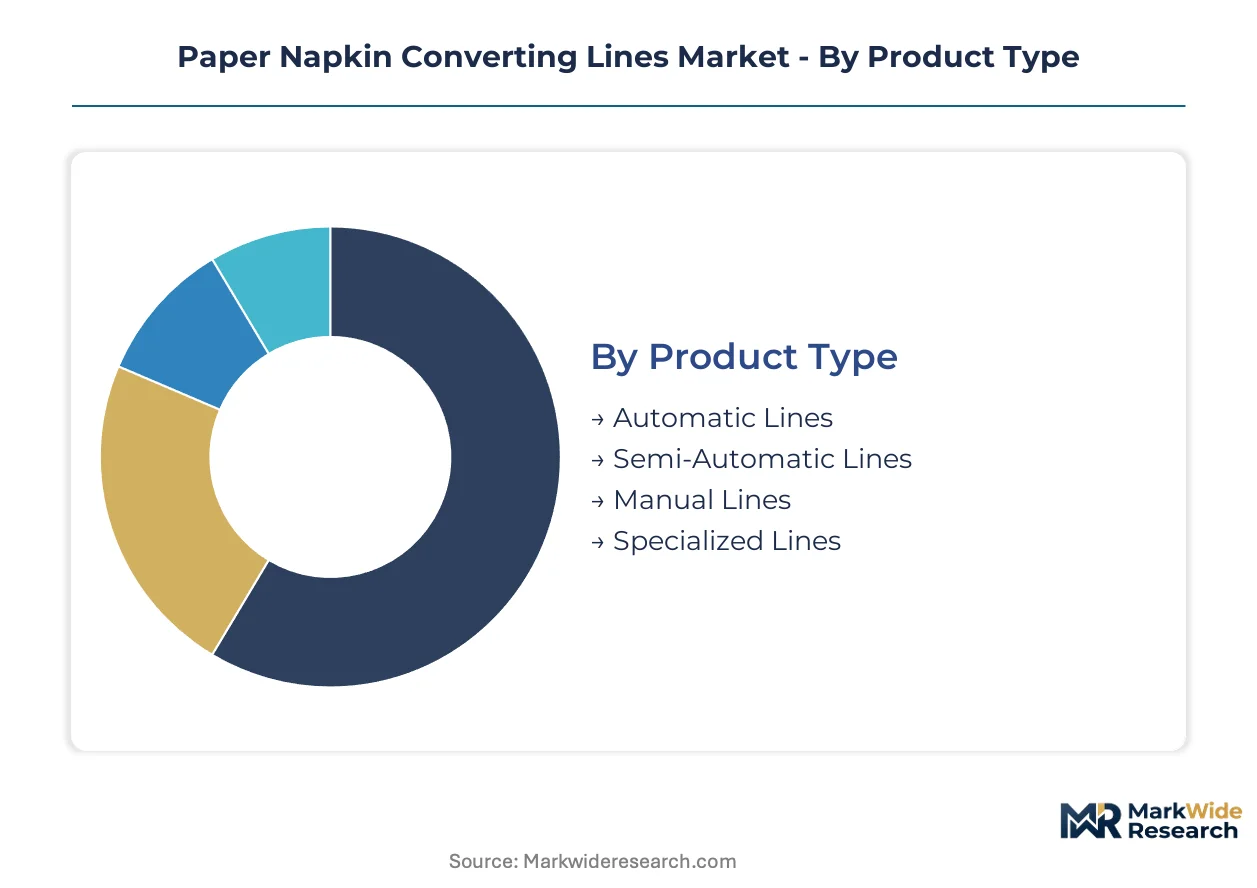
- Automatic Lines:These systems integrate servo-driven folding, inline printing, and automated changeover modules operating at 600-1,000 meters per minute. Food service operators in the United States and Germany are retiring 1990s-era mechanical equipment for these configurations to meet throughput targets and FDA food-contact compliance. Automatic lines retain volume leadership; specialized lines hold the steepest expansion curve.
- Semi-Automatic Lines:Hybrid configurations combine mechanical folding sections with programmable controls for mid-volume converters. Operators in Italy deploy these for seasonal production ramps where full automation cannot be justified.
- Manual Lines:Labor-intensive systems persist in artisanal tissue workshops and developing market startups with limited capital budgets.
- Specialized Lines:Custom configurations handle non-standard napkin formats, embossed patterns, or integrated dispensing systems for quick-service restaurant chains.
Automatic lines retain volume leadership; specialized lines hold the steepest expansion curve.
Technology:
Cost tiers separate long-run flexographic operations from emerging digital platforms serving variable-data production cycles.
- Flexographic Printing:Rotogravure-derived systems dominate high-volume runs exceeding 50,000 impressions with solvent-based or water-based inks. Tissue converters in Germany favor these for retail private-label contracts requiring consistent color matching across extended campaigns.
- Digital Printing:Inkjet and toner-based systems enable short-run customization for event catering and regional quick-service promotions. The technology is gaining share fastest in North American food service accounts.
- Offset Printing:Lithographic transfer systems serve premium napkin grades requiring fine detail reproduction for hospitality branding.
- Inline Converting:Integrated unwinding-to-packaging architectures eliminate intermediate handling stages, reducing contamination risk for FDA-regulated food-contact applications.
Flexographic systems anchor installed base economics; digital platforms are climbing the fastest as run lengths compress.
End User:
Application requirements dictate hygiene certification levels and packaging automation intensity across buyer categories.
- Food Service:Quick-service restaurant chains and contract foodservice operators require ISO 22000-aligned equipment with metal detection and hermetic packaging modules. United States-based operators are standardizing on automatic lines with vision inspection to supply automated dispensing systems.
- Retail:Supermarket private-label programs demand rapid changeover between SKUs, favoring servo-driven configurations with recipe-stored format adjustments.
- Household:Consumer-grade napkin production emphasizes cost minimization over feature complexity, sustaining demand for semi-automatic lines in price-sensitive markets.
- Hospitality:Hotel and catering accounts prioritize premium embossing and custom print registration, often specifying specialized line configurations.
Food service commands the largest equipment procurement budget; retail applications are expanding most quickly through private-label proliferation.
Packaging Type:
Regulatory momentum around single-use plastics is reshaping material specifications for finished napkin containment.
- Biodegradable:Cellulose-based films and compostable wraps align with EU Green Deal procurement criteria and France's anti-waste circular economy law. Converting lines serving European retail accounts now require heat-sealing modules compatible with these substrates.
- Recyclable:Paper-based wraps and fiber trays meet EPA recycling stream guidelines for United States municipal collection systems.
- Plastic-Wrapped:Polyethylene films persist in moisture-sensitive applications and markets with limited recycling infrastructure.
- Bulk Packaging:Unwrapped stack configurations for institutional dispensers minimize material cost in high-throughput food service environments.
Recyclable formats dominate current procurement volumes; biodegradable alternatives are gaining share fastest under European regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact material regulations in the United States anchor the dominant geography for paper napkin converting line procurement, while CE marking requirements under EU machinery directives shape European equipment specifications. Equipment modernization cycles concentrate in Germany, Italy, and the United States where installed bases from the 1990s require replacement.
United States
Quick-service restaurant chains and contract foodservice operators drive demand for automatic lines with vision inspection and hermetic packaging modules. FDA regulations mandate complete migration testing records for ink formulations and packaging films serving food-contact applications. The Southeast manufacturing corridor spanning Georgia and the Carolinas hosts tissue converters modernizing mechanical equipment for automated dispensing system compatibility.
Germany
Retail private-label programs and industrial tissue converters prioritize servo-driven configurations with rapid changeover capabilities between SKUs. CE marking under EU machinery directives enforces safety interlocks and ergonomic design standards that discourage used machinery imports. The Baden-Württemberg industrial cluster around Stuttgart sustains demand for high-speed lines with inline quality inspection.
Italy
Seasonal production ramps and mid-volume operations sustain demand for semi-automatic hybrid configurations combining mechanical folding with programmable controls. REACH chemical restrictions on flexographic ink solvents force equipment suppliers to qualify alternative chemistries and closed-loop solvent recovery systems. The Lucca tissue district in Tuscany operates Europe's densest concentration of converting facilities requiring ongoing modernization.
China
Domestic food service expansion and export-oriented manufacturing drive first-time equipment procurement and capacity additions. GB standards and MIIT industrial policy guide machinery safety and energy efficiency specifications for domestic market access. The Yangtze River Delta manufacturing belt around Shanghai hosts emerging tissue converters scaling from manual to automated production systems.
India
Quick-service pizza and burger chains expanding beyond Tier-1 cities create initial demand for automated napkin supply chains. FSSAI food safety regulations and BIS machinery standards shape equipment import and local fabrication requirements. The Maharashtra-Gujarat industrial corridor around Mumbai and Ahmedabad concentrates emerging converter operations serving Western India food service markets.
Paper Napkin Converting Lines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in paper napkin converting line supply. The upper tier comprises diversified machinery groups with tissue-specific divisions and captive control over automation subsystems. The specialist tier includes family-owned Italian engineering houses and regional Asian fabricators focused on cost-optimized configurations. Competitive moves concentrate on technology licensing partnerships for servo drive integration and geographic expansion through field service network density.
Among Italian engineering specialists, Fabio Perini S.p.A. and Futura S.p.A. exemplify the high-margin customized line archetype anchored in the Lucca industrial district. PCMC represents the North American integrated leader position with extensive rebuild capabilities and field service infrastructure. Körber Business Area Tissue occupies the diversified industrial group tier with integrated digital control platforms spanning multiple tissue converting categories.
| Leading Market Players |
|---|
| Fabio Perini S.p.A. |
| PCMC (Paper Converting Machine Company) |
| Körber Business Area Tissue |
| BaoSuo Paper Machinery |
| Futura S.p.A. |
| Gambini S.p.A. |
| Dechangyu Paper Machinery |
| Kawanoe Zoki Co., Ltd. |
| Bretting Manufacturing |
| Others |
Value Network & Pricing Analysis
Twenty-four to thirty-six week lead times for servo drive modules and precision motion components concentrate pricing power with German and Japanese automation suppliers, compressing margin buffers for machinery OEMs while elevating total cost of ownership for tissue converters evaluating equipment procurement.
Pricing Analysis
Price spreads between Italian-engineered customized lines and Asian-fabricated standard configurations exceed thirty percent at equivalent throughput ratings. Pricing stratifies across premium, standard, and economy tiers based on servo axis density and CE certification tier. Cost compression in mid-tier configurations is intensifying because Chinese fabricators are qualifying European safety interlocks for export markets. Retail private-label converters exhibit highest price sensitivity; quick-service restaurant chains prioritize compliance documentation over capital expenditure minimization.
Supply Chain Analysis
Germany and Japan anchor precision servo motor and motion controller production for converting line automation subsystems. Frame structures draw from Italian steel fabrication clusters; parent tissue rolls feed from Procter & Gamble and Essity mill networks concentrated in the United States and Western Europe. Single-source vulnerability sits with specialty linear encoder suppliers serving high-speed folding modules. Distribution runs through OEM direct sales organizations and regional machinery distributors with captive service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paper napkin converting line supply functions as a defensive-moat market anchored in regulatory entrenchment: CE marking and FDA food-contact compliance create certification barriers that multi-year qualification timelines protect.
For Market Incumbents: Compound installed base leverage through aftermarket service contract unbundling and predictive maintenance platform deployment. Chinese fabricators with European safety certification pose emerging substitution threat; vertical integration into servo drive calibration services defends margin position. Capacity addition in India's Maharashtra-Gujarat corridor captures quick-service restaurant expansion beyond Tier-1 cities. For New Entrants and Emerging Players: Lead with digital printing module retrofits for existing flexographic lines rather than greenfield equipment competition. India's food service modernization presents most penetrable geography; event catering variable-data production offers application white-space. Go-to-market angle centers on component-level service contracts bypassing traditional OEM channels. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because field service network density and rebuild capabilities concentrate value capture with established vendors. Acquisition target archetype: Italian engineering houses with Lucca district positioning and captive control over automation subsystem integration. Signal to watch: third-party technical competence development around specific servo platforms enabling service unbundling acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Servo Drive Integration Partnership | Motion control alliances with German automation suppliers reduce commissioning timelines for tissue converters. |
| Digital Printing Module Retrofit Program | Inkjet head integration enables short-run customization for event catering and private-label accounts. |
| Field Service Network Expansion | Dense technician coverage in India's industrial corridor captures quick-service restaurant equipment demand. |
| Closed-Loop Solvent Recovery System Deployment | REACH-compliant configurations secure European retail procurement under EU Green Deal criteria. |
| Vision-Based Quality Inspection Platform Launch | Camera array integration at 600+ meters per minute displaces manual sampling for high-volume operators. |
Research Methodology
Desk research of EU machinery directive filings, FDA food-contact material registrations, and trade customs data preceded structured interviews with tissue converter plant managers, OEM aftermarket service directors, and quick-service restaurant supply chain procurement leads. Primary fieldwork combined with secondary validation across SEC equipment manufacturer disclosures, ISO certification databases, and regional industrial cluster surveys. Bottom-up equipment shipment tallies triangulated against top-down tissue production capacity estimates.
Variance decomposition across automation level, print technology, and end-use hygiene requirements shaped the analytical framework over the projection horizon. CAGRs derived from equipment replacement cycle modeling and food service expansion trajectory analysis. Segmentation dimensions include product type, technology platform, end user category, and packaging format. Forecast inputs incorporated parent roll supply allocation constraints and REACH chemical restriction implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained quick-service restaurant automation adoption or parent roll supply disruption scenarios would require recalibration. Forecasts reflect documented assumptions regarding equipment modernization cycles and regulatory compliance cost trajectories. Specific risk factors include steel and aluminum commodity price volatility and skilled technician training pipeline scaling shortfalls. Recalibration cycles align with material shifts in EU machinery directive amendments and FDA food-contact material regulation updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Labeling Machines Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Cosmetic Filling Machines Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Emboss Coding Machine Market
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Pre-Made Pouch Packaging Machines Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Laminating Machines Market
Packaging Machinery
North America Printing Machinery Market
Packaging Machinery
Filling Machinery Market