
 Liquid Filling Machines Market | 2026-2036
Liquid Filling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Filling Machines Market Outlook
Asset-light leasing and equipment-as-a-service financing is rewriting competitive entry barriers for mid-tier bottlers and contract manufacturers. Krones leverages its captive finance arm to place turnkey rotary filler lines without upfront capex, while GEA Group sustains European dairy dominance through long-term service contracts that bundle volumetric fillers with predictive maintenance. Syntegon anchors pharmaceutical-grade isolator systems with clean-in-place validation, competing on containment integrity rather than throughput alone.
Liquid filling machines are precision-engineered systems that dispense measured volumes of free-flowing, viscous, or foaming liquids into rigid or flexible containers at rates from ten to over one thousand units per minute, with accuracy tolerances typically within plus or minus 0.5 percent. These machines serve primary packaging operations across beverage bottling, sterile drug manufacturing, cosmetic dispensing, and chemical blending where fill-level consistency directly governs regulatory compliance and material yield. Volumetric filler platforms command the widest installed base due to versatility across viscosity ranges, though gravity fillers generate the highest margin pools in high-speed water and CSD lines where simplicity minimizes downtime. Automatic technology segments displace semi-automatic units fastest in pharmaceutical applications driven by batch integrity and operator reduction mandates.
FDA 21 CFR Part 11, EU MDR Annex I, and REACH substance restrictions collectively shape machine design, forcing stainless steel contact surfaces, audit trail software, and lubricant chemistry disclosures. The EU F-Gas Regulation and EPA SNAP program additionally constrain refrigerant and propellant choices in aerosol and chilled-product filling configurations. Stakeholders must monitor evolving serialization deadlines and carbon-border adjustment mechanisms to time capital deployment and supplier qualification cycles.
Market Dynamics
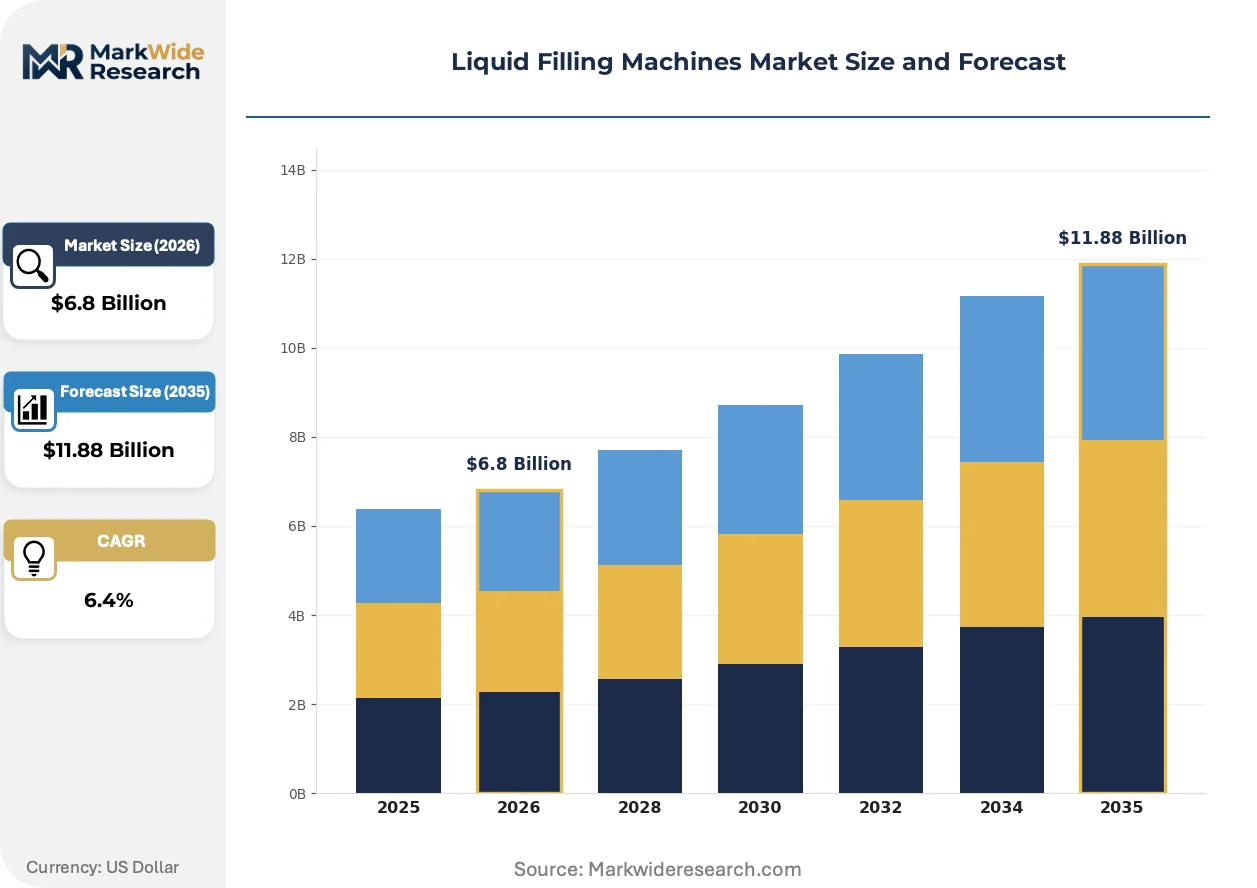
Pharmaceutical serialization mandates and carbon-border adjustment mechanisms are forcing capital deployment cycles to compress from traditional seven-year horizons to three-year equipment refresh windows, reshaping supplier qualification and financing structures across the installed base.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records and signatures requirements in sterile drug manufacturing are mandating automated batch integrity systems that eliminate manual intervention points in aseptic filling operations.
- Asia-Pacific beverage corridors:Gravity filler installations in Thailand, Vietnam, and Indonesia are accelerating as multinational bottlers localize production to avoid carbon-border tariffs on imported packaged goods.
- Isolator technology:Pharmaceutical-grade containment systems with integrated clean-in-place validation are displacing conventional cleanroom configurations in high-potency drug manufacturing.
Market Restraints
- Stainless steel price volatility:316L and 304 grade contact surface materials account for 35-40% of bill-of-materials costs, exposing margins to nickel and chromium commodity swings.
- German precision component concentration:Servo drive systems and high-accuracy flow meters rely on a narrow supplier base centered in Baden-Württemberg and Bavaria, creating single-source vulnerability.
- EU F-Gas Regulation:Refrigerant constraints in chilled-product filling lines are forcing costly retrofits or complete system replacements for aerosol and dairy processors.
Strategic Opportunities
- India contract manufacturing:CDSCO serialization deadlines and PLI scheme incentives for active pharmaceutical ingredients are creating demand for turnkey isolator lines in Hyderabad and Ahmedabad clusters.
- Equipment-as-a-service:Leasing models bundling predictive maintenance with volumetric filler deployments are opening mid-tier bottler segments previously priced out of automated lines.
- Biologic drug formats:Single-use disposable filling paths for cell and gene therapies represent white space where traditional stainless steel systems carry contamination risks.
Industry Challenges
- Mechatronics talent scarcity:Integration of servo-controlled piston systems with vision-based fill-level inspection requires cross-trained engineers scarce in Midwest US dairy processing corridors.
- Legacy SCADA migration:Brownfield pharmaceutical plants running 1990s-era Allen-Bradley or Siemens S7 platforms face multi-year validation timelines to achieve FDA-compliant audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Filling Machines Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Fillers, Volumetric Fillers, Gravity Fillers, Pump Fillers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Technology: Automatic, Semi-Automatic, Manual, Inline Container Type: Bottles, Jars, Pouches, Cans |
| Companies Covered | Krones, GEA Group, Syntegon, JBT Corporation, Bosch Packaging Technology, Accutek Packaging Equipment, KHS GmbH, PACKO Filling Systems, Groninger & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Filling Machines Market Strategic Shifts
Digital thread architectures and closed-loop quality systems are compressing the gap between filling operation and regulatory submission, collapsing validation cycles from months to weeks.
Machine vision with deep-learning defect classification is digitizing in-line quality assurance, replacing manual sampling protocols in pharmaceutical and cosmetic filling lines. Contract manufacturers in New Jersey and North Carolina are deploying these systems at 85% of new installations. The technology is digitizing compliance documentation by auto-generating batch records that map directly to FDA submission templates.
REACH substance restrictions and lubricant chemistry disclosure requirements are forcing reformulation of gearbox oils and pneumatic seal compounds used in food-contact filling environments. European dairy processors must now certify every lubricant point through ECHA-registered safety data sheets. German equipment builders are responding with dry-running ceramic piston options that eliminate hydrocarbon lubricants entirely.
After-sales service unbundling is fragmenting traditional OEM maintenance contracts into component-level subscriptions. North American beverage bottlers now procure predictive analytics for servo drives separately from mechanical service agreements. This shift is most visible in Coca-Cola and PepsiCo anchor bottler networks, where third-party IIoT platforms aggregate data across multi-vendor filler fleets.
Liquid Filling Machines Market Segmentation
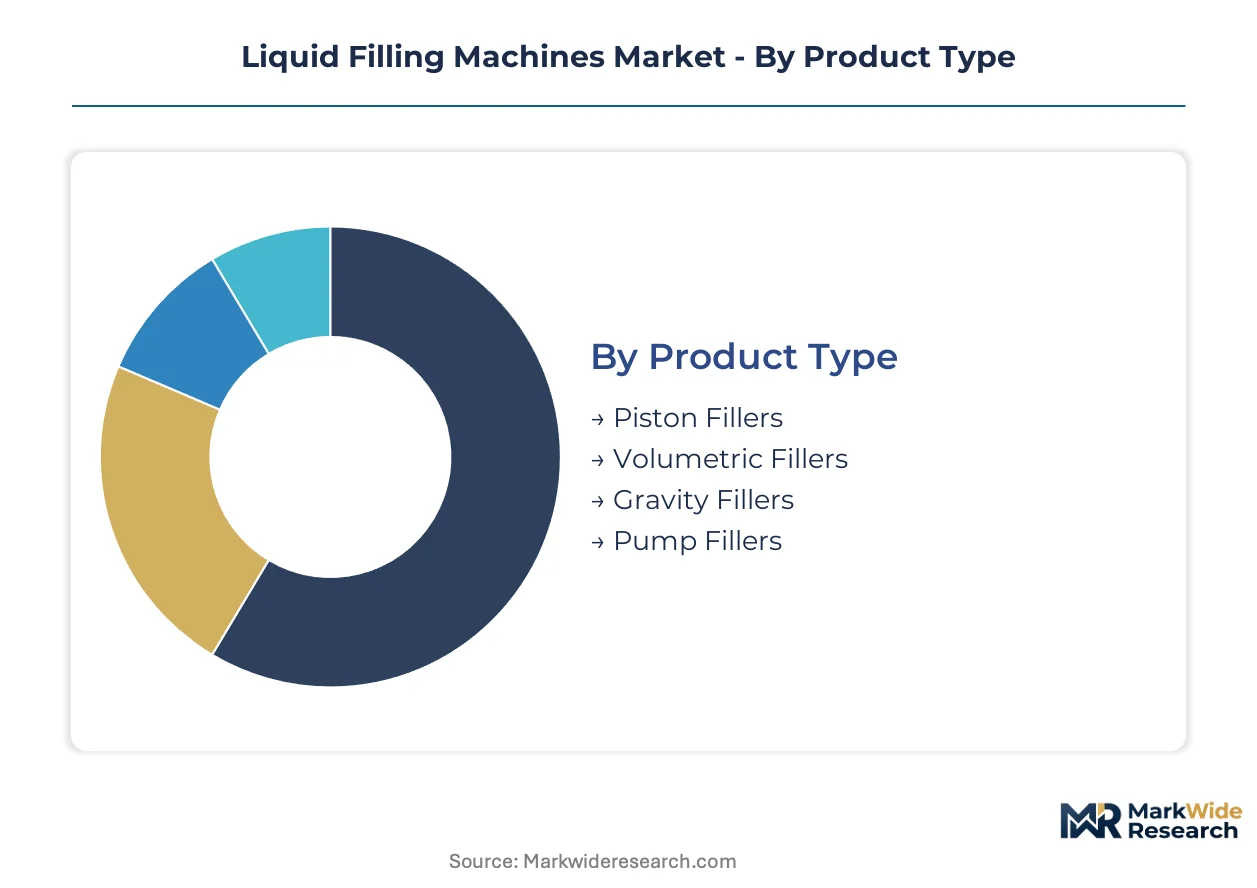
Liquid filling machine procurement follows distinct technical and commercial logics across product architectures, end-use applications, and automation tiers. Segmentation clarity enables suppliers to align R&D pipelines with specific compliance burdens and throughput requirements.
Product Type:
Mature gravity and piston architectures dominate installed capacity, while emerging volumetric platforms capture premium pharmaceutical and high-viscosity food processing contracts.
- Volumetric Fillers:Positive-displacement systems using rotary valves or servo-controlled pistons to deliver precise doses independent of viscosity or container geometry. Pharmaceutical manufacturers in Germany and the United States specify these for sterile injectable lines where FDA 21 CFR Part 11 batch integrity mandates eliminate manual adjustment points.
- Gravity Fillers:Atmospheric-pressure systems relying on hydrostatic head to fill containers at high speeds with minimal moving parts. Beverage bottlers in Thailand and Vietnam deploy these for water and carbonated soft drink lines where simplicity minimizes downtime and carbon-border tariff exposure drives localization.
- Piston Fillers:Reciprocating positive-displacement pumps handling viscous sauces, dairy creams, and cosmetic emulsions with accuracy tolerances within 0.5 percent.
- Pump Fillers:Peristaltic or gear-pump configurations for shear-sensitive biologics and corrosive chemical formulations requiring isolated product paths.
Volumetric fillers retain volume leadership across pharmaceutical and diversified food applications; gravity fillers hold the steepest expansion curve in Asia-Pacific beverage localization corridors.
End User:
Cost tier stratification separates capital-intensive pharmaceutical validation requirements from price-sensitive commodity food and beverage procurement patterns.
- Pharmaceuticals:Aseptic filling lines with isolator containment, clean-in-place validation, and serialization integration for vials, syringes, and ampoules. CDSCO deadlines in India and EMA Annex I requirements in Europe are compressing equipment refresh cycles to three-year windows.
- Food & Beverage:High-speed rotary and inline systems for dairy, sauces, and bottled water where throughput economics dominate specification sheets. North American dairy processors face EU F-Gas Regulation compliance costs for chilled-product filling configurations.
- Cosmetics:Precision dosing equipment for serums, lotions, and fragrance formulations with emphasis on changeover flexibility for SKU proliferation.
- Chemicals:Explosion-proof and corrosion-resistant configurations for solvents, agrochemicals, and industrial coatings requiring ATEX or IECEx certification.
Food & Beverage retains volume leadership across installed base and annual unit shipments; Pharmaceuticals holds the steepest expansion curve driven by biologics capacity buildouts and serialization mandates.
Technology:
Customer type differentiation separates multinational anchor bottlers pursuing full automation from regional contract manufacturers balancing flexibility with capital constraints.
- Automatic:Servo-controlled systems with integrated machine vision, reject handling, and SCADA connectivity operating at 200-1,200 units per minute. These systems anchor new pharmaceutical installations in New Jersey and North Carolina where contract manufacturers deploy deep-learning defect classification at 85 percent of greenfield sites.
- Semi-Automatic:Operator-assisted configurations for mid-tier bottlers and pilot-scale pharmaceutical batches where changeover speed outweighs line speed economics.
- Manual:Benchtop units for artisanal cosmetics, craft beverages, and clinical trial material production with batch sizes below 1,000 units.
- Inline:Linear conveyor-based architectures for rectangular containers and unstable packages unsuited to rotary turret handling.
Automatic technology retains volume leadership in pharmaceutical and high-volume beverage applications; Semi-Automatic holds the steepest expansion curve among contract manufacturers and emerging market mid-tier entrants.
Container Type:
Supply concentration in blow-molded PET and glass bottle formats shapes filler tooling standardization, while pouch and can alternatives demand specialized handling mechanisms.
- Bottles:PET, HDPE, and glass containers from 50 milliliters to 5 liters requiring neck-handling star wheels and turret-based rotary filling. Gravity and volumetric platforms both configure extensively for this format.
- Jars:Wide-mouth glass and plastic containers for sauces, creams, and condiments demanding positive piston displacement to manage thick, particulate-laden products.
- Pouches:Flexible stand-up and flat formats for beverages, detergents, and liquid foods requiring specialized spout-insertion and fill-seal integration.
- Cans:Aluminum and steel beverage and aerosol containers with specific seaming and counter-pressure filling requirements for carbonated products.
Bottles retain volume leadership across beverage, pharmaceutical, and chemical applications; Pouches hold the steepest expansion curve in sustainable packaging substitution and e-commerce-optimized liquid product formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO serialization deadlines in India and FDA 21 CFR Part 11 enforcement in the United States are accelerating equipment refresh cycles across pharmaceutical manufacturing corridors. Carbon-border adjustment mechanisms in the European Union are simultaneously driving beverage bottlers toward localized production in Southeast Asia.
United States
Contract manufacturers in New Jersey and North Carolina are deploying machine vision systems at 85% of greenfield pharmaceutical installations to satisfy FDA 21 CFR Part 11 electronic records mandates. The FDA's sterile drug manufacturing guidelines are eliminating manual intervention points in aseptic filling operations. Boston-area biotech clusters are retrofitting legacy Allen-Bradley SCADA platforms to achieve compliant audit trails.
Germany
EMA Annex I requirements for high-potency drug containment are compressing equipment procurement windows to three-year cycles in Baden-Württemberg and Bavaria. The EU F-Gas Regulation is forcing costly refrigerant retrofits in chilled-product dairy processing lines. Stuttgart-area precision component suppliers dominate servo drive and flow meter fabrication for European pharmaceutical OEMs.
India
PLI scheme incentives for active pharmaceutical ingredients are attracting turnkey isolator line deployments in Hyderabad and Ahmedabad manufacturing clusters. CDSCO serialization deadlines for domestic drug distribution are mandating automated batch integrity systems. Contract manufacturers in these corridors are expanding capacity to serve European and North American export markets.
Japan
PMDA serialization mandates for pharmaceutical track-and-trace are driving isolator technology adoption in Osaka and Tokyo pharmaceutical manufacturing zones. METI industrial policy is supporting precision equipment upgrades for biologic drug formats. Domestic bottlers are localizing gravity filler capacity to reduce carbon-border exposure on packaged beverage exports.
Vietnam
Carbon-border tariff avoidance is accelerating gravity filler installations in Ho Chi Minh City and Hanoi beverage bottling corridors. Multinational bottlers are relocating water and carbonated soft drink production from China to capture EU market access. Local contract manufacturers are leasing automatic rotary lines through equipment-as-a-service financing to bypass upfront capital constraints.
Liquid Filling Machines Market Competitive Environment
On the supply side, the industry is tiered between precision-engineered pharmaceutical specialists and high-volume beverage systems fabricators. German and Swiss builders dominate isolator containment and aseptic validation protocols, while Asian fabricators capture gravity filler volumes through cost-optimized rotary architectures. Two strategic archetypes define competitive positioning: full-line integrators bundling financing with predictive maintenance, and component specialists supplying servo drives and flow meters to third-party assemblers. M&A activity concentrates on isolator technology acquisitions and captive finance arm expansion.
Within the full-line integrator tier, Krones and GEA Group exemplify equipment-as-a-service business model innovation, while Syntegon occupies a position anchoring pharmaceutical-grade containment systems. Krones leverages its captive finance arm to place turnkey rotary filler lines without upfront capital expenditure. GEA Group sustains European dairy market presence through long-term service contracts bundling volumetric fillers with predictive maintenance. Syntegon competes on containment integrity and clean-in-place validation rather than throughput metrics alone.
| Leading Market Players |
|---|
| Krones |
| GEA Group |
| Syntegon |
| JBT Corporation |
| Bosch Packaging Technology |
| Accutek Packaging Equipment |
| KHS GmbH |
| PACKO Filling Systems |
| Groninger & Co. |
| Others |
Value Chain & Pricing Dynamics
German precision component suppliers in Baden-Württemberg and Bavaria anchor servo drive and flow meter fabrication, concentrating margin capture upstream while pharmaceutical OEMs downstream absorb validation-heavy cost structures. Stainless steel 316L and 304 grade contact surfaces account for 35-40% of bill-of-materials costs, tethering equipment pricing to nickel and chromium commodity cycles.
Pricing Analysis
Certification level creates the primary spread across liquid filling machine tiers. FDA 21 CFR Part 11-compliant pharmaceutical-grade isolator systems command premium positioning against standard food-contact configurations. Three-tier pricing structure across premium, standard, and economy levels separates containment-integrity validated lines from beverage-grade gravity fillers. Cost compression in mid-tier volumetric platforms is intensifying because contract manufacturers in India and Vietnam lease equipment-as-a-service rather than purchase outright. Regional bottlers in Southeast Asia exhibit highest price sensitivity, while sterile drug manufacturers in Germany and the United States prioritize compliance over unit economics.
Supply Chain Analysis
Contract manufacturers in Hyderabad, Ahmedabad, and Ho Chi Minh City hold expanding capacity for turnkey isolator line assembly. Component sourcing draws from Germany for precision servo systems, China for stainless steel fabrications, and Italy for rotary turret mechanisms. Single-source vulnerability concentrates in Baden-Württemberg servo drive suppliers. Distribution runs through OEM captive finance arms and third-party equipment-as-a-service platforms serving mid-tier bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as serialization mandates and carbon-border mechanisms splinter demand into compliance-specialized niches across pharmaceutical, beverage, and biologic processing corridors.
For Market Incumbents: Build regulatory certification moats through EMA Annex I and FDA 21 CFR Part 11 validation depth that emerging Asian fabricators cannot replicate. Deepen backward integration into precision flow meter manufacturing to reduce exposure to German component concentration. Anchor long-term service contracts bundling predictive maintenance with volumetric filler deployments, locking out competitors from installed base revenue streams. For New Entrants and Emerging Players: Mid-market beverage bottlers in Vietnam and Indonesia represent the most penetrable entry point, where equipment-as-a-service financing bypasses upfront capital barriers that favor incumbent OEMs. Single-use disposable filling paths for cell and gene therapy biologics offer white space uncontested by stainless steel legacy suppliers. Go-to-market leverage rests on IIoT-native predictive analytics platforms that unbundle after-sales service from mechanical maintenance contracts. For Investors and Strategic Acquirers: Capital is best deployed toward isolator technology specialists with clean-in-place validation capabilities and pharmaceutical-grade containment IP. Long-term viability centers on regulatory compliance automation rather than throughput speed alone. Watch CDSCO enforcement timelines in India as inflection signal for contract manufacturing capacity buildouts.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Financing Expansion | Krones and GEA Group use captive finance arms to place turnkey lines without upfront capex. |
| Isolator Technology Acquisition | Containment-integrity capabilities differentiate Syntegon in high-potency drug manufacturing corridors. |
| Predictive Maintenance Platform Development | IIoT-native analytics unbundle traditional OEM service contracts into component-level subscriptions. |
| Single-Use Disposable Path R&D | Cell and gene therapy formats demand filling systems that eliminate stainless steel contamination risks. |
| Regional Manufacturing Localization | Carbon-border tariffs drive gravity filler assembly in Vietnam and Thailand for EU market access. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and OEM financial disclosures. Plant engineers at dairy processors, pharmaceutical manufacturing heads, and aftermarket service directors provided operational perspective on equipment procurement cycles. Validation drew from FDA 21 CFR Part 11 guidance documents, EMA Annex I technical specifications, CDSCO serialization circulars, and SEC filings of listed equipment manufacturers. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Forecast inputs incorporate machine-level throughput specifications, regional regulatory compliance deadlines, and carbon-border adjustment mechanism implementation timelines. Segmentation dimensions span product architecture, end-use application, automation tier, and container format. CAGRs derive from installed base refresh cycles, capacity expansion announcements, and equipment shipment patterns. Pharmaceutical serialization mandates and beverage localization decisions anchor demand-side modeling.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity prices, euro-yen exchange rates, or EU F-Gas Regulation enforcement intensity would shift the trajectory. Quarterly review of CDSCO deadline adherence, carbon-border tariff implementation, and servo drive supplier capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Automatic Auger Fillers Market
Packaging Machinery
Tray Former Machines Market
Packaging Machinery
Global Pet Stretch Blow Molding Machines Market
Packaging Machinery
Global Tissue Paper Converting Machines Market
Packaging Machinery
Twist Tie Machines Market
Packaging Machinery
Automatic Banding Machine Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
Packaging Conveyors Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Metal Banding Machine Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Rotary Sealers Market