
 Granule Filling Machine Market | 2026-2036
Granule Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Granule Filling Machine Market Foresight
Market Context with Strategic Players
Modular packaging lines with interchangeable dosing units is restructuring how pharmaceutical and food processors configure capital budgets. Bosch Packaging Technology leverages its integrated controls portfolio to anchor premium automatic installations across European pharmaceutical clusters. All-Fill Inc. competes in North American contract packaging through servo-driven auger systems that handle abrasive granules without degradation. Krones AG dominates beverage-adjacent granule applications, extending its rotary filler architecture into nutritional powders and instant coffee.
Technical Definition and Structural Segments
Granule filling machines are precision dosing systems that measure and dispense free-flowing particulate solids into rigid or flexible containers using auger, cup, or weigh-cell mechanisms, with throughput rates spanning fifty to over one thousand units per minute depending on configuration. These machines serve pharmaceutical tablet counting, food seasoning portioning, and agricultural chemical packaging where net-weight accuracy directly determines regulatory compliance and material yield. Automatic installations command the largest installed base due to labor cost arbitrage, though modular configurations represent the fastest-expanding category as manufacturers seek line reconfigurability between batch sizes. Inline systems sustain margin pools in high-volume beverage and dairy powder operations where continuous motion minimizes dwell time, while standalone units occupy niche positions in cosmetics and specialty chemical contract manufacturing.
Regulatory Frame and Forward-Looking Close
FDA 21 CFR Part 211 and EU MDR impose container closure integrity and batch record requirements that elevate demand for electronic check-weighing and reject systems on all new pharmaceutical installations. India's CDSCO and Germany's KBA-equivalent machinery safety inspectorates enforce divergent certification paths, fragmenting vendor qualification timelines and favoring regional assembly partnerships. Stakeholders must monitor evolving EU AI Act implications for vision-based foreign particle detection algorithms that increasingly supplant mechanical sampling protocols.
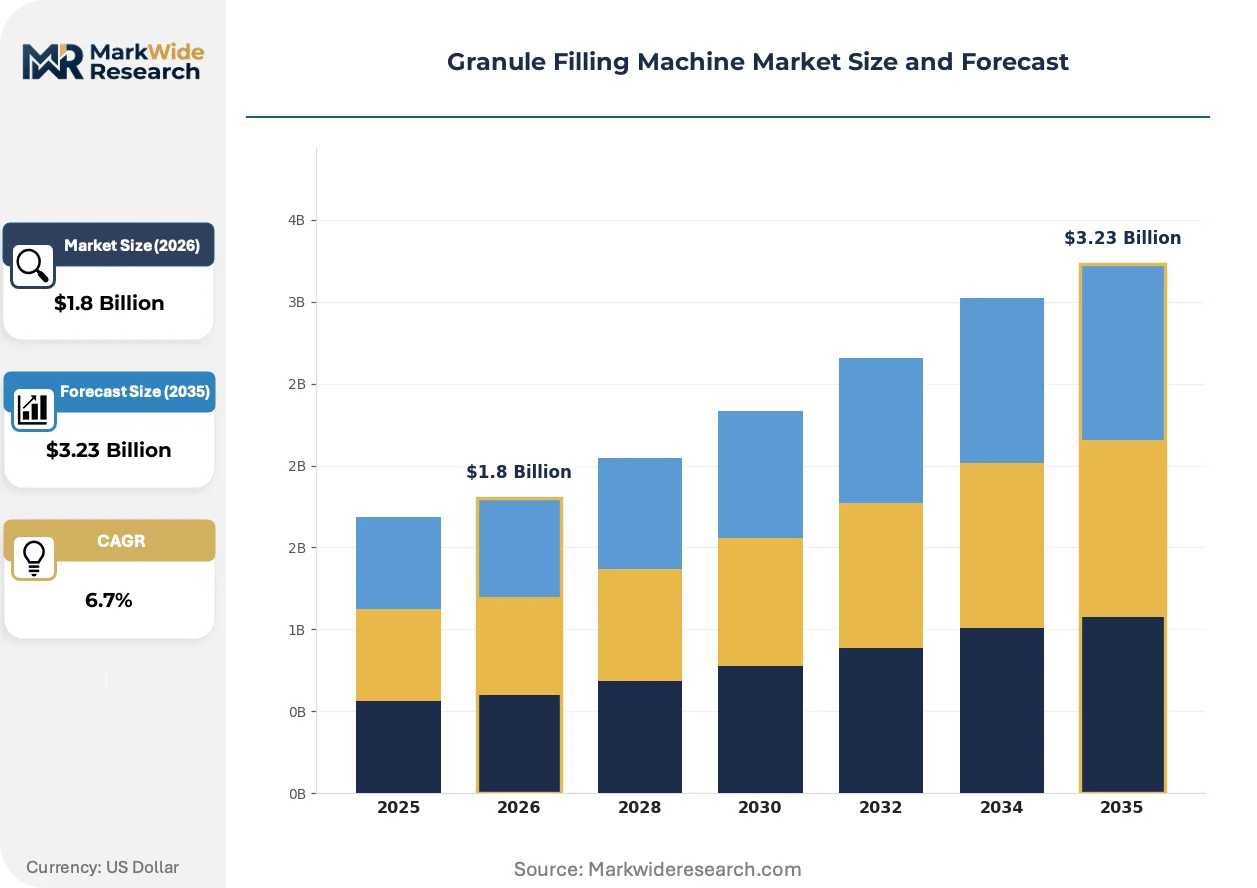
Market Dynamics
Pharmaceutical serialization mandates and food traceability requirements are compressing equipment replacement cycles as manufacturers retrofit existing lines with integrated vision and data-logging systems rather than purchasing greenfield installations.
Growth Catalysts
- EU MDR container closure rules:Medical device manufacturers across Germany and Switzerland are retrofitting filling lines with electronic check-weighing stations to satisfy batch integrity documentation requirements.
- Contract manufacturing expansion:CDSCO enforcement of packaging integrity standards for solid oral dosages is accelerating automatic line installations at Indian pharmaceutical contract manufacturers.
- Servo-driven auger systems:Abrasive granule handling without material degradation is opening food seasoning and agricultural chemical applications previously served by manual operations.
Market Restraints
- Stainless steel price volatility:Grade 316L sheet metal constitutes 35-40% of machine bill-of-materials, exposing European and North American fabricators to nickel market swings.
- Control system import dependence:Mid-cap machinery builders in India and Southeast Asia rely on German and Japanese PLC suppliers, creating lead time vulnerability for complex multi-axis installations.
- Mechanical sampling protocols:FDA 21 CFR Part 211 still permits statistically-based manual inspection, slowing adoption of vision-based foreign particle detection despite superior accuracy.
Strategic Opportunities
- Nutraceutical contract packaging:Protein powder and instant coffee portioning in North America is absorbing rotary filler architectures adapted from beverage bottling lines.
- India PLI scheme for pharmaceuticals:Domestic machinery suppliers near Mumbai and Pune are qualifying for capital subsidy tiers that narrow the cost gap with European imports.
- AI Act algorithmic inspection:Vision-based reject systems using machine learning for particle classification will gain competitive preference as EU conformity assessment pathways mature.
Industry Challenges
- Mechatronics technician scarcity:Integration of servo drives, load cells, and vision systems requires cross-functional expertise that vocational programs in Central Europe and North America are not producing at replacement rates.
- Legacy MES integration:Brownfield pharmaceutical sites running 1990s-era batch management software face protocol translation costs that erode ROI projections for new filling equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Granule Filling Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Electronic Installation: Inline, Standalone, Modular, Portable End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Capacity: Low Capacity, Medium Capacity, High Capacity, Bulk Capacity |
| Companies Covered | IMA Group, Bosch Packaging Technology, All-Fill Inc., Filling Equipment Co. Inc., Groninger & Co. GmbH, Krones AG, Tetra Pak International S.A., GEA Group, Serac Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Granule Filling Machine Market Shifts & Advancements
Equipment architecture is pivoting from fixed-purpose lines toward reconfigurable platforms that accommodate multiple container formats and dosing mechanisms without mechanical changeover downtime.
Interchangeable dosing units with quick-release tooling are modularizing how pharmaceutical and food processors structure capital deployment. Mid-cap manufacturers in the Netherlands and Denmark are adopting these configurations to stretch equipment utilization across shrinking batch sizes and seasonal demand swings. This shift is compressing the traditional five-to-seven-year replacement cycle into three-to-four-year upgrade intervals.
REACH restrictions on lubricant formulations are forcing machinery builders to qualify synthetic alternatives for high-speed auger bearings and cam mechanisms. The industrial consequence is extended qualification timelines for European-bound equipment, with documentation burdens falling heaviest on rotary filler architectures serving dairy powder applications. German suppliers are responding by pre-certifying lubricant portfolios across multiple equipment classes.
After-sales service unbundling is fragmenting how buyers evaluate total cost of ownership. Pharmaceutical contract manufacturers in Maharashtra and Gujarat are separating spare parts procurement from technical support contracts, driving domestic suppliers to publish component-level pricing. This pattern is most visible where CDSCO inspection frequency has elevated preventive maintenance priority above capital equipment specifications.
Granule Filling Machine Market Segmentation
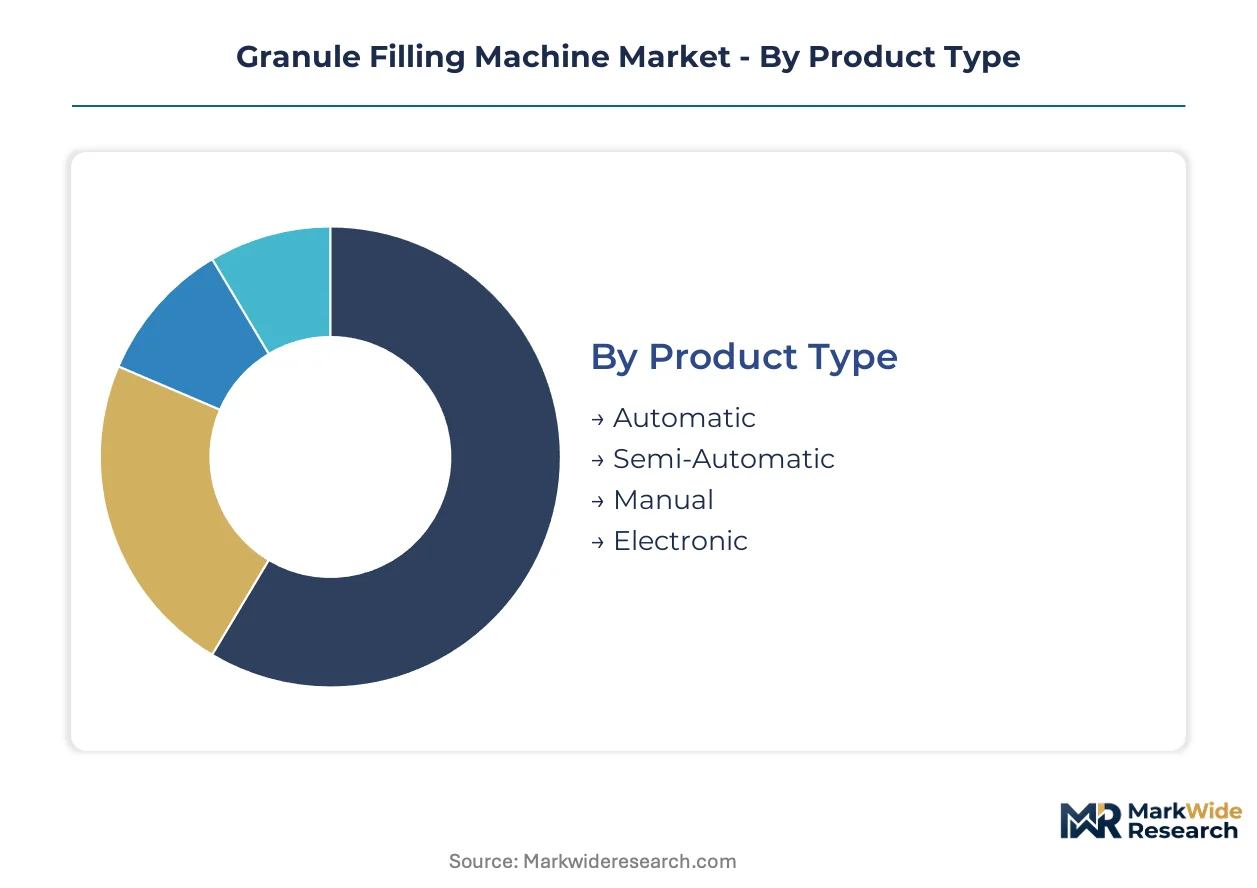
Granule filling machine segmentation reveals how capital deployment strategies diverge between integrated pharmaceutical operations and flexible contract packaging environments. Equipment configuration choices directly determine batch integrity compliance, line reconfigurability, and total cost of ownership across divergent regulatory jurisdictions.
Product Type:
Standalone units serve isolated dosing operations while embedded automatic systems anchor continuous production lines requiring synchronized material flow.
- Automatic:Servo-driven auger and cup mechanisms achieve fifty to over one thousand units per minute with electronic check-weighing integration. Pharmaceutical manufacturers in Maharashtra's Mumbai-Pune belt are expanding these installations as CDSCO tightens packaging integrity documentation for solid oral dosages.
- Semi-Automatic:Operator-assisted dosing with mechanical indexing balances throughput against capital constraints. Contract seasoning packagers in Gujarat deploy these configurations for abrasive spice blends where full automation cannot justify batch scale.
- Manual:Hand-fed hopper systems with gravity discharge serve micro-batch cosmetics and specialty chemical applications. These units occupy niche positions where formulation variability exceeds mechanical changeover feasibility.
- Electronic:Load cell-based gravimetric dosing with programmable recipe management targets high-value pharmaceutical APIs. Swissmedic and FDA 21 CFR Part 211 batch record requirements are elevating demand for these systems in European and North American sterile facilities.
Automatic installations lead volumes today; electronic configurations are gaining share fastest in regulated pharmaceutical environments.
Installation:
Physical integration architecture determines whether equipment operates within synchronized material flow or as isolated dosing nodes.
- Inline:Continuous-motion rotary fillers with conveyor integration minimize dwell time for beverage-adjacent nutritional powders. Krones AG dominates this architecture where dairy and instant coffee operations demand uninterrupted throughput.
- Standalone:Self-contained units with independent power and control systems serve contract manufacturing sites with irregular batch scheduling. Cosmetics formulators in Denmark and the Netherlands favor these for seasonal demand swings.
- Modular:Quick-release tooling platforms accommodate multiple container formats without mechanical changeover downtime. REACH lubricant restrictions are extending qualification timelines for these European-bound systems.
- Portable:Castor-mounted frames with plug-and-play utilities enable multi-line deployment in shared pharmaceutical facilities. CDSCO inspection frequency is elevating preventive maintenance priority for these configurations in Gujarat and Maharashtra.
Inline systems anchor high-volume operations; modular platforms are expanding most quickly as batch sizes shrink.
End User:
Regulatory stringency and material value density shape equipment specification requirements across divergent processing environments.
- Food & Beverage:Rotary filler architectures adapted from beverage bottling handle protein powders and instant coffee portioning. North American contract packaging demand concentrates here.
- Pharmaceuticals:Container closure integrity rules from FDA, EMA, and CDSCO mandate electronic check-weighing and vision-based reject systems. Serialization mandates are compressing replacement cycles.
- Cosmetics:Precision dosing for abrasive pigments and fragrance encapsulation favors standalone auger systems with quick-clean validation.
- Chemicals:Agricultural chemical packaging with corrosion-resistant 316L stainless steel construction faces nickel price volatility exposure.
Pharmaceuticals command premium specification tiers; food and beverage applications are expanding most rapidly.
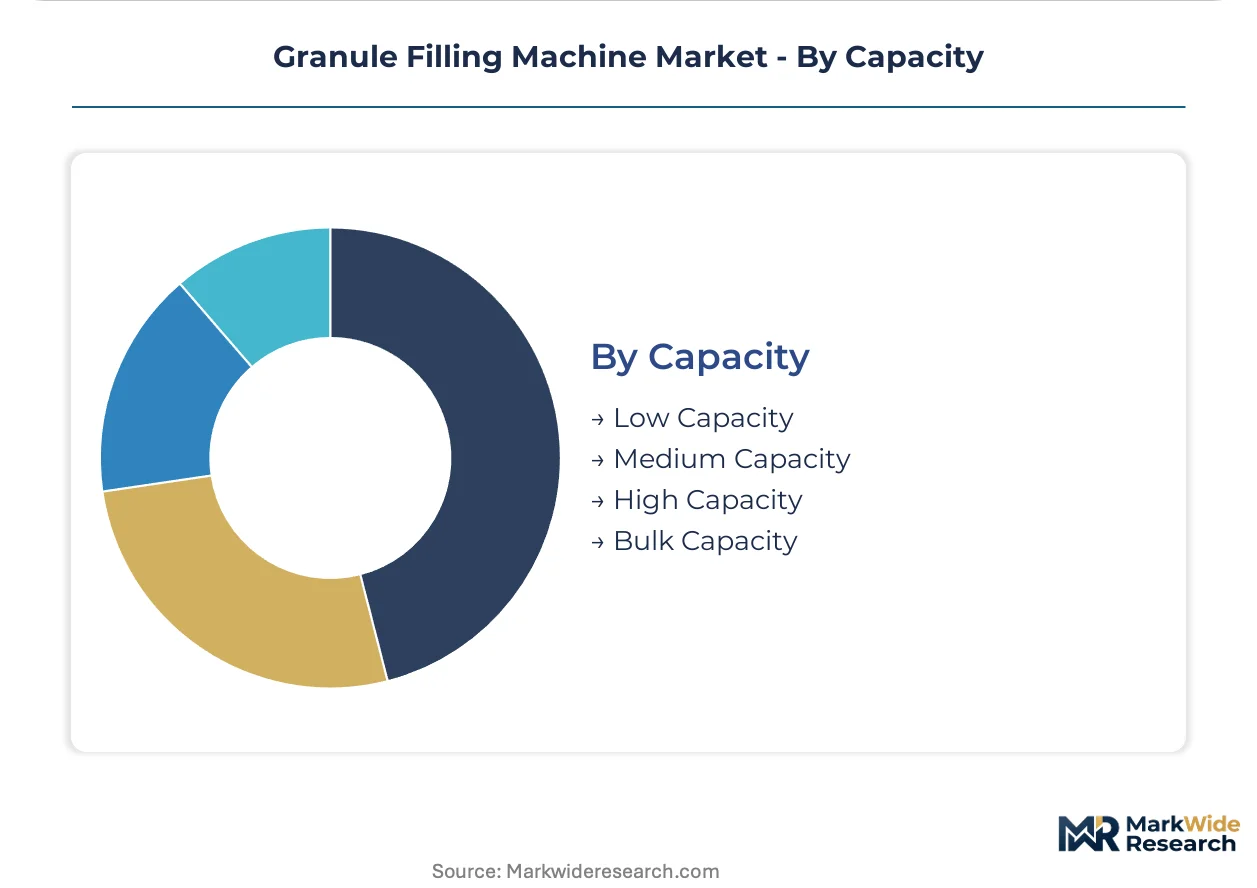
Capacity:
Throughput segmentation aligns equipment scale with batch economics and regulatory sampling protocols.
- Low Capacity:Laboratory-scale units with fifty to two hundred units per minute serve clinical trial material packaging and stability batch production.
- Medium Capacity:Two hundred to six hundred units per minute configurations dominate Indian domestic machinery supplier portfolios competing with European imports.
- High Capacity:Six hundred to one thousand units per minute rotary systems with integrated vision inspection serve high-volume dairy powder operations.
- Bulk Capacity:Super-sack and intermediate bulk container filling with weigh-cell accuracy targets agricultural chemical and industrial mineral applications.
Medium capacity installations lead current procurement volumes; high capacity systems are climbing fastest in beverage-adjacent nutritional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Granule filling machine manufacturing originated in post-war Germany and Switzerland, where precision engineering traditions enabled pharmaceutical-grade dosing systems. European fabricators established quality benchmarks that Asian producers later adapted for cost-sensitive markets.
Germany
Pharmaceutical serialization mandates and EU MDR container closure rules are accelerating retrofit demand at sterile facilities. The KBA machinery safety inspectorate enforces divergent certification paths that favor regional assembly partnerships. Bavaria's pharmaceutical belt around Munich anchors premium automatic line production for export markets.
India
Contract manufacturing expansion and CDSCO packaging integrity enforcement are driving automatic filling line installations. The PLI scheme for pharmaceuticals offers capital subsidies that narrow the cost gap with European imports. Maharashtra's Mumbai-Pune corridor concentrates domestic machinery suppliers competing with imports for mid-capacity installations.
United States
FDA 21 CFR Part 211 batch record requirements are elevating demand for electronic check-weighing and vision-based reject systems. Nutraceutical contract packaging for protein powders and instant coffee is absorbing rotary filler architectures. New Jersey and Pennsylvania pharmaceutical clusters lead retrofit procurement volumes.
China
NMPA pharmaceutical packaging regulations and food traceability mandates are compressing equipment replacement cycles. Domestic fabricators in Jiangsu and Zhejiang provinces are scaling servo-driven auger production for abrasive granule applications. Yangtze River Delta machinery builders compete on lead time for Southeast Asian export markets.
Switzerland
Swissmedic sterile facility requirements and high-value API packaging demand are concentrating electronic gravimetric dosing system procurement. Precision engineering traditions in Basel and Zurich sustain premium-tier fabrication for global pharmaceutical accounts. REACH lubricant restrictions are extending qualification timelines for European-bound modular platforms.
Granule Filling Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and integration complexity. The vendor base separates into three strata: integrated controls specialists commanding pharmaceutical validation premiums, mid-cap regional fabricators competing on delivery speed, and commodity assemblers serving price-sensitive food applications. Two dominant competitive moves are reshaping positioning: pre-certification of lubricant portfolios to compress REACH timelines, and unbundling of after-sales service contracts to capture spare parts revenue.
Among European integrated specialists, Bosch Packaging Technology and Groninger & Co. GmbH occupy positions within the premium-validation tier, anchoring pharmaceutical-grade automatic installations. Krones AG represents the scale-driven archetype, extending rotary filler architectures from beverage bottling into adjacent nutritional powder applications. IMA Group exemplifies portfolio diversification across multiple dosing mechanisms and regulatory jurisdictions.
| Leading Market Players |
|---|
| IMA Group |
| Bosch Packaging Technology |
| All-Fill Inc. |
| Filling Equipment Co. Inc. |
| Groninger & Co. GmbH |
| Krones AG |
| Tetra Pak International S.A. |
| GEA Group |
| Serac Group |
| Others |
Supply & Pricing Matrix
CDSCO-mandated electronic check-weighing retrofits at Indian pharmaceutical contract manufacturers are forcing domestic machinery suppliers to absorb certification costs while European imports maintain premium positioning through pre-validated control architectures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-validated systems from food-grade and commodity packaging equipment. Price differentiation centers on FDA 21 CFR Part 211 compliance tier and after-sales service bundling. Cost compression in mid-capacity Indian domestic supply is intensifying because PLI scheme subsidies narrow the gap with European imports. Contract seasoning packagers in Gujarat exhibit highest price sensitivity; Swiss sterile facilities show least.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and India anchor hub-and-spoke patterns for spare parts and control system components. Machine fabrication draws from Grade 316L stainless steel suppliers in China and India, German and Japanese PLC manufacturers, and synthetic lubricant formulators subject to REACH restrictions. Single-source vulnerability in multi-axis servo drives creates lead time exposure for complex pharmaceutical installations. Distribution runs through OEM-direct channels for premium tiers and domestic assembler networks for mid-capacity Indian supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU MDR container closure rules and FDA serialization mandates are elevating specification thresholds above commodity competition.
For Market Incumbents: Acquire regional service capabilities in Maharashtra and Gujarat to capture unbundled maintenance contracts as CDSCO inspection frequency elevates preventive maintenance priority. Backward integration into synthetic lubricant portfolios compresses REACH qualification timelines for modular platforms. Defensive positioning requires anchoring pharmaceutical validation tiers against emerging Chinese servo-drive competition in Southeast Asian export markets. For New Entrants and Emerging Players: Launch via portable equipment leasing models targeting shared pharmaceutical facilities in Gujarat where CDSCO compliance costs strain capital budgets. White-space concentrates in nutraceutical contract packaging for protein powders and instant coffee in North America, where rotary filler architectures adapted from beverage lines face limited domestic competition. Agricultural chemical packaging in India offers penetrable entry through corrosion-resistant 316L construction at mid-capacity scale. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic Indian machinery suppliers qualifying for PLI scheme capital subsidies while integrating European control architectures. Five-to-ten-year viability favors fabricators with regional assembly partnerships that fragment vendor qualification timelines across divergent inspectorates. Watch EU AI Act conformity assessment pathway maturation as the inflection signal for vision-based reject system adoption displacing mechanical sampling protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-certification of Lubricant Portfolios | German suppliers compress REACH timelines for dairy powder rotary fillers bound for European markets. |
| Service Contract Unbundling | Domestic Indian suppliers publish component-level pricing as Maharashtra contract manufacturers separate spare parts from technical support. |
| Modular Platform Development | Quick-release tooling configurations stretch utilization across shrinking pharmaceutical batch sizes and seasonal food demand swings. |
| Vision-Based Reject System Integration | Machine learning particle classification gains preference as EU AI Act pathways mature for pharmaceutical foreign particle detection. |
| Regional Assembly Partnerships | Fragmented certification timelines across CDSCO, KBA, and FDA inspectorates favor localized qualification for export markets. |
Research Methodology
Bottom-up pharmaceutical and food processor modeling reconciled against top-down machinery shipment tracking forms the analytical core. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers at CDSCO and FDA-inspected facilities combined with secondary validation from customs records, machinery safety inspectorate filings, and pharmaceutical packaging trade databases. Triangulation across stakeholder inputs and secondary sources anchors volume estimates.
Historical trendline analysis of automatic versus semi-automatic installation ratios, capacity tier migration patterns, and regional procurement clusters informed projection frameworks. Segmentation dimensions span product type, installation architecture, end-user industry, and capacity tier alongside regulatory compliance level. CAGRs derive from equipment replacement cycle compression rates and retrofit intensity across pharmaceutical serialization mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel price volatility spikes and REACH lubricant restriction escalations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Lipstick Molding Machines Market
Packaging Machinery
Blind Box Machine Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Glue Machine Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Plastic Vacuum Forming Machinery Market
Packaging Machinery
Cutter-Box Packaging Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Lamination Systems Market
Packaging Machinery
Packaging Machinery Market
Packaging Machinery
Clamshell Labeling Machines Market