
 Auger Powder Filling Machines Market | 2026-2036
Auger Powder Filling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
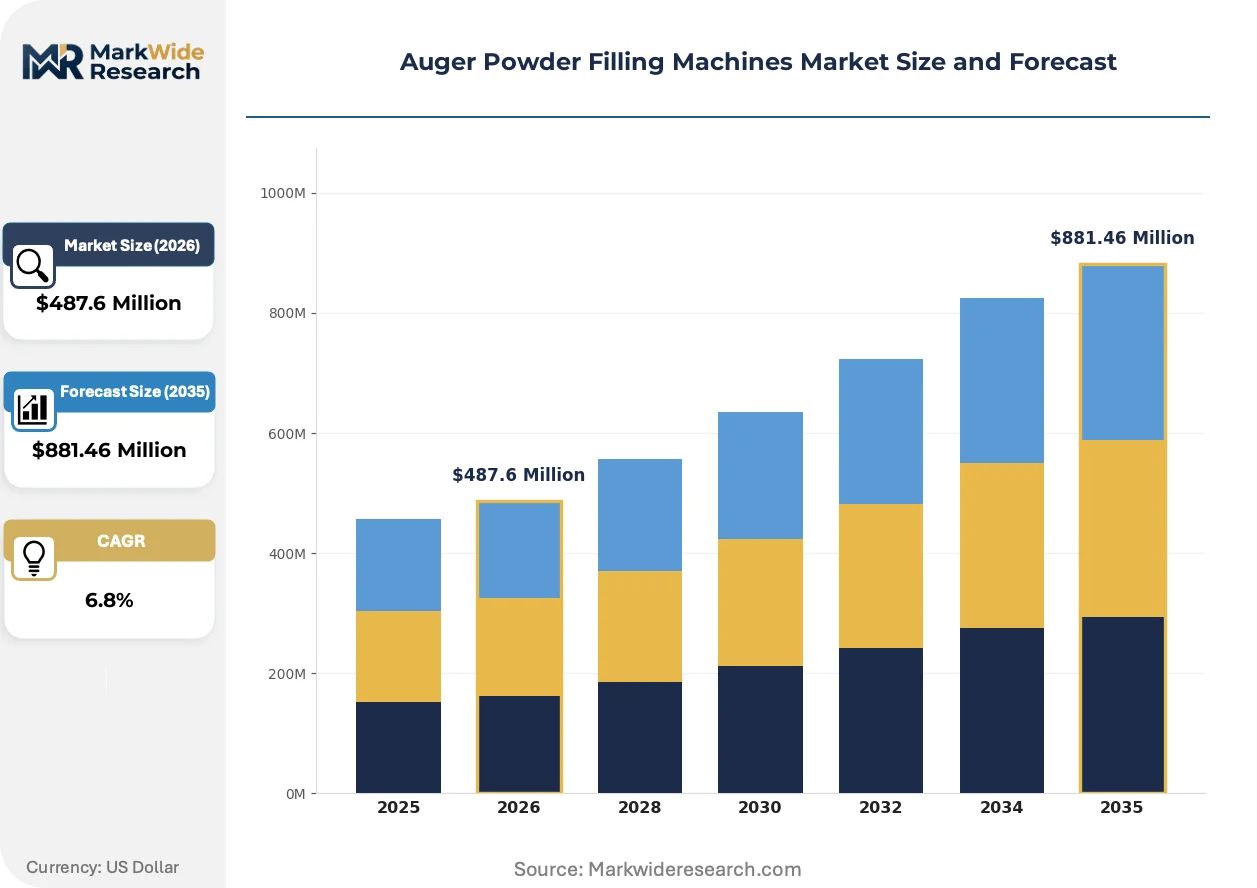
Auger Powder Filling Machines Market Outlook
Multi-source procurement toward integrated single-vendor partnerships is consolidating among large pharmaceutical packagers seeking reduced qualification overhead. All-Fill Inc. leverages its auger technology heritage across both semi-automatic and fully automatic platforms for mid-scale operations. Robert Bosch GmbH anchors European demand through its validated containment systems for potent powder handling. IMA Group competes with integrated lines that combine filling, capping, and serialization in unified footprints.
An auger powder filling machine employs a rotating helical screw to dispense dry, free-flowing or non-free-flowing particulates into rigid or flexible containers with dose weights typically ranging from milligrams to kilograms. The auger mechanism controls fill volume through precise rotation counts, making it indispensable for pharmaceutical tablets, food seasonings, and cosmetic talcs where exact dosing protects consumer safety and regulatory compliance. Fully automatic fillers lead installed capacity in high-throughput pharmaceutical suites, while tabletop fillers capture emerging artisan food producers and compounding pharmacies with limited capital budgets. Electronic control technology is displacing mechanical cam systems as manufacturers prioritize recipe-driven changeovers and real-time torque feedback for powder density variation.
FDA cGMP guidelines and EMA Annex 15 validation requirements shape equipment qualification protocols, compelling vendors to supply comprehensive IQ/OQ documentation and material traceability for product-contact components. ISO 9001 quality management and REACH substance restrictions on lubricants and surface coatings further constrain design choices and supplier qualification. Buyers must weigh total cost of validation against throughput flexibility as powder portfolios diversify into high-potency compounds and allergen-controlled food segments.
Market Dynamics
Electronic control systems are compressing mechanical cam architectures across pharmaceutical and food packaging suites, rewriting equipment qualification protocols and supplier selection criteria as torque-feedback precision becomes the baseline specification.
Growth Catalysts
- FDA cGMP serialization mandates:Pharmaceutical manufacturers in the United States are retrofitting legacy lines with automated auger fillers to comply with track-and-trace requirements for unit-level packaging.
- High-potency compound handling:Containment engineering for cytotoxic and hormonal powders is pulling investment into isolator-integrated filling systems across European contract manufacturing.
- Artisan food scaling:Small-batch spice and supplement producers are adopting tabletop auger units to bridge manual operations and full automation without capital-heavy infrastructure.
Market Restraints
- Stainless steel alloy volatility:Grade 316L price swings and mill lead times are compressing equipment margins and extending delivery schedules for European fabricators.
- Validation documentation burden:EMA Annex 15 IQ/OQ requirements impose six- to twelve-month qualification timelines that freeze capital deployment for mid-scale pharmaceutical packagers.
- Pneumatic dosing substitution:Vacuum and pressure-based powder systems are capturing applications below 500 milligrams where auger torque sensitivity creates unacceptable variability.
Strategic Opportunities
- Indian contract packaging expansion:CDSCO-aligned facilities in Hyderabad and Ahmedabad are scaling dedicated powder lines for export markets, creating demand for validated semi-automatic platforms.
- REACH-compliant lubricant formulations:Bio-based bearing greases and food-grade coatings are opening premium positioning for equipment vendors with full material traceability.
- Serialization-integrated footprints:Combined filling-capping-tracking systems are consolidating floor space in cleanroom-constrained facilities across Germany and Switzerland.
Industry Challenges
- Mechatronics talent scarcity:The convergence of servo engineering, powder rheology, and pharmaceutical validation requires hybrid skill sets that outpace vocational training pipelines in industrial automation hubs.
- Legacy PLC integration friction:Electronic auger controls must interface with twenty-year-old plant networks, forcing costly middleware development or full DCS replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auger Powder Filling Machines Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Fillers, Semi-Automatic Fillers, Fully Automatic Fillers, Tabletop Fillers End User: Pharmaceuticals, Food & Beverage, Cosmetics, Chemicals Application: Granules, Powders, Capsules, Tablets Technology: Vibration, Gravity Feed, Vacuum Fill, Electronic Control |
| Companies Covered | All-Fill Inc., Accutek Packaging Equipment Companies Inc., PER-FIL Industries, Robert Bosch GmbH, Spee-Dee Packaging Machinery, Busch Machinery Inc., AMS Filling Systems Inc., Marchesini Group, IMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auger Powder Filling Machines Market Strategic Shifts
Recipe-driven changeover protocols and real-time density compensation are redefining operational flexibility expectations across powder filling installations.
Machine learning-enabled torque feedback is decentralizing quality control from centralized lab testing to inline process verification. Pharmaceutical suites in Germany and the United States are deploying neural network models trained on powder compressibility curves to auto-adjust auger rotation counts without operator intervention. This shift is compressing batch release timelines and reducing offline sampling labor.
EMA Annex 15 and FDA cGMP updates are tightening material traceability requirements for product-contact components. Equipment vendors must now deliver complete alloy certification chains and surface finish documentation for every auger, hopper, and funnel. European pharmaceutical packagers are responding by consolidating procurement onto suppliers with captive metallurgy capabilities and validated coating processes.
Outcome-based service contracts are displacing traditional break-fix maintenance arrangements in high-throughput pharmaceutical operations. Contract packaging organizations in India and the United States now specify guaranteed uptime percentages and predictive parts replacement in multi-year agreements. This model concentrates vendor risk while transferring operational expertise to equipment manufacturers with remote monitoring infrastructure.
Auger Powder Filling Machines Market Segmentation
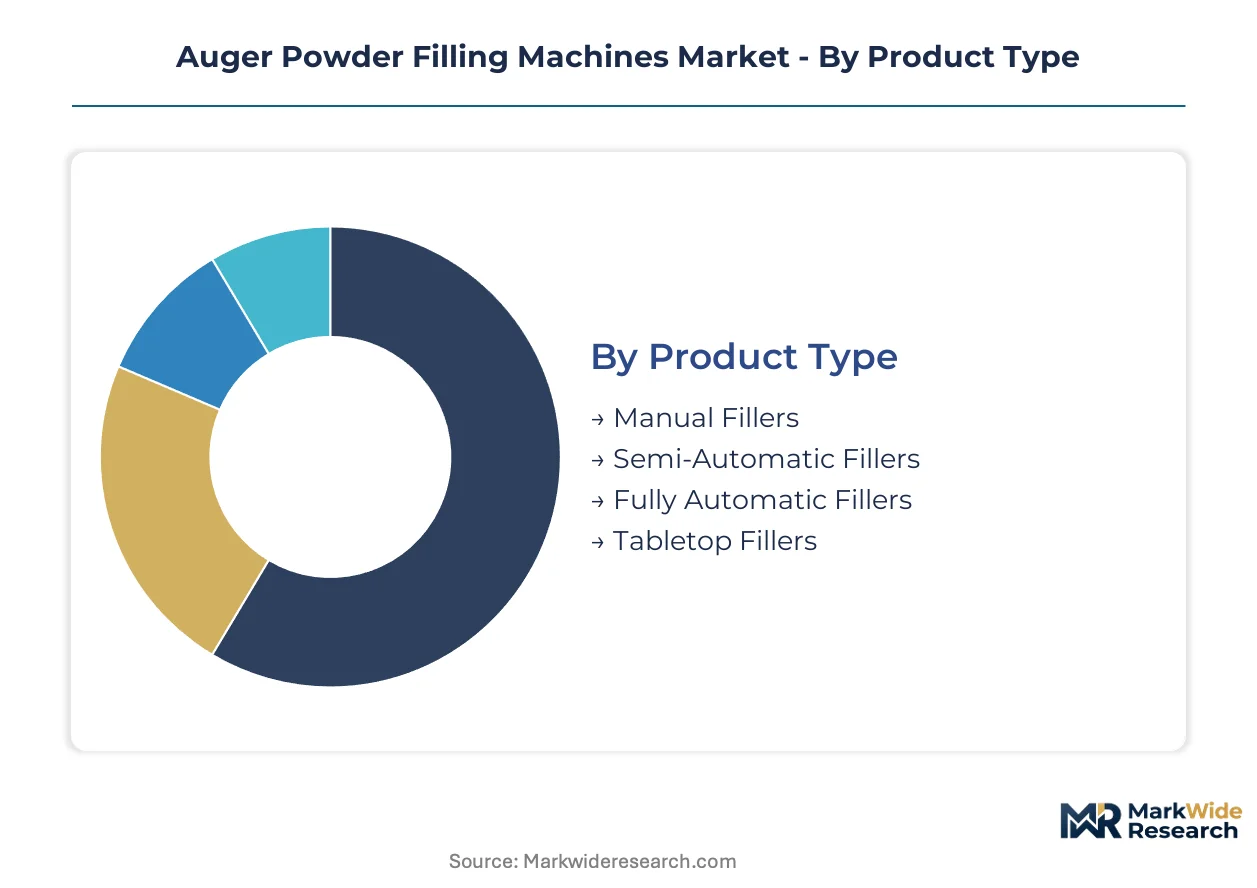
Powder filling equipment segments diverge sharply in validation burden and automation architecture. Pharmaceutical packagers prioritize electronic control systems with FDA-compliant documentation, while food and cosmetic producers navigate lighter certification pathways with different throughput requirements.
Product Type:
FDA cGMP and EMA Annex 15 requirements impose distinct qualification timelines across automation tiers, with fully automatic platforms demanding comprehensive IQ/OQ packages and tabletop units qualifying under abbreviated protocols.
- Fully Automatic Fillers:High-throughput rotary systems integrate servo-driven augers with isolator containment for potent compound handling. Demand concentrates in German pharmaceutical suites where serialization mandates require unified filling-capping-tracking footprints.
- Semi-Automatic Fillers:Intermittent-motion machines bridge manual and automatic operations with recipe-driven changeover capability. Indian contract packaging organizations in Hyderabad and Ahmedabad are scaling these platforms for export-market qualification under CDSCO alignment.
- Tabletop Fillers:Compact units serve artisan food producers and compounding pharmacies with limited capital budgets.
- Manual Fillers:Hand-cranked auger systems persist in specialty chemical batching and small-volume cosmetic production.
Fully Automatic Fillers sit at the top of the volume ranking, with Tabletop Fillers climbing the fastest.
End User:
Cost tiers separate capital-intensive pharmaceutical installations from mid-scale food and cosmetic operations with shorter depreciation horizons.
- Pharmaceuticals:Sterile and potent compound handling drives isolator-integrated auger systems with torque-feedback precision. United States manufacturers retrofit legacy lines to meet FDA track-and-trace mandates for unit-level packaging.
- Food & Beverage:Seasoning and supplement producers balance allergen control against throughput flexibility. REACH-compliant lubricant formulations and food-grade surface coatings constrain equipment selection for European processors.
- Cosmetics:Talc and pigment dosing requires containment engineering for respiratory hazard mitigation.
- Chemicals:Industrial powder handling emphasizes corrosion-resistant alloys and explosion-proof electrical enclosures.
Pharmaceuticals commands the premium pricing tier, while Food & Beverage delivers the steepest expansion trajectory through artisan scaling.
Application:
Volume throughput and dose precision requirements reshape auger geometry and control architecture across powder morphology categories.
- Powders:Free-flowing and cohesive particulates demand real-time density compensation through neural network-enabled torque feedback. German pharmaceutical suites deploy machine learning models trained on compressibility curves to auto-adjust rotation counts without operator intervention.
- Granules:Larger particle sizes reduce segregation risk but require modified auger pitch-to-diameter ratios for consistent dosing.
- Capsules:Hard gelatin and vegetable-derived shells constrain fill weight variability through precision auger control.
- Tablets:In-process powder feeding to tablet presses integrates auger systems with compression force feedback loops.
Powders dominates installed capacity, with Capsules expanding most quickly through high-potency oral solid dosage growth.
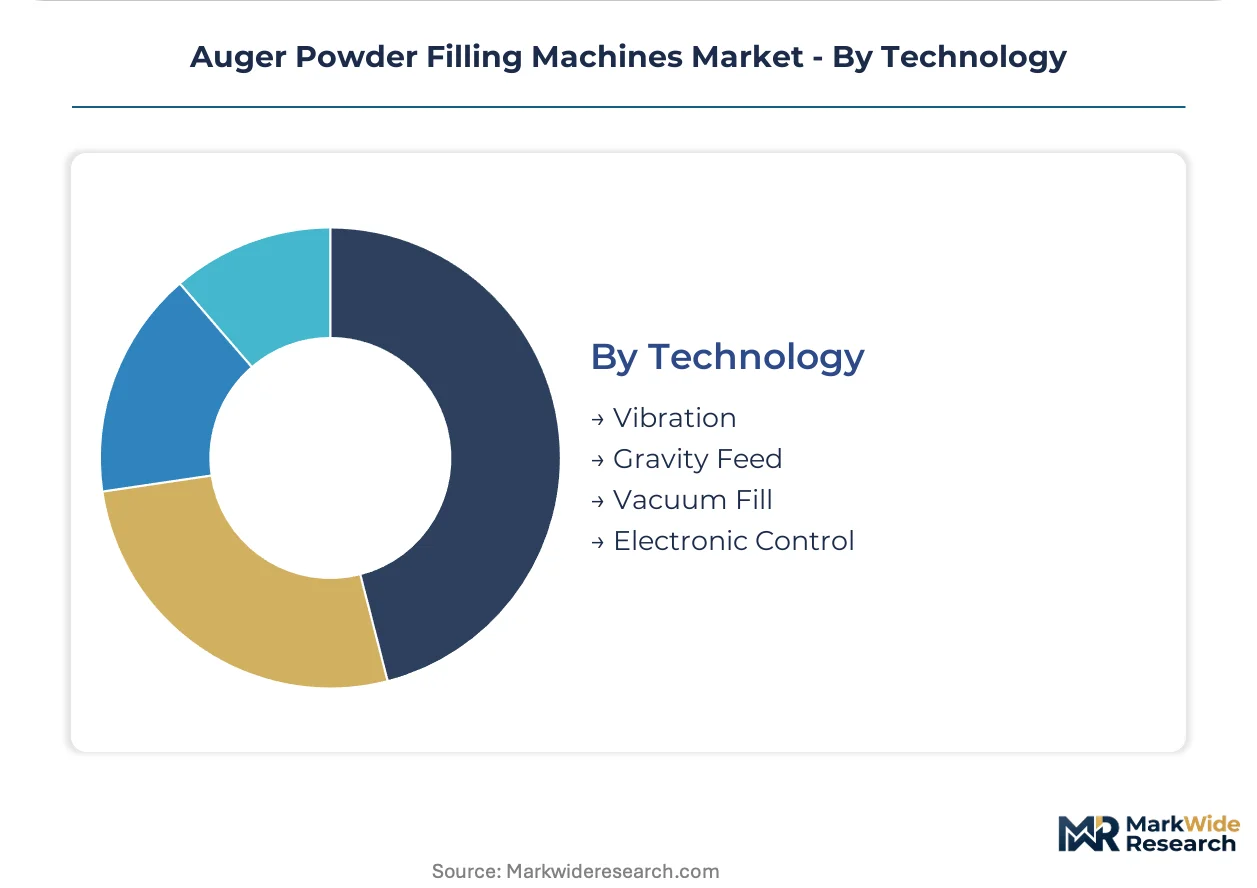
Technology:
Customer procurement patterns favor integrated single-vendor partnerships over multi-source mechanical assemblies as electronic architectures displace legacy cam systems.
- Electronic Control:Servo-driven augers with recipe-driven changeover and real-time torque feedback are displacing mechanical cam architectures across pharmaceutical suites. EMA Annex 15 validation requirements compel comprehensive documentation for these systems.
- Vacuum Fill:Pressure-differential systems capture sub-500 milligram applications where auger torque sensitivity creates unacceptable variability.
- Vibration:Electromechanical agitation assists powder flow in cohesive or arching materials.
- Gravity Feed:Passive powder delivery persists in free-flowing applications with minimal elevation change.
Electronic Control anchors supplier consolidation trends, with Vacuum Fill gaining share fastest in precision micro-dosing niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost arbitrage is redirecting auger filling equipment procurement toward jurisdictions with streamlined qualification pathways, even as FDA and EMA mandates sustain premium demand in established pharmaceutical clusters.
United States
Pharmaceutical contract packagers in New Jersey and North Carolina are retrofitting legacy lines with servo-driven auger systems to meet FDA track-and-trace serialization deadlines. The FDA cGMP guidelines impose comprehensive IQ/OQ documentation requirements that favor vendors with captive validation support teams. Boston-area biotech clusters are driving demand for isolator-integrated fillers as high-potency compound pipelines expand.
Germany
EMA Annex 15 validation protocols and REACH substance restrictions are consolidating procurement onto European fabricators with full material traceability. The Rhine-Main pharmaceutical corridor around Frankfurt maintains dense concentrations of fully automatic rotary auger installations. Bavarian equipment builders are capturing premium positioning through integrated filling-capping-serialization footprints that compress cleanroom floor space.
India
CDSCO-aligned contract packaging facilities in Hyderabad and Ahmedabad are scaling dedicated powder lines for export-market qualification under EMA and FDA standards. The country's national pharmaceutical regulator has tightened GMP inspections, pushing domestic manufacturers toward validated semi-automatic platforms. Pune-based engineering clusters are emerging as fabrication hubs for mid-scale auger systems serving Southeast Asian export markets.
Switzerland
Swissmedic oversight and dense high-potency compound manufacturing are driving demand for containment-engineered auger systems with torque-feedback precision. Basel-area pharmaceutical suites require isolator-integrated fillers for cytotoxic and hormonal powder handling. Zurich equipment vendors are capturing niche positioning through outcome-based service contracts with guaranteed uptime specifications.
China
NMPA alignment with ICH Q7 guidelines and domestic biopharma scaling are pulling investment into electronic control auger architectures. The Yangtze River Delta around Shanghai hosts expanding contract manufacturing capacity for oral solid dosage export. Shenzhen-based automation integrators are developing machine learning-enabled torque feedback systems for real-time density compensation.
Auger Powder Filling Machines Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue modular retrofit kits and subscription-based maintenance models that reduce upfront capital barriers. The supplier base concentrates among three strategic archetypes: European system integrators with validated containment expertise, North American mid-scale specialists leveraging auger technology heritage across automation tiers, and Asian fabricators capturing cost-optimized semi-automatic demand. Competitive positioning hardens around two moves: vertical integration into precision auger machining and strategic partnerships with serialization software vendors to deliver unified filling-tracking footprints.
Among the named participants, All-Fill Inc. and Robert Bosch GmbH occupy positions at opposing ends of the automation spectrum, with the former representing mid-scale flexibility and the latter anchoring high-containment pharmaceutical suites. IMA Group exemplifies the integrated-line archetype that combines filling, capping, and serialization within unified footprints. These three entities collectively illustrate how vendor selection increasingly hinges on validation documentation depth and outcome-based service infrastructure rather than equipment specifications alone.
| Leading Market Players |
|---|
| All-Fill Inc. |
| Accutek Packaging Equipment Companies Inc. |
| PER-FIL Industries |
| Robert Bosch GmbH |
| Spee-Dee Packaging Machinery |
| Busch Machinery Inc. |
| AMS Filling Systems Inc. |
| Marchesini Group |
| IMA Group |
| Others |
Value Chain & Pricing Dynamics
Mechatronics engineering talent concentrated in southern Germany and Switzerland widens pricing spreads between premium servo-driven platforms and economy mechanical systems, as labor-cost differentials in fabrication hubs force tiered positioning across European and Asian supply bases.
Pricing Analysis
Distributor margins compress pricing transparency across pharmaceutical procurement channels, while direct OEM relationships unlock volume discounts for multi-line purchasers. Three-tier pricing structure across premium isolator-integrated, standard servo-driven, and economy mechanical-cam levels separates FDA-validated pharmaceutical suites from food-grade semi-automatic platforms. Pricing pressure stems from Grade 316L stainless steel volatility and extended mill lead times squeezing European fabricator margins. Contract packaging organizations in India exhibit highest price sensitivity, while German pharmaceutical suites prioritize validation documentation depth over unit cost.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Stuttgart, and Milan anchor hub-and-spoke patterns for European pharmaceutical equipment deployment, with secondary nodes in Hyderabad and Ahmedabad serving Asian export markets. Precision auger machining concentrates in Germany, Switzerland, and Japan, while electronic control module assembly rests on Taiwanese and South Korean component flows. Raw material dependencies span Grade 316L stainless steel, servo motors, and REACH-compliant bearing greases. Single-source vulnerability in precision ground screw manufacturing creates chokepoint exposure. Distribution runs through validated equipment dealers for pharmaceutical qualification support and direct manufacturer relationships for high-volume food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The auger powder filling machine market reads as a late-cycle quality story, with pharmaceutical serialization mandates and high-potency containment requirements pulling demand toward premium specifications with comprehensive IQ/OQ documentation.
For Market Incumbents: Anticipate pneumatic dosing substitution below 500 milligram applications and vacuum-fill technology encroachment by investing in machine learning-enabled torque feedback differentiation. Backward integration into captive auger screw machining secures margin control against alloy price volatility. Consolidate procurement relationships with CDSCO-aligned Indian contract packagers scaling export capacity before regional fabricators capture mid-scale semi-automatic demand. For New Entrants and Emerging Players: Capture modular retrofit kit opportunities targeting legacy mechanical-cam installations in North American compounding pharmacies and artisan food producers bridging manual and automatic operations. The most penetrable white-space sits in subscription-based predictive maintenance contracts for high-throughput pharmaceutical suites, leveraging remote monitoring infrastructure to displace traditional break-fix arrangements. Position through REACH-compliant lubricant formulations with full material traceability chains. For Investors and Strategic Acquirers: Pharmaceutical contract packaging organizations are the most active acquirer in this space, seeking validated equipment vendors with integrated serialization footprints to compress vendor qualification overhead. Long-term viability hinges on electronic control architecture dominance and outcome-based service contract penetration. Target acquisition archetype: mid-scale specialists with captive metallurgy capabilities and established FDA documentation libraries. Watch for inflection in Indian CDSCO inspection intensity tightening domestic GMP compliance as signal for validated semi-automatic platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Torque Feedback Integration | Neural network-enabled density compensation compresses batch release timelines for FDA-regulated pharmaceutical suites. |
| Isolator-Containment System Development | Engineered barriers for cytotoxic powder handling capture premium positioning in Swissmedic-regulated Basel manufacturing. |
| Serialization-Integrated Footprint Consolidation | Unified filling-capping-tracking systems reduce cleanroom floor space constraints across EMA Annex 15 facilities. |
| REACH-Compliant Material Traceability Program | Complete alloy certification chains satisfy tightening EMA surface finish documentation requirements for product-contact components. |
| Outcome-Based Service Contract Expansion | Guaranteed uptime specifications with predictive parts replacement transfer operational risk to equipment manufacturers. |
Study Parameters
Multiple input streams — equipment procurement managers at pharmaceutical contract packagers, plant engineers at food processing facilities, regulatory affairs specialists, and aftermarket service heads — were reconciled against secondary validation from FDA 483 inspection observations, EMA GMP inspection databases, CDSCO facility approval records, and customs trade data for powder filling machinery classifications. Bottom-up installation base modeling and top-down pharmaceutical capital expenditure triangulation anchored volume estimates.
Data-stream reconciliation across product type, automation tier, end-use industry, powder morphology category, and regional regulatory cluster enabled segmentation-level projections throughout the forecast period. CAGRs were derived from fitted growth curves calibrated to equipment replacement cycles and regulatory deadline impacts. Forecast inputs incorporated stainless steel price indices, pharmaceutical serialization mandate timelines, and contract manufacturing capacity expansion announcements.
Underlying measurement precision varies by segment; fully automatic pharmaceutical installations carry tighter precision than fragmented artisan food producer estimates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and alloy supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Product Dispensing Machinery Market
Packaging Machinery
High Vacuum Filling Machine Market
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
Packaging Machinery Market
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Air Cushion Machine Market
Packaging Machinery
Automated Poly Bagging Machines Market
Packaging Machinery
Europe Blow Molding Machine Market
Packaging Machinery
Emboss Coding Machine Market
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Clamshell Labeling Machines Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
Paper Napkins Converting Machines Market