
 Middle East and Africa Baby Food Packaging Market | 2026-2036
Middle East and Africa Baby Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Baby Food Packaging Market Foresight
Saudi polyethylene resin producers is realigning output toward food-grade specifications for regional baby food converters. Amcor leverages its Riyadh-based flexible packaging footprint to serve Gulf Cooperation Council dairy and infant nutrition brands. Mondi Group anchors East African demand through Kenyan manufacturing assets that supply pouch substrates to local co-packers.
Middle East and Africa Baby Food Packaging encompasses barrier-coated substrates, sterilizable closures, and portion-controlled formats engineered to preserve nutritional integrity across tropical supply chains. Multi-layer coextrusion and retort-compatible polymers constitute core manufacturing processes, with oxygen transmission rates below 0.5 cc/m²/day required for shelf-stable infant formulations. Pouch formats capture the fastest expansion trajectory as Nigerian and Kenyan parents prioritize portability and reduced per-feed waste. Glass jars retain premium positioning in Gulf retail environments where visual product inspection influences purchase decisions. Pressure-sensitive labeling dominates volume given shorter production runs and frequent regulatory text revisions across heterogeneous national standards.
SFDA in Saudi Arabia and Egypt's national food safety authority enforce divergent additive and migration limit schedules that complicate pan-regional SKU strategies. South Africa's compulsory micronutrient disclosure rules for infant foods extend to packaging information panels, pressuring converters to integrate variable-data printing capabilities. Stakeholders must monitor harmonization negotiations between Gulf standardization bodies and COMESA member states to anticipate whether unified label protocols emerge or fragmentation deepens procurement complexity.
Market Dynamics
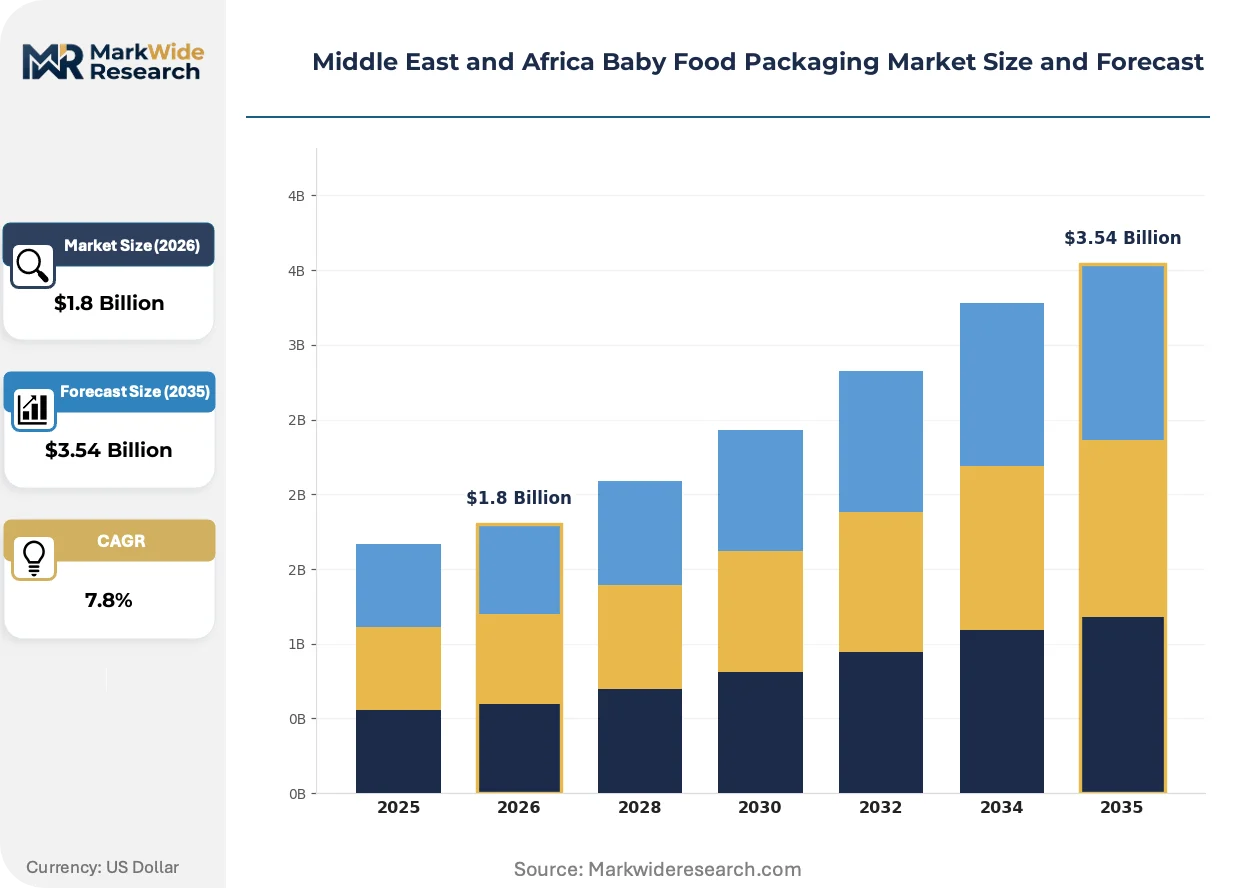
Saudi Arabia's SFDA infant nutrition labeling mandates are compressing production timelines across Gulf Cooperation Council converter facilities. Polyethylene resin realignment toward food-grade specifications is forcing substrate procurement redesigns among regional flexible packaging suppliers.
Growth Catalysts
- SFDA Labeling Mandates:Saudi Arabia's strict infant nutrition disclosure rules are standardizing packaging information panels across Gulf states, creating uniform demand for variable-data printing capabilities.
- Urban Working Parents:South African metropolitan professionals are prioritizing pouch formats for on-the-go feeding convenience, accelerating single-serve substrate adoption in Johannesburg and Cape Town retail corridors.
- Retort-Compatible Polymers:Multi-layer coextrusion technologies enabling oxygen transmission rates below 0.5 cc/m²/day are extending shelf-stable infant formulation viability across tropical Nigerian supply chains.
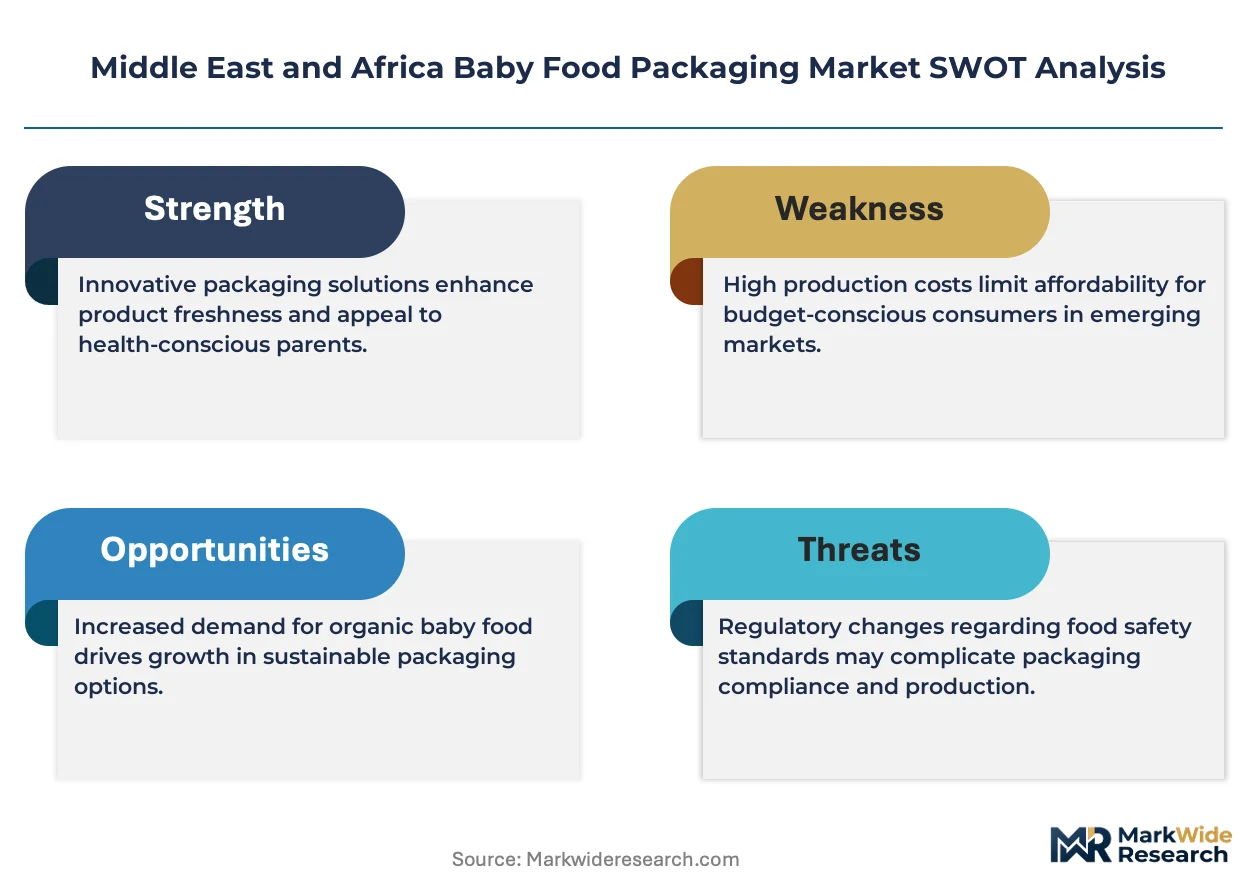
Market Restraints
- Resin Price Volatility:Food-grade polyethylene specification shifts are exposing regional converters to feedstock cost swings from Saudi petrochemical suppliers.
- Regulatory Fragmentation:Divergent additive and migration limit schedules between Egypt's national food safety authority and Gulf standardization bodies complicate pan-regional SKU rationalization.
- Glass Jar Substitution:Premium Gulf retail environments where visual product inspection drives purchase decisions are slowing flexible format penetration in high-margin segments.
Strategic Opportunities
- Kenyan Manufacturing Hub:East African pouch substrate production anchored through local assets can capture COMESA trade corridor expansion before harmonization negotiations conclude.
- COMESA Harmonization:Pending label protocol unification between Gulf standardization bodies and Common Market for Eastern and Southern Africa members could simplify procurement complexity for multi-territory brands.
- E-Commerce Direct Channels:Nigerian demand concentration in Lagos and Abuja retail corridors is creating last-mile delivery optimization potential for subscription-based infant nutrition packaging.
Industry Challenges
- Variable-Data Printing Talent:South Africa's compulsory micronutrient disclosure rules are outpacing regional converter workforce development in digital press operation and regulatory text management.
- Retort Line Capex:Sterilizable closure and barrier-coated substrate certification requires capital-intensive equipment upgrades that strain mid-scale Kenyan and Nigerian co-packer balance sheets.
- Legacy Label Inventory:Frequent regulatory text revisions across heterogeneous national standards are generating obsolete stock write-downs for pressure-sensitive label converters serving shorter production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Baby Food Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Glass Jars, Plastic Containers, Pouches, Tetra Packs Labeling Method: Pressure Sensitive, Shrink Sleeves, In-Mold, Heat Transfer Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Health Food Shops Closure Type: Snap-On Lids, Twist-Off Caps, Flip Top, Rigid Containers |
| Companies Covered | Amcor, Ardagh Group, Mondi Group, Winpak Ltd, Tetra Pak International S.A., AptarGroup, Ball Corporation, Sonoco Products Company, Sealed Air, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Baby Food Packaging Market Shifts & Advancements
Active barrier technologies and digital printing integration are compressing development cycles for infant nutrition packaging. Material science advances are reshaping shelf-life extension capabilities across tropical distribution networks.
Retort-compatible polymer coextrusion is electrifying shelf-stable infant formula preservation standards. Nigerian and Kenyan dairy brands are adopting these substrates at accelerating rates to reduce cold-chain dependency. The technology is electrifying regional distribution reach into secondary cities previously excluded by spoilage constraints.
South Africa's compulsory micronutrient disclosure framework is mandating real-time packaging information panel updates. Infant food manufacturers must now integrate variable-data printing across production batches. Local converters are responding by retrofitting flexographic lines with digital hybrid capabilities to accommodate shorter runs and frequent regulatory text changes.
Subscription-based replenishment models are displacing traditional retail stocking patterns among middle-income Lagos and Abuja households. Direct-to-consumer infant nutrition brands are specifying portion-controlled pouch formats optimized for automated fulfillment. This behavioral shift concentrates demand planning precision requirements among Nigerian co-packers serving e-commerce channels.
Middle East and Africa Baby Food Packaging Market Segmentation
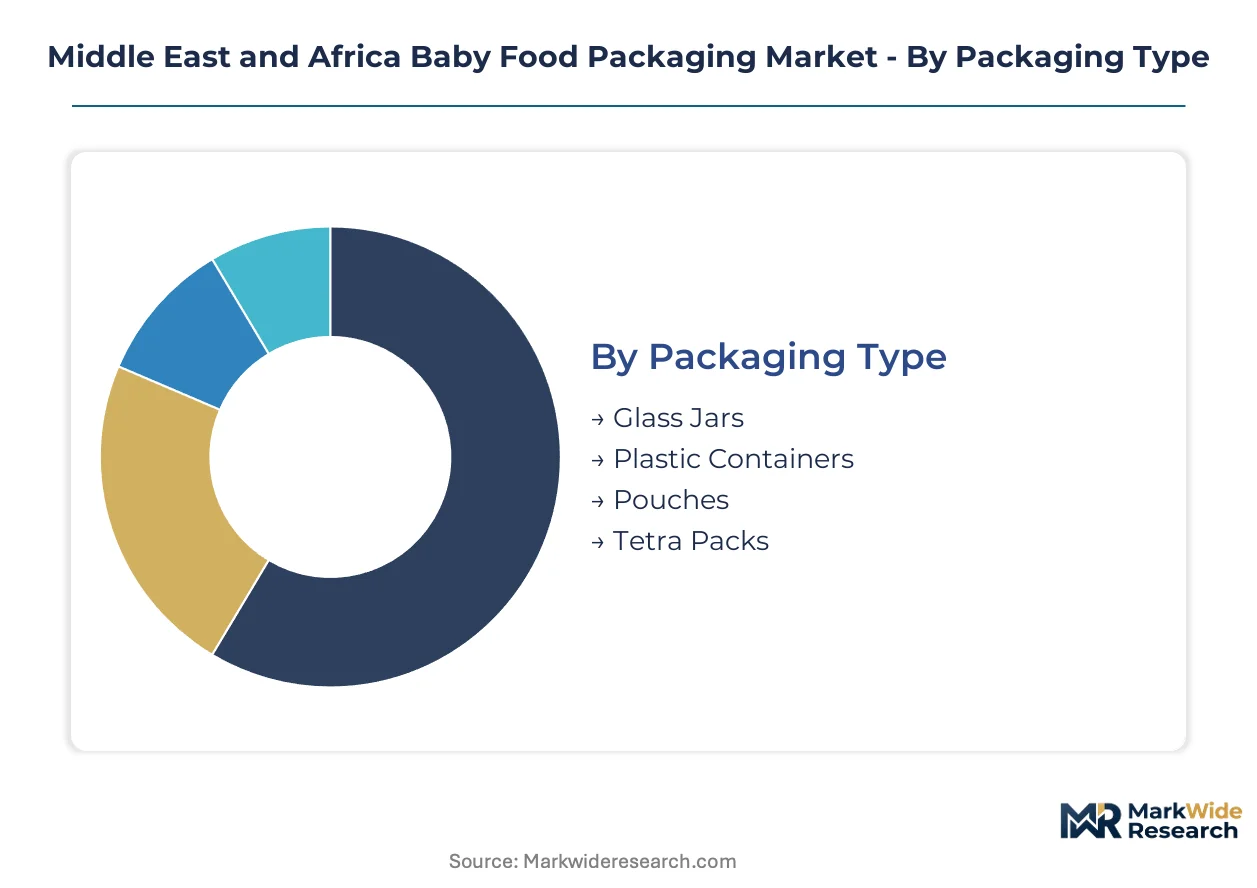
Segmentation in Middle East and Africa Baby Food Packaging reveals how substrate specifications, closure mechanics, and retail channel requirements fragment procurement strategies across tropical supply chains and divergent regulatory environments. Understanding these divides enables converters to align capital deployment with the specific technical and commercial demands of Gulf premium retail versus East African mass-market distribution.
Packaging Type:
Customization versus standardization tensions run deepest here, with premium Gulf retailers demanding visual inspection capabilities while Nigerian and Kenyan distributors prioritize logistics efficiency and breakage reduction.
- Pouches:Multi-layer coextrusion structures incorporating aluminum oxide or ethylene vinyl alcohol barrier layers achieve oxygen transmission rates below 0.5 cc/m²/day. Demand concentrates in Lagos and Abuja retail corridors where urban working parents prioritize single-serve portability for on-the-go feeding scenarios.
- Glass Jars:Borosilicate and soda-lime formulations with wide-mouth finishes support thermal processing and visual product verification. Saudi Arabian and UAE premium retail environments sustain this format where purchase decisions depend on visible texture and color assessment.
- Plastic Containers:Polypropylene and polyethylene terephthalate injection-molded vessels with tamper-evident bands serve South African supermarket channels requiring extended shelf stability.
- Tetra Packs:Aseptic carton systems with aluminum foil laminates dominate ambient distribution networks across COMESA trade corridors with limited cold-chain infrastructure.
Leading the category by volume: Plastic Containers. Growing fastest: Pouches.
Labeling Method:
Production run economics and regulatory revision frequency determine method selection, with shorter Gulf-state production cycles favoring digital-adjacent technologies over dedicated in-mold tooling.
- Pressure Sensitive:Facestock-adhesive-liner constructions enable rapid graphic changes without cylinder or plate investment. South African converters deploy this method to accommodate compulsory micronutrient disclosure rules requiring frequent information panel updates across infant food batches.
- Shrink Sleeves:Polyethylene terephthalate glycol or polylactic acid films provide 360-degree decoration and tamper evidence. Nigerian health food shops and premium supermarket channels specify this format for differentiated shelf presence in crowded Lagos retail environments.
- In-Mold:Polypropylene labels fused during injection molding deliver scratch resistance and premium aesthetics. Gulf Cooperation Council dairy brands specify this for glass jar alternatives in high-margin infant nutrition segments.
- Heat Transfer:Silicone-based release coatings transfer ink through thermal pressure onto curved surfaces. Kenyan manufacturing assets employ this for limited-edition promotional runs serving East African co-packer flexibility requirements.
Pressure Sensitive dominates production volume. Shrink Sleeves expand most quickly in premium channel applications.
Distribution Channel:
Channel selection maps directly to packaging format specifications, with direct-to-consumer growth forcing portion-control and automated-fulfillment compatibility into substrate design criteria.
- Supermarkets:Multi-unit corrugated shelf-ready packaging and promotional display configurations. Johannesburg and Cape Town retail corridors drive standardized case counts and pallet optimization for high-velocity infant formula restocking.
- Online Stores:Subscription-optimized pouch formats with dimensional weight minimization and automated fulfillment compatibility. Lagos and Abuja middle-income households displace traditional stocking patterns through direct-to-consumer replenishment models.
- Convenience Stores:Single-serve impulse formats with extended ambient stability. Nigerian secondary cities beyond Lagos core rely on this channel for infant food access.
- Health Food Shops:Premium positioning with organic certification callouts and tactile substrate differentiation. Saudi Arabian urban centers sustain this channel for specialized infant nutrition segments.
Supermarkets anchor volume throughput. Online Stores gain share fastest among channel alternatives.
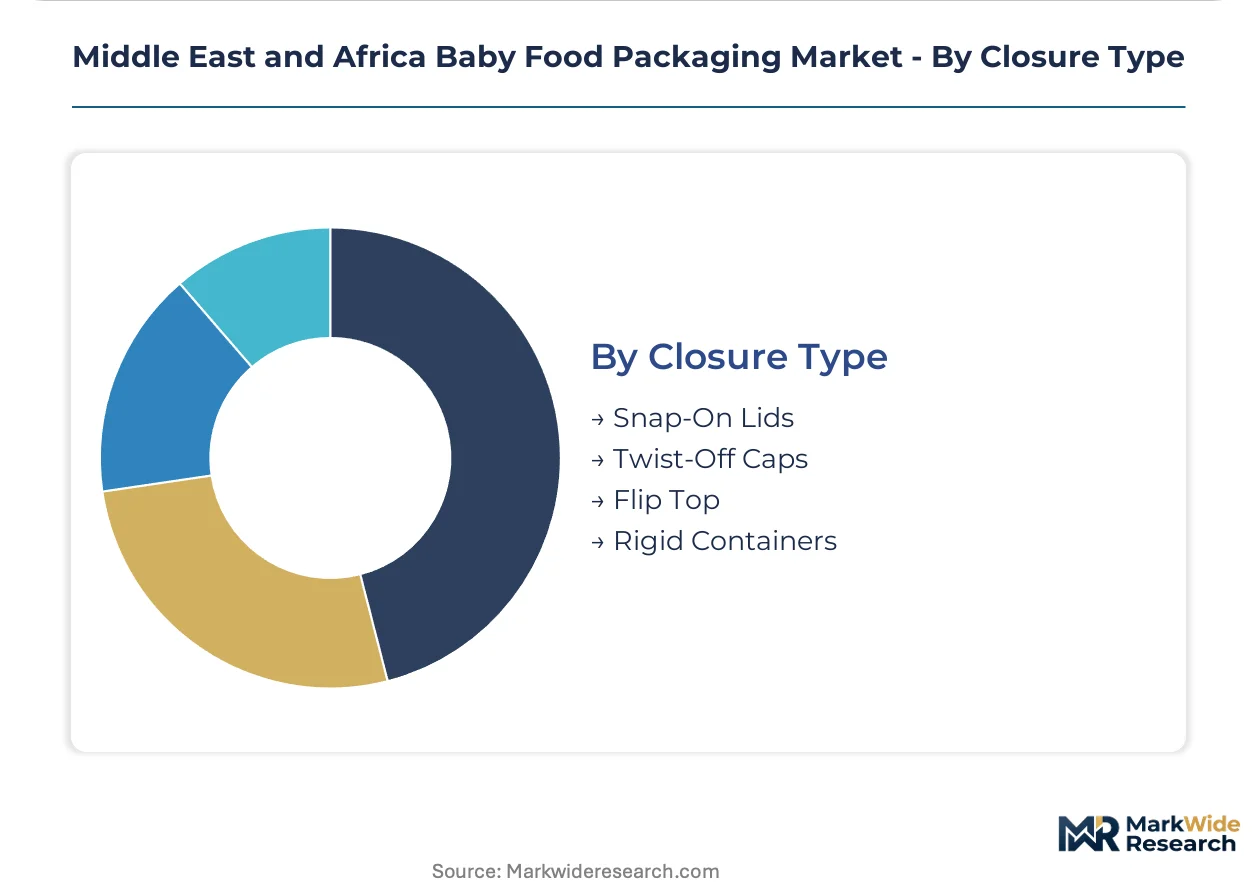
Closure Type:
Sterilization compatibility and reseal functionality create tiered performance requirements, with retort processing demands separating premium specifications from standard mass-market applications.
- Twist-Off Caps:Metal lug or plastic continuous-thread designs with plastisol liners enabling hermetic seals through thermal processing. Glass jar formats in Gulf retail environments specify these for repeated opening cycles and visual tamper evidence.
- Flip Top:Polypropylene living-hinge mechanisms with silicone valves for controlled dispensing. Pouch and flexible container adoption in South African metropolitan areas prioritizes one-handed operation for working parent convenience.
- Snap-On Lids:Injection-molded polyethylene components with audible engagement confirmation. Nigerian plastic container specifications favor these for cost-efficient tamper indication.
- Rigid Containers:Integrated vessel-and-closure systems with interlocking features for stacking stability. Kenyan manufacturing assets supply these to COMESA corridor distributors managing extended overland logistics.
Twist-Off Caps lead by unit volume. Flip Top mechanisms show steepest expansion trajectory in flexible format applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi petrochemical feedstock supplies anchor flexible substrate production across the Gulf, with resin realignment toward food-grade specifications redirecting regional converter procurement patterns.
Saudi Arabia
SFDA infant nutrition labeling mandates compress production timelines for Gulf Cooperation Council converter facilities. The national food safety authority enforces strict additive and migration limit schedules that standardize packaging information panels. Riyadh-based flexible packaging operations serve regional dairy and infant nutrition brands with barrier-coated substrates.
South Africa
Urban working parents in Johannesburg and Cape Town metropolitan corridors drive pouch adoption for on-the-go feeding convenience. Compulsory micronutrient disclosure rules for infant foods extend to packaging information panels. Local converters retrofit flexographic lines with digital hybrid capabilities to accommodate shorter production runs.
Nigeria
Demand concentrates in Lagos and Abuja retail corridors where middle-income households embrace subscription-based replenishment models. The national food safety authority maintains divergent standards from Gulf bodies, complicating pan-regional SKU strategies. Secondary cities beyond Lagos core rely on convenience store channels for infant food access.
Kenya
East African pouch substrate production anchors COMESA trade corridor expansion before harmonization negotiations conclude. Manufacturing assets supply barrier-coated substrates to local co-packers serving regional distribution networks. Nairobi and Mombasa industrial zones concentrate co-packer activity for extended overland logistics.
United Arab Emirates
Premium retail environments in Dubai and Abu Dhabi sustain glass jar formats where visual product inspection influences purchase decisions. MOHAP regulations interface with Gulf standardization bodies on infant nutrition packaging standards. High-margin infant nutrition segments specify in-mold labeling for premium positioning.
Middle East and Africa Baby Food Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue e-commerce-optimized formats and variable-data printing capabilities. The vendor base stratifies across multinational substrate suppliers, regional converter networks, and specialized co-packer operations. Three archetypes dominate: integrated resin-to-package conglomerates, flexible-format specialists, and digital-printing-enabled regional players. Capacity expansion and strategic partnerships constitute the dominant competitive moves as participants align with SFDA compliance requirements.
Among multinational packaging conglomerates, Amcor leverages its Riyadh-based flexible packaging footprint to serve Gulf Cooperation Council dairy and infant nutrition brands, while Mondi Group anchors East African demand through Kenyan manufacturing assets. Tetra Pak International S.A. occupies a position exemplifying aseptic carton systems for ambient distribution networks. These three entities represent the scale-driven, regional-anchored, and technology-licensed archetypes respectively, each responding to divergent regulatory schedules across Middle East and Africa jurisdictions.
| Leading Market Players |
|---|
| Amcor |
| Ardagh Group |
| Mondi Group |
| Winpak Ltd |
| Tetra Pak International S.A. |
| AptarGroup |
| Ball Corporation |
| Sonoco Products Company |
| Sealed Air |
| Others |
Supply & Pricing Matrix
Retort-compatible polymer coextrusion technology adoption simultaneously compresses per-unit production costs and concentrates substrate supply among Saudi and South African converters with certified sterilization capabilities. This dual effect reshapes procurement economics as food-grade polyethylene specification shifts force buyers to qualify fewer qualified suppliers.
Pricing Analysis
Warranty and technical service bundling separates premium-tier Gulf suppliers from unbundled East African mass-market offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and variable-data printing capability. Cost compression in standard-tier pouch substrates intensifies as Kenyan manufacturing assets expand capacity. Price-sensitive Nigerian co-packers serving convenience store channels drive volume, while least-sensitive UAE premium infant nutrition brands prioritize visual inspection compatibility.
Supply Chain Analysis
Dual-sourcing mandates from Saudi dairy brands and South African supermarket chains require converters to qualify resin suppliers across Saudi Arabia, South Africa, and Kenya. Food-grade polyethylene resin, aluminum oxide barrier coatings, and silicone valve components anchor raw material dependencies. Single-source vulnerability concentrates around Riyadh-based petrochemical feedstock. Distribution runs through COMESA trade corridors with Nairobi and Mombasa serving as consolidation hubs for East African last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA infant nutrition labeling mandates erect a cost-of-compliance barrier that rewards incumbent converters with existing variable-data printing infrastructure while straining mid-scale Nigerian and Kenyan co-packer balance sheets.
For Market Incumbents: Cement defensive positioning by acquiring certified retort line capacity in Johannesburg and Cape Town corridors before South African micronutrient disclosure rules expand. Deepen backward integration into food-grade polyethylene resin sourcing through Saudi petrochemical partnerships to offset feedstock cost volatility from regional suppliers.
For New Entrants and Emerging Players: Capture white-space opportunity in subscription-optimized pouch formats serving Lagos and Abuja middle-income households displacing traditional retail stocking patterns. Target Nigerian e-commerce direct channels with automated-fulfillment-compatible portion control specifications as the most penetrable entry vector.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational packaging conglomerates seeking Gulf Cooperation Council regulatory compliance capabilities. Five-to-ten-year viability favors converters with dual SFDA and South African micronutrient disclosure certification. Watch for COMESA-Gulf harmonization negotiations as the inflection signal for pan-regional SKU rationalization plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Retort Line Certification Investment | SFDA sterilizable closure mandates force capital deployment toward compliant Gulf suppliers. |
| Variable-Data Printing Capability Expansion | South African disclosure rules require digital hybrid press retrofits for infant food batches. |
| Food-Grade Resin Backward Integration | Saudi petrochemical realignment creates captive supply advantages for integrated converters. |
| COMESA Trade Corridor Manufacturing Footprint | Kenyan pouch substrate production captures East African demand before harmonization concludes. |
| E-Commerce Channel Format Development | Lagos subscription models demand dimensional-weight-optimized pouch specifications for automated fulfillment. |
Research Methodology
Document review covered SFDA regulatory filings, South African Department of Health micronutrient disclosure guidelines, and COMESA trade statistics, complemented by interviews with flexible packaging plant managers, infant nutrition brand procurement leads, and digital press operations specialists. Secondary validation drew from Saudi petrochemical supplier disclosures, Nigerian retail audit data, and Kenyan manufacturing asset registers. Bottom-up substrate demand modeling triangulated against top-down infant nutrition consumption projections.
Segmentation outputs across packaging type, labeling method, distribution channel, and closure type dimensions fed into analytical framework development over the projection horizon. CAGRs derived from regression analysis against urban working parent population growth and retail channel shift elasticity. Forecast inputs incorporated resin price volatility indices and regulatory revision frequency assumptions.
The model holds under stable SFDA and South African disclosure enforcement; deviation in COMESA-Gulf harmonization timelines or Saudi petrochemical export policy would shift substrate supply economics. A model refresh is warranted upon material change in regional infant nutrition labeling mandate adoption schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food Packaging
Europe Pet Food Packaging Market
Baby Food Packaging
Baby Food Packaging Market
Baby Food Packaging
Baby Care Packaging Market
Baby Food Packaging
United States Baby Food Packaging Market
Baby Food Packaging
APAC Baby Food Packaging Market
Baby Food Packaging
Global Pet Food and Pet Product Packaging Market
Baby Food Packaging
Asia-Pacific Child Resistant Packaging Market
Baby Food Packaging
Breathable Films for Baby Care Market
Baby Food Packaging
United States and Canada Child Resistant Bottles Market
Baby Food Packaging
Infant Formula Packaging Market
Baby Food Packaging
Europe Home Care Packaging Market
Baby Food Packaging
Europe Baby Food Packaging Market
Baby Food Packaging
US Pet Food Packaging Market
Baby Food Packaging
North America Home Care Packaging Market