
 In-Line Thermoforming Machine Market | 2026-2036
In-Line Thermoforming Machine Market Size, Share, and Industry Trends Forecast 2026-2036
In-Line Thermoforming Machine Market Analytics
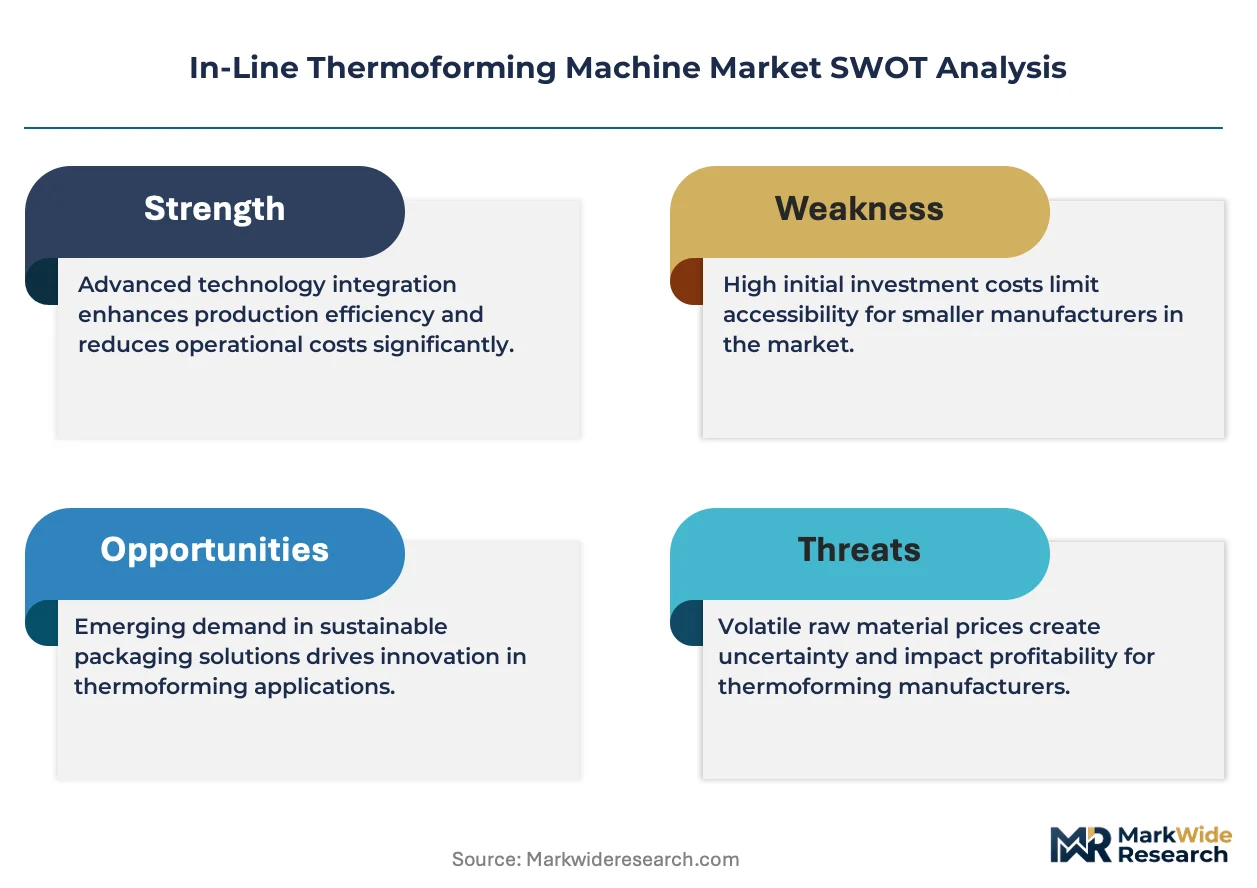
Remote diagnostics and predictive maintenance subscriptions is broadening revenue capture beyond hardware sales for thermoforming equipment vendors. ILLIG Maschinenbau leverages its German engineering base to sustain premium positioning in medical-grade forming systems. Kiefel Technologies anchors the European market through deep specialization in multi-station rotary machines. MULTIVAC competes aggressively on integrated packaging lines that combine forming, sealing, and labeling in single footprints.
An in-line thermoforming machine continuously feeds thermoplastic sheet from roll stock through heating, forming, trimming, and stacking stations in a single production flow, typically processing PET, PP, or PS at cycle speeds exceeding 30 strokes per minute for high-volume packaging output. The equipment serves primarily food packaging, medical device sterilization trays, and consumer goods containment where thin-wall precision and repeatability matter. Automated technology lines command the steepest capital investment but capture the fastest replacement demand as labor costs escalate across mature manufacturing economies. Food packaging end users represent the deepest installed base, though medical devices applications generate superior margin pools due to validation requirements and FDA compliance overhead.
OSHA machine guarding standards and FDA 21 CFR Part 820 quality system regulations shape North American equipment specifications, while EU machinery directives and REACH material compliance dictate European market access protocols. The EU Green Deal packaging waste framework is forcing material transitions from conventional PS to recyclable PET and paperboard composites, redirecting R&D spending across equipment portfolios. Stakeholders must monitor how dual regulatory pressure from food contact safety and circular economy mandates reshapes acceptable machine configurations and aftermarket service contracts.
Market Dynamics
EU Green Deal packaging waste targets are compressing material transitions from polystyrene to recyclable PET and paperboard composites, forcing equipment recalibration across installed machine bases and redirecting vendor R&D spending toward multi-material compatibility.
Growth Catalysts
- Servo-driven forming systems:German precision machinery corridors deploy electric servo actuation to replace pneumatic forming, cutting energy consumption and stroke-to-stroke variability for medical-grade output.
- EU Green Deal packaging waste framework:Mandatory recyclability quotas accelerate replacement cycles for legacy PS-dedicated lines, concentrating demand in PET-capable equipment with integrated trim scrap recovery.
- Medical device sterilization trays:FDA 21 CFR Part 820 validation requirements create sticky demand for thermoforming systems with documented process control and IQ/OQ/PQ qualification support.
Market Restraints
- Steel and aluminum input volatility:Machine frame and tooling alloy costs fluctuate with commodity markets, compressing quoted equipment margins before contract execution.
- German supply chain concentration:Critical servo drive and precision heating element suppliers cluster in Baden-Württemberg and Bavaria, exposing lead times to single-region logistics disruptions.
- Cycle speed ceilings for paperboard:Fiber-based forming materials currently constrain stroke rates to sub-20 per minute versus 30+ for thermoplastics, limiting throughput parity.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO manufacturing compliance expansion and FSSAI food contact safety enforcement create first-mover advantage for validated thermoforming lines in Mumbai-Pune and Hyderabad clusters.
- Remote diagnostics subscription layering:Predictive maintenance telemetry bundled with hardware contracts captures recurring revenue streams and locks out third-party service competitors.
- Hybrid forming-sealing-labeling integration:Converged packaging lines reduce cleanroom footprint and operator touchpoints for sterile medical device containment.
Industry Challenges
- Servo motion programming expertise:Electric forming systems require controls engineers with PLC and HMI integration skills scarce in legacy thermoforming maintenance workforces.
- IQ/OQ/PQ documentation burden:Medical device customers demand extensive installation and operational qualification protocols that extend commissioning timelines and tie up field service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Line Thermoforming Machine Market |
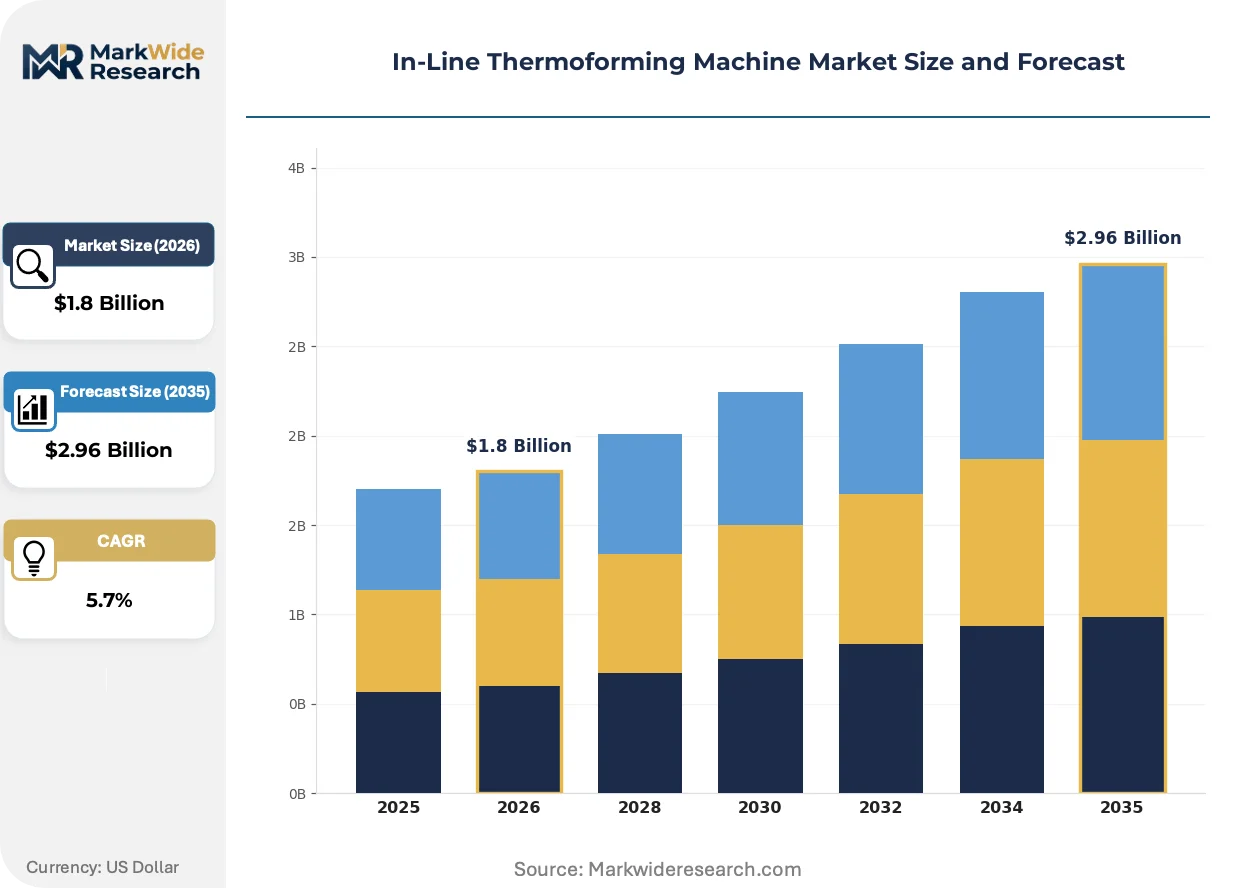
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Clamshells, Trays, Containers Material: Plastic, Film, Composite, Paperboard End User: Food Packaging, Medical Devices, Consumer Goods, Electronics Technology: Mechanical, Hydraulic, Pneumatic, Automated |
| Companies Covered | ILLIG Maschinenbau, Kiefel Technologies, MULTIVAC, TZ Machinery, GABLER Thermoform, Brown Machine Group, MAAC Machinery, Foshan Crown Machinery, Wemac Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Line Thermoforming Machine Market Evolving Landscape
Digital thread integration across heating, forming, and trimming stations is compressing setup times and enabling lot-level traceability demanded by medical device and food safety auditors.
Electric servo forming is expanding into high-speed food packaging lines previously dominated by pneumatic systems. Major North American dairy and fresh produce processors now specify all-electric actuation for repeatability and energy recovery. This transition is expanding into mid-volume contract packaging operations that previously deferred capital upgrades.
REACH substance restrictions on phthalate plasticizers and ECHA candidate list updates are forcing material formulation changes in flexible forming membranes and sealing dies. Equipment vendors must qualify alternative elastomer compounds without sacrificing cycle life. Medical device sterilization tray manufacturers face the steepest revalidation costs under this regulatory pressure.
Consolidated procurement by multi-site food packaging operators is displacing single-facility equipment purchasing. National and continental account structures now dominate capital equipment negotiations, with technical specification authority centralizing at corporate engineering headquarters. This concentration is most visible across German and US dairy packaging networks where corporate sustainability mandates override local plant preferences.
In-Line Thermoforming Machine Market Segmentation
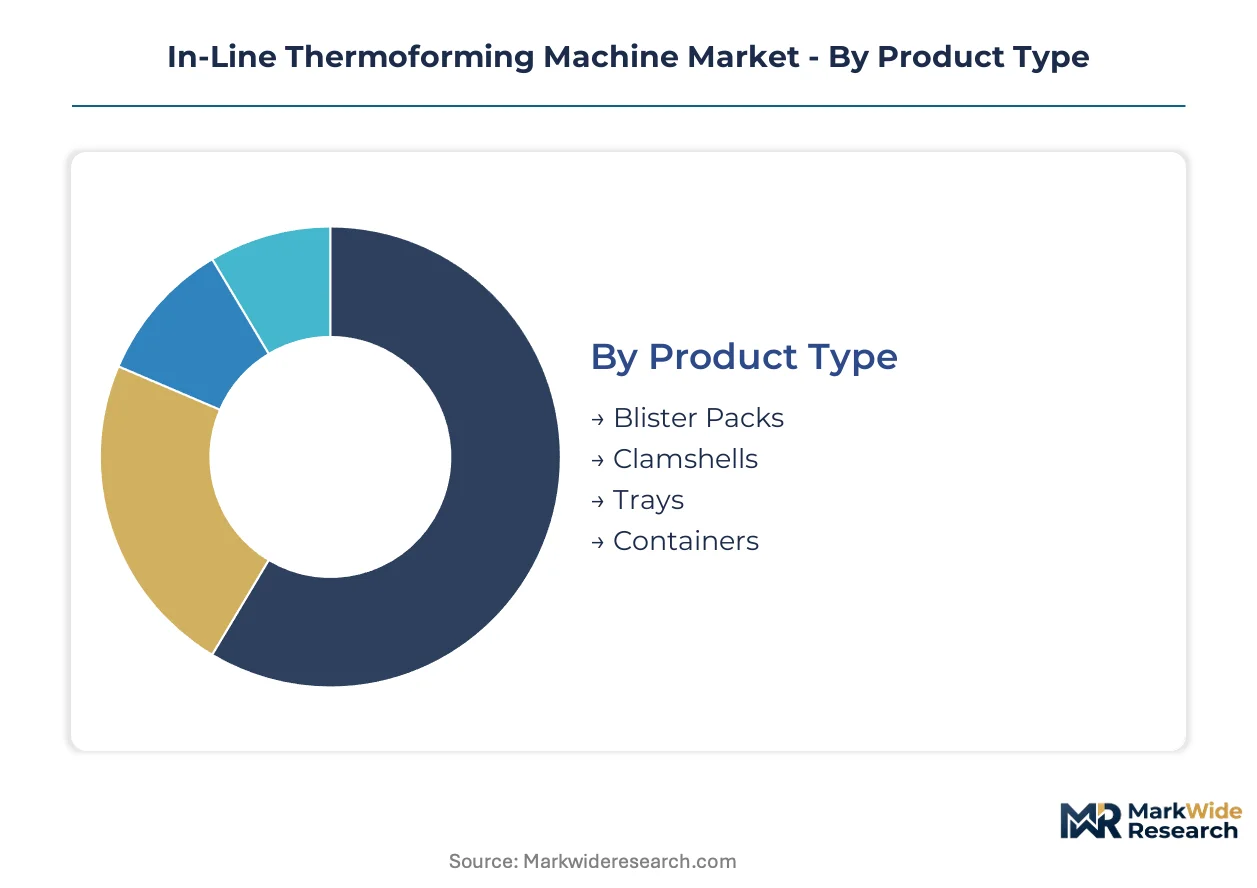
Thermoforming equipment purchasing hinges on matching forming precision to end-use validation requirements, with material compatibility and throughput speed driving configuration choices across food, medical, and industrial applications.
Product Type:
Buyers prioritize cavity complexity and trim tolerance against unit economics and downstream automation integration.
- Blister Packs:Multi-cavity forming with lidding compatibility dominates pharmaceutical unit-dose and consumer healthcare packaging. Demand clusters in FDA-regulated sterile barrier applications where peel strength and seal integrity require validated process windows.
- Trays:Deep-draw precision for medical device sterilization containment commands premium positioning due to IQ/OQ/PQ documentation burdens and material traceability mandates. German and US surgical instrument manufacturers anchor installed base replacement cycles.
- Clamshells:Hinge-integrated forming for retail display and produce containment favors high-speed pneumatic lines with integrated trim-in-place systems.
- Containers:Lidded cup and tub formats for dairy and ready-meal applications concentrate volume in European co-packing networks facing EU Green Deal recyclability deadlines.
Volume sits with containers; growth tilts toward trays.
Material:
Equipment specification follows regulatory pressure on recyclability and food contact safety across regional compliance frameworks.
- Plastic:PET and PP sheet stock dominates high-speed food lines with integrated flake-to-sheet recycling loops. EU packaging waste directives are compressing PS-dedicated machine retirements in favor of PET-capable forming systems with trim scrap recovery.
- Film:Thin-gauge flexible forming for modified atmosphere packaging requires precise temperature control across heating zones. Fresh protein and produce processors in North America specify film-capable lines for extended shelf-life applications.
- Composite:Multi-layer barrier structures for pharmaceutical blister lidding demand specialized sealing die configurations and controlled atmosphere forming chambers.
- Paperboard:Fiber-based forming for single-use food service and produce trays operates at reduced cycle speeds, constraining throughput parity with thermoplastic lines until heating and moisture management technology matures.
Plastic commands current installed capacity; paperboard attracts R&D allocation for circular economy alignment.
End User:
Margin capture varies sharply by validation burden and aftermarket service dependency.
- Medical Devices:Sterilization tray and procedure kit containment requires FDA 21 CFR Part 820 quality system documentation and process validation support. Equipment vendors capture sticky recurring revenue through qualification protocol services and spare parts exclusivity.
- Food Packaging:Dairy, fresh produce, and ready-meal processors represent the deepest equipment installed base with fastest replacement cycles driven by sustainability mandate compliance and labor cost escalation.
- Consumer Goods:Cosmetic and personal care blister packaging favors quick-changeover tooling for short-run SKU proliferation.
- Electronics:ESD-sensitive tray forming for semiconductor and component shipping demands conductive material handling and cleanroom-compatible machine configurations.
Food packaging anchors unit shipments; medical devices concentrate margin contribution.
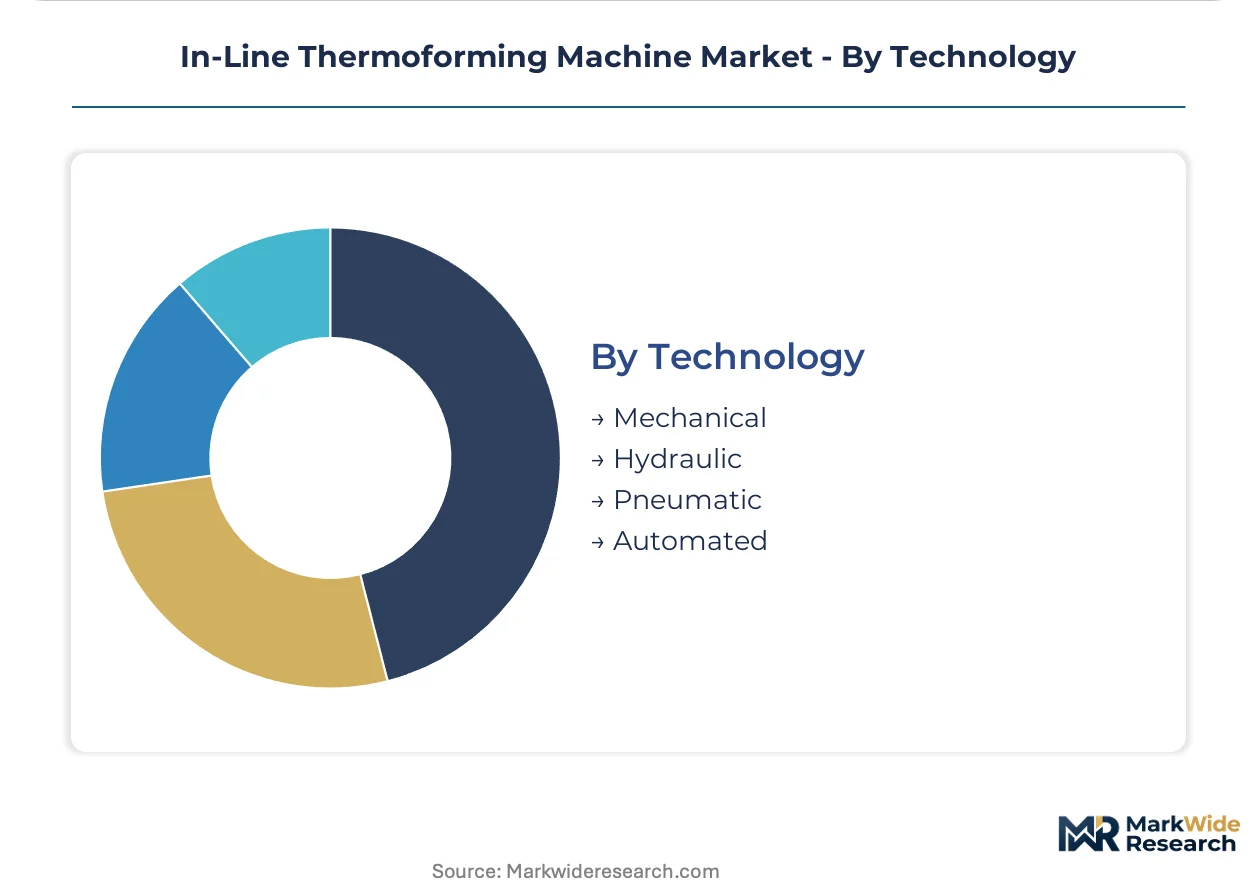
Technology:
Actuation method determines energy efficiency, repeatability, and maintenance staffing requirements.
- Automated:Servo-electric forming with integrated robotics and vision inspection commands steepest capital investment but captures replacement demand from labor-constrained operations. German precision machinery corridors anchor supply concentration for high-end medical and food applications.
- Pneumatic:Compressed air actuation retains cost advantage in high-volume food packaging where stroke-to-stroke variability tolerance permits lower precision thresholds.
- Hydraulic:High-tonnage forming for deep-draw industrial applications maintains niche presence in thick-gauge material processing.
- Mechanical:Cam-driven systems persist in legacy installed bases with limited upgrade appetite among price-sensitive contract packagers.
Pneumatic lines retain volume leadership; automated systems climb the fastest on replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering corridors generate the densest concentration of precision thermoforming equipment, while end-use demand spreads across packaging hubs in the United States, China, and India where food safety and medical device regulations tighten compliance burdens.
United States
Dairy processors and fresh produce packers in Wisconsin and California drive replacement cycles for automated forming lines. FDA 21 CFR Part 820 quality system regulations govern medical-grade equipment specifications for sterilization tray manufacturers. Chicago-area contract packaging networks consolidate procurement under corporate sustainability mandates that override local plant preferences.
Germany
Baden-Württemberg and Bavaria anchor global supply chains for servo-driven forming systems serving medical device and premium food applications. EU machinery directives and REACH material compliance dictate equipment access protocols across the single market. Stuttgart precision engineering clusters concentrate critical servo drive and heating element suppliers, exposing lead times to regional logistics disruptions.
China
Domestic pharmaceutical packaging expansion in Jiangsu and Zhejiang provinces creates demand for validated thermoforming lines. NMPA manufacturing compliance requirements and GB standards for food contact materials shape equipment specifications. Yangtze River Delta manufacturing bases are upgrading from pneumatic to servo-electric actuation to meet export quality thresholds for European and North American customers.
India
CDSCO manufacturing compliance expansion and FSSAI food contact safety enforcement generate first-mover opportunities in Mumbai-Pune and Hyderabad pharmaceutical clusters. Domestic machinery fabricators compete with European imports on price for mid-volume food packaging applications. Gujarat dairy cooperatives are automating thermoforming lines to reduce labor dependency and meet cold-chain export standards.
In-Line Thermoforming Machine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market structure that concentrates premium positioning among German precision engineering groups while fragmenting mid-tier supply among Asian fabricators. The vendor base splits into three strategic archetypes: integrated packaging line specialists, pure-play forming equipment manufacturers, and regional machinery builders serving price-sensitive contract packagers. Dominant competitive moves include vertical integration into aftermarket service contracts and geographic expansion through distributor partnerships in emerging pharmaceutical packaging markets.
Among German-based precision engineering groups, ILLIG Maschinenbau GmbH and Kiefel Technologies GmbH exemplify the premium-tier archetype anchored in Baden-Württemberg's industrial corridor. MULTIVAC occupies a position representing integrated packaging line convergence, combining forming, sealing, and labeling in single footprints. Brown Machine Group and MAAC Machinery sit within the North American machinery builder tier, serving regional food packaging and industrial forming demand with shorter lead times than transatlantic competitors.
| Leading Market Players |
|---|
| ILLIG Maschinenbau |
| Kiefel Technologies |
| MULTIVAC |
| TZ Machinery |
| GABLER Thermoform |
| Brown Machine Group |
| MAAC Machinery |
| Foshan Crown Machinery |
| Wemac Machinery |
| Others |
Value Network & Pricing Analysis
Consolidated procurement by multi-site food packaging operators is compressing quoted equipment margins before contract execution, forcing German and Asian suppliers to absorb commodity volatility through captive component production or risk losing corporate account mandates.
Pricing Analysis
Margin tightening in mid-tier pneumatic systems reflects steel and aluminum input volatility coupled with buyer consolidation into national account structures. Equipment pricing stratifies across premium servo-electric medical-grade systems, standard hybrid food-packaging lines, and economy mechanical units for contract packagers. Cost-down pressure on economy-tier machinery accelerates because regional Asian fabricators compete aggressively on capital cost. Food packaging operators exhibit highest price sensitivity; medical device manufacturers accept premium positioning for IQ/OQ/PQ documentation bundled with hardware.
Supply Chain Analysis
Single-source vulnerability sits with Baden-Württemberg and Bavaria servo drive and precision heating element suppliers clustered in Stuttgart engineering corridors. Critical machine frame alloys draw from Germany, China, and Japan; thermoplastic sheet stock feeds from petrochemical complexes in the United States, Saudi Arabia, and South Korea. Supply chain risk centers on regional logistics disruptions affecting just-in-time component delivery to equipment assembly plants. Distribution runs through manufacturer-direct sales teams for premium medical-grade systems and distributor partnerships for mid-volume food packaging applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision servo drive and heating element fabrication capacity concentrates in southern Germany, propping equipment pricing and extending lead times for non-captive buyers.
For Market Incumbents: Deploy backward integration into critical servo drive production to defend against lead time vulnerability and margin compression from commodity steel volatility. Lock in multi-year aftermarket service contracts with corporate food packaging accounts to preempt third-party competitors. Fortify medical-grade positioning through enhanced IQ/OQ/PQ protocol automation that accelerates customer commissioning timelines. For New Entrants and Emerging Players: Mid-volume pharmaceutical packagers in India represent the most penetrable buyer archetype underserved by established German vendors on price and local service response. Target CDSCO-validated equipment demand in Mumbai-Pune and Hyderabad clusters with servo-electric systems priced below European imports. Capture initial reference installations through distributor partnerships with regional machinery integrators possessing existing pharmaceutical customer relationships. For Investors and Strategic Acquirers: The window for entry favors vertically integrated equipment manufacturers with captive control over precision motion components and established medical device validation protocols. Long-term viability hinges on recurring revenue density from predictive maintenance subscriptions rather than transactional hardware margins. Watch for inflection when corporate sustainability mandates accelerate PS-to-PET equipment replacement cycles beyond current replacement rates.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Platform Migration | Replaces pneumatic actuation to meet EU Green Deal energy efficiency targets and medical-grade repeatability requirements. |
| Predictive Maintenance Subscription Bundling | Captures recurring revenue from telemetry-enabled remote diagnostics that lock out third-party service competitors. |
| Multi-Material Compatibility R&D | Expands equipment addressability across PET, PP, and emerging paperboard composites mandated by circular economy regulations. |
| Pharmaceutical Validation Protocol Automation | Reduces IQ/OQ/PQ documentation burden that currently extends commissioning timelines and constrains field service capacity. |
| Regional Assembly Footprint Expansion | Shortens lead times for Asian pharmaceutical and food packaging markets beyond transatlantic supply chain reach. |
Research Methodology
Multi-period observation of equipment shipment volumes, replacement cycle patterns, and regulatory compliance cost trajectories anchored the trend analysis, supplemented by interviews with plant engineers at dairy and produce packaging operations, biomedical engineers at sterilization tray manufacturers, OEM procurement teams at multi-site food networks, and aftermarket service heads at precision machinery vendors. Secondary validation drew from EU machinery directive filings, FDA 510(k) submissions for medical-grade forming systems, SEC 10-K disclosures from packaging equipment conglomerates, and customs trade data on thermoplastic sheet stock imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Input-output matrices mapped forming precision requirements, material compatibility specifications, and actuation technology choices to end-use validation burdens and regional regulatory clusters. Modeled dimensions spanned product type complexity, material recyclability tier, end-user margin capture potential, and technology automation level. CAGRs were derived from regression-weighted historical replacement rates projected against sustainability mandate compliance deadlines and labor cost escalation curves. Industry-specific forecast inputs incorporated servo drive lead time volatility and REACH substance restriction implementation timelines affecting sealing die elastomer formulations.
Revisions become necessary when EU packaging waste directive enforcement intensifies beyond current trajectories, when steel alloy commodity spikes exceed historical volatility bands, or when medical device validation protocols undergo substantive FDA restructuring. Forecasts reflect documented assumptions about replacement cycle elasticity and corporate procurement centralization momentum. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Combination Filler Machine Market
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Box Filling Machine Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Filling Machinery Market
Packaging Machinery
Tamper Evidence Machinery Market
Packaging Machinery
Meal Tray Sealing Machines Market