
 Capping Machine Market | 2026-2036
Capping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Capping Machine Market Analysis
Skilled automation technician availability is collapsing across European packaging hubs, forcing OEMs to redesign machines for remote diagnostics and reduced touch maintenance. Krones AG leverages its German engineering base to sustain premium positioning in high-speed rotary cappers for beverage giants. SACMI Group anchors its competitiveness through integrated blow-molding and capping lines that dominate Mediterranean wine and olive oil bottling. Syntegon competes by specializing in pharmaceutical containment systems that meet FDA and EMA aseptic filling standards.
A capping machine applies closures to containers through torque-controlled tightening, snap-fit engagement, or thermal induction sealing, with throughput rates spanning 50 to 120,000 units per hour depending on rotary head count and container geometry. Automatic capping machines lead capital deployment as food and beverage manufacturers eliminate manual stations to contain labor costs and contamination risk. Screw cap technology occupies the largest installed base due to its resealability and compatibility with plastic and glass threads across beverage, pharmaceutical, and chemical applications. Snap cap technology is gaining share in single-serve dairy and ready-to-drink formats where consumer convenience outweighs reclosure needs.
FDA 21 CFR Part 11 and EU GMP Annex 1 drive pharmaceutical capping equipment toward isolator-integrated designs with continuous particle monitoring and electronic batch records. EMA's Medical Device Regulation and EPA container closure integrity guidelines for agrochemicals tighten validation protocols, extending sales cycles but raising replacement demand for non-compliant legacy lines. Stakeholders must weigh total cost of ownership against compliance trajectory when selecting between European precision engineering and Asian cost-optimized alternatives.
Market Dynamics
Serialization mandates from FDA and EMA are forcing pharmaceutical manufacturers to replace legacy capping lines with integrated track-and-trace systems, compressing equipment replacement cycles and elevating validation requirements across the supply base.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic batch record mandates drive pharmaceutical OEMs toward isolator-integrated capping systems with continuous particle monitoring.
- Lightweight closure retrofitting:Beverage bottlers in Germany, India, and Brazil are converting lines to handle reduced-material screw caps, creating replacement demand for torque-calibrated rotary cappers.
- Track-and-trace compliance:EMA's Falsified Medicines Directive enforcement compels contract packagers to install vision-inspected capping stations with serialization-ready conveyor interfaces.
Market Restraints
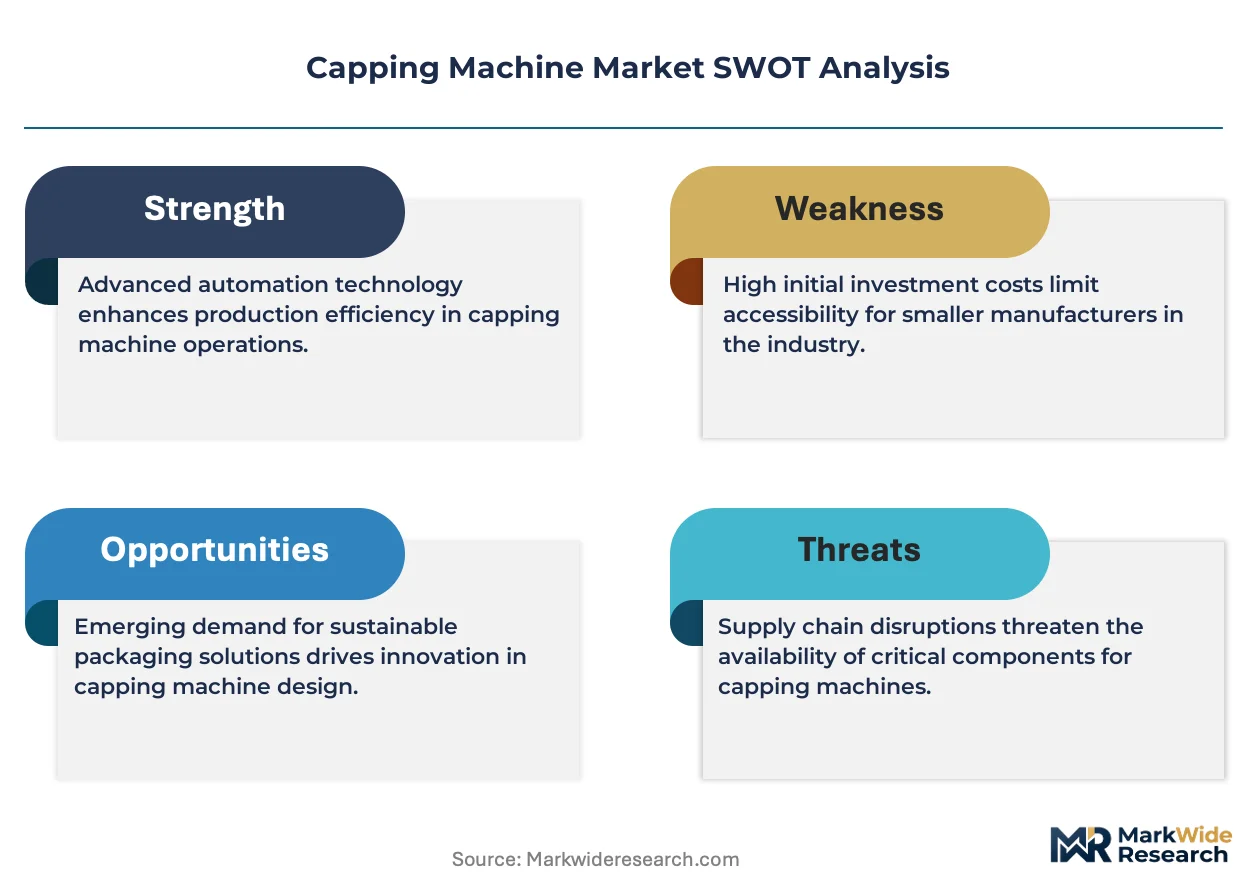
- Stainless steel alloy volatility:Price swings in 316L and 304 grades compress margin buffers for European precision engineering houses.
- Extended validation protocols:EPA container closure integrity guidelines for agrochemicals stretch sales cycles from quotation to commissioning.
- Skilled technician scarcity:Collapsing automation specialist availability across European packaging hubs forces OEMs to absorb remote diagnostics development costs.
Strategic Opportunities
- Aseptic ready-to-drink expansion:Dairy processors in North America are adopting snap-cap rotary systems for single-serve formats where resealability is secondary to convenience.
- Induction sealing convergence:Pharmaceutical containment systems are integrating electromagnetic induction with isolator technology, opening new specification tiers for high-potency drug packaging.
- Remote diagnostics channel:OEM service contracts are unbundling from hardware sales, creating recurring revenue streams through predictive maintenance subscriptions.
Industry Challenges
- Isolator integration complexity:Pharmaceutical capping lines must synchronize with restricted access barrier systems, extending commissioning timelines and requiring cross-functional validation teams.
- Legacy line obsolescence:Non-compliant mechanical cappers face accelerated replacement pressure as FDA and EMA enforcement windows narrow, straining capital allocation at mid-tier contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capping Machine Market |
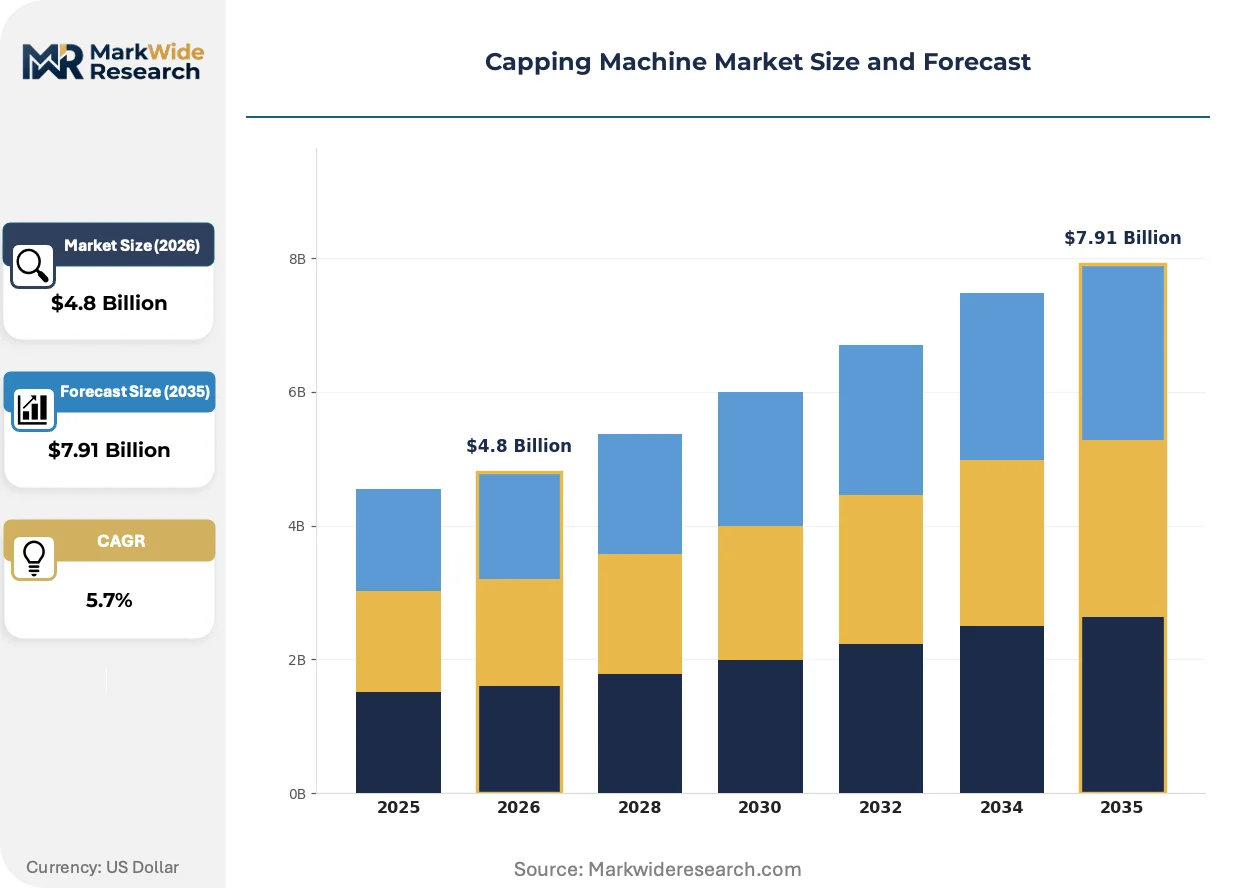
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Capping Machines, Semi-Automatic Capping Machines, Manual Capping Machines, Rigid Cappers Technology: Screw Cap Technology, Snap Cap Technology, Press-On Cap Technology, Thermal Cap Technology End User: Pharmaceutical Companies, Food & Beverage Manufacturers, Cosmetics Producers, Chemical Industries Packaging Type: Glass Bottles, Plastic Bottles, Metal Containers, Jars |
| Companies Covered | Closure Systems International, Krones AG, Syntegon, Tetra Pak International, Accutek Packaging Equipment, Arol Group, Zalkin, SACMI Group, IMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capping Machine Market Emerging Trajectories
Equipment architecture is pivoting toward modularity and connectivity as pharmaceutical serialization deadlines compress replacement windows and beverage producers demand format flexibility without line downtime.
Servo-driven torque control is supplanting mechanical clutch systems in high-speed rotary cappers. Pharmaceutical fillers in Switzerland and Germany are adopting these systems to achieve repeatable closure application within tight process limits. The shift is compressing the installed base of pneumatic cappers and elevating specification thresholds for entry-level equipment.
EMA's Medical Device Regulation tightens validation documentation for capping equipment used in combination products, forcing OEMs to restructure quality management systems. Contract manufacturers in Ireland and the Netherlands are responding by consolidating supplier relationships to reduce audit burden. The regulation is accelerating consolidation among validation service providers serving the packaging machinery sector.
Outcome-based service contracts are displacing traditional break-fix maintenance arrangements in beverage bottling. Large-scale producers in Brazil and India are negotiating throughput guarantees from OEMs, transferring operational risk to equipment suppliers. This shift is most visible in carbonated soft drink and bottled water segments where line efficiency directly determines contract renewal.
Capping Machine Market Segmentation
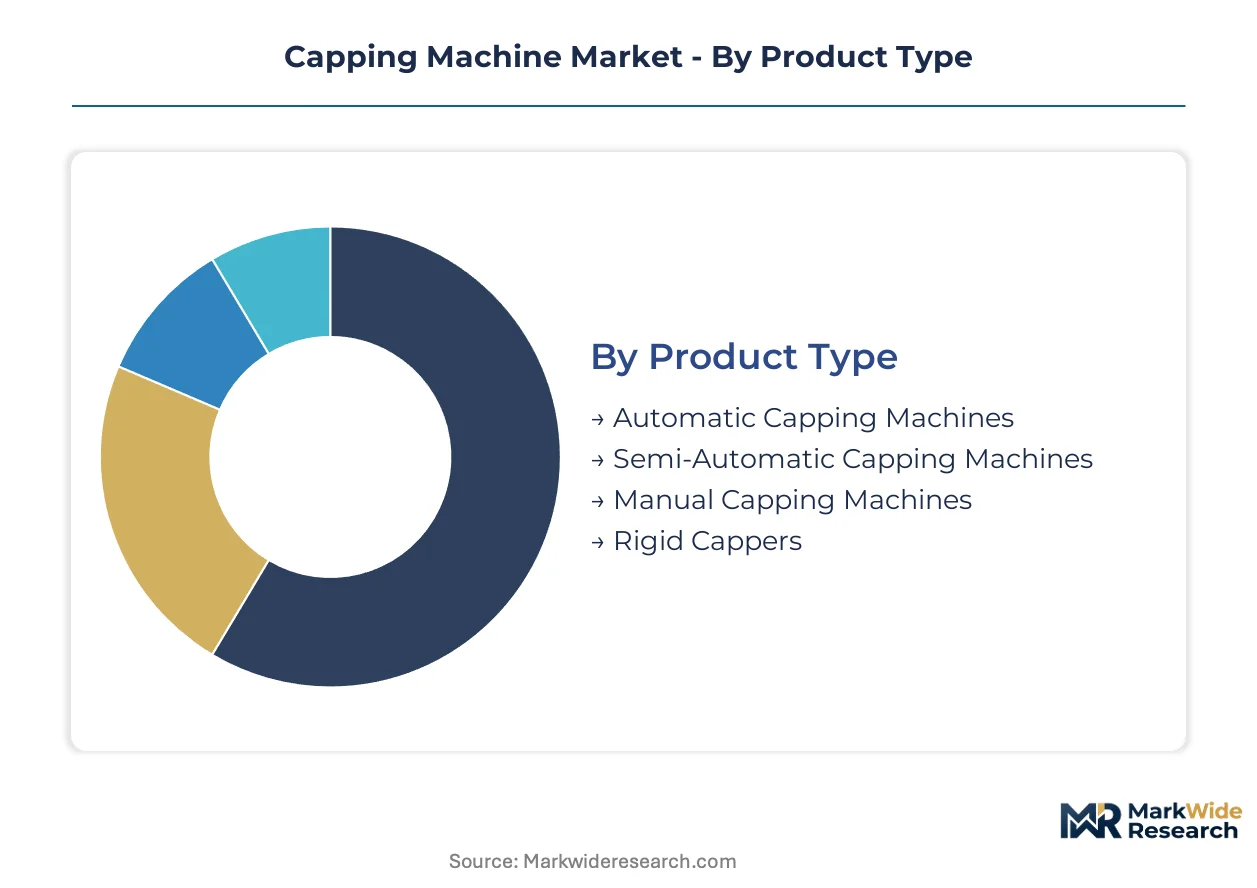
Capping machine procurement patterns diverge sharply across automation tiers and end-use compliance requirements. Pharmaceutical serialization mandates and beverage lightweighting trends are fragmenting demand specifications, forcing OEMs to maintain parallel product architectures.
Product Type:
Automatic systems dominate export-led demand from German and Italian engineering houses, while semi-automatic and manual variants serve domestic-scale producers in emerging manufacturing clusters.
- Automatic Capping Machines:Rotary head configurations achieve 50,000 to 120,000 units per hour through servo-driven torque control. Pharmaceutical bottlers in Switzerland and Germany deploy these for FDA 21 CFR Part 11 compliance with electronic batch records and isolator integration.
- Semi-Automatic Capping Machines:Pneumatic or electric benchtop units bridge manual stations and full automation. Contract packagers in India and Brazil favor these for mid-volume SKUs where format flexibility outweighs throughput maximization.
- Manual Capping Machines:Hand-operated chuck or press tools serve artisanal food producers and pilot-scale pharmaceutical operations. Demand concentrates in domestic European markets with strong craft beverage traditions.
- Rigid Cappers:Heavy-duty stationary units engineered for chemical and agrochemical container sealing. EPA container closure integrity guidelines extend validation timelines for this category.
Automatic capping machines hold the largest share; momentum sits with semi-automatic systems as mid-tier contract manufacturers defer full automation investments.
Technology:
Technology selection tracks closure material evolution and resealability requirements, with screw and snap formats diverging on torque precision versus speed economics.
- Screw Cap Technology:Threaded closure systems compatible with plastic and glass containers across beverage, pharmaceutical, and chemical applications. German and Indian beverage bottlers are retrofitting lines for lighter-weight screw caps with reduced material profiles.
- Snap Cap Technology:Push-fit closures eliminating torque application for single-serve dairy and ready-to-drink formats. North American processors adopt these where consumer convenience outweighs reclosure needs.
- Press-On Cap Technology:Direct-force application for crown caps and lug closures in carbonated beverages. Demand clusters in traditional brewing markets with established crown cap supply chains.
- Thermal Cap Technology:Induction sealing systems for pharmaceutical containment and tamper-evident food packaging. Integration with isolator technology is opening specification tiers for high-potency drug manufacturing.
Screw cap technology commands the dominant installed base; thermal cap systems are climbing the fastest on pharmaceutical containment requirements.
End User:
End-user concentration reflects regulatory stringency gradients, with pharmaceutical and food sectors driving premium equipment specifications.
- Pharmaceutical Companies:Aseptic filling and serialization compliance demand isolator-integrated capping with continuous particle monitoring. FDA and EMA track-and-trace mandates are compressing replacement cycles for legacy mechanical lines.
- Food & Beverage Manufacturers:High-speed rotary cappers for carbonated soft drinks, bottled water, and edible oils. Brazilian and Indian producers negotiate throughput guarantees from OEMs, transferring operational risk to suppliers.
- Cosmetics Producers:Precision torque control for premium packaging aesthetics. Demand fragments across batch sizes with frequent format changeovers.
- Chemical Industries:Corrosion-resistant sealing systems for agrochemical and industrial chemical containers. Extended EPA validation protocols stretch procurement timelines.
Food and beverage manufacturers represent the largest demand pool; pharmaceutical companies are expanding most quickly on compliance-driven replacement.
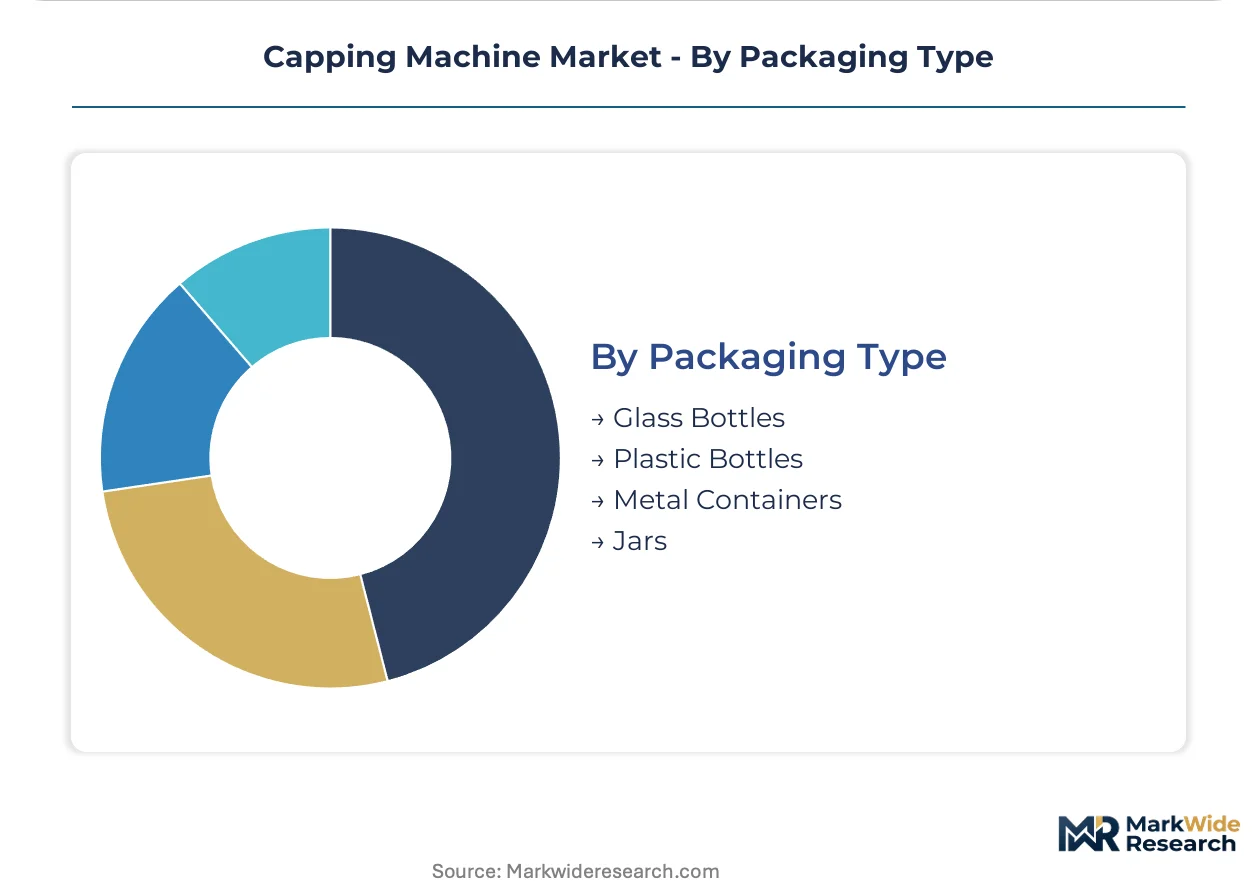
Packaging Type:
Container material selection shapes capping head geometry and torque calibration requirements, with glass and plastic commanding distinct equipment architectures.
- Glass Bottles:Rigid thread profiles requiring precise torque control to prevent fracture. Premium wine and olive oil bottling in Mediterranean markets sustains demand for precision-engineered rotary cappers.
- Plastic Bottles:Flexible thread forms accommodating lighter-weight closure designs. Lightweight closure retrofitting in Germany, India, and Brazil is driving replacement demand for recalibrated torque systems.
- Metal Containers:Aerosol and industrial chemical packaging with specialized crimping and sealing mechanisms. Demand concentrates in agrochemical and coatings sectors.
- Jars:Wide-mouth containers for spreads, sauces, and cosmetics. Lug closure and twist-off formats require adaptable chuck configurations.
Plastic bottles hold the largest share; glass bottles are gaining share fastest on premium beverage packaging trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates anchor North American pharmaceutical capping demand, while German beverage engineering and Indian contract packaging sustain distinct procurement patterns across three continents.
United States
Pharmaceutical serialization under FDA 21 CFR Part 11 drives isolator-integrated capping system procurement. The Drug Supply Chain Security Act enforcement compresses replacement cycles for legacy mechanical lines. New Jersey and Massachusetts pharmaceutical clusters concentrate demand for vision-inspected capping stations with electronic batch records.
Germany
Beverage bottlers retrofit lines for lightweight screw caps with reduced material profiles. The country's national packaging regulator enforces strict container closure integrity standards for carbonated products. Bavarian engineering houses supply precision rotary cappers to domestic breweries and export markets.
India
Contract packagers scale semi-automatic capping systems for mid-volume pharmaceutical and food SKUs. CDSCO track-and-trace requirements for domestic drug packaging tighten equipment specifications. Mumbai and Ahmedabad industrial corridors concentrate demand for format-flexible capping stations.
Brazil
Carbonated soft drink producers negotiate throughput guarantees from OEMs, transferring operational risk to equipment suppliers. ANVISA pharmaceutical serialization deadlines approach for domestic drug manufacturers. São Paulo state beverage clusters drive high-speed rotary capper procurement.
Switzerland
Pharmaceutical fillers deploy servo-driven torque control systems to achieve repeatable closure application within tight process limits. Swissmedic aseptic manufacturing guidelines elevate isolator integration requirements. Basel and Zurich pharmaceutical manufacturing zones sustain premium capping equipment demand.
Capping Machine Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in capping machine supply. German and Italian engineering houses dominate high-speed beverage rotary systems through precision manufacturing heritage. Pharmaceutical containment specialists compete on isolator integration and FDA validation documentation. Strategic moves concentrate on remote diagnostics capability development and outcome-based service contract structuring.
Among German-based integrated suppliers, Krones AG exemplifies the premium-tier engineering archetype through its sustained positioning in high-speed beverage applications. SACMI Group represents the integrated blow-molding-to-capping system model that dominates Mediterranean liquid packaging. Syntegon occupies a position within the pharmaceutical containment specialist tier, anchoring competitiveness through aseptic filling integration capabilities.
| Leading Market Players |
|---|
| Closure Systems International |
| Krones AG |
| Syntegon |
| Tetra Pak International |
| Accutek Packaging Equipment |
| Arol Group |
| Zalkin |
| SACMI Group |
| IMA Group |
| Others |
Supply Flow & Price Mechanics
Long-term service contracts with capacity reservation clauses anchor pricing visibility for pharmaceutical bottlers sourcing isolator-integrated capping systems from German and Swiss engineering houses. These arrangements lock in stainless steel alloy allocations and shield buyers from 316L price volatility while committing OEMs to fixed maintenance escalation rates.
Pricing Analysis
European precision engineering commands a 40-60% premium over Asian cost-optimized alternatives for pharmaceutical-grade capping equipment. Pricing stratifies across premium, standard, and economy tiers based on isolator integration depth and FDA 21 CFR Part 11 validation documentation completeness. Cost compression in the standard tier is intensifying because Brazilian and Indian beverage producers negotiate throughput guarantees that transfer operational risk to OEMs. Contract packagers in emerging manufacturing clusters exhibit the highest price sensitivity, while Swiss and German pharmaceutical fillers prioritize compliance trajectory over acquisition cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for servo drives and precision torque sensors sourced from East Asian component suppliers. Capping machine manufacturing concentrates in Germany, Italy, and China, with Bavarian engineering houses drawing from captive stainless steel forging capacity and Swiss precision sensor suppliers. The supply chain rests on single-source vulnerability for high-grade 316L alloy from specialized European foundries. Distribution runs through OEM-direct channels for pharmaceutical containment systems and machinery distributor networks for beverage rotary cappers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent OEMs face substitution pressure from modular, software-centric entrants offering predictive maintenance platforms that unbundle service revenue from hardware sales.
For Market Incumbents: Consolidate validation service capabilities through backward integration into compliance documentation and isolator commissioning. Acquire remote diagnostics software specialists to offset collapsing automation technician availability across European packaging hubs. Lock in pharmaceutical customers with FDA 21 CFR Part 11 pre-validated platform architectures that accelerate deployment timelines versus modular competitors. For New Entrants and Emerging Players: Remote service-layer gaps in legacy OEM maintenance contracts present entry points for predictive analytics specialists. Target mid-tier contract packagers in India and Brazil with semi-automatic capping systems featuring format-flexible tooling and subscription-based validation support. Lead with outcome-based throughput guarantees that incumbent engineering houses resist offering. For Investors and Strategic Acquirers: The market sits at a compliance-driven replacement phase that favors pharmaceutical containment specialists with isolator integration capabilities. Long-term viability hinges on recurring revenue mix from service contracts versus transactional equipment sales. Monitor FDA enforcement window narrowing as the inflection signal for accelerated replacement demand at mid-tier contract manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Integration Partnership | Pharmaceutical OEMs secure FDA 21 CFR Part 11 compliance pathways through restricted access barrier system alliances. |
| Predictive Maintenance Platform Launch | Remote diagnostics subscriptions offset skilled technician scarcity across European packaging hubs. |
| Lightweight Closure Retrofit Program | German and Brazilian beverage bottlers recalibrate torque systems for reduced-material screw caps. |
| Validation Service Acquisition | Consolidation of EMA Medical Device Regulation documentation specialists reduces audit burden exposure. |
| Throughput Guarantee Contracting | Operational risk transfer to OEMs aligns supplier incentives with line efficiency metrics at carbonated soft drink producers. |
Methodological Framework
The analysis maps automatic, semi-automatic, and manual capping system tiers, each validated through plant engineers at beverage bottlers, pharmaceutical manufacturing directors, and aftermarket service heads. Primary interviews with OEM procurement teams and contract packaging executives combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EMA Medical Device Regulation filings, and SEC machinery sector disclosures. Bottom-up equipment shipment tracking and top-down end-use demand modeling provided triangulation across the analysis window.
Consistency checks against customs data for stainless steel alloy imports and pharmaceutical capital expenditure surveys validated volume and value outputs. The analytical framework segments by automation tier, technology type, end-use compliance requirements, and regional regulatory cluster throughout the forecast period. CAGRs derive from installed base replacement cycles, lightweight closure retrofitting timelines, and serialization mandate enforcement schedules. Forecast inputs include skilled technician availability indices and stainless steel price volatility assumptions.
Underlying assumptions cover sustained FDA and EMA enforcement of track-and-trace mandates, with deviation risk concentrated in extended EPA validation timelines for agrochemical applications and alloy price spikes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Pulp Molding Machines Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Tray Forming Machine Market
Packaging Machinery
Vacuum Chamber Packaging Machines Market
Packaging Machinery
Tray Former Machines Market
Packaging Machinery
Automatic Banding Machine Market
Packaging Machinery
Pre-Made Pouch Packaging Machines Market
Packaging Machinery
Plastic Vacuum Forming Machinery Market
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Lid Applicator Machine Market
Packaging Machinery
Bagging Machine Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Metal Banding Machine Market