
 Molded Pulp Packaging Machines Market | 2026-2036
Molded Pulp Packaging Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Pulp Packaging Machines Market Foresight
Project finance and equipment leasing is rewriting competitive entry barriers for molded pulp packaging machinery, allowing mid-sized converters to access automated blow molding and vacuum forming lines without full capital commitment. Mudanjiang City Joy Sun Pulp Molding Technology leverages its integrated tooling foundry to control delivery timelines for Asian customers. Western Pulp anchors North American demand through regionalized service networks and spare-parts proximity. Kawaguchi Machinery differentiates via precision robotics integration for thin-wall food container applications.
Molded pulp packaging machines form fiber slurries—typically bamboo, bagasse, or recycled paperboard—into dimensionally stable trays, clamshells, and protective inserts using heat, pressure, and vacuum-assisted dewatering molds, with cycle speeds ranging from 8 to 30 seconds per unit depending on wall thickness and automation level. Compression molding equipment dominates current installed base economics due to lower energy intensity and simpler die maintenance, while robotics-integrated lines represent the fastest-expanding technology segment as labor costs rise and repeatability standards tighten. Vacuum forming systems occupy a specialized niche in custom electronics protective packaging where deep-draw geometries and anti-static fiber blends command premium pricing.
The EU Green Deal and F-Gas Regulation directly shape European equipment demand by mandating plastic reduction timelines that force food and consumer goods packagers toward fiber-based alternatives. FDA food-contact substance notifications and BIS mechanical safety certifications govern machine eligibility for respective national markets, creating compliance layering that favors suppliers with multi-territory validation experience. Stakeholders must monitor how evolving compostability certification requirements from TÜV Austria and BPI alter mold design specifications and downstream customer qualification protocols.
Market Dynamics
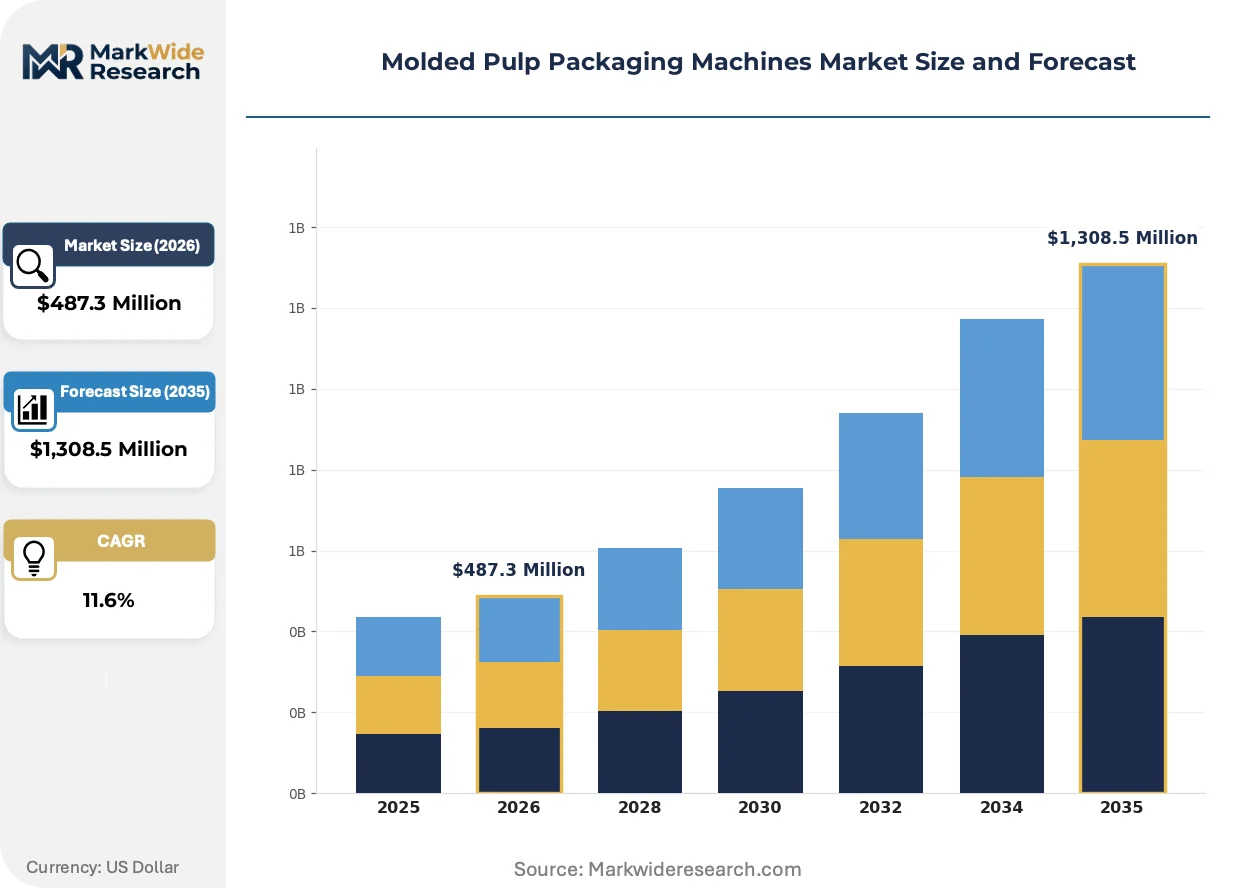
Equipment finance restructuring is compressing capital barriers for mid-sized converters seeking robotics-integrated compression molding lines, while EU Green Deal mandates accelerate replacement cycles for plastic-dependent machinery.
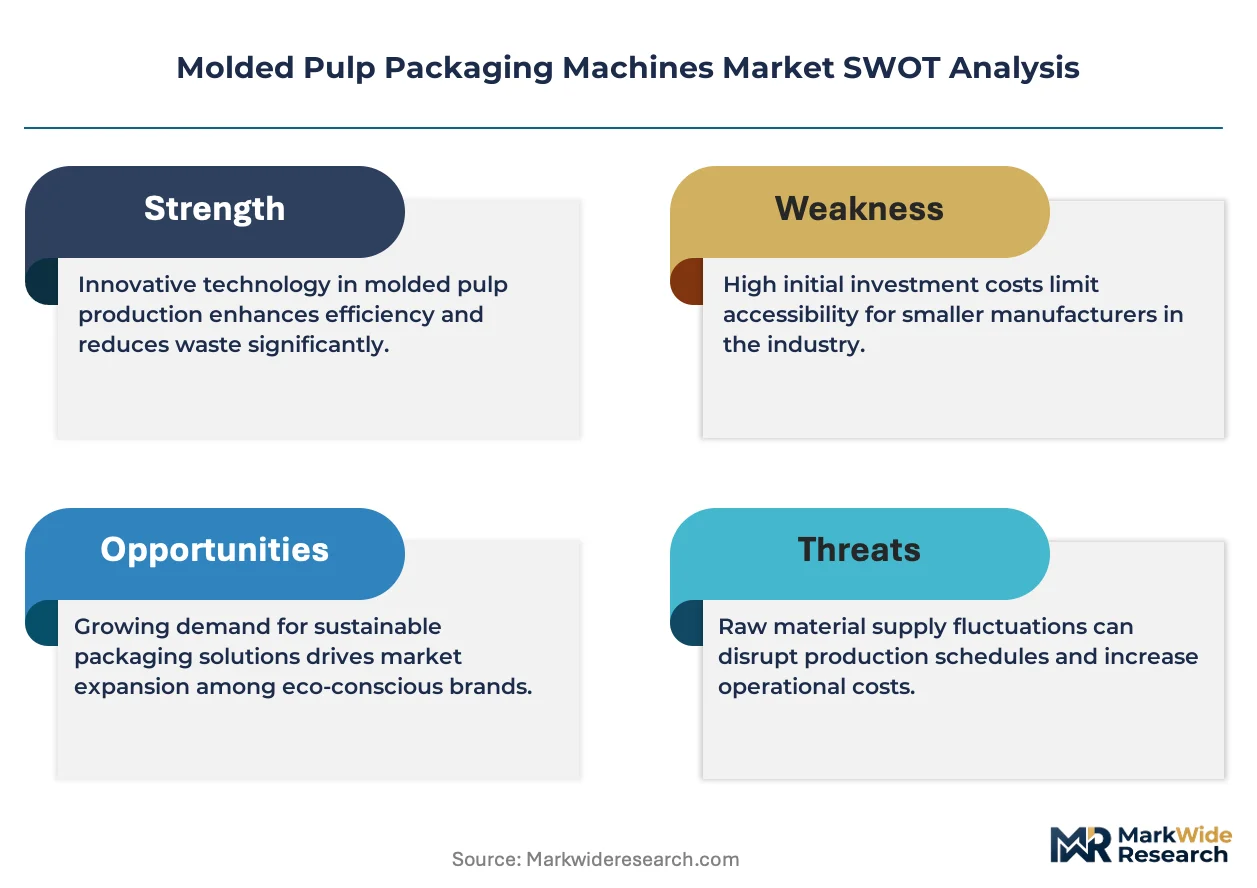
Growth Catalysts
- EU F-Gas Regulation:Phasedown schedules for fluorinated greenhouse gases eliminate polystyrene foam alternatives, forcing food packagers toward fiber-based tray and clamshell production lines.
- Bamboo fiber slurry adoption:Asian pulp processors integrate bagasse and agricultural waste streams into molding feedstocks, reducing raw material costs and improving compostability certification alignment.
- Robotics integration:Automated pick-and-place systems cut cycle times for thin-wall food containers, attracting dairy and ready-meal processors in Germany and France.
Market Restraints
- Tooling lead times:Precision aluminum molds for complex geometries require 14-20 week delivery windows from specialized foundries, constraining rapid capacity expansion.
- Energy cost volatility:Thermal dewatering processes consume 180-250 kWh per ton of finished pulp packaging, exposing converters to electricity price spikes in manufacturing-intensive regions.
- Competing barrier coatings:PFAS-free oil and grease resistance remains technically immature, limiting molded pulp penetration in fatty food applications where plastic films retain functional superiority.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for sustainable packaging machinery create localized assembly opportunities for European and Asian equipment suppliers.
- Electronics protective packaging:Anti-static fiber blends and deep-draw vacuum forming capabilities address unmet demand from semiconductor and consumer electronics shippers.
- After-sales service unbundling:Remote diagnostics and predictive maintenance subscriptions generate recurring revenue streams independent of new equipment sales cycles.
Industry Challenges
- Multi-territory compliance layering:FDA food-contact notifications, BIS mechanical safety certifications, and evolving TÜV Austria compostability standards create parallel qualification timelines for machine exporters.
- Control systems integration:Legacy thermoforming lines lack Industry 4.0 connectivity protocols, forcing costly retrofitting for converters seeking unified production data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Pulp Packaging Machines Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blow Molding, Compression Molding, Injection Molding, Vacuum Forming Technology: Automated Systems, Semi-Automated Systems, Manual Systems, Robotics End User: Food Industry, Electronics Packaging, Consumer Goods, Personal Care Application: Food Containers, Protective Packaging, Retail Packaging, Custom Designs |
| Companies Covered | Mudanjiang City Joy Sun Pulp Molding Technology, Gongyi City Hongrun Machinery, Fujian Hualong Machinery, Chaoan County Shuangxing Machinery, Zhengzhou Ailence Machinery, Shanghai Shouyu Machinery, Jiangsu Huaneng Machinery, Western Pulp, Kawaguchi Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Pulp Packaging Machines Market Shifts & Advancements
Digital thread integration across design-to-mold workflows is compressing product development cycles, while regulatory chemistry restrictions and buyer consolidation reshape equipment specification priorities.
Machine learning-driven predictive maintenance is digitizing uptime assurance for high-volume compression molding operations. Dairy and protein tray converters in the Netherlands deploy sensor arrays on hydraulic presses to anticipate seal wear and heating element degradation. This capability is digitizing service contract structures, shifting vendor revenue from reactive spare parts toward subscription-based performance guarantees.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating oil-resistant coatings from food-contact applications. Equipment manufacturers accelerate plasma treatment and chitosan-based barrier integration to maintain functional performance. Ready-meal and bakery segments in France and Germany face the steepest compliance deadlines, driving accelerated mold redesign cycles.
Consolidated procurement by multinational food retailers is compressing vendor qualification timelines. Category managers at European grocery chains now mandate compostability certification and carbon footprint disclosure as standard RFP elements. This behavioral shift concentrates equipment purchasing authority among fewer buyers with standardized technical specifications, favoring suppliers with pre-validated multi-territory compliance dossiers.
Molded Pulp Packaging Machines Market Segmentation
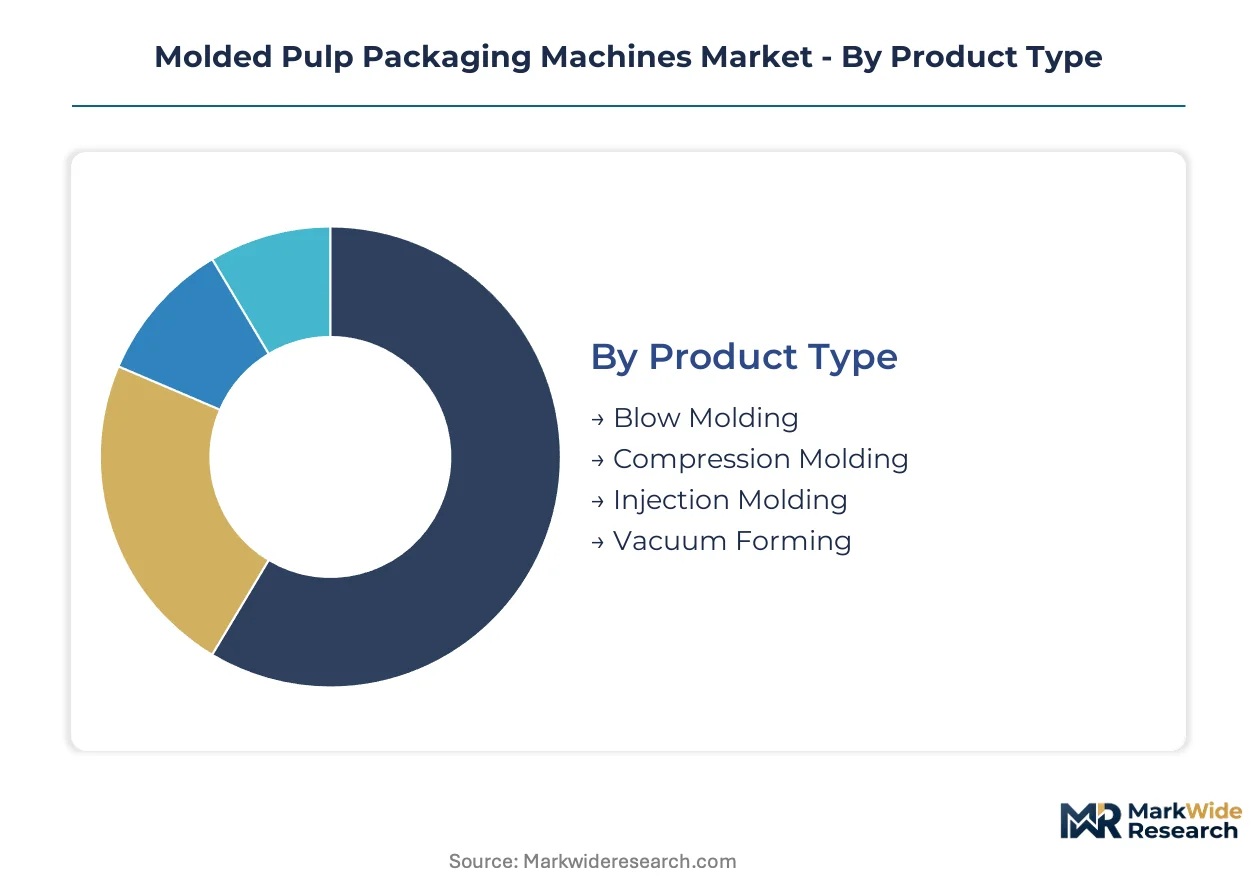
Segmentation in molded pulp packaging machinery reveals divergent service intensity and capital requirements across equipment categories. After-sales attachment rates vary sharply by automation level and mold complexity, reshaping vendor revenue models and customer lifetime value calculations.
Product Type:
After-sales service intensity escalates with thermal cycling frequency and mold wear rates, compressing maintenance contract pricing power for high-duty equipment categories.
- Compression Molding:Hydraulic presses apply heat and pressure to dewater fiber slurries into dimensionally stable trays and clamshells. Dairy processors in Germany and France favor these lines for ready-meal containers due to lower energy intensity and simpler die maintenance compared to alternatives. EU Green Deal plastic phase-out deadlines accelerate replacement demand.
- Vacuum Forming:Suction-assisted dewatering shapes deep-draw geometries for protective inserts using anti-static fiber blends. Electronics shippers in semiconductor clusters concentrate demand here, where custom mold tooling and premium pricing offset smaller batch sizes.
- Blow Molding:Compressed air expands heated fiber preforms into hollow containers. Beverage bottle applications remain limited by fiber strength constraints.
- Injection Molding:High-pressure ram injection fills complex multi-cavity molds. Fine-detail personal care packaging drives niche adoption.
By volume, Compression Molding leads. By growth pace, Vacuum Forming is ahead.
Technology:
Capital deployment patterns stratify sharply across automation tiers, with mid-sized converters leveraging equipment finance to bridge capability gaps.
- Automated Systems:Fully integrated lines with programmable logic controllers and continuous fiber slurry feed achieve cycle speeds of 8-15 seconds per unit. Food industry buyers in the Netherlands and Belgium prioritize these for high-volume dairy tray production where labor cost arbitrage justifies upfront investment.
- Robotics:Articulated pick-and-place arms and vision-guided quality inspection reduce touch labor in thin-wall container handling. Ready-meal processors in France adopt these fastest as repeatability standards tighten and cycle time compression yields direct margin recovery.
- Semi-Automated Systems:Operator-assisted loading with automated pressing and ejection. Smaller converters in Eastern Europe favor this tier for flexible batch sizing.
- Manual Systems:Hand-loaded molds with basic hydraulic actuation. Artisan and startup operations dominate this shrinking category.
By installed base, Semi-Automated Systems lead. By expansion trajectory, Robotics climbs fastest.
End User:
Compliance layering intensity varies by end-use exposure to food-contact regulations and compostability certification requirements.
- Food Industry:Tray, clamshell, and bowl production for dairy, protein, and bakery segments. REACH restrictions on per- and polyfluoroalkyl substances force accelerated mold redesign for oil-resistant applications in France and Germany.
- Electronics Packaging:Anti-static protective inserts and precision-fit cushioning for semiconductor and consumer device shipment. Deep-draw vacuum forming capabilities command premium pricing in this segment.
- Consumer Goods:Durable goods protective packaging and retail display units. Brand sustainability commitments drive fiber substitution faster than regulatory mandates here.
- Personal Care:Molded pulp bottles and jars for cosmetics and toiletries. Injection molding lines serve this niche with fine surface finish requirements.
By equipment revenue, Food Industry leads. By technology upgrade frequency, Electronics Packaging is ahead.
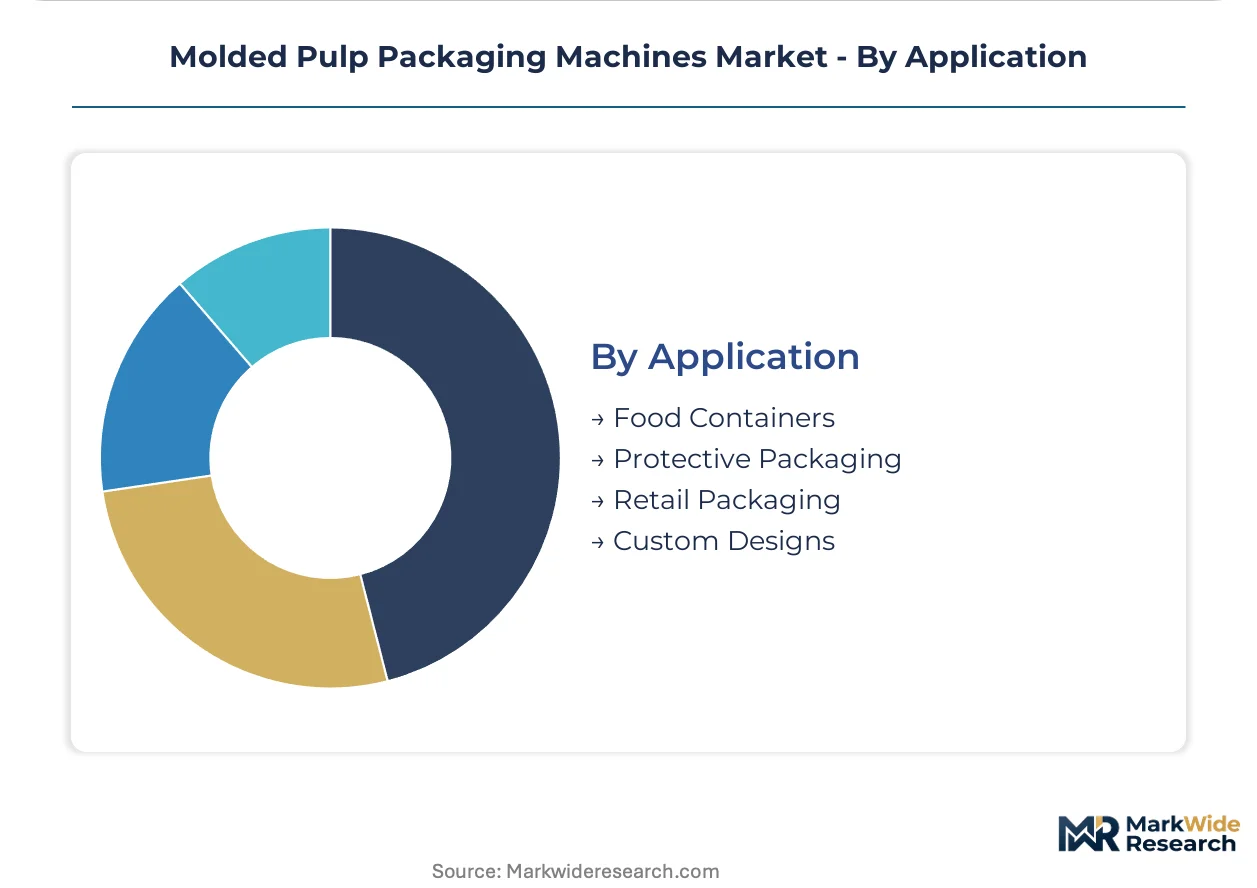
Application:
Mold complexity and tooling lead times fragment vendor specialization across application categories.
- Food Containers:Thin-wall trays, bowls, and clamshells requiring FDA food-contact substance notification compliance. Dairy and protein processors in the Netherlands deploy predictive maintenance sensor arrays on these lines to anticipate seal wear.
- Protective Packaging:Engineered cushioning and blocking for shock-sensitive goods. Anti-static fiber blends and custom geometries extend mold design cycles in this application.
- Retail Packaging:Shelf-ready display units and primary packaging for consumer goods. Compostability certification from TÜV Austria and BPI increasingly gates customer qualification.
- Custom Designs:Bespoke geometries for premium brand differentiation. Specialized aluminum foundries face 14-20 week delivery windows for complex molds here.
By unit volume, Food Containers lead. By margin per machine hour, Custom Designs is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor machinery producers with integrated tooling capabilities, while regulatory phase-outs in major economies accelerate replacement cycles for plastic-dependent equipment.
Germany
Food processors in Bavaria and North Rhine-Westphalia deploy automated compression molding lines for dairy tray production. The EU F-Gas Regulation enforces polystyrene foam elimination timelines that force packagers toward fiber-based alternatives. Machine builders in Stuttgart industrial clusters retool for thin-wall container robotics integration.
France
Ready-meal and bakery segments in Île-de-France accelerate mold redesign for PFAS-free oil resistance compliance. REACH restrictions on per- and polyfluoroalkyl substances eliminate legacy barrier coatings from food-contact applications. Packaging converters around Lyon partner with aluminum foundries for complex geometry tooling.
United States
Electronics shippers in Silicon Valley and Austin semiconductor clusters demand anti-static fiber blends and deep-draw vacuum forming capabilities. FDA food-contact substance notifications govern machine eligibility for national market entry. Western Pulp anchors regionalized service networks across California and Texas manufacturing corridors.
China
Bamboo and bagasse fiber slurry adoption reduces raw material costs for Asian pulp processors. The country's national sustainability frameworks align with compostability certification requirements from TÜV Austria and BPI. Machine fabricators in Zhengzhou and Shanghai integrate foundry operations to control mold delivery timelines.
India
The PLI scheme for sustainable packaging machinery creates localized assembly opportunities for European and Asian equipment suppliers. BIS mechanical safety certifications govern machine eligibility for domestic market sales. Converters in Maharashtra and Gujarat pilot semi-automated lines for flexible batch sizing.
Molded Pulp Packaging Machines Market Competitive Landscape
On the supply side, the industry is tiered between integrated tooling specialists and regional service providers. Hydraulic press fabricators and robotics integrators occupy distinct competitive layers. Dominant competitive moves include strategic partnerships with aluminum foundries and geographic expansion through regionalized spare-parts networks.
Within the integrated tooling tier, Mudanjiang City Joy Sun Pulp Molding Technology represents Chinese fabricators with captive foundry capabilities. Western Pulp exemplifies North American players anchoring demand through proximity-based service infrastructure. Kawaguchi Machinery occupies a position among precision robotics specialists serving thin-wall food container applications.
| Leading Market Players |
|---|
| Mudanjiang City Joy Sun Pulp Molding Technology |
| Gongyi City Hongrun Machinery |
| Fujian Hualong Machinery |
| Chaoan County Shuangxing Machinery |
| Zhengzhou Ailence Machinery |
| Shanghai Shouyu Machinery |
| Jiangsu Huaneng Machinery |
| Western Pulp |
| Kawaguchi Machinery |
| Others |
Supply & Pricing Matrix
Undercapacity in European aluminum foundries tightens mold delivery schedules and pushes equipment purchasers toward Asian suppliers with captive tooling operations. This utilization gap compresses pricing power for Western machine builders while rewarding integrated fabricators in China and India with order flow.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium robotics-integrated lines, standard automated systems, and economy manual presses. Price differentiation rests on certification grade—FDA food-contact notification compliance commands 15-25% premiums—and after-sales service bundling. Cost compression in the standard tier intensifies because equipment finance restructuring allows mid-sized converters to access previously premium capabilities. Food industry buyers in Germany and France exhibit lowest price sensitivity due to regulatory compliance deadlines, while artisan startup operations in Eastern Europe drive economy-tier volume.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for North American equipment purchasers. Manufacturing concentrates in China, Germany, and India, with precision aluminum mold sourcing anchored in Zhengzhou and Shanghai industrial clusters. Raw material dependencies span high-grade steel for hydraulic presses, servo motors for robotics integration, and specialty aluminum alloys for thermal cycling molds. Distribution runs through regionalized spare-parts networks where proximity service contracts determine vendor selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment specification fragmentation creates niche openings as EU Green Deal mandates splinter buyer requirements across compostability certification tiers and PFAS-free barrier integration needs.
For Market Incumbents: Pre-empt margin erosion in standard automated tiers by backward integration into aluminum foundry operations or captive mold production in Stuttgart and Zhengzhou clusters. Robotics integration capabilities represent the priority defensive investment as labor cost arbitrage shifts buyer preference toward pick-and-place automation. For New Entrants and Emerging Players: Pursue electronics protective packaging as the most penetrable white space, where anti-static fiber blend demand from semiconductor clusters in Silicon Valley and Austin outpaces specialized vacuum forming supply. A service-led go-to-market emphasizing predictive maintenance subscriptions unlocks recurring revenue without full equipment capital commitment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among robotics-integrated line suppliers with installed base sensor networks and performance-guarantee service contracts. Long-term viability favors acquisition targets with multi-territory compliance dossiers spanning FDA, BIS, and TÜV Austria certifications. Monitor PFAS-free barrier coating technical maturity as the inflection signal for food container market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Foundry Operations | Captive mold production compresses 14-20 week delivery windows for Asian suppliers serving European food packagers. |
| Robotics Integration for Thin-Wall Containers | Automated pick-and-place systems cut cycle times for dairy and ready-meal processors in Germany and France. |
| Predictive Maintenance Subscription Launch | Sensor arrays on hydraulic presses shift vendor revenue from spare parts toward uptime-guarantee contracts. |
| Multi-Territory Compliance Dossier Investment | Pre-validated FDA, BIS, and TÜV Austria certifications accelerate vendor qualification for consolidated retail procurement. |
| PFAS-Free Barrier Coating R&D Partnership | Plasma treatment and chitosan-based integration maintains food-contact functionality under REACH restrictions. |
Research Methodology
The analysis maps compression molding, vacuum forming, blow molding, and injection molding equipment categories, each validated through equipment procurement managers at food processors, aftermarket service heads at packaging converters, plant engineers at electronics shippers, and regulatory affairs leads at machine builders. Primary interview insights triangulate against customs trade data, SEC machinery filings, EU F-Gas Regulation implementation schedules, and TÜV Austria compostability certification databases. Bottom-up equipment shipment tracking and top-down end-use demand estimation reconcile through cross-segment consistency checks.
Fixed assumptions across the projection horizon include EU Green Deal plastic phase-out timelines, BIS mechanical safety certification requirements for Indian market entry, and sustained electricity price volatility in manufacturing-intensive regions. Segmentation dimensions modeled encompass product type, automation technology tier, end-use industry exposure, and application-specific mold complexity. CAGRs derive from equipment replacement cycle analysis and capacity expansion announcements across the analysis window. Industry-specific inputs include thermal dewatering energy consumption rates and precision aluminum mold lead time distributions.
Sensitivities concentrate around PFAS-free coating technical breakthroughs, EU F-Gas Regulation enforcement acceleration, and equipment finance availability shifts for mid-sized converters. Forecasts reflect documented assumptions about regulatory compliance timelines and raw material cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
Banding Machine Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Packaging Conveyors Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
LAMEA Printing Machinery Market
Packaging Machinery
Stacking Machine Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Automatic Banding Machine Market
Packaging Machinery
Binding & Lamination Machines Market
Packaging Machinery
Tamper Evidence Machinery Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Clamshell Labeling Machines Market