
 Glue Machine Market | 2026-2036
Glue Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Glue Machine Market Outlook
Preventive maintenance contracts and remote diagnostics software is recalibrating how OEMs monetize glue machine deployments. METAL CREATION CO., LTD. leverages its Japanese engineering base to sustain premium positioning in precision electronics bonding. Zhejiang Xinwei Machinery Co., Ltd. anchors cost-competitive fully automatic lines for packaging converters across Southeast Asia. Schaefer Machine Company differentiates through specialized hot melt configurations for automotive tier-one suppliers.
A glue machine is industrial equipment that dispenses, meters, and applies adhesive substrates at controlled temperatures, pressures, and flow rates, typically operating between 120°C and 200°C for hot melt systems and ambient conditions for cold glue variants, serving to join materials in continuous or batch manufacturing processes. Hot melt systems dominate installed base volume due to faster set times and elimination of drying stages, though epoxy segments command higher per-unit margins from aerospace and medical device validation requirements. Fully automatic installations are expanding fastest as labor costs rise and line integration with vision systems becomes standard, while manual units retain share in custom furniture workshops and prototype electronics labs where changeover flexibility outweighs throughput optimization.
FDA regulations govern adhesive contact with food packaging substrates in the United States, forcing equipment redesigns for clean-in-place compatibility and material traceability. REACH and RoHS frameworks in Europe restrict hazardous substance content in both adhesives and machine components, creating compliance barriers for imported equipment lacking CE marking and substance documentation. OSHA machine guarding standards further shape North American demand for enclosed dispensing heads and interlocked access panels. Stakeholders must weigh regulatory certification timelines against regional manufacturing localization decisions as trade documentation requirements intensify for cross-border equipment shipments.
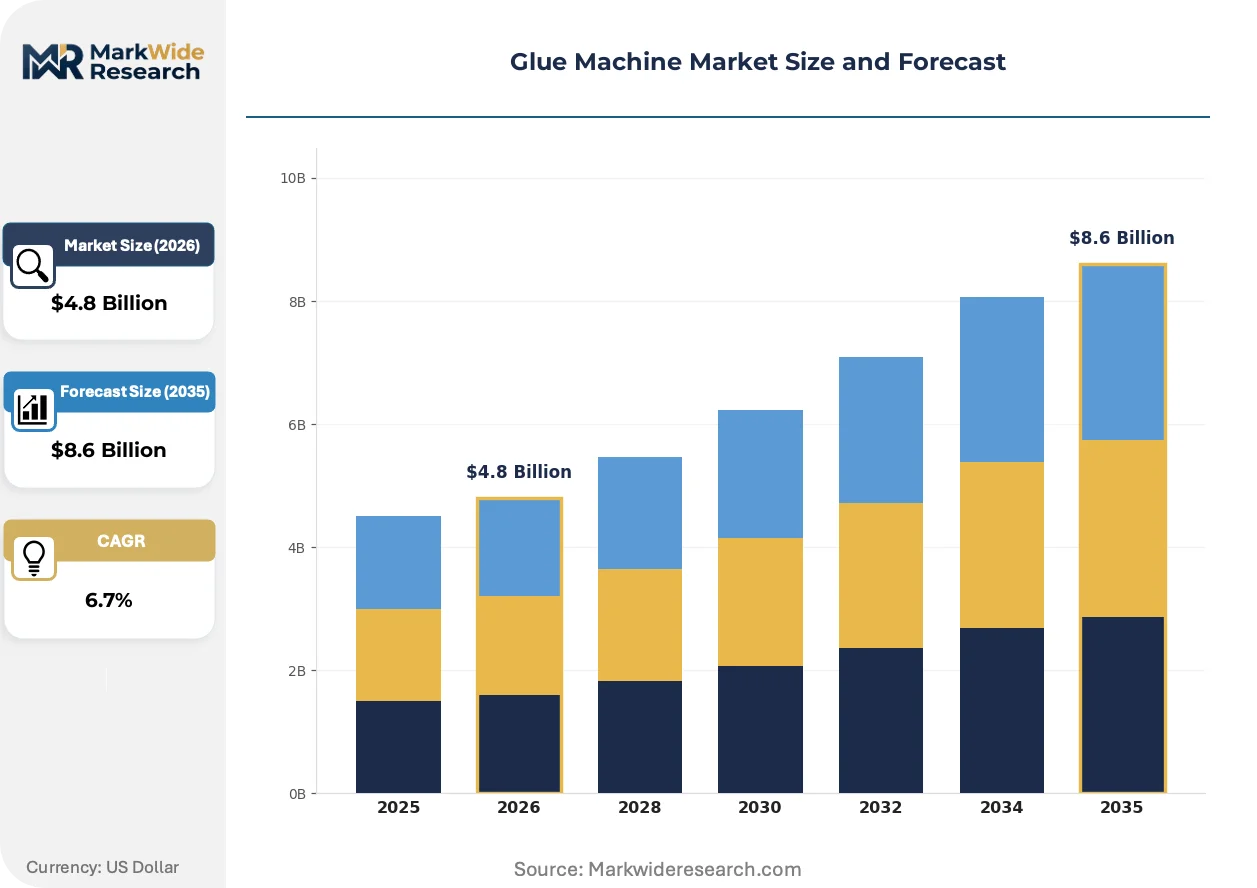
Market Dynamics
Packaging automation lines in Asia-Pacific are forcing equipment upgrades across installed bases, while REACH compliance in Europe accelerates solvent-free adhesive system replacements. OEMs now monetize through preventive maintenance contracts and remote diagnostics software rather than pure hardware sales.
Growth Catalysts
- Hot melt system dominance:Faster set times and elimination of drying stages pull demand from cold glue variants in high-throughput packaging lines. Food contact applications under FDA regulations further validate equipment redesigns for clean-in-place compatibility.
- India and Vietnam manufacturing concentration:Export-oriented furniture and electronics assembly clusters concentrate emerging capacity, driving localized equipment procurement. Government industrial zone incentives accelerate greenfield automation investments.
- Fully automatic line integration:Labor cost inflation across Southeast Asia pushes converters toward vision-system-integrated dispensing. Changeover flexibility trade-offs diminish as batch sizes standardize for e-commerce packaging volumes.
Market Restraints
- Epoxy raw material volatility:Petrochemical feedstock fluctuations compress margins for aerospace and medical device validation-grade systems. Specialized hot melt configurations for automotive tier-one suppliers face input cost pass-through limitations.
- CE marking documentation barriers:REACH and RoHS substance documentation requirements block imported equipment lacking European compliance infrastructure. Certification timelines extend 8-14 months for Asian OEMs without established EU representation.
- Cold glue substitution pressure:Ambient-condition adhesive variants retain share in custom furniture workshops where temperature-controlled infrastructure investment is prohibitive. Manual units resist displacement in prototype electronics labs requiring rapid changeover flexibility.
Strategic Opportunities
- Remote diagnostics software penetration:Unbundled predictive maintenance contracts create recurring revenue streams beyond initial hardware deployment. Japanese engineering-base OEMs leverage precision electronics bonding expertise to command premium positioning.
- OSHA machine guarding upgrade cycle:North American enclosed dispensing head and interlocked access panel mandates force replacement of legacy open-architecture equipment. Compliance-driven procurement favors vendors with documented safety system integration.
- Vision system convergence:Glue dispensing heads integrating real-time substrate inspection compress quality control station footprint. Automotive and medical device manufacturers consolidate inspection and bonding operations to reduce line length.
Industry Challenges
- Clean-in-place engineering talent scarcity:FDA food packaging substrate compliance requires specialized fluid dynamics and materials science expertise. Equipment redesign cycles extend as qualified validation engineers concentrate with pharmaceutical system vendors.
- Legacy PLC integration complexity:Brownfield packaging lines running proprietary control architectures resist seamless Industry 4.0 connectivity upgrades. Retrofit gateway solutions introduce latency incompatible with high-speed dispensing synchronization.
- Cross-border trade documentation intensification:Customs authorities in Germany, Japan, and the United States demand granular substance declarations for adhesive-contact machine components. Shipment delays accumulate from harmonized tariff schedule reclassification disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glue Machine Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Cold Glue, Epoxy, Pressure Sensitive Installation: Manual, Semi-Automatic, Fully Automatic, Mobile End User: Automotive, Electronics, Furniture, Packaging Application: Assembly, Bonding, Sealing, Coating |
| Companies Covered | METAL CREATION CO., LTD., Zhejiang Xinwei Machinery Co., Ltd., Schaefer Machine Company, SBL MACHINERY CO., LTD., Robus India, Glue Machinery Corp., POLYTEX AG, FERPLAST, Shantou Quanfangwei Machinery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glue Machine Market Strategic Shifts
Equipment architecture is fragmenting into interoperable subsystems as converters demand flexibility without sacrificing throughput. Three developments are compressing traditional integrated-line economics.
Modular dispensing head platforms are modularizing glue machine architecture. Automotive tier-one suppliers and medical device contract manufacturers adopt swappable heated manifold configurations to reduce SKU-specific tooling inventory. This technology is modularizing capital deployment, allowing converters to defer full-line replacement and upgrade subsystems incrementally.
REACH authorization list expansion is restricting hazardous substance content in both adhesives and machine components. European packaging converters face equipment obsolescence risk as candidate list substances migrate to Annex XIV. Hot melt system manufacturers with pre-validated substance portfolios capture replacement demand from competitors scrambling to reformulate.
After-sales service unbundling is separating hardware procurement from maintenance obligation. Large packaging converters in Germany and Japan now tender predictive analytics and spare parts logistics as standalone contracts. This shift concentrates vendor selection criteria on software platform maturity rather than mechanical reliability alone.
Glue Machine Market Segmentation
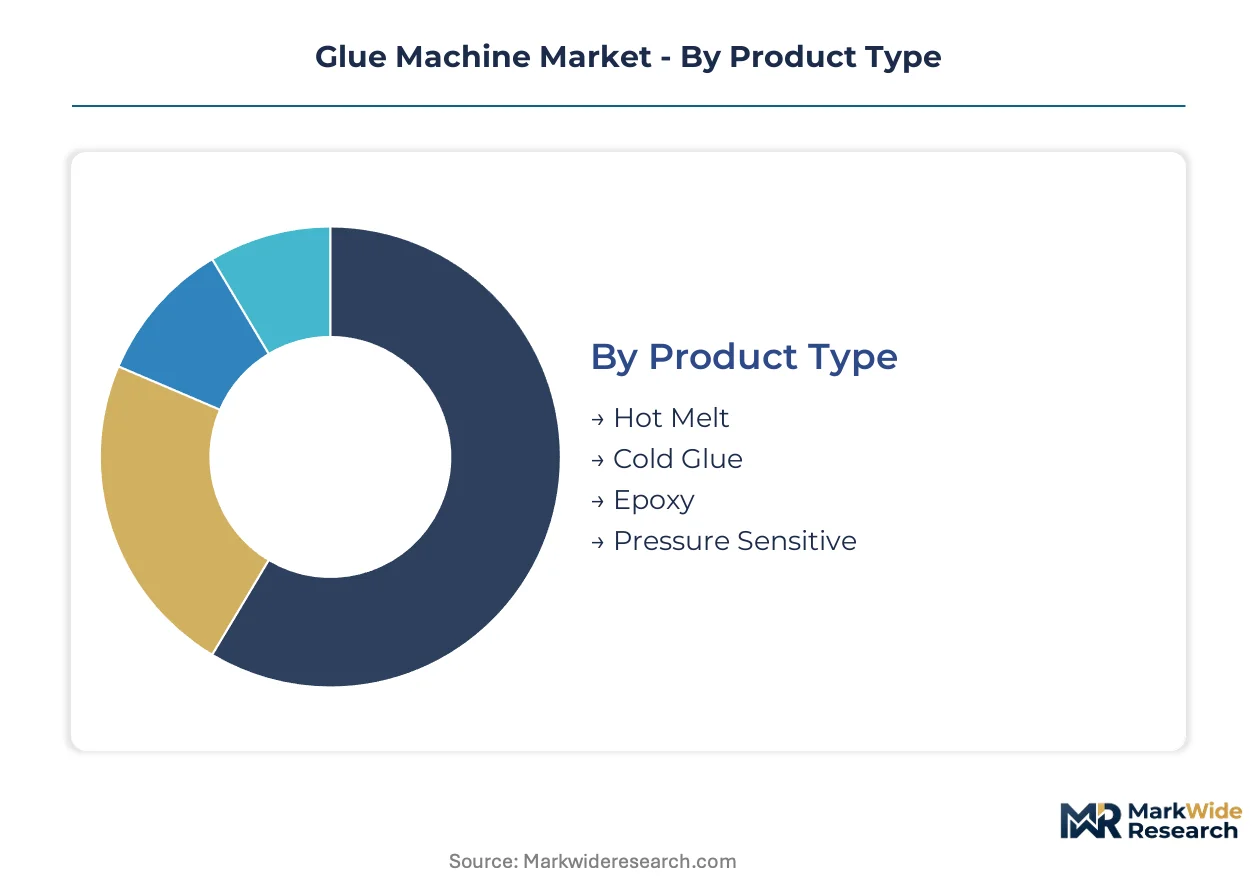
Glue machine segmentation reveals how thermal requirements, automation intensity, and regulatory exposure split procurement budgets across manufacturing verticals. Equipment specification diverges sharply between FDA-governed food packaging substrates and aerospace-grade epoxy validation protocols.
Product Type:
Buyers in this category differentiate primarily by set time requirements and energy infrastructure availability.
- Hot Melt:Thermoplastic adhesive systems operate between 120°C and 200°C with polymer-based formulations that eliminate drying stages. High-throughput packaging lines in Germany and Japan favor these systems for continuous board-feed operations where compressed air costs dominate unit economics.
- Cold Glue:Ambient-condition water-based adhesives require no heated manifold infrastructure. Custom furniture workshops in Vietnam and India retain these systems where temperature-controlled capital investment is prohibitive and batch sizes remain irregular.
- Epoxy:Two-component thermoset systems command premium positioning in aerospace structural bonding and medical device assembly where FDA validation documentation is mandatory.
- Pressure Sensitive:Self-adhesive coating equipment serves label converting and tape manufacturing with immediate tack properties without thermal activation.
Hot Melt leads volumes today; Fully Automatic installations are gaining share fastest.
Installation:
Procurement patterns in this category track labor cost trajectories and line integration maturity.
- Fully Automatic:Vision-system-integrated dispensing heads synchronize with upstream carton erectors and downstream case packers. Electronics assembly clusters in South Korea and Taiwan deploy these configurations for smartphone and semiconductor packaging where defect rates below 50 ppm are contractual requirements.
- Manual:Handheld or bench-mounted units serve prototype electronics labs and artisan furniture workshops. Rapid changeover flexibility outweighs throughput optimization in these environments where SKU variety exceeds production volume.
- Semi-Automatic:Operator-fed systems with automated dispensing cycles bridge cost thresholds for mid-volume converters.
- Mobile:Portable cart-mounted configurations serve field repair operations and temporary production lines.
Fully Automatic dominates new capital deployment; Mobile configurations expand most quickly in contract manufacturing.
End User:
Margin structures in this category separate validation-intensive medical and aerospace applications from commodity packaging procurement.
- Packaging:Corrugated case sealing and folding carton operations constitute the largest installed base. E-commerce volume concentration in the United States and China drives equipment refresh cycles as line speeds push past 400 cases per minute.
- Electronics:Precision bonding of display assemblies, battery packs, and circuit board conformal coatings demands micron-level dispensing accuracy. Japanese and South Korean OEMs specify equipment with closed-loop pressure control and real-time viscosity compensation.
- Automotive:Tier-one suppliers bond interior trim, lighting assemblies, and structural components with hot melt configurations rated for vibration and thermal cycling.
- Furniture:Edge banding and veneer pressing operations in Vietnam and Poland concentrate export-oriented capacity with cost-optimized manual and semi-automatic lines.
Packaging commands the largest equipment base; Electronics applications show the steepest expansion trajectory.
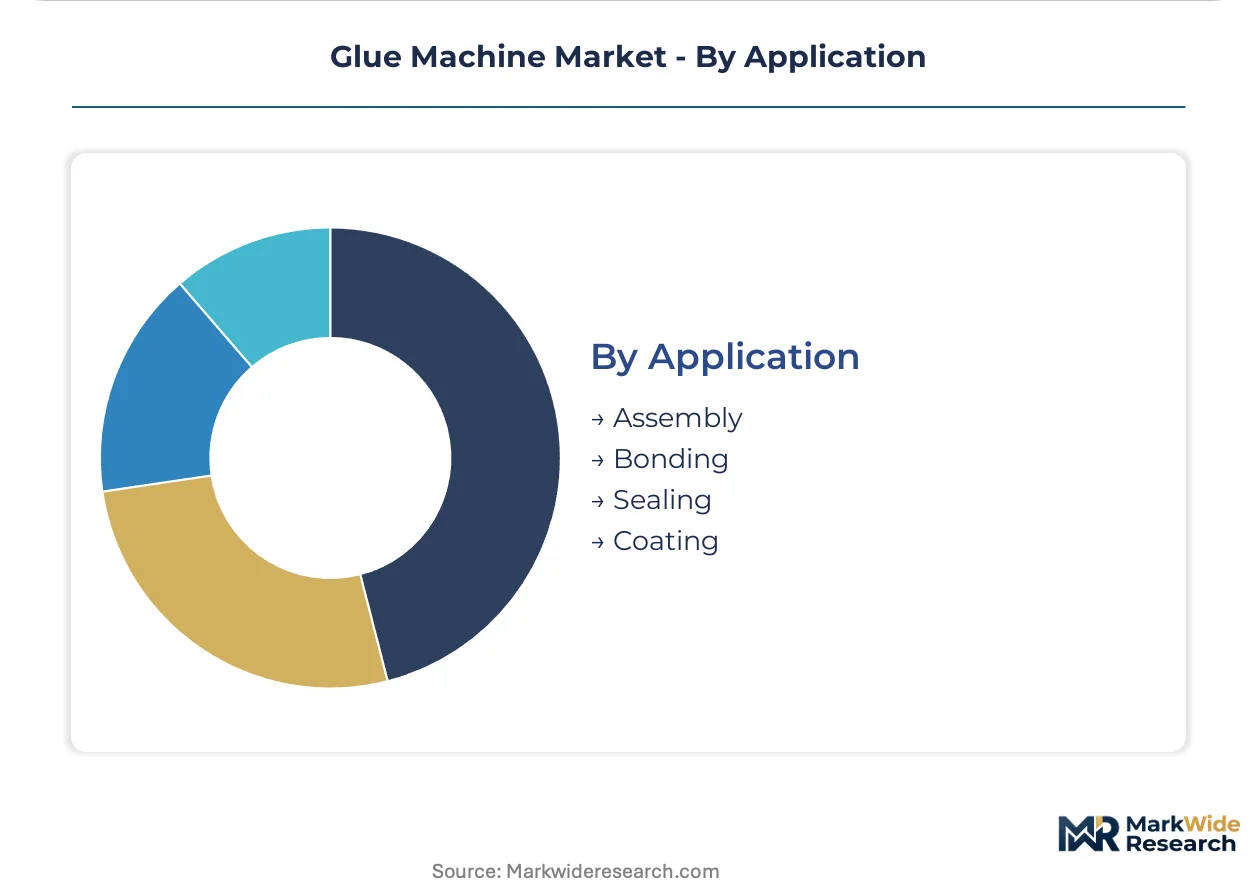
Application:
Process requirements in this category determine dispensing head architecture and substrate handling integration.
- Assembly:Component joining operations in automotive and electronics manufacturing require programmable bead patterns and multi-axis positioning. Medical device contract manufacturers in Germany and Switzerland specify cleanroom-compatible stainless steel construction with validated cleaning protocols.
- Bonding:Structural adhesive applications in aerospace and construction materials demand controlled clamp pressure and cure temperature monitoring. REACH-compliant solvent-free formulations are displacing legacy systems in European operations.
- Sealing:Gasket and enclosure closure applications in food packaging and electronics housings prioritize hermetic integrity over structural load bearing.
- Coating:Uniform adhesive film deposition for label stock and tape manufacturing requires slot-die or roll-coater integration with tension-controlled unwind stands.
Assembly generates the highest equipment revenue; Sealing applications are climbing the fastest as barrier packaging requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping glue machine procurement geography. Manufacturers migrate toward jurisdictions with streamlined REACH documentation pathways and concentrated industrial zone incentives, compressing equipment refresh cycles in compliant clusters while delaying investment in high-documentation-cost markets.
Germany
Automotive tier-one suppliers in Baden-Württemberg and Bavaria drive demand for hot melt configurations with vibration-rated specifications. ECHA REACH authorization list expansion forces packaging converters toward pre-validated substance portfolios. The Stuttgart industrial corridor concentrates equipment replacement demand as legacy systems face Annex XIV substance restrictions.
United States
OSHA machine guarding standards mandate enclosed dispensing heads and interlocked access panels across corrugated case sealing operations. FDA regulations govern adhesive contact with food packaging substrates, forcing clean-in-place compatibility redesigns. E-commerce volume concentration in the Midwest and Southeast pushes line speeds past 400 cases per minute, triggering automation upgrades.
China
GB standards and MIIT industrial automation directives accelerate vision-system-integrated dispensing deployment in Yangtze River Delta electronics clusters. Dual carbon goals pressure packaging converters toward energy-efficient hot melt systems. Shenzhen and Dongguan manufacturing bases concentrate smartphone and semiconductor packaging equipment procurement where defect rates below 50 ppm are contractual requirements.
Vietnam
Government industrial zone incentives accelerate greenfield automation investments in export-oriented furniture assembly. Ambient-condition cold glue systems retain share where temperature-controlled capital investment remains prohibitive. Ho Chi Minh City and Binh Duong provinces concentrate edge banding and veneer pressing operations with cost-optimized manual and semi-automatic lines.
Japan
METI industrial efficiency standards push precision electronics bonding equipment with closed-loop pressure control. JIS certification requirements sustain premium positioning for domestic engineering-base OEMs. Kanto and Kansai manufacturing clusters demand micron-level dispensing accuracy for display assembly and battery pack bonding operations.
Glue Machine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. The vendor base organizes into three tiers: Japanese and German engineering-base OEMs commanding premium positioning, Chinese cost-optimized fabricators capturing volume in Southeast Asia, and regional specialists serving validation-intensive aerospace and medical device applications. Consolidation pressure concentrates among mid-scale European players facing REACH compliance cost escalation. Dominant competitive moves include geographic expansion into Vietnam and India industrial zones, plus strategic partnerships for remote diagnostics software integration.
Within the precision-engineering tier, METAL CREATION CO., LTD. exemplifies Japanese engineering-base positioning for electronics bonding applications. Zhejiang Xinwei Machinery Co., Ltd. and Shantou Quanfangwei Machinery Co., Ltd. represent Chinese cost-optimized fabricators anchoring fully automatic lines for packaging converters. Schaefer Machine Company occupies a position among North American specialists serving automotive tier-one supplier requirements. These three archetypes illustrate how geographic origin and customer validation intensity stratify competitive positioning rather than pure scale.
| Leading Market Players |
|---|
| METAL CREATION CO., LTD. |
| Zhejiang Xinwei Machinery Co., Ltd. |
| Schaefer Machine Company |
| SBL MACHINERY CO., LTD. |
| Robus India |
| Glue Machinery Corp. |
| POLYTEX AG |
| FERPLAST |
| Shantou Quanfangwei Machinery Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of heated manifold assemblies and precision dispensing heads anchors premium-tier pricing power for Japanese and German engineering-base OEMs, while outsourced fabrication of standard pneumatic components compresses margins for cost-optimized fabricators serving Southeast Asian packaging converters. This integration divergence separates vendors who command validation-grade premiums from those competing on unit economics in high-volume, low-customization procurement.
Pricing Analysis
Distributor margin layers in European and North American markets absorb 15-25 points before equipment reaches end-users, while direct-to-OEM contracts in Asia-Pacific bypass intermediaries for volume discounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification intensity—FDA-validated systems for medical device bonding command substantial premiums over CE-marked packaging equipment. Cost compression in economy-tier manual units is intensifying because Vietnamese and Indian fabricators are scaling standardized platform production. Contract packaging converters in Germany and Japan show lowest price sensitivity due to downtime cost exposure, while Vietnamese furniture workshops prioritize capital outlay minimization above performance specifications.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Chicago maintain 4-6 week safety stocks of critical spare parts, with hub-and-spoke patterns radiating to secondary industrial clusters. Manufacturing concentration in China, Germany, and Japan supplies 70% of precision dispensing heads and heated manifolds, while Taiwan and South Korea dominate servo motor and vision system componentry. Raw material dependencies center on specialty steel alloys for corrosion-resistant construction, polymer formulations for hot melt adhesive compatibility, and rare-earth magnets for precision motion control. Single-source vulnerability in high-temperature sensor supply creates bottleneck exposure when Japanese component makers face allocation constraints. Distribution runs through authorized dealer networks for validation-intensive segments, with direct factory relationships governing high-volume packaging converter procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on software unbundling and predictive maintenance contract penetration, where recurring revenue streams offset hardware commoditization pressure in standard packaging equipment tiers.
For Market Incumbents: Acquire remote diagnostics software platforms and predictive analytics capabilities to fortify aftermarket revenue capture. METAL CREATION CO., LTD. and comparable Japanese engineering-base OEMs should consolidate specialized hot melt configuration expertise through targeted talent acquisition in automotive tier-one supplier engineering departments. CE marking documentation infrastructure represents a critical defensive moat—vendors without established EU representation face 8-14 month certification delays that lock them out of replacement demand cycles triggered by REACH Annex XIV substance restrictions. Channel control through exclusive distribution agreements in Vietnam and India industrial zones limits price erosion from gray-market equipment imports. For New Entrants and Emerging Players: OSHA machine guarding standards in the United States open a window for enclosed dispensing head and interlocked access panel specialists to capture compliance-driven replacement demand from legacy open-architecture equipment bases. Vision system convergence presents the most penetrable white-space—glue dispensing heads integrating real-time substrate inspection compress quality control station footprint for automotive and medical device manufacturers consolidating inspection and bonding operations. Target contract manufacturing clusters in Mexico and Eastern Europe where brownfield packaging lines resist seamless Industry 4.0 connectivity upgrades and retrofit gateway solutions introduce latency incompatible with high-speed dispensing synchronization. Go-to-market positioning should emphasize modular dispensing head platforms that allow converters to defer full-line replacement and upgrade subsystems incrementally. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with validation-intensive aerospace and medical device customer relationships because customer switching costs and requalification timelines create sticky revenue bases resistant to price competition. Platform consolidation among mid-scale European players facing REACH compliance cost escalation offers acquisition currency for private equity sponsors with regulatory affairs infrastructure. Long-term viability across the projection horizon favors vendors with software platform maturity rather than mechanical reliability alone—predictive maintenance contract penetration rates serve as the critical inflection indicator for recurring revenue transformation and multiple expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Diagnostics Software Integration | Unbundled predictive maintenance contracts create recurring revenue streams beyond initial hardware deployment for Japanese OEMs. |
| REACH-Compliant Substance Portfolio Pre-validation | Hot melt system manufacturers with validated portfolios capture replacement demand from competitors scrambling to reformulate adhesives. |
| Vision System Convergence Development | Real-time substrate inspection integration compresses quality control footprint for automotive tier-one suppliers in Germany. |
| Modular Dispensing Head Platform Expansion | Swappable heated manifold configurations reduce SKU-specific tooling inventory for medical device contract manufacturers. |
| CE Marking Documentation Infrastructure Investment | Established EU representation accelerates certification timelines for Asian OEMs targeting European packaging converter replacement cycles. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at packaging converters across Germany, Japan, China, Vietnam, and the United States with secondary validation from customs trade data, SEC filings of disclosed equipment vendors, MIIT industrial automation directives, and ECHA REACH authorization list updates. Bottom-up equipment shipment tracking and top-down manufacturing capacity analysis were triangulated against adhesive consumption patterns and industrial zone investment incentive disclosures.
Comparable-period anchoring tied projection models to historical reference periods spanning equipment refresh cycles, regulatory compliance deadlines, and industrial automation adoption waves across the analysis window. Segmentation dimensions modeled include product type thermal requirements, installation automation intensity, end-user validation exposure, and application process architecture. CAGRs were derived from installed base turnover rates, greenfield investment trajectories, and replacement demand timing linked to substance restriction phase-in schedules. Forecast inputs incorporated labor cost inflation indices for Southeast Asian manufacturing clusters and e-commerce packaging volume concentration patterns in the United States and China.
Revisions become necessary when REACH authorization list expansions accelerate, OSHA machine guarding enforcement intensifies, or raw material volatility in petrochemical feedstocks disrupts epoxy system margin structures. Forecasts reflect documented assumptions about regulatory timeline adherence, industrial zone incentive continuity, and vision system integration cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Food Packaging Machinery Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Binding & Lamination Machines Market
Packaging Machinery
Global Paper Napkin Making Machine Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Side Sealer Machines Market
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Lid Applicator Machine Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Pouch Sealing Machine Market
Packaging Machinery
Thermoform Fill Sealing Machine Market
Packaging Machinery
Paper Napkins Converting Machines Market