
 Overwrapping Machines Market | 2026-2036
Overwrapping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Overwrapping Machines Market Analytics
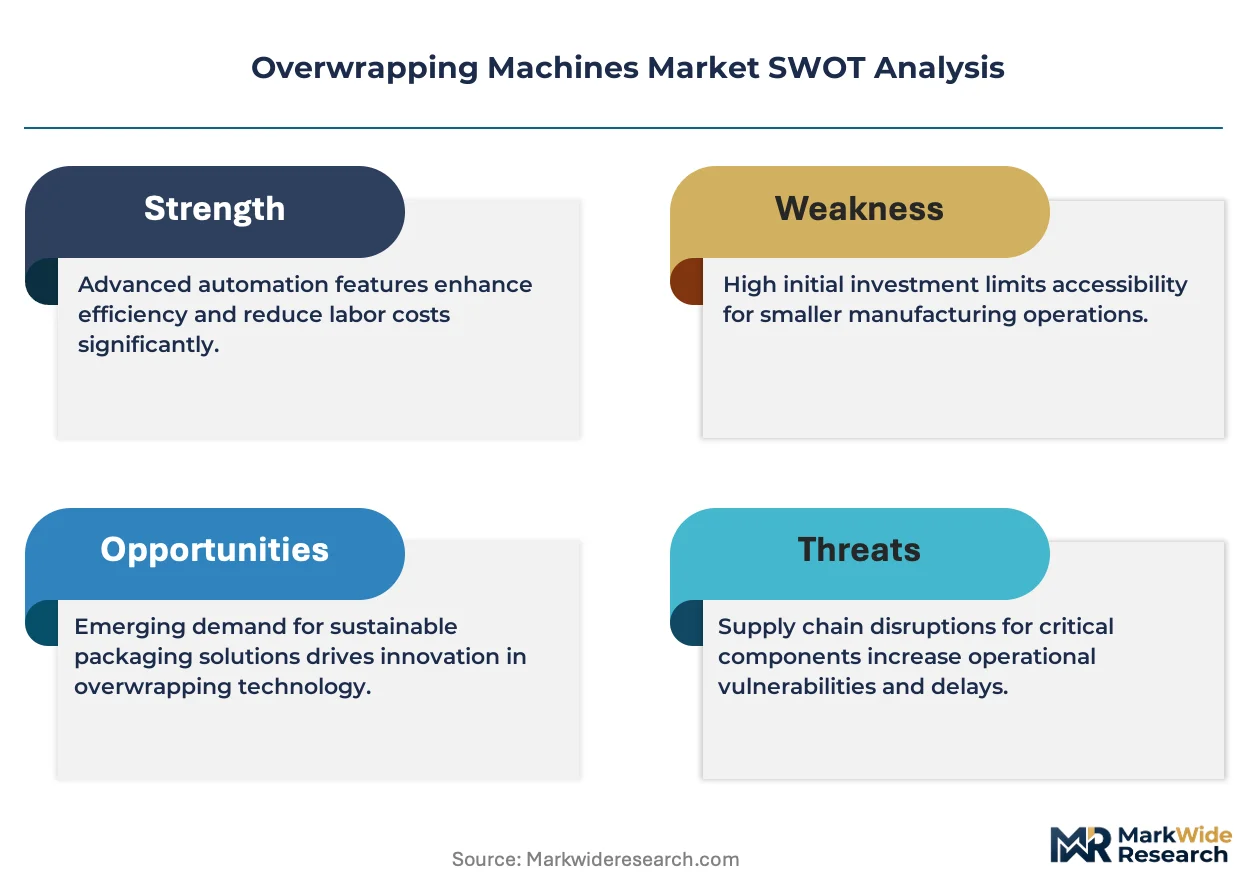
Bundle-size modularization is restructuring how food and consumer goods manufacturers specify overwrapping equipment, shifting procurement from single-lane to multi-lane configurable systems that handle variable pack counts without changeover downtime. IMA Group leverages its pharmaceutical serialization expertise to cross-sell integrated overwrapping-cartoning lines to cosmetics houses seeking compliance-ready packaging suites. ULMA Packaging anchors its competitive position through captive film supply partnerships that stabilize raw material access for European bakery and confectionery clients. TAM Tokyo Automatic Machinery specializes in ultra-compact vertical overwrappers designed for Japanese convenience-store portion packs, occupying a niche where floor-space constraints override throughput metrics.
Overwrapping machines apply a tight, continuous film sleeve around individual products or product bundles using heat-seal, cold-seal, or pressure-seal technologies, with typical operating speeds ranging from 30 to 600 packs per minute depending on configuration and product stability requirements. Automatic horizontal systems lead installed capacity in mature markets where labor costs justify capital intensity, while semi-automatic vertical units represent the fastest-growing configuration in emerging manufacturing economies seeking flexible entry-level automation. Heat-seal technology commands the largest technology segment by installed base due to its compatibility with polyolefin and PVC films, though cold-seal systems are capturing margin pools in temperature-sensitive pharmaceutical and chocolate applications where thermal degradation risks exclude hot-seal methods.
FDA cGMP guidelines and EU MDR traceability requirements shape pharmaceutical overwrapper specifications by mandating serialization-ready machine architectures with integrated vision verification and reject stations. REACH and RoHS frameworks restrict certain plasticizers and heavy metals in sealing films, compelling equipment makers to qualify alternative film chemistries and validate seal-bar temperature profiles for compliant materials. Stakeholders must monitor evolving extended producer responsibility regulations across multiple geographies, as film-recycling quotas will increasingly dictate material compatibility requirements that determine machine resale value and retrofit economics.
Market Dynamics
Pharmaceutical serialization mandates across Germany and the EU are compressing replacement cycles for legacy overwrapping equipment, forcing manufacturers to prioritize integrated vision-verification architectures over standalone machinery upgrades.
Growth Catalysts
- EU MDR Traceability Mandates:Medical device manufacturers in Germany and France must deploy serialization-ready overwrapping lines with integrated reject stations, creating pull for compliant machine architectures.
- FMCG Localization in India:Domestic consumer goods brands are building captive film-overwrapping capacity to reduce dependency on imported Chinese packaging systems.
- Heat-Seal Technology Upgrades:European cosmetics manufacturers are replacing cold-seal equipment with advanced heat-seal systems that accommodate bio-based polyolefin films under REACH compliance.
Market Restraints
- Film Raw Material Concentration:Polyolefin and PVC film supply chains concentrate among a limited set of European and Asian petrochemical suppliers, exposing equipment makers to input cost volatility.
- REACH Plasticizer Restrictions:ECHA frameworks ban certain phthalate plasticizers in sealing films, forcing expensive requalification of seal-bar temperature profiles for alternative chemistries.
- Substitution by Flow-Wrapping:High-speed food applications in bakery and snack segments increasingly adopt flow-wrapping systems that offer superior throughput for single-serve portions.
Strategic Opportunities
- Modular Multi-Lane Systems:Food and confectionery producers seek configurable overwrappers handling variable pack counts without changeover downtime, opening white space for flexible automation.
- Extended Producer Responsibility Tailwinds:EU Green Deal recycling quotas for plastic packaging films will favor equipment compatible with mono-material and chemically recyclable substrates.
- Ultra-Compact Vertical Designs:Japanese convenience-store portion-pack formats create demand for floor-space-optimized overwrappers where spatial constraints override speed metrics.
Industry Challenges
- Serialization Integration Complexity:Pharmaceutical manufacturers struggle to retrofit legacy overwrapping lines with FDA cGMP-compliant vision verification and track-and-trace modules without full replacement.
- Cross-Material Certification Timelines:Equipment makers face extended validation periods when qualifying seal systems for novel bio-based films under evolving REACH and RoHS substance restrictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overwrapping Machines Market |
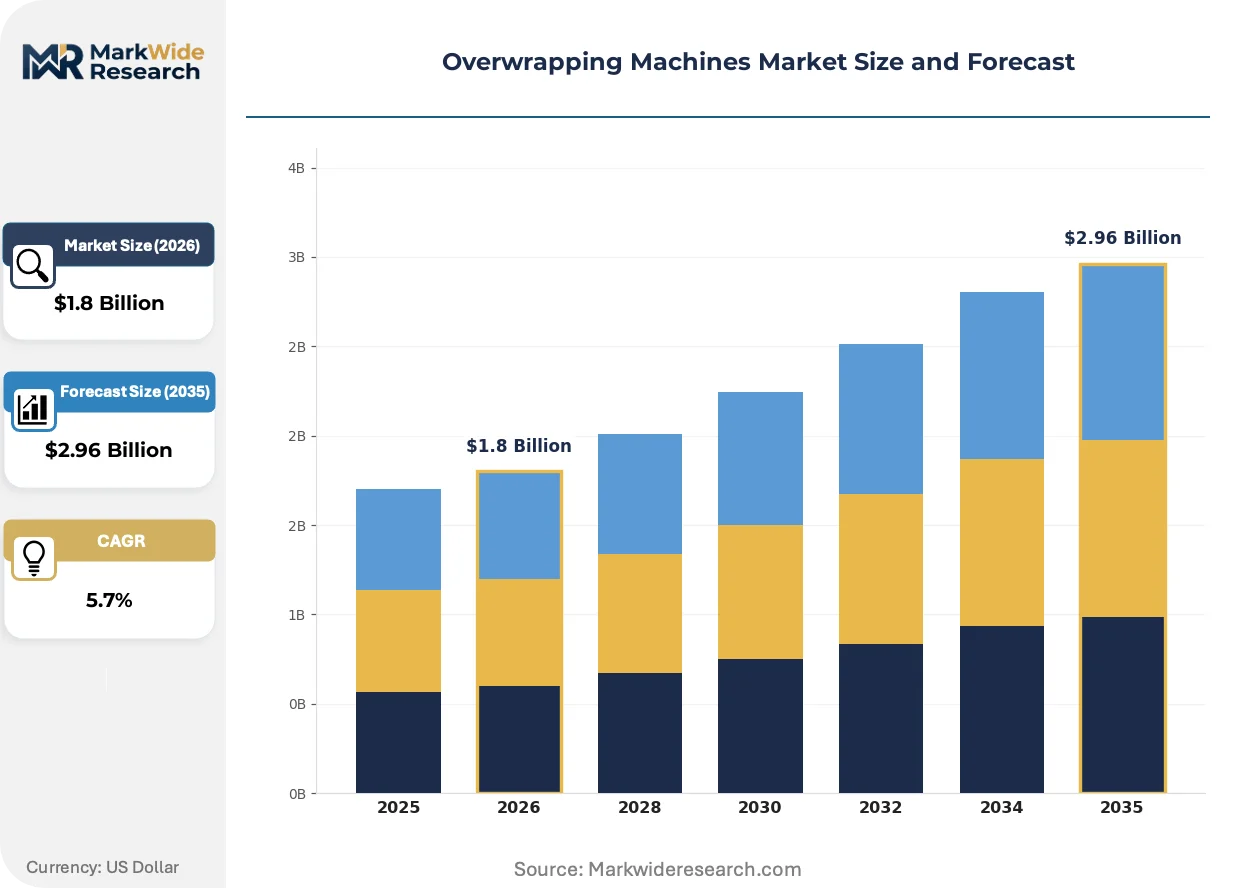
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Automatic, Semi-Automatic End User: Food, Pharmaceuticals, Consumer Goods, Cosmetics Material: Plastic Film, Paper, Laminated Film, Others Technology: Heat Seal, Cold Seal, Pressure Seal, Wrapping Film |
| Companies Covered | IMA Group, Marchesini Group, FOCKE & CO, ULMA Packaging, CAM Packaging, Sollas Holland BV, ProMach, Uhlmann Packaging, TAM Tokyo Automatic Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overwrapping Machines Market Evolving Landscape
Equipment architectures are pivoting from standalone overwrapping units toward integrated packaging suites that combine film application, cartoning, and serialization in single-line configurations.
Vision-based inspection systems are converging with robotic reject handling to create closed-loop quality control in pharmaceutical overwrapping lines. German contract packaging services are deploying these integrated architectures at scale to meet EU MDR aggregation requirements. This convergence is compressing the addressable market for standalone overwrappers without native serialization capability.
REACH substance restrictions on heavy metals and specific plasticizers are compelling equipment manufacturers to revalidate seal-bar temperature profiles for compliant film chemistries. The industrial consequence is extended equipment qualification timelines and higher engineering costs passed to buyers. Pharmaceutical and cosmetics segments in France and Germany are absorbing these premiums to maintain market access.
Buyer preference is consolidating around outcome-based equipment performance contracts rather than traditional capital purchase models. European bakery and confectionery producers are unbundling maintenance and film supply from machine acquisition, shifting risk to OEMs. This pattern is most visible in Germany where energy cost pressures make predictable operating expenditures preferable to large upfront capex.
Overwrapping Machines Market Segmentation
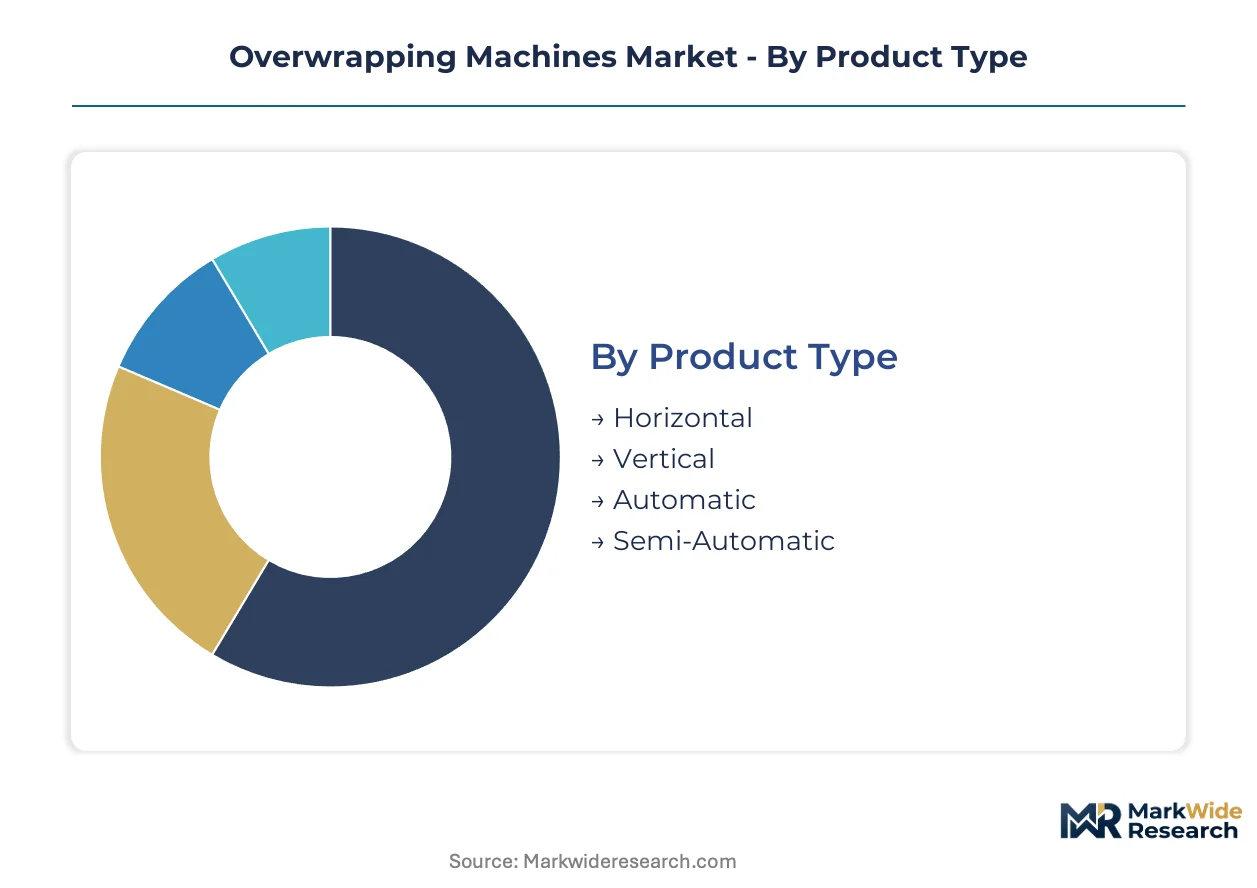
Overwrapping machine procurement patterns diverge sharply between high-volume commodity producers seeking throughput maximization and premium manufacturers prioritizing serialization compliance and flexible format changeovers. Understanding these splits enables equipment suppliers to align R&D investments with divergent buyer economics across pharmaceutical, food, and cosmetics verticals.
Product Type:
Automatic horizontal systems anchor volume procurement in mature manufacturing economies, while semi-automatic vertical configurations capture entry-level automation demand in emerging markets.
- Horizontal:These systems apply film sleeves across a horizontal product flow path, achieving sustained speeds of 200-600 packs per minute for stable rectangular formats. German pharmaceutical contract packers deploy these architectures to meet EU MDR aggregation requirements with integrated cartoning modules.
- Vertical:Compact footprint designs orient film application vertically, sacrificing absolute throughput for spatial efficiency. Japanese convenience-store suppliers specify ultra-compact vertical units where floor-space constraints in urban production facilities override speed metrics.
- Automatic:Fully automated systems integrate feeding, film cutting, sealing, and discharge without operator intervention. European bakery chains favor these configurations to offset labor cost pressures in high-wage manufacturing environments.
- Semi-Automatic:Operator-assisted systems require manual loading with automated sealing cycles. Indian domestic FMCG brands deploy semi-automatic vertical units as stepping-stone automation that reduces import dependency on fully integrated Chinese packaging lines.
Today's leader: Horizontal automatic systems. Tomorrow's challenger: Semi-automatic vertical configurations gaining share fastest in South and Southeast Asian manufacturing expansion.
End User:
Pharmaceutical serialization mandates concentrate premium equipment demand, while food sector volume requirements drive standard-configuration procurement at scale.
- Food:Bakery, confectionery, and snack producers specify heat-seal overwrappers compatible with polyolefin films for moisture barrier protection. REACH plasticizer restrictions are forcing European food manufacturers to revalidate seal-bar profiles for compliant film chemistries.
- Pharmaceuticals:Drug manufacturers and contract packaging services require FDA cGMP-compliant architectures with native vision verification, reject stations, and track-and-trace integration. German serialization mandates are compressing replacement cycles for legacy equipment lacking these capabilities.
- Consumer Goods:Household product and personal care brands prioritize format flexibility for promotional multi-packs. Indian localization trends are building captive overwrapping capacity to reduce supply chain exposure to imported Chinese systems.
- Cosmetics:Premium beauty houses demand cold-seal or precision heat-seal systems that prevent thermal degradation of temperature-sensitive formulations. European cosmetics manufacturers are upgrading to advanced heat-seal platforms compatible with bio-based polyolefin films under evolving REACH frameworks.
Pharmaceutical specifications currently command the highest equipment margins. Food sector volume provides the installed base foundation.
Material:
Film chemistry selection directly determines seal technology compatibility and regulatory compliance pathways across end-use applications.
- Plastic Film:Polyolefin and PVC formulations dominate installed capacity due to cost efficiency and heat-seal compatibility. ECHA restrictions on specific plasticizers are compelling equipment requalification for alternative chemistries.
- Paper:Kraft and coated paper substrates serve sustainability-positioned brands seeking plastic reduction. Cold-seal or pressure-seal systems accommodate paper's thermal sensitivity.
- Laminated Film:Multi-layer structures combining plastic, aluminum, and paper deliver barrier properties for extended shelf-life pharmaceuticals. Extended producer responsibility quotas under the EU Green Deal are favoring mono-material alternatives.
- Others:Cellulose-based and emerging bio-polymer films occupy niche applications where compostability certifications justify premium positioning.
Plastic film maintains volume dominance. Laminated and paper alternatives are climbing fastest as regulatory pressure intensifies on single-use plastics.
Technology:
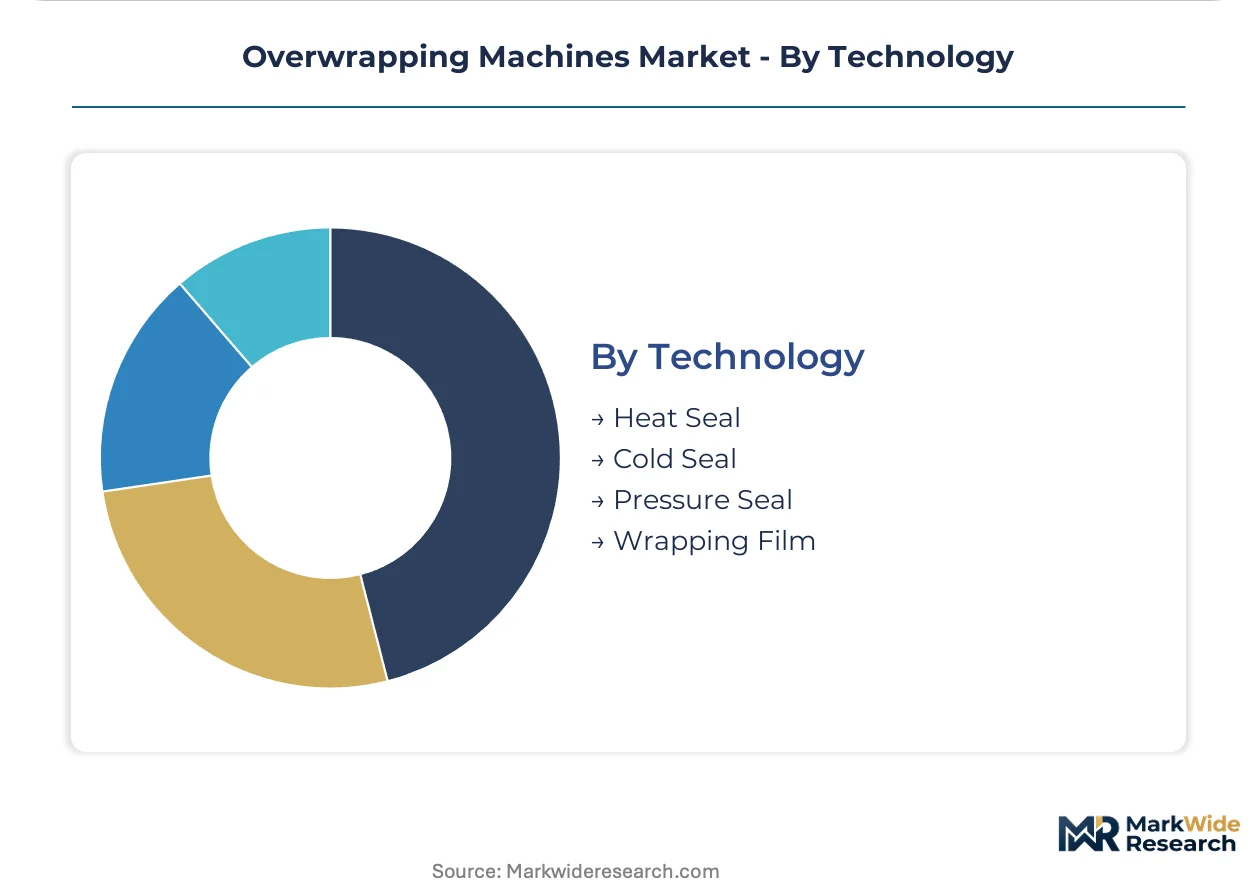
Seal method selection hinges on product thermal stability, film chemistry, and throughput requirements that vary across pharmaceutical, food, and cosmetics applications.
- Heat Seal:Thermal bonding of thermoplastic films delivers strong seals at high speeds. European cosmetics manufacturers are driving upgrade cycles to advanced heat-seal platforms compatible with REACH-compliant bio-based polyolefins.
- Cold Seal:Pressure-activated adhesive coatings eliminate thermal exposure for chocolate, wax-based pharmaceuticals, and temperature-sensitive formulations. Premium positioning in these niche applications sustains margin pools despite lower throughput.
- Pressure Seal:Mechanical compression without thermal input serves paper-based and heat-sensitive substrates. Limited penetration outside specialty confectionery and paper-wrapped applications.
- Wrapping Film:Stretch and shrink film systems without discrete sealing cycles occupy distinct equipment categories adjacent to traditional overwrapping. Food bundling applications favor these for multi-pack aggregation.
Heat seal commands the largest installed base. Cold seal retains strategic importance in temperature-constrained pharmaceutical and confectionery segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Overwrapping machine manufacturing originated in post-war Europe, where Swiss and German engineering firms developed precision heat-seal systems for pharmaceutical and confectionery applications. This technical lineage continues to shape regional specialization patterns.
Germany
Pharmaceutical contract packaging services in Bavaria and North Rhine-Westphalia are replacing legacy overwrappers with EU MDR-compliant architectures featuring integrated serialization modules. ECHA REACH restrictions on phthalate plasticizers are forcing requalification of seal-bar temperature profiles for compliant film chemistries. The Stuttgart industrial cluster concentrates cosmetics manufacturers upgrading to bio-based polyolefin-compatible heat-seal platforms.
Japan
TAM Tokyo Automatic Machinery anchors domestic demand for ultra-compact vertical overwrappers designed around convenience-store portion-pack formats. METI energy efficiency guidelines favor equipment with reduced thermal mass in sealing stations. The Nagoya-Chubu manufacturing belt hosts precision machinery suppliers serving pharmaceutical and food processing OEMs.
India
Domestic FMCG brands in Maharashtra and Gujarat are localizing film-overwrapping capacity to reduce import dependency on Chinese packaging systems. BIS certification requirements for food-contact machinery are accelerating equipment standardization. The Pune-Ahmedabad industrial corridor concentrates semi-automatic vertical unit deployments as stepping-stone automation.
France
Cosmetics houses in Île-de-France and Provence-Alpes-Côte d'Azur are absorbing equipment premiums to maintain market access under evolving REACH substance restrictions. ANSM pharmaceutical traceability mandates are compressing replacement cycles for standalone overwrappers lacking native vision verification. The Lyon-Auvergne-Rhône-Alpes cluster specializes in cold-seal systems for temperature-sensitive formulations.
United States
Food manufacturers in the Midwest and Southeast are specifying modular multi-lane systems handling variable pack counts without changeover downtime. FDA cGMP guidelines for pharmaceutical applications mandate serialization-ready machine architectures with integrated reject stations. The Chicago-Wisconsin industrial belt concentrates bakery and confectionery producers seeking flexible automation.
Overwrapping Machines Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance depth and integrated serialization capability. The vendor base stratifies between pharmaceutical-grade specialists with native vision-verification architectures and food-sector generalists competing on throughput metrics. Three archetypes dominate: integrated packaging suite providers bundling overwrapping with cartoning and serialization; film-captive equipment makers stabilizing raw material access through supply partnerships; and compact-format specialists serving space-constrained urban production. Competitive moves concentrate on M&A for serialization technology access and strategic film supply partnerships insulating against polyolefin cost volatility.
Within the integrated suite tier, IMA Group exemplifies cross-selling strategies leveraging pharmaceutical serialization expertise into cosmetics compliance-ready packaging lines. Among European film-captive fabricators, ULMA Packaging anchors competitive positioning through supply partnerships stabilizing raw material access for bakery and confectionery clients. At the compact-format vector, TAM Tokyo Automatic Machinery occupies a niche where Japanese convenience-store portion-pack specifications override throughput metrics.
| Leading Market Players |
|---|
| IMA Group |
| Marchesini Group |
| FOCKE & CO |
| ULMA Packaging |
| CAM Packaging |
| Sollas Holland BV |
| ProMach |
| Uhlmann Packaging |
| TAM Tokyo Automatic Machinery |
| Others |
Value Network & Pricing Analysis
Heat-seal platform upgrades across European cosmetics manufacturers are compressing equipment cost structures while concentrating procurement power among film-captive OEMs with captive polyolefin supply partnerships. This technology transition simultaneously reduces buyer switching costs and locks in long-term material economics for vertically integrated suppliers.
Pricing Analysis
Outcome-based performance contracts now dominate equipment procurement across German bakery and confectionery chains, unbundling maintenance and film supply from capital acquisition. Price differentiation rests on serialization certification grade and after-sales service bundling. Cost compression in standard-configuration segments is intensifying because Indian domestic FMCG brands are localizing semi-automatic vertical units to bypass imported Chinese system premiums. Contract packaging services exhibit lowest price sensitivity due to EU MDR compliance mandates, while emerging market entry-level buyers drive hardest bargain on upfront capex.
Supply Chain Analysis
BIS certification requirements for food-contact machinery and India's PLI scheme for domestic manufacturing are reshaping sourcing patterns away from Chinese integrated packaging lines toward localized assembly. Polyolefin and PVC film production concentrates in Germany, Japan, and India. Equipment fabrication draws from precision machining clusters in Bavaria, Nagoya-Chubu, and Stuttgart. Single-source vulnerability runs through European petrochemical suppliers for specialized sealing films. Distribution runs through regional equipment distributors with captive service networks and direct OEM relationships for pharmaceutical-grade systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on modular multi-lane system premiums and serialization-ready architecture upgrades that command compliance-driven pricing power. Bio-based polyolefin film compatibility investments are shifting cost curves toward premium-tier equipment with extended producer responsibility tailwinds.
For Market Incumbents: Deepen serialization technology integration to defend against integrated packaging suite competitors cross-selling cartoning lines. Expand captive film supply partnerships in India to offset REACH plasticizer restriction compliance costs passed through European supply chains. Prioritize EU MDR-native vision verification architectures as the primary defensive moat against standalone equipment commoditization.
For New Entrants and Emerging Players: Capture ultra-compact vertical overwrapper demand in Japanese convenience-store portion-pack formats where TAM Tokyo Automatic Machinery's niche dominance leaves price elasticity. Target Indian semi-automatic vertical configurations as the fastest-penetrating entry point where BIS certification creates localization barriers for Chinese imports. Lead with floor-space-optimized designs and stepping-stone automation value propositions.
For Investors and Strategic Acquirers: Valuations sit cheapest among food-sector generalists lacking pharmaceutical serialization capability but holding installed base relationships for upgrade conversion. Long-term viability favors equipment makers with backward integration into film supply or native compliance architectures. Watch EU Green Deal mono-material recycling quota implementation as the inflection signal for bio-based polyolefin-compatible platform demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Technology Integration | EU MDR and FDA cGMP mandates compress replacement cycles for vision-verification-ready architectures. |
| Captive Film Supply Partnerships | ULMA Packaging's polyolefin partnerships stabilize raw material access for European bakery clients against petrochemical volatility. |
| Modular Multi-Lane System Development | Food manufacturers in the US Midwest specify configurable pack-count handling without changeover downtime. |
| Ultra-Compact Vertical Design Specialization | TAM Tokyo Automatic Machinery dominates Japanese convenience-store formats where METI energy guidelines favor reduced thermal mass. |
| Extended Producer Responsibility Compliance | EU Green Deal recycling quotas favor equipment compatible with mono-material and chemically recyclable substrates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical contract packaging executives, cosmetics manufacturing engineers, food sector plant managers, and aftermarket service heads with secondary validation. Bottom-up equipment shipment data triangulated against top-down end-use demand modeling. Secondary sources included FDA cGMP guidance documents, ECHA REACH substance restriction databases, BIS machinery certification records, METI energy efficiency standards, and customs trade flows for packaging equipment imports.
Segment-weighting approaches distributed value and volume across product type, end user, material, and technology dimensions over the projection horizon. CAGRs derived from equipment replacement cycle analysis, regulatory mandate timelines, and localization trend trajectories. Forecast inputs incorporated EU MDR serialization compliance deadlines, Indian PLI scheme manufacturing incentives, and REACH plasticizer restriction phase-in schedules.
Regulatory enforcement delays, film raw material supply disruptions, and substitution acceleration by flow-wrapping systems are the dominant revision risks to modeled outputs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Pouch Sealing Machine Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Pre-Made Pouch Packaging Machines Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Automatic Filling Machine Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Lipstick Molding Machines Market
Packaging Machinery
Medicine Decoction and Packing Machines Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Global Tissue Paper Converting Machines Market
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Induction Sealing Machine Market
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Cutter-Box Packaging Market