
 Oral Dosage Powder Packaging Machines Market | 2026-2036
Oral Dosage Powder Packaging Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Dosage Powder Packaging Machines Market Analytics
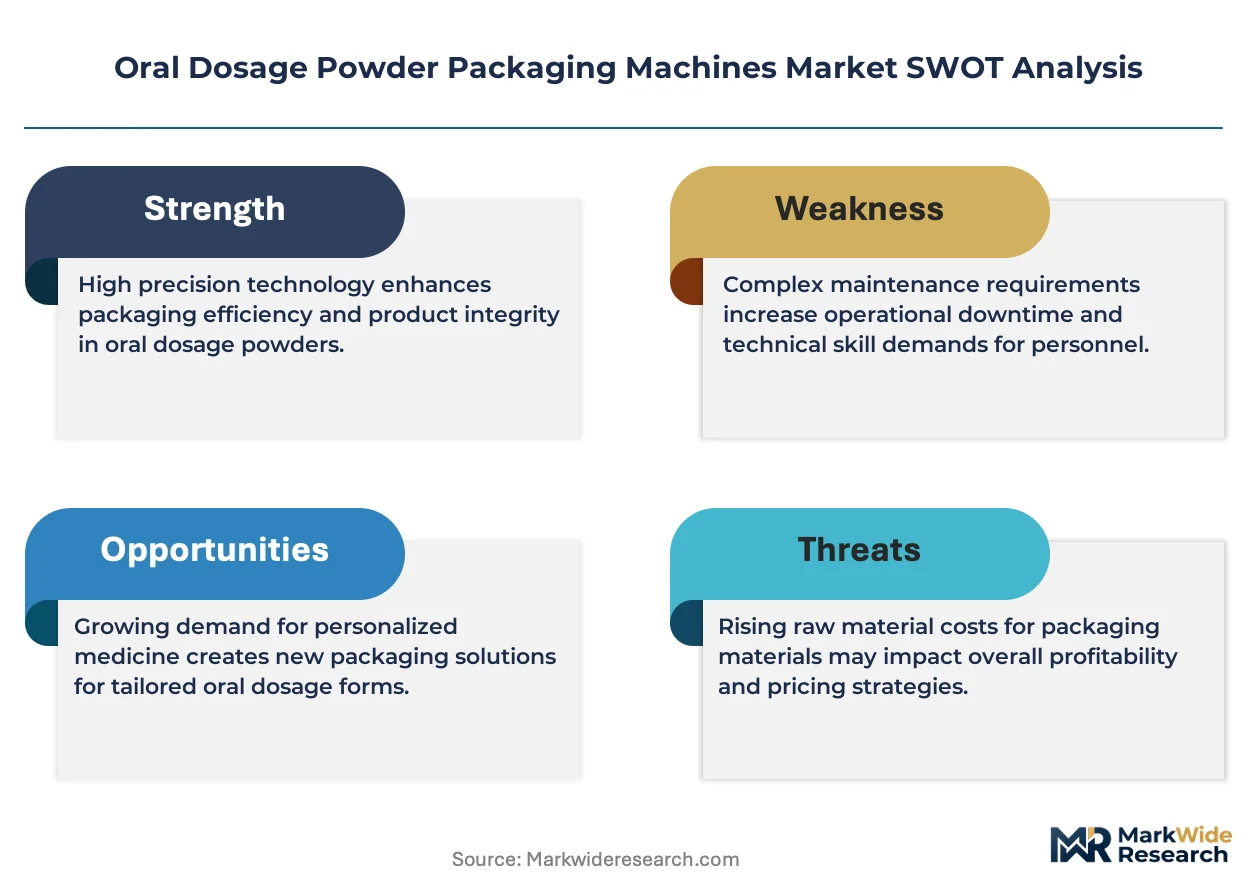
Integration of digital twin platforms with servo-driven filling systems is tilting capital allocation toward predictive maintenance architectures. IMA Group leverages its Italian manufacturing base to anchor high-speed vial filling lines for European pharmaceutical exporters. Syntegon Technology competes through modular machine platforms that reduce changeover times for multi-product facilities. ACG Worldwide dominates South Asian markets with localized service networks and region-specific cGMP configurations.
Oral dosage powder packaging machines are precision-engineered systems that meter, fill, and seal dry pharmaceutical powders into primary containers at throughputs ranging from 60 to 600 units per minute, with fill-weight accuracy typically held within plus or minus one percent to prevent therapeutic underdosing or overdosing. These machines serve commercial manufacturing by ensuring batch uniformity, minimizing operator exposure to potent compounds, and generating electronic records for regulatory traceability. Sachet machines lead unit volume in emerging markets where single-dose antibiotic and rehydration therapy formats prevail, while bottle fillers command premium pricing in North American and European nutraceutical channels where child-resistant closure integration adds complexity. Automatic technology segments capture the majority of replacement demand as labor costs rise and FDA data integrity requirements tighten audit trails around manual interventions.
FDA cGMP regulations and EU GMP Annex 1 revisions on containment and cross-contamination shape machine design requirements, compelling vendors to engineer isolator-integrated filling lines and continuous particulate monitoring systems. CDSCO in India and China's NMPA impose country-specific documentation and validation protocols that extend commissioning timelines but create barriers against uncertified imports. Manufacturers must monitor evolving serialization mandates from the EU Falsified Medicines Directive and corresponding traceability rules in Brazil's ANVISA framework to align R&D roadmaps with compliance-driven replacement cycles.
Market Dynamics
Servo-driven filling architectures are displacing mechanical cam systems as pharmaceutical manufacturers confront FDA data integrity mandates and rising labor costs across high-volume production environments.
Growth Catalysts
- EU GMP Annex 1 containment revisions:European pharmaceutical exporters are retrofitting lines with isolator-integrated powder handling systems to satisfy upgraded cross-contamination protocols, accelerating replacement cycles for legacy open-containment equipment.
- Contract packager consolidation:Third-party manufacturing organizations in Germany and Switzerland are consolidating procurement around single-source machine platforms to standardize validation documentation and reduce multi-site audit complexity.
- Predictive maintenance software:Digital twin platforms integrated with servo motor diagnostics are reducing unplanned downtime in continuous manufacturing environments, creating pull-through demand for connected machine architectures.
Market Restraints
- Stainless steel alloy volatility:Grade 316L pharmaceutical-grade steel price fluctuations are compressing margins for European machine builders who cannot fully pass input cost increases to locked contract customers.
- Validation documentation burden:India's CDSCO and China's NMPA impose non-harmonized qualification protocols that extend commissioning timelines by four to eight months, freezing capital deployment and delaying revenue recognition.
- Pre-filled syringe substitution:Liquid dosage form conversion for pediatric and geriatric populations is eroding addressable demand for single-dose powder sachets in certain therapeutic categories.
Strategic Opportunities
- Brazilian ANVISA serialization mandates:Track-and-trace equipment retrofits for existing powder packaging lines represent a captive installed base opportunity as compliance deadlines approach for secondary packaging integration.
- Continuous manufacturing convergence:Direct compression tableting lines feeding into integrated bottle filling systems are creating demand for real-time release testing equipment that pharmaceutical OEMs currently under-supply.
- Modular platform architectures:Syntegon-style quick-changeover systems enable multi-product facilities to switch between antibiotic powders and nutraceutical formulations within two hours, opening contract manufacturing versatility premiums.
Industry Challenges
- Mechatronics technician scarcity:Servo system calibration and PLC programming expertise shortages in India's pharmaceutical manufacturing clusters are extending installation timelines and inflating commissioning costs for European vendors.
- Legacy SCADA integration friction:Brownfield facilities running Allen-Bradley or Siemens S7-300 architectures face protocol incompatibility when connecting new OPC-UA-enabled filling machines to existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Dosage Powder Packaging Machines Market |
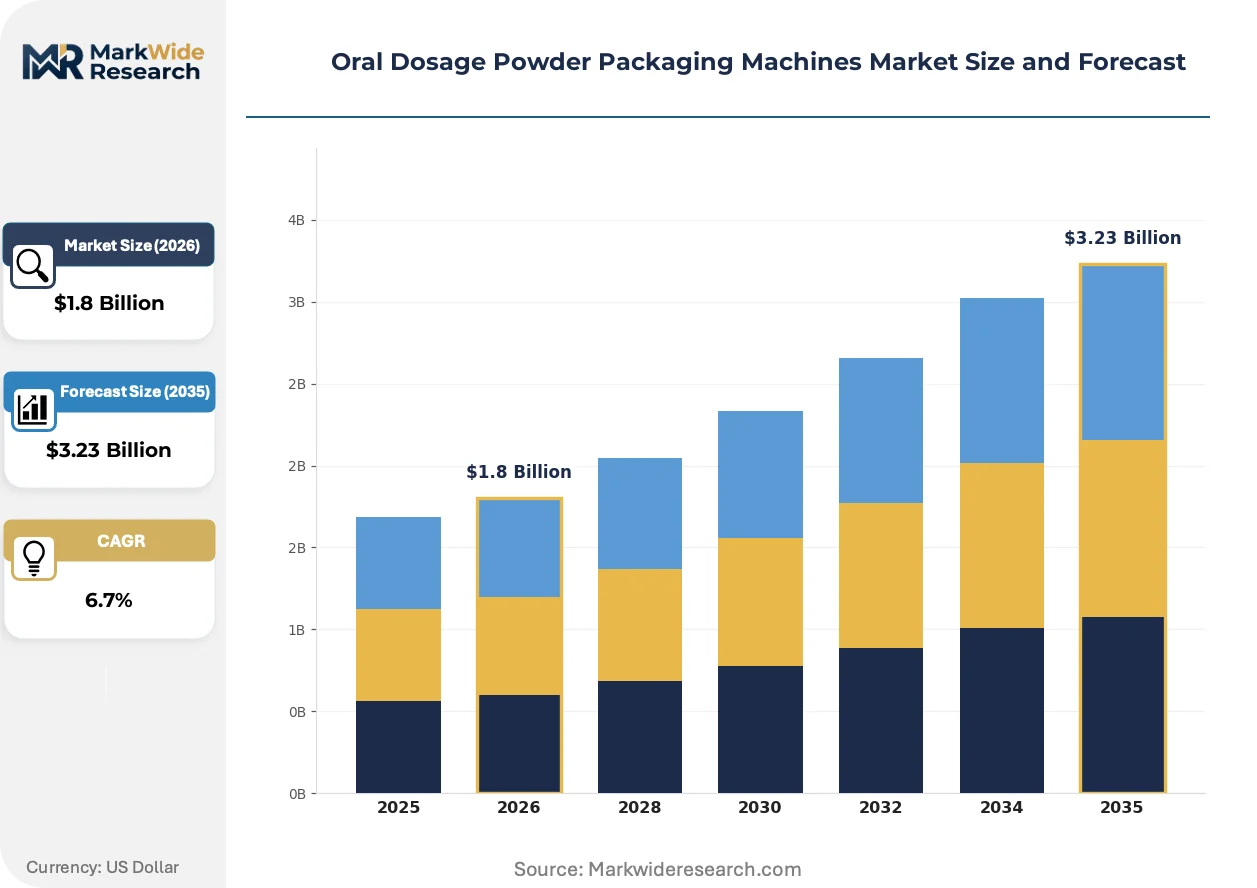
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vial Fillers, Sachet Machines, Bottle Fillers, Pouch Fillers End User: Pharmaceutical Manufacturers, Nutraceutical Companies, Contract Packagers, Food Processors Technology: Automatic, Semi-Automatic, Manual, Digital Packaging Type: Plastic Bags, Cartons, Glass Bottles, Blister Packaging |
| Companies Covered | IMA Group, Marchesini Group, Uhlmann Group, Syntegon Technology, Romaco Group, MG2, Harro Höfliger, Körber Medipak Systems, ACG Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Dosage Powder Packaging Machines Market Evolving Landscape
Active pharmaceutical ingredient potency escalation and occupational exposure band tightening are forcing simultaneous upgrades to containment engineering and data capture architectures across oral dosage powder operations.
Electromagnetic resonant cavity filling technology is hybridizing gravimetric and volumetric measurement principles to achieve sub-milligram accuracy for high-potency hormone therapies. Specialty contract manufacturers in Switzerland and Denmark are piloting these systems for cytotoxic powder handling. The technology is hybridizing competitive positioning by enabling European vendors to command premium pricing against Asian competitors limited to mechanical filling architectures.
REACH chemical registration requirements for lubricants and cleaning agents used in powder contact zones are compelling reformulation of standard machine maintenance protocols. European pharmaceutical manufacturers must now document substance volumes and exposure scenarios for downstream regulatory filings. Bottle filling lines with integrated clean-in-place systems are capturing preference as they reduce manual solvent handling and associated documentation burden.
Pharmaceutical procurement departments are unbundling after-sales service contracts from initial capital purchases, forcing machine vendors to compete on transparent hourly service rates rather than bundled maintenance premiums. Large multi-site operators in Germany and the Netherlands are centralizing spare parts inventory management and demanding predictive analytics dashboards as contract deliverables. This shift is most visible among CDMOs serving North American nutraceutical brands where total cost of ownership calculations dominate vendor selection criteria.
Oral Dosage Powder Packaging Machines Market Segmentation
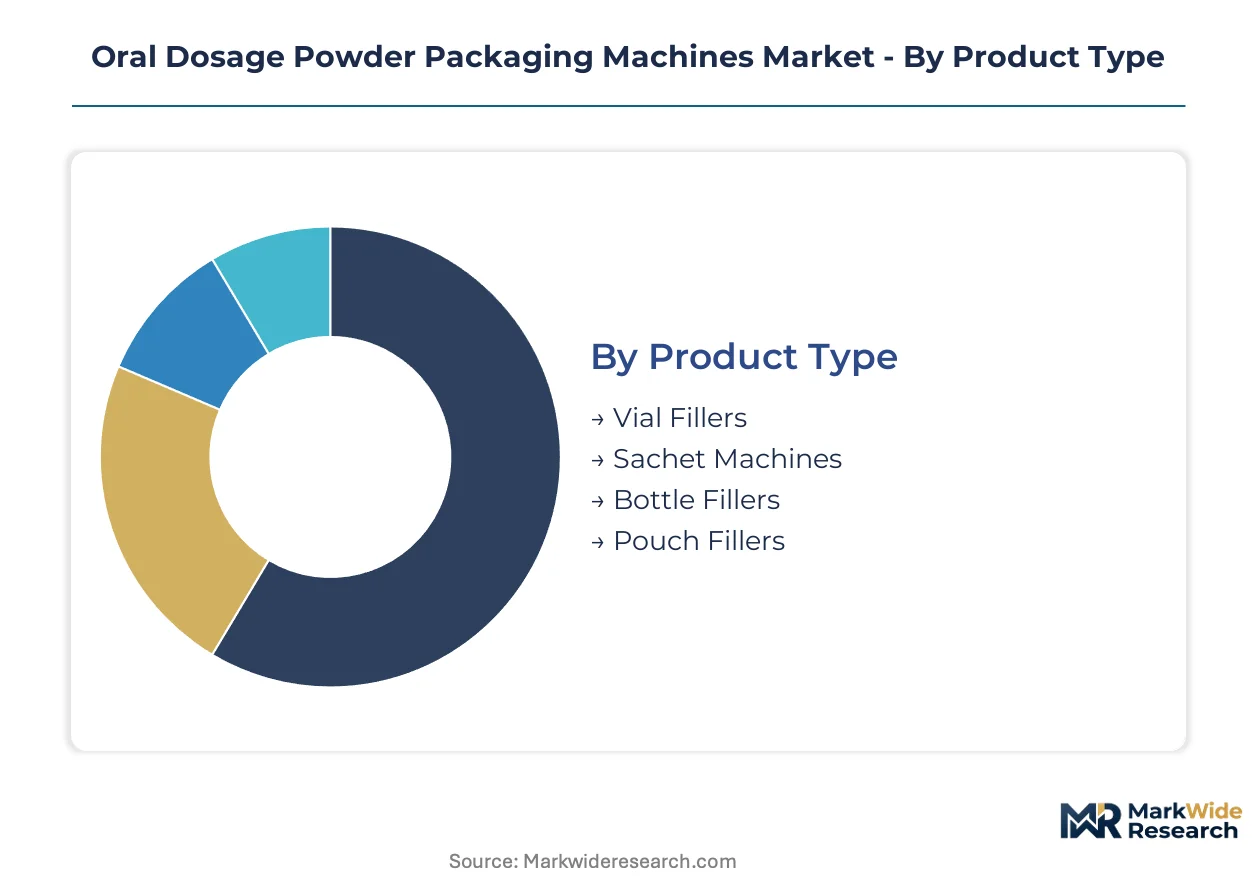
Machine configuration varies sharply across therapeutic formats and containment requirements. Vendors engineer distinct architectures for single-dose sachets versus multi-dose bottles, each demanding specialized metering systems and closure integration.
Product Type:
Vial fillers, sachet machines, bottle fillers, and pouch fillers serve divergent use cases spanning hospital pharmacies to mass-market nutraceutical distribution.
- Vial Fillers:Precision-engineered systems handle sterile powder aseptic processing with isolator integration for high-potency compounds. Swiss and Danish contract manufacturers deploy these for cytotoxic hormone therapies under EMA containment guidelines.
- Sachet Machines:High-speed rotary systems seal single-dose antibiotic and oral rehydration powders in laminated foil. Indian pharmaceutical clusters drive volume as CDSCO tightens powder containment standards for domestic and export markets.
- Bottle Fillers:Auger-based systems integrate child-resistant closure mechanisms for North American nutraceutical channels.
- Pouch Fillers:Flexible format machines accommodate variable dose weights for clinical trial materials and veterinary applications.
Established volume favors sachet machines; emerging adoption favors vial fillers as containment requirements escalate.
End User:
Customer archetypes span integrated pharmaceutical giants to specialized third-party packagers, each with distinct validation protocols and throughput requirements.
- Pharmaceutical Manufacturers:In-house production lines demand FDA 21 CFR Part 11-compliant data integrity architectures with electronic batch records. German and Swiss exporters prioritize isolator-integrated systems to satisfy EU GMP Annex 1 revisions.
- Contract Packagers:Multi-product facilities require rapid changeover capabilities and standardized validation documentation across client portfolios. German CDMOs consolidate procurement around single-source platforms to reduce audit complexity.
- Nutraceutical Companies:Probiotic and protein powder operations emphasize clean-in-place systems and allergen containment protocols.
- Food Processors:Infant formula and fortified beverage applications drive demand for hygienic design standards with USDA dairy-grade certifications.
Pharmaceutical manufacturers command premium pricing tiers; contract packagers drive modular platform innovation.
Technology:
Automation intensity correlates directly with labor cost structures and regulatory data integrity mandates across production environments.
- Automatic:Servo-driven architectures with PLC-controlled auger speeds and real-time fill-weight feedback dominate high-volume commercial manufacturing. These systems capture replacement demand as FDA audit trails tighten around manual interventions.
- Semi-Automatic:Operator-assisted configurations persist in emerging market facilities and clinical trial material production where batch sizes remain variable.
- Manual:Benchtop units serve compounding pharmacies and research institutions with low throughput requirements.
- Digital:OPC-UA-enabled machines with integrated digital twin platforms support predictive maintenance and remote diagnostics.
Automatic systems anchor replacement cycles; digital architectures gain share fastest among multi-site operators.
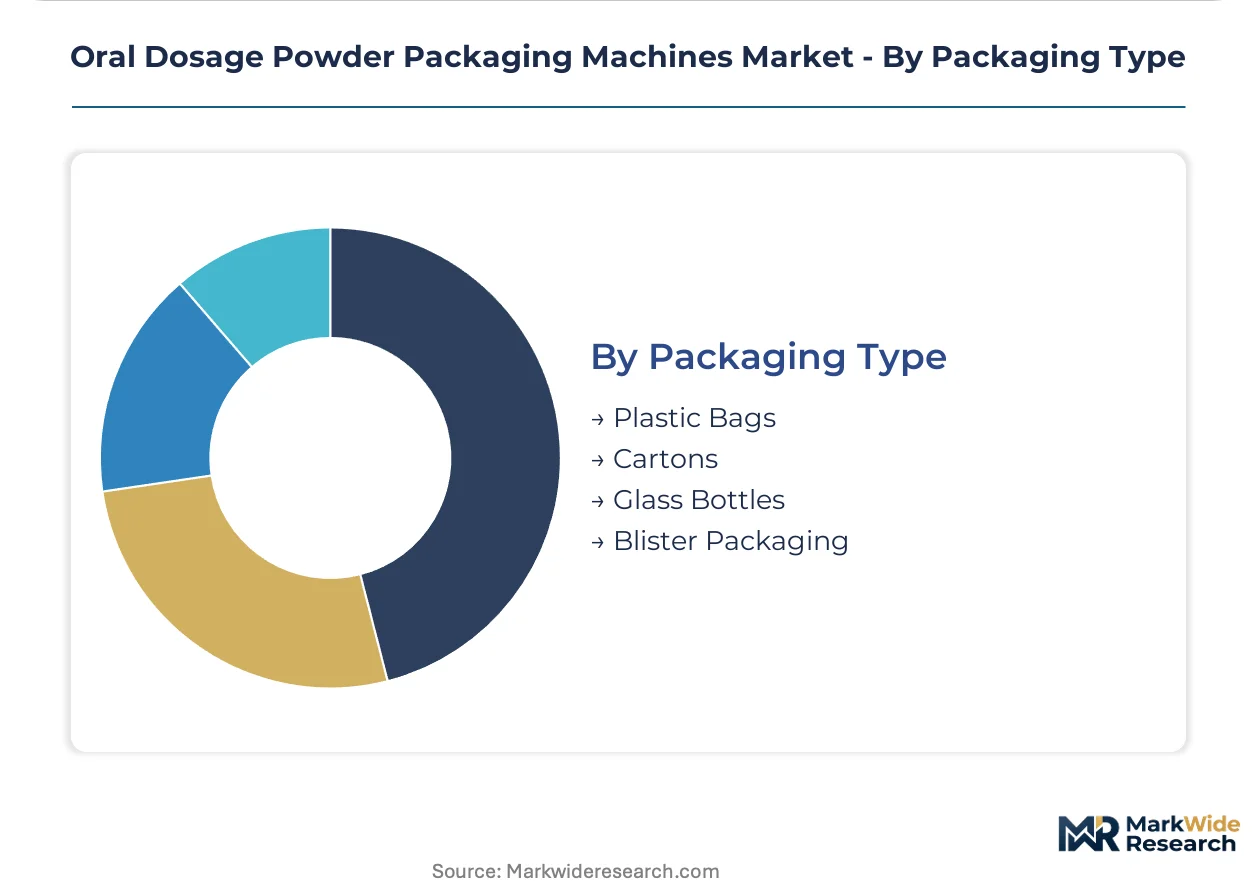
Packaging Type:
Primary container selection hinges on moisture sensitivity, child safety requirements, and distribution channel durability standards.
- Plastic Bags:Multi-layer laminates with aluminum foil barriers protect hygroscopic antibiotic powders in tropical climates. Sachet formats concentrate in Indian and Brazilian markets where single-dose dispensing improves medication adherence.
- Glass Bottles:Amber and clear borosilicate containers with desiccant closures serve premium nutraceutical and probiotic segments requiring shelf-life extension.
- Cartons:Secondary packaging integration with serialization compliance for EU Falsified Medicines Directive tracking requirements.
- Blister Packaging:Unit-dose formats for clinical trials and hospital formulary compliance with tamper-evident features.
Plastic bags dominate unit economics; glass bottles sustain premium positioning in North American and European channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German machine builders export high-speed filling lines to Swiss and Danish contract manufacturers serving North American nutraceutical brands. Indian pharmaceutical clusters drive sachet machine demand as CDSCO tightens domestic containment standards for antibiotic powder exports.
Germany
Contract packagers in Baden-Württemberg and North Rhine-Westphalia consolidate procurement around single-source platforms to standardize validation documentation. EU GMP Annex 1 revisions on cross-contamination compel retrofit investments in isolator-integrated powder handling systems. The Stuttgart industrial corridor anchors high-speed vial filling production for European pharmaceutical exporters.
India
Pharmaceutical manufacturers in Maharashtra and Gujarat upgrade equipment as CDSCO imposes stricter powder containment standards for domestic and export markets. The country's national pharmaceutical regulator extends commissioning timelines through non-harmonized qualification protocols. Ahmedabad and Mumbai pharmaceutical clusters drive sachet machine volume for single-dose antibiotic and oral rehydration therapy formats.
Switzerland
Specialty contract manufacturers pilot electromagnetic resonant cavity filling systems for cytotoxic hormone therapies under EMA containment guidelines. Swissmedic maintains stringent occupational exposure band classifications that force containment engineering upgrades. Basel and Zurich pharmaceutical manufacturing zones command premium pricing for high-potency powder handling equipment.
United States
Nutraceutical brands in New Jersey and California demand bottle fillers with child-resistant closure integration for premium distribution channels. FDA 21 CFR Part 11 data integrity mandates tighten audit trails around manual interventions in commercial manufacturing. The New York Metro and Pacific Northwest corridors drive replacement demand for servo-driven automatic systems.
Brazil
Pharmaceutical manufacturers prepare for ANVISA serialization mandates requiring track-and-trace equipment retrofits on existing powder packaging lines. The country's national pharmaceutical regulator imposes compliance deadlines for secondary packaging integration. São Paulo and Rio de Janeiro industrial zones concentrate contract manufacturing capacity serving Latin American export markets.
Oral Dosage Powder Packaging Machines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: Italian and German engineering houses with pharmaceutical heritage, Indian and Chinese fabricators with localized service networks, and modular platform specialists with rapid changeover capabilities. Dominant competitive moves include M&A consolidation among European engineering groups and capacity expansion into Southeast Asian pharmaceutical manufacturing corridors.
Among Italian engineering houses, IMA Group and Marchesini Group exemplify the precision-engineered vial filling tradition anchored in Bologna's pharmaceutical machinery cluster. Syntegon Technology occupies a position within the modular platform tier, representing quick-changeover capabilities that reduce multi-product facility downtime. ACG Worldwide anchors the localized service network archetype for South Asian markets with region-specific cGMP configurations.
| Leading Market Players |
|---|
| IMA Group |
| Marchesini Group |
| Uhlmann Group |
| Syntegon Technology |
| Romaco Group |
| MG2 |
| Harro Höfliger |
| Körber Medipak Systems |
| ACG Worldwide |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Antwerp pharmaceutical logistics corridor channels Grade 316L stainless steel and servo motor assemblies from German fabricators to Indian pharmaceutical clusters, with freight cost volatility amplifying the technology-generation pricing gap between isolator-integrated systems and mechanical legacy equipment while compressing margins for European builders locked into long-term service contracts.
Pricing Analysis
Technology-generation pricing gaps separate three distinct tiers: next-generation electromagnetic resonant cavity fillers command premium positioning against current servo-driven architectures, while mechanical cam systems face accelerated price erosion. Three-tier pricing structure across premium isolator-integrated, standard servo-driven, and economy mechanical levels reflects FDA 21 CFR Part 11 certification tiers and geographic delivery cost differentials. Pricing pressure stems from stainless steel alloy volatility that European builders cannot fully pass to contract packagers. Contract manufacturing organizations in Germany exhibit lowest price sensitivity due to total cost of ownership calculations, while emerging market pharmaceutical manufacturers in India demonstrate highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Contract manufacturing concentration centers on German CDMOs in Baden-Württemberg and Swiss specialty packagers in Basel, with Indian pharmaceutical clusters in Ahmedabad and Mumbai anchoring secondary assembly capacity. Raw material dependencies draw from Italian servo motor suppliers, Chinese PLC component fabricators, and domestic Indian stainless steel processors. Supply chain risk hinges on single-source vulnerability for electromagnetic resonant cavity subassemblies currently manufactured by limited European specialists. Distribution runs through direct OEM sales to integrated pharmaceutical manufacturers and bundled service contracts to multi-site contract packagers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated contract packagers in Germany and Switzerland, with multi-site procurement standardization reducing vendor count and intensifying price competition among machine builders.
For Market Incumbents: Pre-empt modular platform replication by accelerating OPC-UA digital twin integration and securing exclusive electromagnetic resonant cavity technology licensing from Swiss pilot facilities. Defend against Asian competitors with localized service networks by embedding predictive maintenance software as standard contract deliverables rather than premium add-ons. Prioritize backward integration into Grade 316L stainless steel processing to buffer margin compression from alloy price volatility. For New Entrants and Emerging Players: Build out Brazilian ANVISA serialization retrofit capabilities as the most penetrable white-space opportunity, targeting existing powder packaging line installed bases facing compliance deadlines. Target Indian pharmaceutical clusters with region-specific cGMP documentation packages that accelerate CDSCO commissioning timelines relative to European competitors. Pursue partnership-based go-to-market models with established aftermarket service providers to bypass direct sales infrastructure requirements. For Investors and Strategic Acquirers: Modular platform specialists with rapid changeover capabilities represent the most attractive acquisition archetype given contract packager consolidation trends. Long-term viability over the coming decade hinges on digital twin software recurring revenue streams displacing bundled hardware-service pricing models. Monitor servo motor diagnostic patent filings as the critical inflection signal for predictive maintenance technology maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Integrated Line Retrofit | EU GMP Annex 1 revisions compel European pharmaceutical exporters to upgrade containment engineering. |
| Digital Twin Platform Development | FDA data integrity mandates create pull-through demand for predictive maintenance architectures. |
| Regional Service Network Expansion | CDSCO qualification protocols favor vendors with localized commissioning expertise in India. |
| Electromagnetic Resonant Cavity Licensing | Swiss and Danish contract manufacturers pilot sub-milligram accuracy systems for cytotoxic therapies. |
| Serialization Equipment Integration | Brazilian ANVISA mandates require track-and-trace retrofits on existing powder packaging lines. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical manufacturing engineers, contract packaging procurement directors, regulatory affairs specialists, and aftermarket service technicians, and refined through secondary validation against FDA 21 CFR Part 11 guidance documents, EU GMP Annex 1 revision drafts, CDSCO equipment qualification circulars, and customs trade data for pharmaceutical machinery imports. Bottom-up demand modeling across machine configurations and top-down supply-side capacity assessments were triangulated to converge on volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end user archetype, automation technology tier, and primary packaging format. CAGRs were derived from regression analysis of replacement cycle dynamics and regulatory compliance-driven upgrade timelines, incorporating pharmaceutical capital expenditure survey data and equipment vendor order backlog disclosures as industry-specific forecast inputs.
Stress conditions across stainless steel alloy price volatility, CDSCO commissioning timeline extensions, and pre-filled syringe substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and contract packager consolidation trajectories. Quarterly review of electromagnetic resonant cavity technology commercialization rates and ANVISA serialization compliance deadlines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Powder Packing Machine Market
Packaging Machinery
Medicine Decoction and Packing Machines Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Liquid Pouch Filling and Sealing Machine Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Metal Banding Machine Market
Packaging Machinery
Pallet Drum Filler Capper Market
Packaging Machinery
Bottle Filling Machine Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Pallet Stretch Wrapping Machines Market
Packaging Machinery
Kitchen/ Toilet Roll Converting Machines Market