
 Automatic Auger Fillers Market | 2026-2036
Automatic Auger Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Auger Fillers Market Analytics
Stainless steel is consolidating its position as the dominant material for auger filler contact surfaces, displacing coated carbon steel in pharmaceutical and food-grade installations. All-Fill Inc. leverages servo-driven architecture to sustain precision in high-variability powder applications. GEA Group Aktiengesellschaft anchors European supply through integrated processing and packaging lines for dairy and nutritional powders. Spee-Dee Packaging Machinery, Inc. differentiates via proprietary tooling systems that reduce changeover intervals in contract packaging environments.
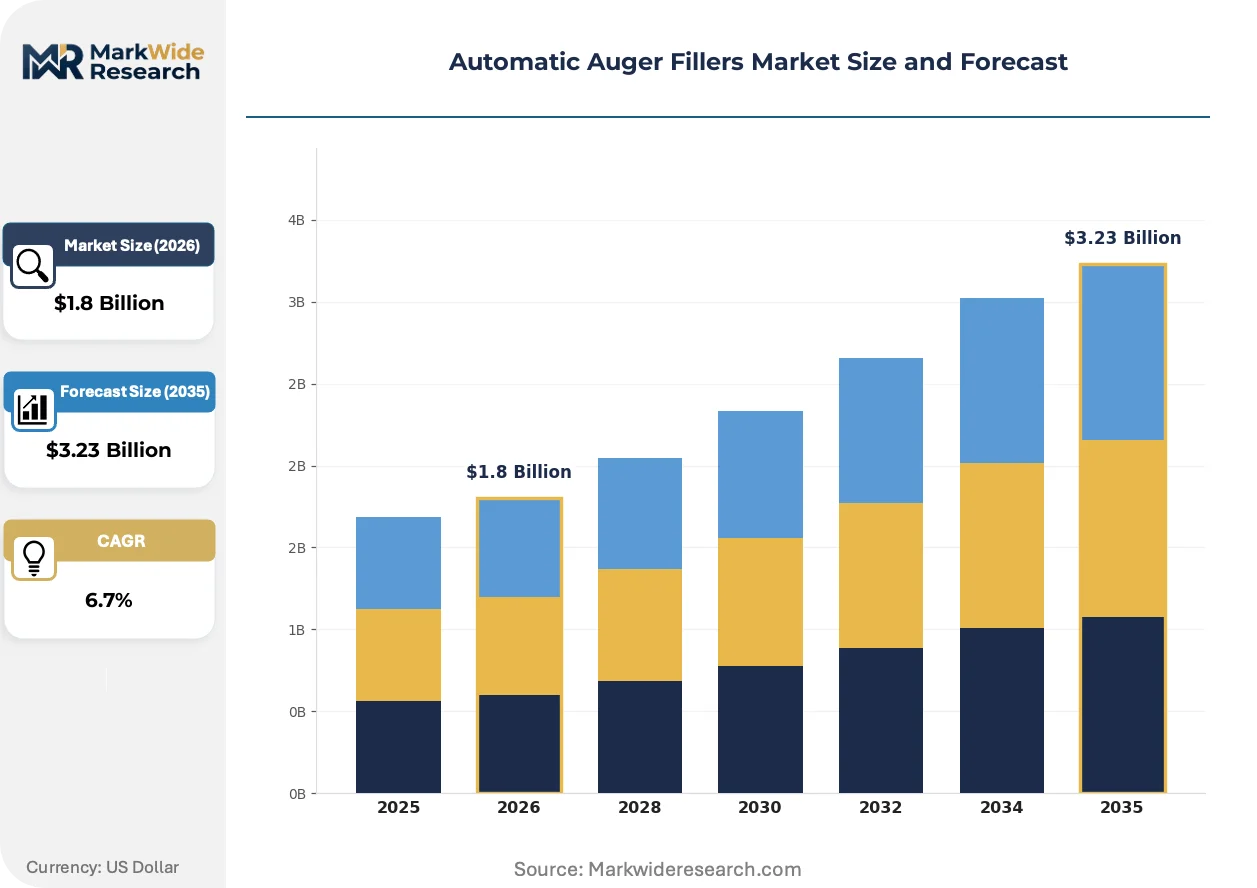
An automatic auger filler is a volumetric dispensing machine that uses a rotating helical screw to transfer measured quantities of dry, free-flowing or non-free-flowing powders, granules, and pastes into rigid or flexible containers with typical accuracies of plus or minus one to two percent by weight. The equipment serves primary functions across filling, dosing, and portioning operations in continuous or intermittent motion packaging lines. Fully automatic configurations command the largest installed base among product types, though servo drive technology generates disproportionate margin pools due to programmable fill profiles and reduced mechanical wear. Food and beverage applications retain the broadest volume footprint, while pharmaceutical end users drive specification intensity through validation documentation and clean-in-place requirements.
FDA cGMP guidelines and EU MDR traceability mandates shape equipment qualification protocols, compelling manufacturers to document material certificates of analysis and calibration records across installation and operational qualification phases. OSHA dust exposure limits and ATEX directives for explosive powder atmospheres further constrain design choices for chemical and food processing environments. Stakeholders must weigh total cost of ownership against throughput flexibility when selecting between pneumatic simplicity and servo programmability for multi-SKU operations.
Market Dynamics
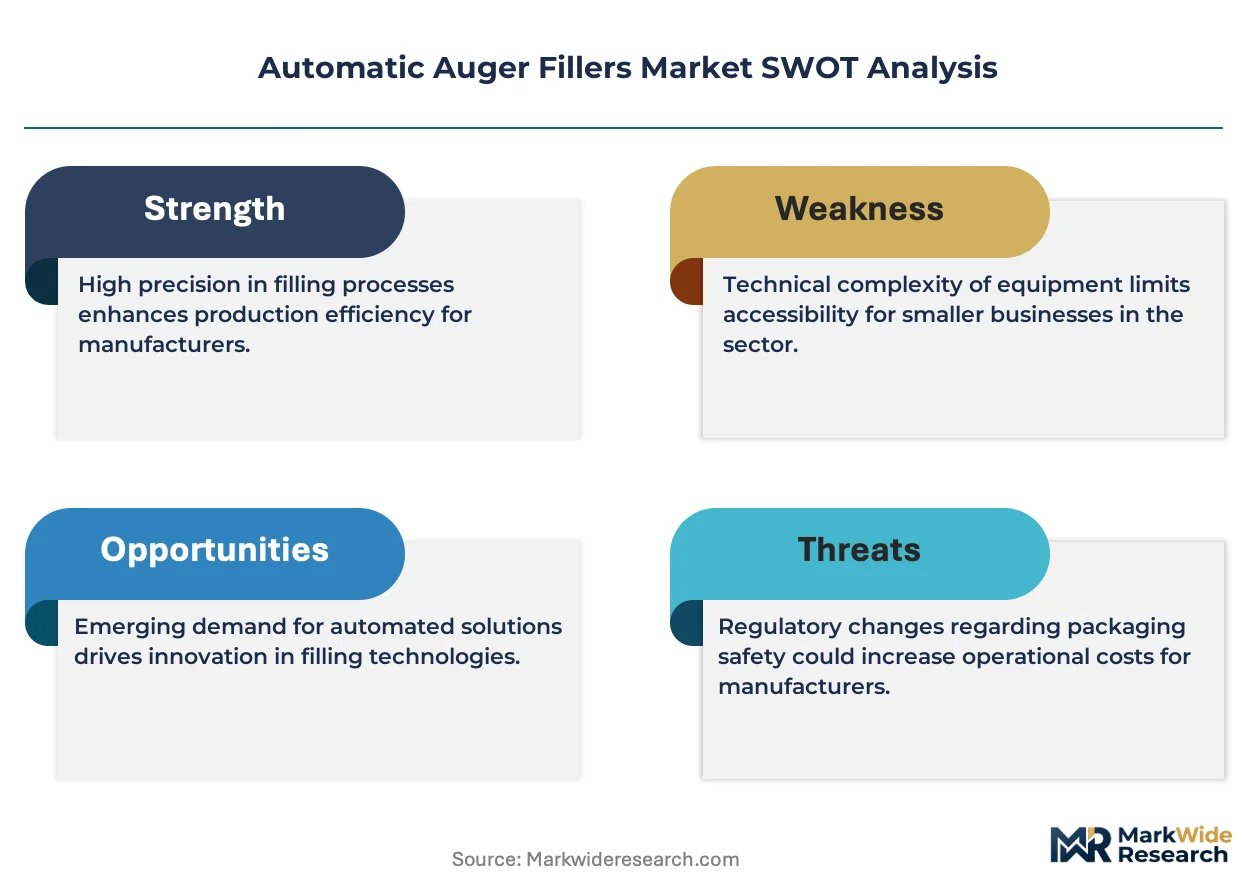
Pharmaceutical serialization mandates and EU MDR traceability requirements are compressing equipment replacement cycles and forcing validation documentation upgrades across installed bases. This regulatory pressure is the dominant structural force reshaping specification intensity and supplier selection criteria.
Growth Catalysts
- FDA cGMP validation protocols:Powder-based drug manufacturers must demonstrate installation qualification and operational qualification documentation, driving replacement of legacy pneumatic fillers with servo-driven systems that generate auditable fill profiles.
- Contract packaging concentration in Germany:Hub operations serving both domestic chemical producers and EU food processors create dense demand clusters for multi-SKU flexible equipment with rapid changeover capabilities.
- Stainless steel material transition:Displacement of coated carbon steel in pharmaceutical and food-grade installations is expanding addressable equipment value per unit through higher-specification contact surface requirements.
Market Restraints
- Servo motor and drive component concentration:Supply bottlenecks in precision motion control hardware from Japanese and German component suppliers extend equipment lead times and inflate input costs for domestic manufacturers.
- ATEX compliance burden:Explosive atmosphere certification for chemical and food powder processing adds engineering overhead and limits supplier participation in hazardous environment segments.
- Secondary packaging line integration:Auger fillers must interface with legacy cartoning and case-packing systems, constraining architectural flexibility and extending commissioning timelines.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO compliance requirements and PLI scheme incentives for active pharmaceutical ingredient production are creating demand for validated powder dosing equipment in contract manufacturing organizations.
- Clean-in-place automation convergence:Integration of CIP systems with servo-driven fill heads reduces manual intervention and downtime, commanding premium positioning in dairy and nutritional powder applications.
- Direct-to-consumer nutraceutical channels:E-commerce fulfillment models require portion-controlled single-serve packaging formats, expanding demand for precision micro-dosing auger configurations.
Industry Challenges
- Validation engineer scarcity:Pharmaceutical equipment qualification requires specialists capable of executing IQ/OQ/PQ protocols, and this talent pool concentrates with incumbent suppliers and large contract manufacturers.
- Legacy control system integration:Brownfield packaging lines operate on proprietary PLC architectures, forcing custom gateway development for Industry 4.0 data connectivity and remote diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Auger Fillers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Alone, Semi-Automatic, Fully Automatic, Custom Built Application: Food & Beverage, Pharmaceuticals, Chemicals, Cosmetics End User: Manufacturers, Packaging Companies, Food Processors, Laboratories Technology: Servo Drive, Pneumatic, Mechanical, Electronic |
| Companies Covered | Accutek Packaging Equipment Company, Inc., All-Fill Inc., Busch Machinery, Inc., PER-FIL Industries, AMS Filling Systems, Inc., Spee-Dee Packaging Machinery, Inc., Paxiom Group Inc., GEA Group Aktiengesellschaft, IMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Auger Fillers Market Evolving Landscape
Servo-driven architecture is displacing pneumatic actuation as the default motion control paradigm, enabling programmable fill profiles and predictive maintenance capabilities that reshape competitive differentiation.
Brushless servo motor technology with integrated encoders is electrifying precision powder dosing by eliminating mechanical wear points in the auger drive train. Pharmaceutical manufacturers in Germany and Switzerland are specifying these systems for high-value active pharmaceutical ingredients where batch-to-batch consistency determines regulatory approval. This electrification is compressing maintenance intervals and enabling real-time torque feedback that detects powder flow anomalies before fill weight deviation occurs.
EU MDR traceability mandates now require unique device identification for powder-based drug delivery systems, extending documentation obligations to primary packaging equipment. Equipment suppliers must provide material certificates of analysis and calibration records across installation and operational qualification phases. Pharmaceutical end users in the European Union are responding by consolidating supplier relationships with vendors capable of delivering validated documentation packages rather than sourcing on equipment cost alone.
Contract packaging buyers are unbundling after-sales service from capital equipment procurement, selecting specialized field service organizations for preventive maintenance while negotiating stripped-down capital quotes. This disintermediation is visible in German chemical and food processing hubs where multi-site operators prefer standardized service contracts across heterogeneous equipment fleets over captive manufacturer service agreements. The shift compresses supplier margin pools and elevates spare parts logistics capabilities as a competitive variable.
Automatic Auger Fillers Market Segmentation
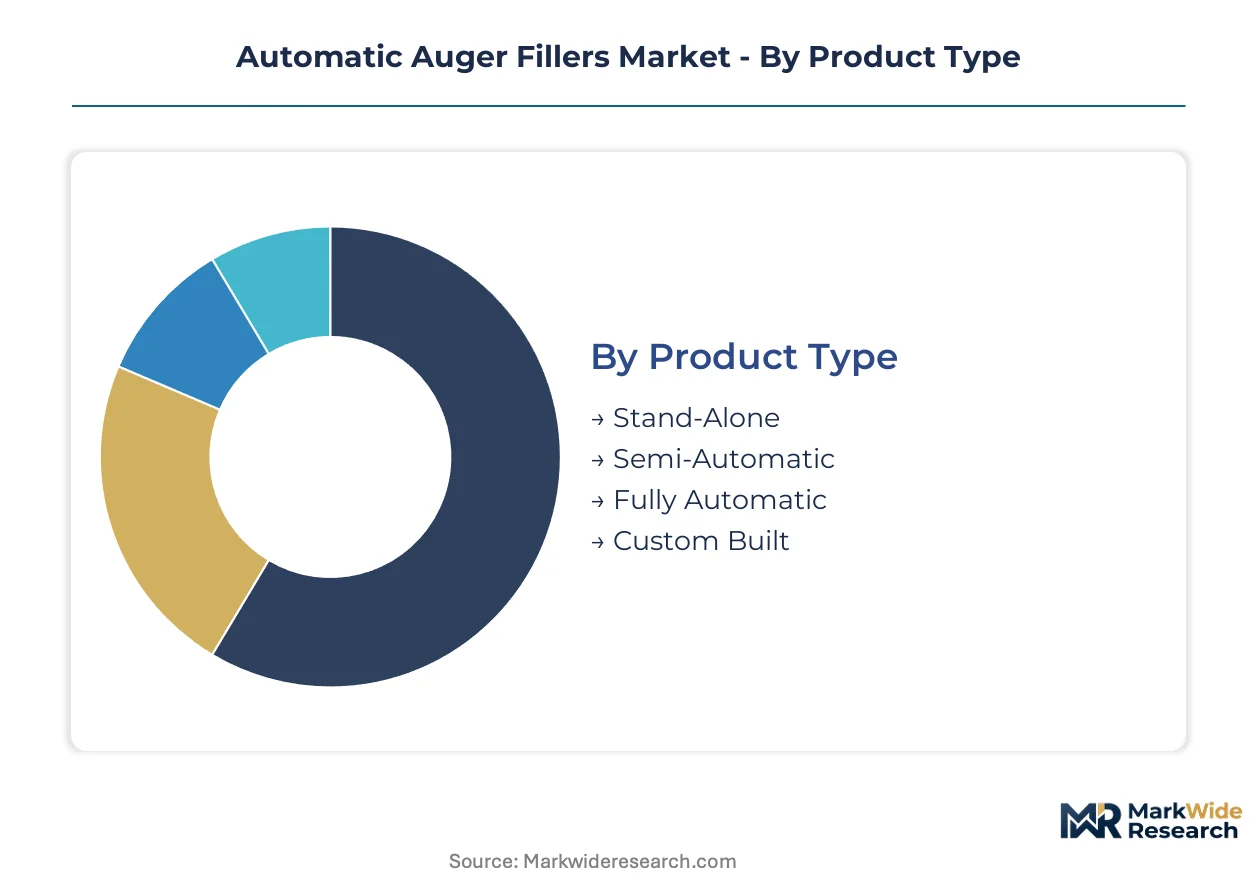
Auger filler procurement patterns diverge sharply between high-volume food processors seeking throughput maximization and pharmaceutical manufacturers prioritizing validation documentation. Segment selection determines total cost of ownership calculations, spare parts availability, and regulatory compliance pathways across installation lifecycles.
Product Type:
Capital expenditure thresholds and line integration complexity separate buyers across this category, with multi-SKU operators weighing changeover flexibility against dedicated throughput.
- Fully Automatic:Continuous-motion architectures with integrated conveyor systems dominate high-volume dairy and nutritional powder operations. German contract packaging hubs specify these configurations for multi-client campaigns requiring rapid format changeovers.
- Stand-Alone:Modular units with independent control systems serve laboratory-scale production and pilot manufacturing where line integration is deferred. Pharmaceutical R&D facilities in Switzerland favor these for formulation flexibility during clinical trial material production.
- Semi-Automatic:Operator-assisted loading with automated dispensing cycles occupies the mid-market for regional food processors.
- Custom Built:Engineered-to-order systems address ATEX hazardous environments and containment requirements for potent pharmaceutical compounds.
Volume sits with Fully Automatic configurations; growth tilts toward Custom Built systems as potent compound manufacturing expands.
Application:
Regulatory intensity and powder characteristics reshape equipment specifications, with validation documentation requirements creating distinct procurement workflows.
- Pharmaceuticals:FDA cGMP and EU MDR traceability mandates demand servo-driven systems with auditable fill profiles and material certificates of analysis. Installation qualification and operational qualification documentation now determine supplier selection ahead of equipment cost.
- Food & Beverage:Dairy powders, nutritional supplements, and spice blends drive the broadest installed base. Clean-in-place integration and rapid changeover tooling dominate specification conversations for contract manufacturers serving multiple brand owners.
- Chemicals:ATEX compliance for explosive powder atmospheres constrains supplier participation and extends engineering lead times.
- Cosmetics:Precision dosing for mineral foundations and talc-based products favors compact servo configurations with cosmetic-grade contact surfaces.
Revenue concentrates in Food & Beverage; specification intensity climbs fastest in Pharmaceuticals.
End User:
Internal technical capabilities and service outsourcing preferences differentiate procurement behavior across buyer types.
- Packaging Companies:German chemical and food processing hubs unbundle after-sales service from capital procurement, selecting specialized field service organizations for preventive maintenance across heterogeneous fleets.
- Manufacturers:Captive production operations prioritize vertical integration of maintenance capabilities and standardized spare parts inventories.
- Food Processors:Seasonal demand patterns and SKU proliferation drive interest in rapid changeover tooling and programmable fill profiles.
- Laboratories:Small-batch flexibility and containment requirements for potent compounds dominate specification priorities.
Equipment shipments favor Manufacturers; margin expansion is steepest with Packaging Companies.
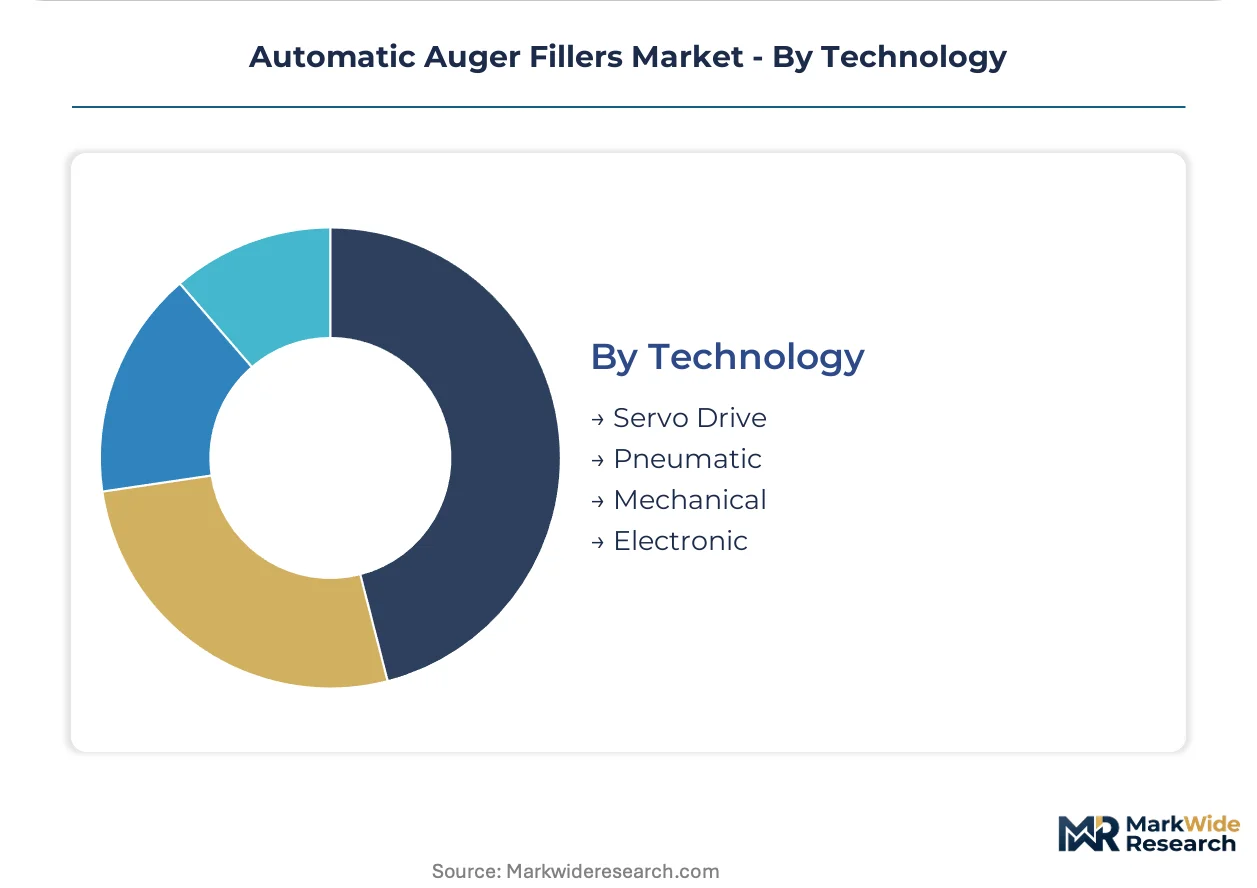
Technology:
Motion control architecture determines precision capabilities, maintenance intervals, and Industry 4.0 connectivity potential.
- Servo Drive:Brushless motors with integrated encoders enable programmable fill profiles and real-time torque feedback. Pharmaceutical manufacturers specify these for high-value active pharmaceutical ingredients where batch consistency determines regulatory approval.
- Pneumatic:Simpler architectures with lower capital cost serve stable, high-volume applications with limited SKU variation.
- Mechanical:Cam-driven systems persist in legacy installations with long depreciation schedules.
- Electronic:Hybrid architectures combining stepper motors with load cell feedback occupy niche precision applications.
Installed base remains with Pneumatic systems; replacement demand flows toward Servo Drive technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contract packaging hubs concentrate European demand for multi-SKU flexible equipment, while pharmaceutical serialization mandates in Switzerland and regulatory expansion in India reshape procurement patterns across distinct national frameworks.
Germany
Contract packaging operations serving domestic chemical producers and EU food processors drive dense demand clusters for rapid changeover tooling. ATEX directives for explosive powder atmospheres constrain supplier participation in hazardous environment segments. The Rhine-Ruhr industrial corridor anchors equipment specification intensity through integrated processing and packaging line requirements.
Switzerland
Pharmaceutical manufacturers specify brushless servo systems for high-value active pharmaceutical ingredients where batch consistency determines regulatory approval. Swissmedic validation protocols demand auditable fill profiles and material certificates of analysis across installation qualification phases. Basel and Zurich clusters concentrate precision dosing equipment procurement for clinical trial material production.
United States
FDA cGMP validation protocols compel powder-based drug manufacturers to demonstrate installation and operational qualification documentation. OSHA dust exposure limits further constrain design choices for chemical and food processing environments. New Jersey and Massachusetts pharmaceutical corridors drive replacement of legacy pneumatic fillers with servo-driven systems.
India
CDSCO compliance requirements and PLI scheme incentives for active pharmaceutical ingredient production create demand for validated powder dosing equipment. Contract manufacturing organizations in Hyderabad and Mumbai expand adoption of precision dosing equipment to meet domestic and export regulatory standards. Maharashtra and Telangana states concentrate pharmaceutical manufacturing investment.
China
NMPA traceability mandates for powder-based drug delivery systems extend documentation obligations to primary packaging equipment. Dual carbon goals accelerate electrification of precision powder dosing through brushless servo motor adoption. Yangtze River Delta pharmaceutical clusters specify equipment with predictive maintenance capabilities and Industry 4.0 connectivity.
Automatic Auger Fillers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical validation capabilities commanding premium positioning against food-grade volume plays. The vendor base organizes around three strategic archetypes: integrated processing conglomerates with packaging line bundling power, precision dosing specialists with servo-driven architectures, and regional fabricators serving mid-market pneumatic demand. Consolidation pressures concentrate among validation-capable suppliers as EU MDR documentation requirements eliminate price-only procurement. Geographic expansion and technology licensing represent the dominant competitive vectors as suppliers seek to overcome servo motor and drive component bottlenecks.
Within the precision dosing specialist tier, All-Fill Inc. and Spee-Dee Packaging Machinery, Inc. exemplify servo-driven architecture positioning, while GEA Group Aktiengesellschaft anchors European supply through its Aktiengesellschaft structure and integrated processing heritage. These three occupy positions spanning programmable fill profile capabilities to dairy and nutritional powder line integration, representing distinct competitive postures without overlapping segment dominance.
| Leading Market Players |
|---|
| Accutek Packaging Equipment Company, Inc. |
| All-Fill Inc. |
| Busch Machinery, Inc. |
| PER-FIL Industries |
| AMS Filling Systems, Inc. |
| Spee-Dee Packaging Machinery, Inc. |
| Paxiom Group Inc. |
| GEA Group Aktiengesellschaft |
| IMA Group |
| Others |
Value Network & Pricing Analysis
Backward integration into servo motor and drive component production anchors supply position and pricing power for auger filler manufacturers seeking insulation from Japanese and German component bottlenecks. Pharmaceutical validation requirements compress margin flexibility for suppliers lacking auditable fill profile capabilities, while contract packaging buyers in Germany unbundle after-sales service to strip capital quotes.
Pricing Analysis
Volume concentrates in pneumatic systems serving stable dairy and nutritional powder operations; margins accrue to servo-driven architectures with programmable fill profiles and predictive maintenance capabilities. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical configurations from food-grade stainless steel installations and legacy carbon steel units. Cost compression in mid-market pneumatic tiers intensifies because contract packaging buyers negotiate stripped-down capital quotes. Regional food processors exhibit highest price sensitivity; Swiss pharmaceutical manufacturers prioritize validation documentation over equipment cost.
Supply Chain Analysis
Workforce availability constraints in German and Swiss precision engineering clusters extend lead times for servo motor integration and encoder calibration. Component sourcing draws from Japan, Germany, and Taiwan for brushless servo motors, precision gearboxes, and integrated control systems. Single-source vulnerability concentrates in precision motion control hardware from specialized Japanese suppliers. Distribution runs through integrated processing conglomerates with packaging line bundling power and regional fabricators serving mid-market pneumatic demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through servo motor and drive component bottlenecks, with validation-capable suppliers commanding pricing premiums that compound through equipment replacement cycles.
For Market Incumbents: Hedge against component concentration by securing long-term supply agreements with Japanese servo motor suppliers or acquiring precision motion control specialists. FDA cGMP validation protocols and EU MDR traceability mandates compress replacement cycles for competitors lacking documentation capabilities. Capacity addition in Indian pharmaceutical manufacturing clusters represents the priority lever for geographic diversification. For New Entrants and Emerging Players: E-commerce direct-to-consumer nutraceutical channels offer white-space entry with portion-controlled single-serve packaging formats requiring precision micro-dosing configurations. Clean-in-place automation convergence in dairy and nutritional powder applications presents secondary penetration opportunity with reduced validation burden compared to pharmaceutical tiers. Target contract manufacturing organizations in India with CDSCO-compliant documentation packages as the go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated processing conglomerates seeking precision dosing capabilities. Long-term viability favors suppliers with captive servo drive technology and pharmaceutical validation expertise. Watch for CDSCO enforcement acceleration in Indian contract manufacturing as the inflection indicator signaling demand inflection for validated equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Servo Drive Technology Licensing | Japanese and German component suppliers monetize precision motion control IP through technology transfer agreements. |
| Validation Documentation Bundling | FDA cGMP and EU MDR compliance packages differentiate suppliers in pharmaceutical procurement decisions. |
| Clean-in-Place System Integration | Dairy processors reduce downtime through automated CIP convergence with servo-driven fill heads. |
| Contract Packaging Service Unbundling | German chemical and food hubs separate after-sales maintenance from capital equipment procurement. |
| Indian Manufacturing Footprint Expansion | CDSCO compliance requirements and PLI scheme incentives attract precision dosing equipment investment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this automatic auger fillers analysis. Primary interviews with packaging line engineers, pharmaceutical validation specialists, contract manufacturing procurement managers, and aftermarket service directors combined with FDA 483 observations, EU MDR technical documentation, and German mechanical engineering association statistics. Bottom-up equipment shipment triangulation against top-down powder processing capacity expansion verified market sizing.
Data-stream reconciliation across servo drive adoption rates, pneumatic system replacement cycles, and pharmaceutical capital expenditure patterns shaped the analytical framework. Segmentation dimensions modeled include motion control architecture, automation level, end-use regulatory intensity, and regional manufacturing hub concentration. CAGRs derived from equipment replacement cycle compression and validation mandate expansion throughout the forecast period. Industry-specific inputs incorporated ATEX compliance engineering overhead and stainless steel material certificate traceability costs.
The model holds under stable regulatory enforcement intensity; deviation in FDA inspection frequency or EU MDR implementation pace would shift replacement demand timing. Forecasts reflect assumptions regarding servo component supply normalization and pharmaceutical serialization mandate adherence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Product Dispensing Machinery Market
Packaging Machinery
Asia-Pacific Pharmaceutical Packaging Machinery Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Paper Slitting Machine Market
Packaging Machinery
Paper Napkin Converting Lines Market
Packaging Machinery
Cartridge Filling System Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Emboss Coding Machine Market
Packaging Machinery
Pick Fill Seal Machines Market
Packaging Machinery
Wicketed Bagging Machines Market