
 Automatic Strapping Machines Market | 2026-2036
Automatic Strapping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Strapping Machines Market Analytics
Skilled maintenance technicians for servo-driven strapping systems is rotating toward shortage in mature manufacturing economies, tightening equipment uptime guarantees and reshaping vendor service contracts. Mosca GmbH leverages its German engineering base to sustain premium positioning in high-throughput applications. FROMM Packaging Systems anchors Nordic and Asian markets through specialized cold-climate strapping solutions. Samuel Strapping Systems competes on manufacturing scale across North American corrugated and palletizing operations.
Automatic strapping machines apply tensioned plastic, steel, or composite bands around packages or palletized loads, sealing joints through heat welding, friction welding, or mechanical seals at speeds exceeding sixty straps per minute in fully automatic configurations. The equipment secures goods for transport, stabilizes pallet loads, and automates the final stage of packaging lines in distribution centers and manufacturing plants. Fully automatic systems lead volume shipments in logistics end-use while servo-driven technology captures margin pools through precision tension control and energy efficiency. Plastic strap dominates material consumption due to cost and handling advantages, though steel strap retains structural applications in heavy manufacturing.
FDA regulations govern strapping material contact with food and pharmaceutical products in the United States, while OSHA standards mandate guarding and emergency stop protocols on automated packaging equipment. The EU Machinery Directive and CE marking framework enforce safety interlocks and electromagnetic compatibility across European installations. REACH compliance constrains chemical composition of plastic strapping materials in European markets. Stakeholders must monitor evolving servo-motor efficiency standards and regional recyclability mandates for plastic strap waste as equipment replacement cycles accelerate.
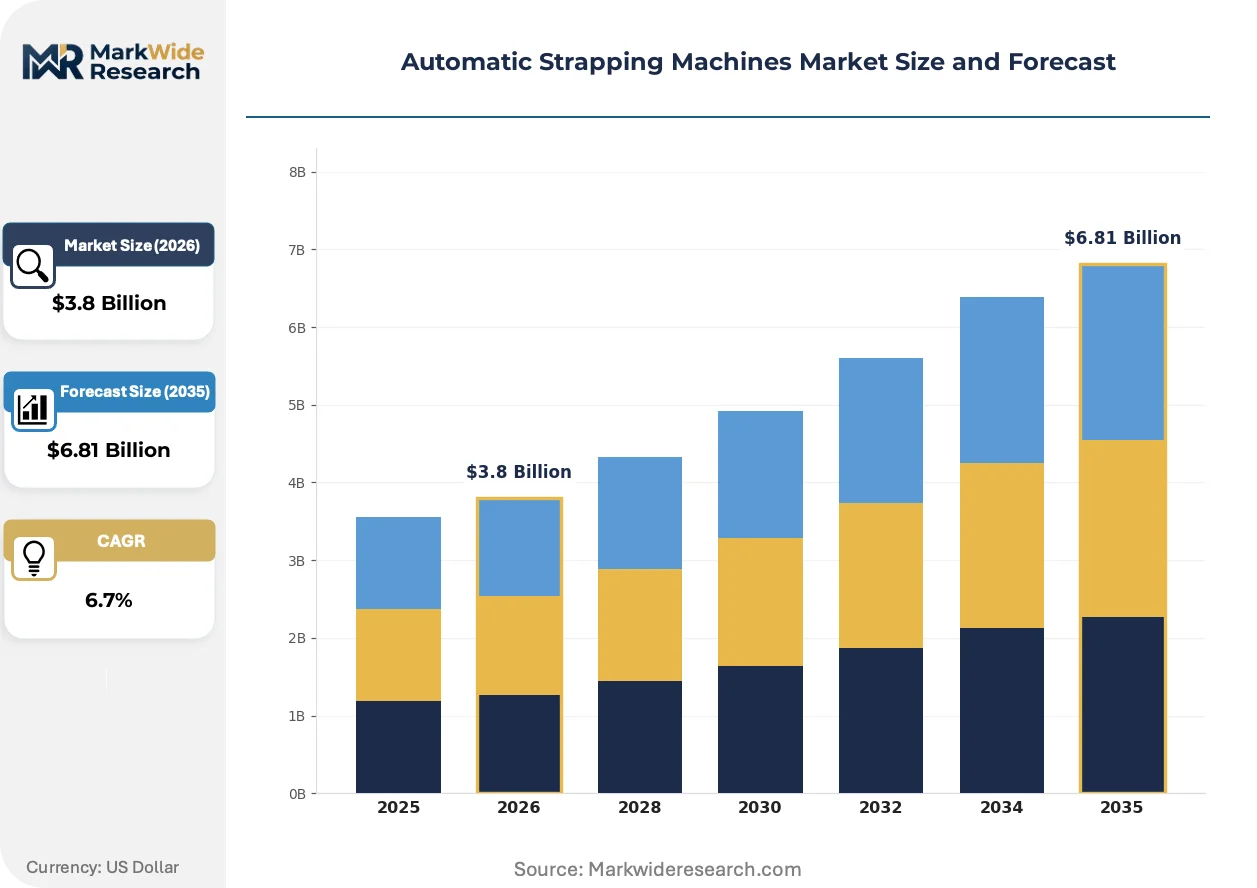
Market Dynamics
Servo-driven tension control systems are compressing maintenance intervals and forcing vendor restructuring of field service networks across high-throughput logistics installations. The technology shift from pneumatic to electric actuation is redefining equipment lifecycle economics and aftermarket revenue pools.
Growth Catalysts
- E-commerce fulfillment density:Parcel consolidation centers in Germany and the United States are specifying fully automatic arch-type machines capable of sixty-plus straps per minute to match sortation throughput.
- EU Machinery Directive compliance:CE marking requirements for safety interlocks and electromagnetic compatibility are accelerating replacement of pre-2023 equipment across European manufacturing plants.
- Plastic strap material conversion:Polypropylene and polyester strapping is capturing share from steel in secondary packaging applications due to handling efficiency and recyclability profile.
Market Restraints
- Steel price volatility:Structural strapping applications in heavy manufacturing remain exposed to raw material cost swings that compress equipment margin on bundled steel-strap systems.
- Maintenance technician scarcity:Servo-drive diagnostics and programming skills concentrate in aging workforce pools across the United States and Germany, extending downtime response windows.
- REACH chemical constraints:European plastic strap formulations face restricted additive portfolios that limit material performance in high-tension cold-climate applications.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for electronics and automotive assembly are creating greenfield demand for automatic strapping integration in new plant construction.
- Pharmaceutical serialization:FDA track-and-trace requirements for unit-level verification are driving strapping equipment specification with integrated vision and rejection systems.
- Remanufactured equipment channels:Certified rebuild programs for servo-driven systems are opening secondary market penetration among mid-volume corrugated converters in the United States.
Industry Challenges
- Servo calibration expertise:Precision tension programming requires specialized technicians that OEMs struggle to train and retain across dispersed service territories.
- Legacy integration complexity:Pneumatic-era palletizing lines in mature manufacturing bases require costly control system retrofits to interface with modern strapping controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Strapping Machines Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automatic, Fully Automatic, Manual, Automatic with Print & Apply Technology: Pneumatic, Electric, Servo-Driven, Hydraulic End User: Packaging, Logistics, Manufacturing, Retail Material: Plastic Strap, Steel Strap, Composite Strap, Others |
| Companies Covered | Signode Industrial Group LLC, Mosca GmbH, FROMM Packaging Systems, StraPack Inc., Dynaric Inc., Samuel Strapping Systems, Polychem Corporation, Transpak Equipment Corp., M.J. Maillis Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Strapping Machines Market Evolving Landscape
Digital tension monitoring and predictive maintenance algorithms are reconfiguring how operators manage strap quality and equipment uptime. The convergence of sensor hardware and cloud analytics is compressing the traditional reactive service model.
Friction-weld sealing heads with integrated force-feedback sensors are displacing heat-weld architectures in high-speed plastic strapping applications. E-commerce fulfillment centers in the United States and Germany are specifying these systems to eliminate thermal cycling delays and reduce energy draw. The shift is displacing incumbent European heat-weld specialists from premium logistics contracts.
REACH compliance deadlines for plastic strapping additives are forcing reformulation of polyester and polypropylene compounds across European supply chains. ECHA substance restrictions on certain plasticizers are elevating material costs and compressing availability windows for legacy strap grades. German automotive and appliance manufacturers are responding by qualifying alternative bio-based strap materials ahead of 2025 renewal cycles.
Outcome-based maintenance contracts are unbundling equipment purchase from performance guarantees in North American corrugated and beverage distribution. Large volume operators are shifting from capital acquisition to per-strap pricing models that transfer uptime risk to OEM service organizations. The model is most visible among palletizing operations in the United States Midwest where seasonal volume spikes strain internal maintenance capacity.
Automatic Strapping Machines Market Segmentation
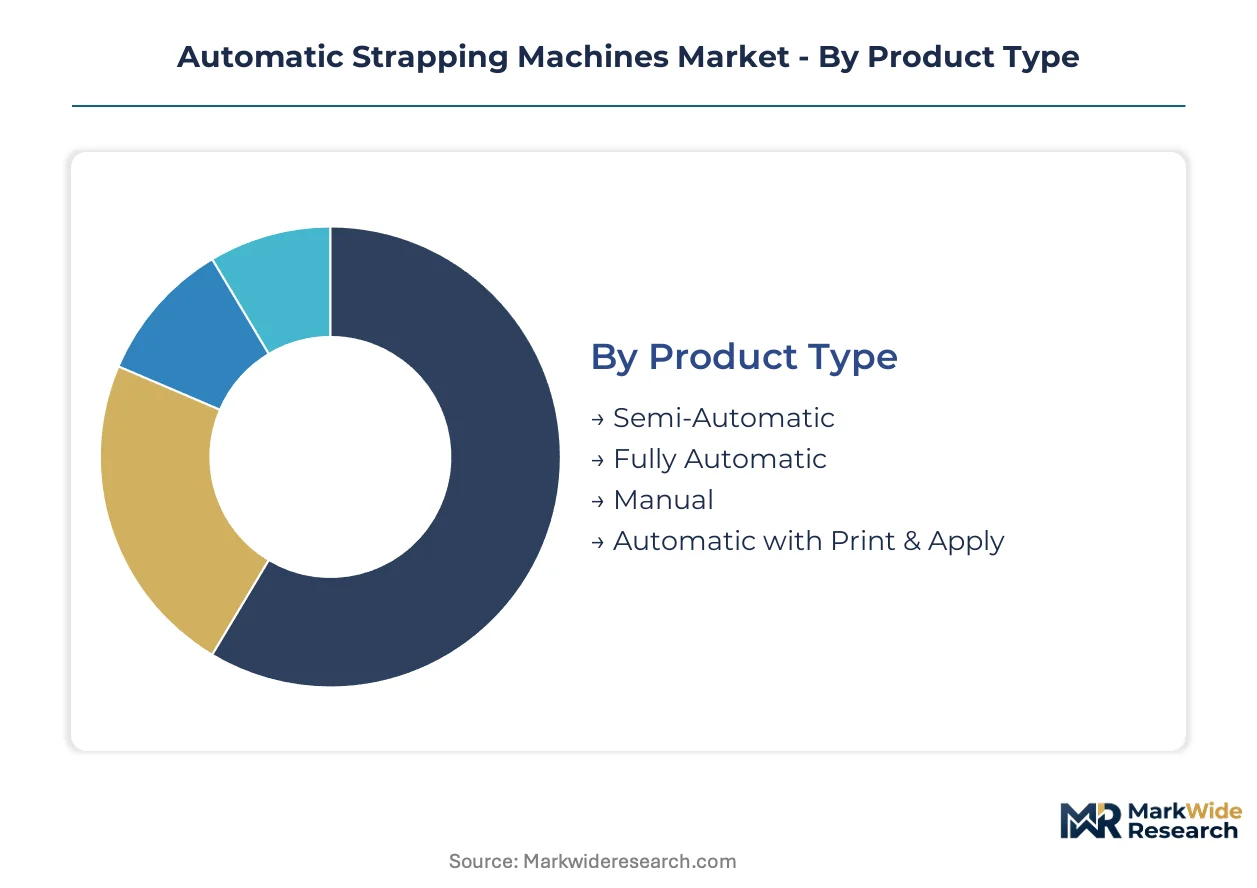
Automatic strapping machines serve divergent operational requirements across fulfillment velocity tiers and regulatory exposure levels. Segmentation reveals how equipment specifications map to compliance burdens and throughput economics in distinct customer environments.
Product Type:
CE marking requirements under the EU Machinery Directive create divergent compliance costs across automation tiers, with fully automatic systems facing stricter safety interlock mandates than semi-automatic alternatives.
- Fully Automatic:Arch-type configurations process sixty-plus straps per minute with integrated conveyor interfaces and programmable logic controllers. E-commerce fulfillment centers in Germany and the United States specify these systems to match high-velocity sortation infrastructure, though servo-drive calibration complexity extends vendor response windows.
- Semi-Automatic:Operator-fed designs apply tension and seal through foot-pedal or button activation, bridging manual handling and automated throughput. Mid-volume corrugated converters in the United States Midwest favor these units where seasonal volume spikes strain capital budgets.
- Manual:Hand-held tensioning tools serve low-volume repair, field service, and specialty packaging applications.
- Automatic with Print & Apply:Integrated label applicators support pharmaceutical serialization and unit-level tracking requirements.
Fully automatic systems handle the majority of throughput; automatic with print and apply is climbing the fastest on share.
Technology:
Customer procurement patterns concentrate on energy efficiency and maintenance predictability, with electric actuation displacing pneumatic infrastructure in greenfield installations.
- Servo-Driven:Closed-loop tension control delivers precision within two percent variance, enabling lightweight strap specification without load instability. Precision programming demands scarce technician expertise across the United States and Germany, compressing vendor service contract terms.
- Electric:Brushless motor architectures eliminate compressed air infrastructure, reducing energy draw in continuous-duty logistics environments.
- Pneumatic:Legacy installations dominate mature manufacturing bases where control system retrofits impose integration costs.
- Hydraulic:High-force applications in heavy manufacturing retain this technology for steel strap tensioning.
Servo-driven systems command the steepest expansion trajectory; pneumatic equipment retains installed base dominance.
End User:
Application-specific throughput requirements and regulatory exposure shape equipment specification across customer verticals.
- Logistics:Parcel consolidation centers specify friction-weld sealing heads to eliminate thermal cycling delays. FDA track-and-trace mandates drive vision-integrated configurations in pharmaceutical distribution.
- Manufacturing:Automotive and appliance plants qualify bio-based strap materials ahead of REACH renewal cycles.
- Packaging:Corrugated converters adopt per-strap pricing models to transfer uptime risk.
- Retail:Back-of-store applications favor compact semi-automatic units for pallet stabilization.
Logistics commands the largest equipment flow; manufacturing is expanding most quickly on specification intensity.
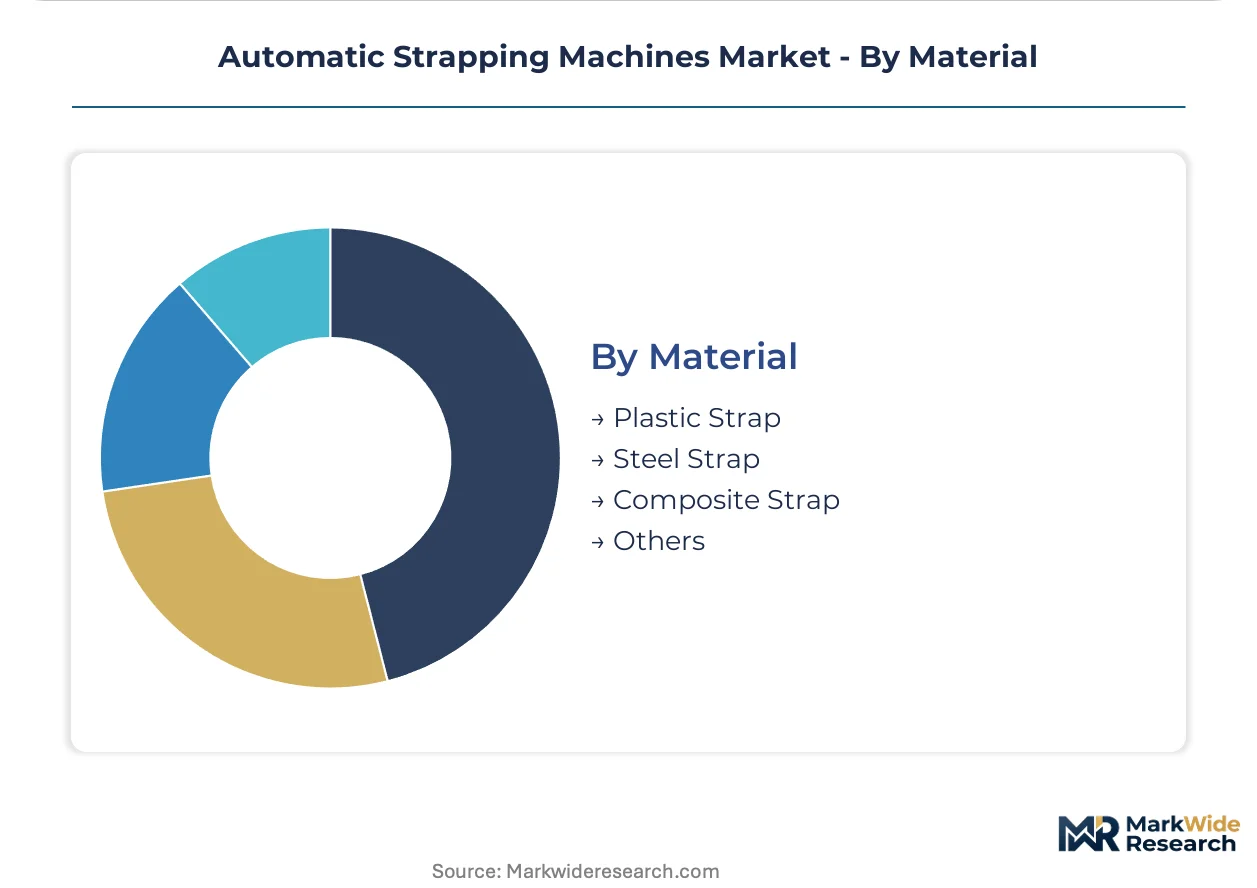
Material:
REACH chemical constraints and recyclability mandates are reformulating material selection across European supply chains.
- Plastic Strap:Polypropylene and polyester compounds capture secondary packaging share through handling efficiency and recyclability profile. ECHA restrictions on certain plasticizers elevate costs and compress availability for legacy grades.
- Steel Strap:Structural applications in heavy manufacturing retain this material for load security, though price volatility compresses bundled system margins.
- Composite Strap:Corded polyester formulations bridge plastic handling advantages with steel tensile strength.
- Others:Bio-based and paper-based alternatives emerge in sustainability-focused specifications.
Plastic strap dominates material throughput; composite formulations are gaining share fastest on performance hybridization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety mandates in the United States are synchronizing with CE marking enforcement across European installations, creating parallel compliance upgrade cycles that concentrate equipment procurement in Germany, China, and the United States.
United States
E-commerce fulfillment centers in the Midwest and Southeast are specifying friction-weld sealing heads to match sortation throughput. FDA track-and-trace requirements for pharmaceutical distribution are mandating vision-integrated strapping configurations. The Chicago-Detroit corridor hosts dense palletizing operations where outcome-based maintenance contracts are displacing capital acquisition models.
Germany
Automotive and appliance manufacturers in Bavaria and Baden-Württemberg are qualifying bio-based strap materials ahead of REACH renewal cycles. The EU Machinery Directive's safety interlock mandates are accelerating replacement of pre-2023 equipment. Stuttgart's manufacturing belt exhibits concentrated demand for servo-driven precision tension control in high-throughput export packaging.
China
Electronics assembly clusters in the Yangtze River Delta and Pearl River Delta are integrating automatic strapping into greenfield plant construction. MIIT industrial upgrading programs are subsidizing automation equipment procurement for domestic manufacturers. Shenzhen's logistics hubs are deploying arch-type machines to match cross-border e-commerce export velocity.
India
PLI scheme incentives for electronics and automotive assembly are creating demand for automatic strapping integration in Maharashtra and Tamil Nadu new plant construction. BIS equipment safety standards are tightening certification requirements for imported machinery. The Chennai-Bengaluru industrial corridor is emerging as a concentration zone for servo-driven system adoption.
Japan
Precision manufacturing facilities in the Kanto and Kansai regions are specifying servo-driven tension control for lightweight strap applications. METI energy efficiency standards are favoring electric actuation over pneumatic infrastructure in packaging line retrofits. Nagoya's automotive supplier network is consolidating strapping equipment specifications to reduce maintenance technician dependency.
Automatic Strapping Machines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting divergent scale economies across high-throughput logistics and mid-volume manufacturing applications. The upper tier commands premium positioning through captive service networks and precision engineering capabilities. Specialist fabricators compete on customization depth and regional responsiveness. Dominant competitive moves include backward integration into strap material production and geographic expansion through certified rebuild programs.
Within the engineering-intensive tier, Mosca GmbH and FROMM Packaging Systems exemplify divergent geographic anchoring strategies, with the former occupying a position calibrated to German precision manufacturing demand and the latter representing Nordic and Asian market specialization. Samuel Strapping Systems sits within the scale-driven North American segment, reflecting manufacturing volume concentration across corrugated and palletizing operations. These three entities collectively illustrate how competitive positioning fragments across regional infrastructure maturity and end-use density.
| Leading Market Players |
|---|
| Signode Industrial Group LLC |
| Mosca GmbH |
| FROMM Packaging Systems |
| StraPack Inc. |
| Dynaric Inc. |
| Samuel Strapping Systems |
| Polychem Corporation |
| Transpak Equipment Corp. |
| M.J. Maillis Group |
| Others |
Value Network & Pricing Analysis
Ninety-day component lead times for servo-drive modules concentrate pricing power with German and Japanese motion-control suppliers, compressing margins for strapping equipment OEMs while elevating total cost of ownership for end users. This inventory pressure intersects with regional regulatory divergence to fragment pricing architectures across mature and emerging manufacturing bases.
Pricing Analysis
Equipment price spreads between German-engineered servo systems and Chinese electric alternatives span roughly forty percent at equivalent throughput ratings, with CE certification and FDA validation tiers commanding premiums over baseline BIS-compliant configurations. Three-tier pricing structure across premium, standard, and economy levels segments by automation depth and after-sales bundling intensity. Cost compression in economy-tier pneumatic equipment is intensifying because of surplus capacity among Asian fabricators. Mid-volume corrugated converters in the United States Midwest exhibit highest price sensitivity, while pharmaceutical serialization mandates render logistics operators least sensitive.
Supply Chain Analysis
Germany and Japan anchor precision servo motor and controller production for high-throughput strapping architectures, while China dominates electric actuator and frame fabrication at scale. Steel strap feedstock draws from integrated mills in the United States and South Korea, with polypropylene resin sourcing tethered to petrochemical complexes along the Gulf Coast and in the Middle East. Single-source vulnerability concentrates in precision tension sensors and sealed bearing assemblies. Distribution runs through OEM-direct channels for large-volume logistics operators, with regional distributors serving mid-tier manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic strapping machines market sits at an inflection where servo-driven precision technology and REACH chemical compliance are simultaneously elevating equipment specification intensity and fragmenting vendor competitive positions.
For Market Incumbents: Compound service network density in Germany and the United States to defend against emerging Asian challengers exploiting PLI-subsidized greenfield demand in India. Deepen backward integration into strap material production to capture margin pools eroding at the equipment tier. Prioritize certified rebuild programs for servo-driven systems to lock mid-volume corrugated accounts into recurring revenue streams. For New Entrants and Emerging Players: Anchor in India's electronics and automotive assembly corridors where PLI scheme incentives are accelerating greenfield plant construction and local vendor relationships remain unformed. Target friction-weld sealing head technology gaps in Southeast Asian logistics hubs seeking to bypass thermal-cycling limitations of legacy heat-weld architectures. Pursue outcome-based maintenance contracts as the primary go-to-market mechanism to transfer uptime risk and differentiate from capital-sale incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because servo-drive calibration expertise scarcity and aging technician demographics are structurally advantaging scaled service organizations over point-product fabricators. Acquisition candidates should exhibit captive strap material production and dense regional service footprints. Monitor REACH additive restriction enforcement timelines as the signal indicating acceleration of bio-based strap material qualification cycles and associated equipment retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strap Material Production | Captive polypropylene supply secures margin pools against ECHA plasticizer cost volatility. |
| Certified Rebuild Program Expansion | Secondary market penetration captures mid-volume corrugated converters in seasonal-demand regions. |
| Friction-Weld Sealing Head Development | Eliminates thermal cycling delays for e-commerce fulfillment centers in Germany and the United States. |
| Outcome-Based Maintenance Contract Rollout | Per-strap pricing transfers uptime risk to OEMs in palletizing operations with strained internal capacity. |
| Bio-Based Strap Material Qualification | REACH compliance positioning captures automotive and appliance manufacturer renewal cycles in Bavaria. |
Research Methodology
Cross-validation between maintenance director interviews at logistics operators and SEC filings from packaging equipment OEMs anchors the qualitative findings in operational reality and financial disclosure. Primary fieldwork engaged plant engineers at corrugated converters, aftermarket service heads at regional distributors, OEM procurement teams, and maintenance technicians specializing in servo-drive diagnostics. Secondary validation incorporated customs trade data for strapping material flows, OSHA and EU Machinery Directive enforcement records, and ECHA substance restriction timelines. Bottom-up equipment shipment estimates triangulated against top-down manufacturing value-added projections.
Sensitivity analysis around servo-drive adoption curves and REACH compliance deadlines tested forecast robustness across the projection horizon. Segmentation dimensions modeled include automation tier, actuation technology, end-use vertical, material type, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and greenfield installation tracking. Industry-specific inputs encompassed e-commerce fulfillment center buildout pipelines and pharmaceutical serialization mandate implementation schedules.
Decision-makers should treat outputs as directional under assumptions of sustained e-commerce velocity and stable steel strap pricing; material deviation would warrant model refresh. Specific risks that could revise forecasts include acute servo-motor supply disruption, accelerated REACH additive bans, or tariff escalation affecting Chinese electric actuator imports. Recalibration cycles align with material shifts in EU Machinery Directive enforcement intensity and PLI scheme renewal terms in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Pre-Assembled Packaging Market
Packaging Automation
Automatic Die Cutting Machines Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
Automatic Glue Machine Market
Packaging Automation
Automatic Capping Machine Market
Packaging Automation
Europe Packaging Automation Market
Packaging Automation
APAC Packaging Automation Market
Packaging Automation
Packaging Automation Solutions Market
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
Packaging Automation Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
Automated Tray Fill and Seal Machines Market
Packaging Automation
Robotic Packaging Machines Market