
 Strapping Machine Market | 2026-2036
Strapping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Strapping Machine Market Intelligence
Equipment leasing and pay-per-use financing is reconfiguring competitive dynamics for mid-sized logistics operators seeking automated strapping without capital commitment. FROMM Packaging Systems leverages its European manufacturing footprint to sustain regional service density. Samuel Strapping Systems anchors North American demand through steel strapping specialization. Dynaric Inc. differentiates via in-house production of strapping heads and control systems.
A strapping machine applies tensioned banding material around pallets, cartons, or bundles and seals the joint through heat welding, friction welding, or mechanical fastening to secure loads for transport and storage. Automatic variants achieve throughput exceeding 60 straps per minute with programmable tension control for fragile electronics. Semi-automatic units retain the largest installed base among small-to-mid warehouses where operator-assisted feeding balances speed and capital outlay. Robotic strapping systems are capturing margin pools in high-volume beverage distribution centers where labor scarcity pressures automation decisions.
The U.S. OSHA and the EU Machinery Directive impose guarding, emergency-stop, and noise-level standards that shape machine design and market access for imported equipment. EPA and REACH regulations on plastic strapping composition are pushing manufacturers toward recycled-content polyester and phthalate-free formulations. Stakeholders must monitor how evolving extended producer responsibility frameworks in Germany and France reshape material specifications and total cost of ownership calculations.
Market Dynamics
Equipment leasing and pay-per-use financing are reconfiguring competitive dynamics for mid-sized logistics operators seeking automated strapping without capital commitment. E-commerce fulfillment centers are driving equipment procurement across North America and Europe, while China's manufacturing hub expansion concentrates automated packaging line demand.
Growth Catalysts
- Germany's Packaging Act:Extended producer responsibility frameworks mandate recyclable polyester strapping, accelerating equipment upgrades for compliance.
- Beverage distribution automation:Labor scarcity in high-volume beverage centers is pulling robotic strapping systems into active deployment.
- Polyester material innovation:Recycled-content and phthalate-free strapping formulations align with EPA and REACH specifications, expanding addressable equipment markets.
Market Restraints
- Steel input cost volatility:Samuel Strapping Systems' specialization in steel strapping exposes buyers to ferrous metal price swings that compress margin predictability.
- Control system supply concentration:Dynaric Inc.'s in-house production of strapping heads creates dependency risk for competitors lacking captive component supply.
- Mechanical fastening technical ceiling:Heat and friction welding speeds plateau below 60 straps per minute for fragile electronics handling, limiting throughput gains.
Strategic Opportunities
- India manufacturing hub expansion:Automated packaging line concentration in Indian production facilities remains underpenetrated relative to China, offering first-mover positioning.
- EU Green Deal alignment:France's evolving extended producer responsibility frameworks create regulatory tailwinds for circular-economy-certified equipment.
- Vision-guided robotics convergence:Integration of machine vision with collaborative robot arms enables adaptive strapping for variable pallet geometries without manual reprogramming.
Industry Challenges
- OSHA guarding compliance:U.S. equipment importers face extended certification timelines for emergency-stop and noise-level standard verification.
- Legacy warehouse management integration:Semi-automatic unit installed bases in small-to-mid warehouses create friction for programmable tension control upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strapping Machine Market |
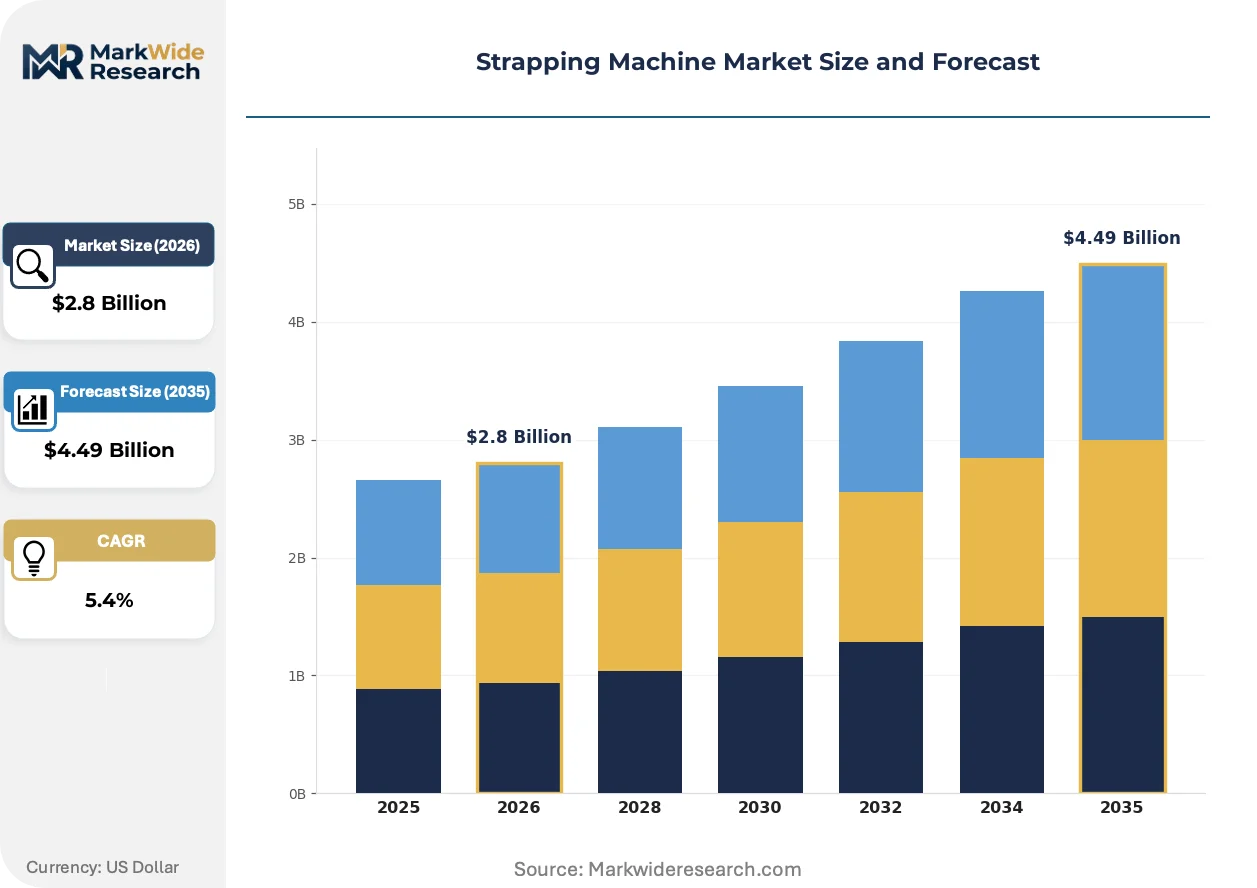
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Automatic, Robotic Material Type: Plastic, Steel, Polypropylene, Polyester End User: Food & Beverage, Electronics, Pharmaceuticals, Retail Technology: Heat Seal, Friction Weld, Ultrasonic, Electric |
| Companies Covered | StraPack Inc., FROMM Packaging Systems, Signode Industrial Group LLC, Samuel Strapping Systems, Cyklop International, Mosca GmbH, Dynaric Inc., MJ Maillis Group, Polychem Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strapping Machine Market Strategic Shifts & Innovations
Automation architecture is fragmenting across throughput tiers, with programmable control systems separating premium from economy equipment tiers. Material science advances and regulatory chemistry restrictions are simultaneously reshaping strapping composition and sealing technology roadmaps.
Ultrasonic welding heads for polyester banding are rendering obsolete heat-seal architectures in food-grade packaging environments where thermal residue contamination poses liability risk. Pharmaceutical cold-chain distributors in Switzerland and the Netherlands are adopting these heads at replacement cycle pace. The shift is compressing maintenance intervals and spare parts revenue for legacy sealing component suppliers.
REACH regulations on phthalate plasticizers are forcing reformulation of polypropylene strapping across EU member states. Manufacturers must validate alternative plasticizers through ECHA notification procedures before market placement. German packaging machinery OEMs are responding with pre-certified strapping material bundling to accelerate customer compliance.
Third-party logistics operators are unbundling after-sales service from equipment purchase, preferring per-strap maintenance contracts with uptime guarantees. This displaces traditional break-fix service models in Benelux distribution corridors. The pattern is most visible among mid-sized e-commerce fulfillment contractors serving pan-European retailer networks.
Strapping Machine Market Segmentation
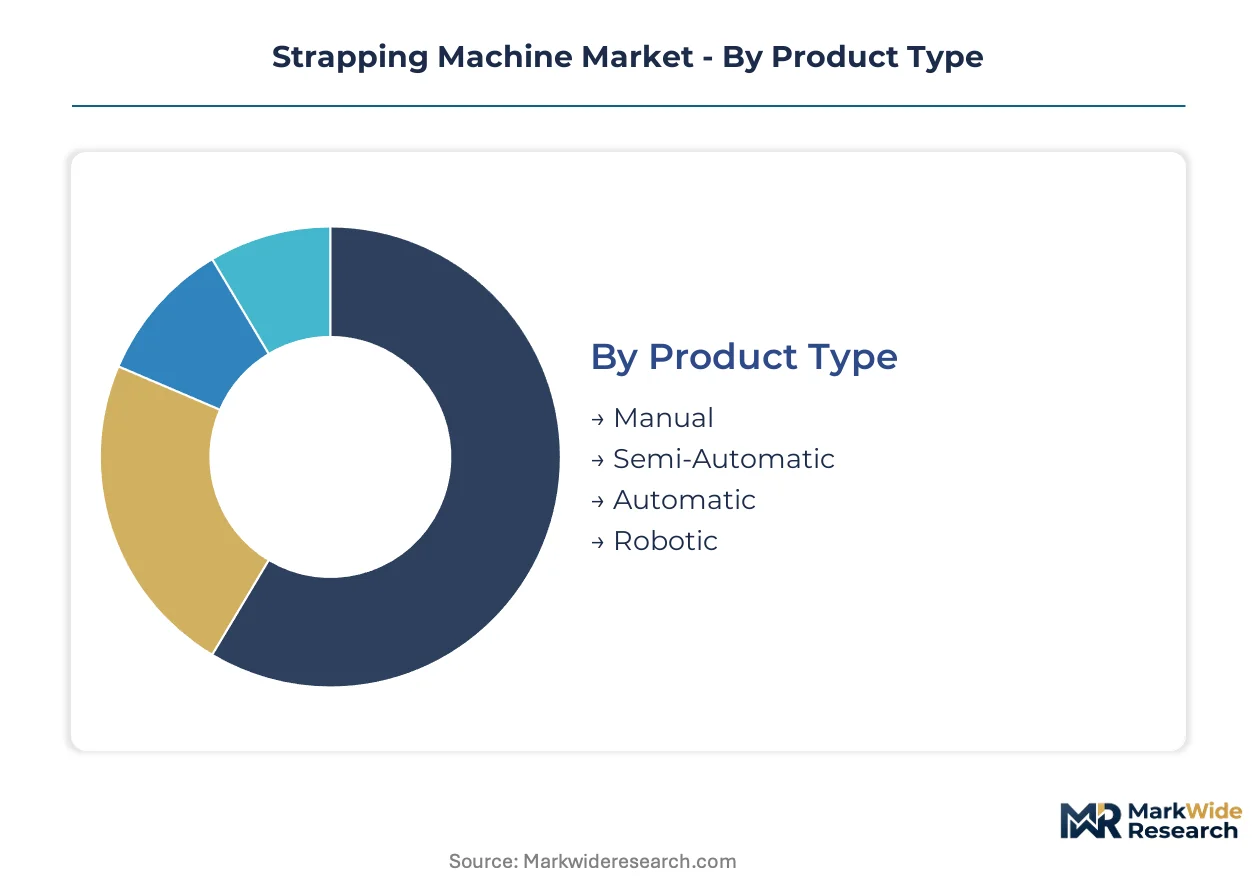
Strapping machine segmentation reveals divergent service intensity requirements across automation tiers, with robotic systems demanding predictive maintenance contracts while manual units rely on minimal parts replacement. Material composition and sealing technology further stratify aftermarket revenue potential and regulatory compliance burdens for equipment suppliers.
Product Type:
After-sales service intensity varies dramatically across automation levels, with robotic installations requiring continuous calibration support and semi-automatic units generating break-fix revenue only.
- Automatic:Programmable tension control achieves throughput exceeding 60 straps per minute for fragile electronics handling. E-commerce fulfillment centers in Germany and the Netherlands concentrate procurement for high-volume carton sealing with uptime guarantee contracts.
- Robotic:Vision-guided collaborative arms adapt to variable pallet geometries without manual reprogramming. Beverage distribution centers facing labor scarcity pull these systems into active deployment with per-strap maintenance agreements.
- Manual:Operator-tensioned banding suits low-throughput warehouses with minimal capital budgets and no service infrastructure requirements.
- Semi-Automatic:Operator-assisted feeding balances speed and capital outlay for small-to-mid warehouses where legacy management system integration creates upgrade friction.
Semi-automatic units hold the largest share; momentum sits with robotic systems.
Material Type:
Material selection dictates sealing technology compatibility and regulatory compliance pathways, with recycled-content formulations commanding premium equipment specifications.
- Polyester:Recycled-content and phthalate-free formulations align with EPA and REACH specifications. Germany's Packaging Act mandates recyclable variants, accelerating equipment upgrades for extended producer responsibility compliance.
- Steel:Ferrous metal banding delivers maximum tensile strength for heavy industrial loads. Input cost volatility exposes buyers to margin compression and inventory valuation risk.
- Polypropylene:REACH regulations on phthalate plasticizers force reformulation across EU member states with ECHA notification validation requirements.
- Plastic:Generic polymer strapping serves cost-sensitive applications with limited regulatory scrutiny and baseline equipment specifications.
Polypropylene holds the largest installed base; polyester is climbing the fastest on regulatory tailwinds.
End User:
End-use verticals separate hygiene-critical applications requiring residue-free sealing from general logistics where speed dominates specification.
- Food & Beverage:Ultrasonic welding heads eliminate thermal residue contamination liability in food-grade packaging. Swiss and Dutch cold-chain distributors adopt these at replacement cycle pace.
- Electronics:Programmable tension control prevents damage to fragile components during high-speed automated strapping. Contract manufacturers in China and India drive specification.
- Pharmaceuticals:Cold-chain distributors require validated sealing integrity for temperature-sensitive shipments with full traceability documentation.
- Retail:General merchandise fulfillment tolerates standard heat-seal architectures with minimal customization and faster payback periods.
Food & beverage holds the largest share; electronics is gaining share fastest on automation intensity.
Technology:
Sealing technology roadmaps fragment across thermal residue sensitivity, energy consumption, and maintenance interval requirements.
- Ultrasonic:High-frequency vibration welding eliminates thermal residue in hygiene-critical environments. Pharmaceutical and food-grade adopters in Switzerland and the Netherlands compress maintenance intervals for legacy sealing suppliers.
- Heat Seal:Thermal bonding architectures face obsolescence pressure where contamination liability exists, though cost efficiency sustains deployment in general logistics.
- Friction Weld:Mechanical friction generates localized heat for joint formation with moderate energy consumption and standard maintenance schedules.
- Electric:All-electric actuation systems reduce pneumatic infrastructure dependency and align with facility decarbonization targets.
Heat seal holds the largest share; ultrasonic represents the fastest-growing trajectory on hygiene compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Packaging Act and extended producer responsibility frameworks are reshaping equipment procurement priorities across developed markets. Regulatory chemistry restrictions in the European Union and EPA specifications in North America are accelerating polyester strapping adoption. Manufacturing hub expansion in Asia-Pacific is concentrating automated packaging line demand in specific industrial corridors.
United States
E-commerce fulfillment centers in California and Texas are driving automatic strapping equipment procurement with uptime guarantee contracts. OSHA guarding and emergency-stop standards impose extended certification timelines for imported machinery. The Chicago-Milwaukee industrial corridor concentrates beverage distribution automation where labor scarcity pressures robotic system deployment.
Germany
The Packaging Act mandates recyclable polyester strapping for extended producer responsibility compliance, forcing equipment upgrades among export-oriented manufacturers. ECHA notification procedures under REACH regulate phthalate-free formulation validation. The Stuttgart industrial region anchors automotive component packaging lines requiring programmable tension control for fragile electronics handling.
China
Contract electronics manufacturers in the Yangtze River Delta and Pearl River Delta are automating packaging lines to match export quality specifications. MIIT industrial upgrading programs subsidize smart manufacturing equipment procurement. Shenzhen and Suzhou cluster high-throughput strapping installations serving consumer electronics OEMs with 60-plus straps per minute requirements.
India
Automotive and pharmaceutical contract manufacturers in Maharashtra and Gujarat are expanding automated packaging capacity for export market access. BIS certification requirements shape equipment import specifications and local assembly partnerships. The Pune-Nashik industrial belt concentrates first-mover adoption of semi-automatic units balancing capital constraints with throughput needs.
Netherlands
Pharmaceutical cold-chain distributors in Rotterdam and Amsterdam are replacing heat-seal architectures with residue-free sealing technologies. EU Green Deal alignment creates procurement preferences for circular-economy-certified equipment. The Randstad logistics corridor hosts third-party operators unbundling after-sales service into per-strap maintenance contracts with uptime guarantees.
Strapping Machine Market Key Industry Players
Channel-controlling players compete with product-specialist players across automation tiers, creating a bifurcated structure where scale-driven OEMs face regional service-density specialists. The vendor base separates into three archetypes: European manufacturing-footprint holders sustaining regional service networks, North American steel-strapping specialists exposed to ferrous input volatility, and in-house component producers controlling critical strapping head supply. Competitive moves concentrate on geographic footprint expansion through distribution partnerships and captive component production to reduce supply dependency.
Among European manufacturing-footprint holders, FROMM Packaging Systems and Mosca GmbH exemplify regional service-density strategies. Samuel Strapping Systems and Dynaric Inc. represent North American competitive positioning, with the former anchoring steel-strapping specialization and the latter exemplifying in-house production of control systems. StraPack Inc. and Signode Industrial Group LLC occupy positions across automation tiers, while Cyklop International, MJ Maillis Group, and Polychem Corporation sit within mid-scale specialist tiers serving specific material or regional segments.
| Leading Market Players |
|---|
| StraPack Inc. |
| FROMM Packaging Systems |
| Signode Industrial Group LLC |
| Samuel Strapping Systems |
| Cyklop International |
| Mosca GmbH |
| Dynaric Inc. |
| MJ Maillis Group |
| Polychem Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's Yangtze River Delta packaging machinery cluster is compressing export pricing while simultaneously pressuring European OEMs to defend premium positioning through certification bundling and localized service density investments.
Pricing Analysis
Certification level (ISO/CE/UL-grade) creates the primary spread between equipment tiers, with phthalate-free REACH-compliant systems commanding substantial premiums over baseline heat-seal architectures. Three-tier pricing structure across premium, standard, and economy levels reflects automation intensity, with robotic vision-guided systems at the apex and manual operator-tensioned units at the base. Cost compression in semi-automatic equipment is intensifying because contract manufacturers in India and Vietnam are localizing assembly partnerships to bypass import duties. Small-to-mid warehouses with legacy management system integration requirements exhibit highest price sensitivity, while pharmaceutical cold-chain distributors demonstrate lowest sensitivity due to contamination liability exposure.
Supply Chain Analysis
Export control regimes on precision motion control components and machine vision systems limit technology flows from Germany and Japan to Chinese equipment assemblers, creating sourcing friction for high-throughput programmable tension systems. Component manufacturing concentrates in Germany, China, and Japan, with strapping head production anchored in European captive facilities and control system assembly distributed across Shenzhen and Suzhou industrial parks. Steel input cost volatility and recycled-content polyester formulation shortages constitute primary supply chain risks. Distribution runs through OEM-direct channels for large fulfillment center deployments, while regional service partners handle aftermarket parts and calibration support for mid-sized logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from adhesive-free stretch-hood systems in beverage distribution, requiring defensive positioning around sealing integrity validation and total cost of ownership documentation.
For Market Incumbents: Insulate installed base relationships through predictive maintenance contract bundling and ultrasonic welding head upgrade programs that lock in spare parts revenue streams. Captive production of strapping heads and control systems reduces dependency exposure on precision component suppliers. FROMM Packaging Systems' European service density model offers a template for geographic footprint replication.
For New Entrants and Emerging Players: Pursue white-space penetration in India's Maharashtra and Gujarat pharmaceutical contract manufacturing corridors where BIS certification requirements have slowed established competitor entry. Semi-automatic equipment with operator-assisted feeding balances capital constraints against throughput needs in this underpenetrated segment. Partner with local assembly specialists to accelerate regulatory compliance timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because extended producer responsibility frameworks across EU member states and select US states are structurally expanding addressable equipment markets through mandated upgrade cycles. Acquisition targets should display captive component production capabilities or established per-strap maintenance contract books. Monitor ECHA notification volume for phthalate-free plasticizer alternatives as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strapping Head Production | Dynaric Inc.'s captive supply model eliminates single-source dependency risk for competitors. |
| Ultrasonic Welding Technology Licensing | Swiss and Dutch pharmaceutical distributors compress legacy heat-seal supplier maintenance revenue. |
| Per-Strap Maintenance Contract Rollout | Benelux third-party logistics operators displace break-fix service models with uptime guarantees. |
| REACH-Compliant Material Bundling | German OEMs accelerate customer compliance through pre-certified polyester strapping formulations. |
| Vision-Guided Robotics Partnership | Beverage distribution centers facing labor scarcity deploy adaptive pallet geometry systems. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, maintenance directors at e-commerce fulfillment centers, OEM procurement teams specifying automated packaging lines, and aftermarket service heads managing uptime guarantee contracts. Secondary validation drew from SEC filings of publicly traded packaging machinery OEMs, EU ECHA notification databases tracking phthalate-free formulation approvals, OSHA machinery guarding standard documentation, and customs trade data on strapping equipment imports. Bottom-up equipment unit forecasts triangulated against top-down manufacturing automation capex projections.
Calibration against historical replacement cycles and regulatory compliance deadlines anchored volume and value outputs across the analysis window. Segmentation dimensions modeled include automation tier, material composition, sealing technology, end-use vertical, and regional regulatory cluster. CAGRs derived from equipment procurement pipeline analysis and manufacturing hub expansion trajectories. Industry-specific inputs incorporated MIIT industrial upgrading subsidy disbursements and extended producer responsibility framework implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in capital expenditure cycles at contract electronics manufacturers or ferrous metal price volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology substitution rates. Material shifts in REACH phthalate restriction scope or OSHA guarding standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
Global Blister Packaging Machinery Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
CCL Laminating Machine Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Global Filling Machines Market
Packaging Machinery
Tissue Paper Embosser Machine Market
Packaging Machinery
Glazing Machine Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Vertical Bagging Machine Market
Packaging Machinery
Powder Auger Fillers Market