
 Asia-Pacific Pharmaceutical Packaging Machinery Market | 2026-2036
Asia-Pacific Pharmaceutical Packaging Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pharmaceutical Packaging Machinery Market Outlook
Biotech firms is expanding their share of machinery procurement as sterile injectable and biologics output rises across the region. ACG Worldwide anchors its position through deep specialization in capsule filling and blister packaging systems for emerging markets. Robert Bosch GmbH leverages integrated vision inspection and robotics to sustain technology leadership in high-speed lines. MULTIVAC Group differentiates through thermoforming expertise that extends into medical device packaging adjacent segments.
Asia-Pacific pharmaceutical packaging machinery encompasses equipment engineered to form, fill, seal, label, and cart drug products at speeds ranging from 50 to 600 units per minute with compliance to GMP and cGMP protocols. These systems integrate servo-driven motion control, HMI interfaces, and serialized data management to ensure product integrity, patient safety, and supply chain traceability from manufacturing through distribution. Blister machines occupy the largest installed base due to universal adoption for oral solid dose protection across tropical climates, while smart packaging systems represent the fastest-growing technology segment as IoT-enabled cold-chain monitoring becomes standard for temperature-sensitive biologics. Filling machines command premium margin pools where aseptic isolator technology and single-use fluid path systems reduce contamination risk in biologics production.
India's CDSCO mandates barcoding and serialization under its Drugs and Cosmetics Act amendments, compelling domestic manufacturers to upgrade legacy lines. China's NMPA enforces GMP Annex 1 revisions on sterile manufacturing, driving demand for isolator-based filling and robotic decontamination systems. Japan's PMDA maintains stringent validation protocols that favor suppliers with established local service networks. Stakeholders must weigh regulatory divergence against platform standardization strategies when configuring regional supply footprints.
Market Dynamics
Serialization mandates across India and China are forcing pharmaceutical manufacturers to retire mechanical cam-driven lines in favor of servo-controlled systems with integrated track-and-trace databases. This regulatory compression is accelerating capital deployment toward connected packaging infrastructure.
Growth Catalysts
- CDSCO Serialization Mandates:India's drug regulator now requires 2D barcoding on all active pharmaceutical ingredients and finished formulations, compelling domestic contract manufacturers to upgrade legacy blister and bottle packaging lines.
- Biologics Cold-Chain Expansion:Temperature-sensitive monoclonal antibody output is rising across South Korea and Singapore, driving demand for IoT-enabled smart packaging systems with real-time monitoring capabilities.
- Isolator Technology:China's NMPA enforcement of revised GMP Annex 1 standards is electrifying procurement of restricted access barrier systems for aseptic filling operations.
Market Restraints
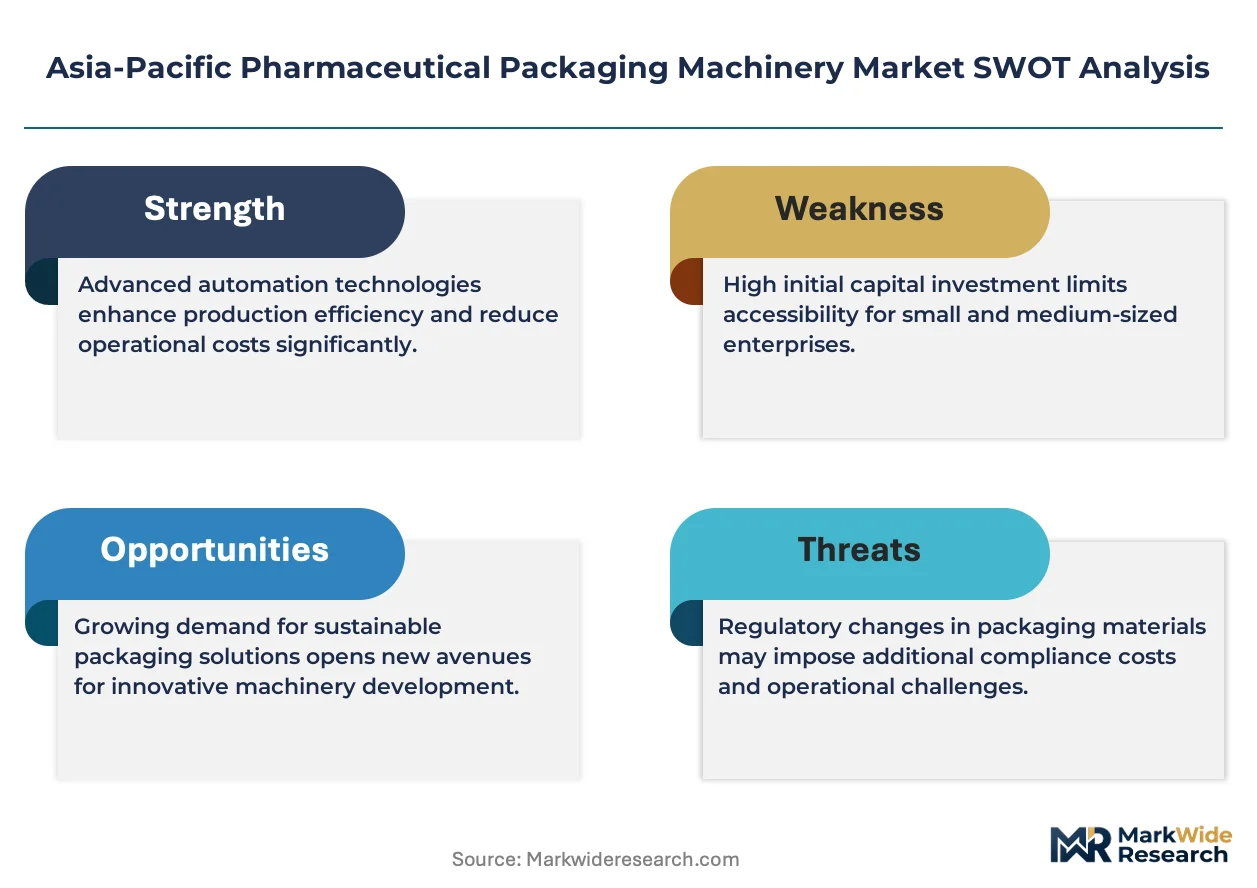
- Stainless Steel Input Volatility:Grade 316L stainless steel price swings compress margin predictability for machinery fabricators serving mid-tier Indian pharmaceutical exporters.
- German Component Concentration:Precision servo motors and vision sensors remain concentrated among Bavarian and Baden-Württemberg suppliers, exposing Asia-Pacific OEMs to euro-denominated cost pressure and extended lead times.
- Validation Timeline Friction:Japan's PMDA maintains 18-24 month qualification protocols for novel robotic decontamination systems, delaying revenue recognition for equipment vendors.
Strategic Opportunities
- Vietnam Contract Manufacturing:Underpenetrated compared to India and China, Vietnam's emerging pharmaceutical parks offer first-mover positioning for modular packaging lines with rapid format changeover.
- Cell and Gene Therapy Packaging:Cryogenic vial filling and ultra-low temperature secondary packaging represent adjacent white space as Singapore and Australia expand biologics manufacturing.
- PLI Scheme Tailwind:India's production-linked incentive scheme for pharmaceutical manufacturing is channeling capital toward domestic machinery procurement with local content requirements.
Industry Challenges
- Servo Programming Expertise Gap:Regional system integrators face acute shortages of engineers capable of configuring multi-axis motion control for synchronized filling and sealing operations.
- Legacy Line Integration Complexity:Brownfield pharmaceutical facilities struggle to graft serialization databases and vision inspection modules onto 1990s-era mechanical packaging equipment without full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pharmaceutical Packaging Machinery Market |
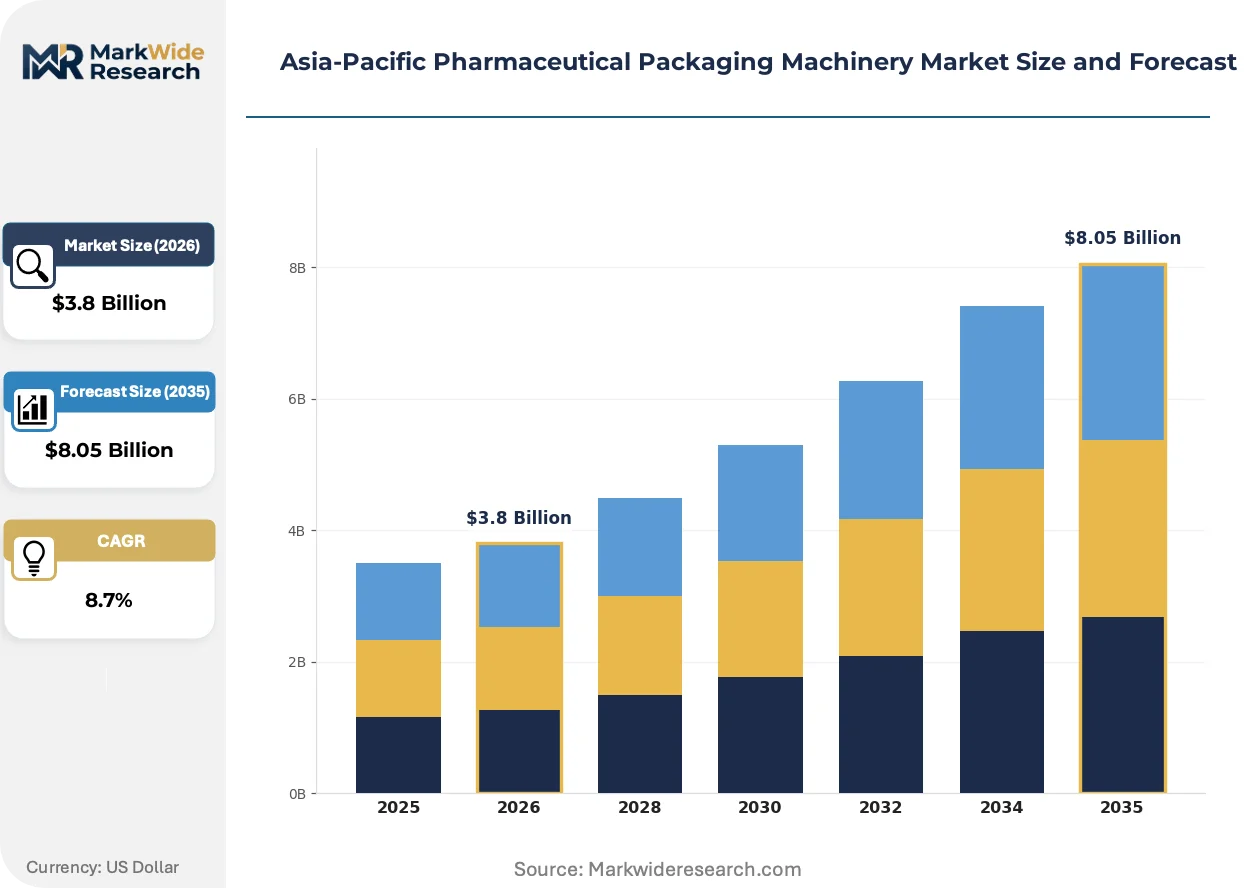
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Machines, Labeling Machines, Filling Machines, Cartoning Machines Technology: Automated, Semi-Automated, Manual, Smart Packaging End User: Pharmaceutical Companies, Contract Manufacturers, CMO, Biotech Firms Packaging Type: Primary Packaging, Secondary Packaging, Tertiary Packaging, Tamper-Evident Packaging |
| Companies Covered | Marchesini Group S.p.A., MULTIVAC Group, Robert Bosch GmbH, Uhlmann Group, Körber AG, Romaco Pharmatechnik GmbH, I.M.A Industria Macchine Automatiche S.p.A, ACG Worldwide, Optima Packaging Group GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pharmaceutical Packaging Machinery Market Strategic Shifts
Digital thread integration is collapsing the boundary between packaging execution and enterprise resource planning, enabling real-time quality release and automated regulatory submission. This connectivity shift is redefining machinery specification criteria across the region.
Electrified servo architectures are displacing pneumatic and mechanical cam systems across high-speed blister and carton packaging lines. Korean biopharma manufacturers are specifying all-electric motion platforms for cleanroom environments to eliminate compressed air contamination risk. This transition is electrifying demand for precision torque motors and linear drive technologies that enable format changeover without tool replacement.
China's NMPA has aligned its GMP Annex 1 implementation with EU and PIC/S standards, mandating continuous viable particle monitoring in Grade A filling zones. This harmonization is compressing validation documentation cycles for multinational machinery suppliers while elevating entry barriers for domestic Chinese equipment makers lacking international certification experience. Aseptic isolator systems face the steepest compliance burden under these revisions.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-tier Indian generic manufacturers. Monthly subscription arrangements covering maintenance, spare parts, and regulatory software updates are reducing upfront cash requirements while locking in long-term supplier relationships. This financing innovation is most visible in Mumbai and Hyderabad contract manufacturing clusters where working capital efficiency determines competitive tender outcomes.
Asia-Pacific Pharmaceutical Packaging Machinery Market Segmentation
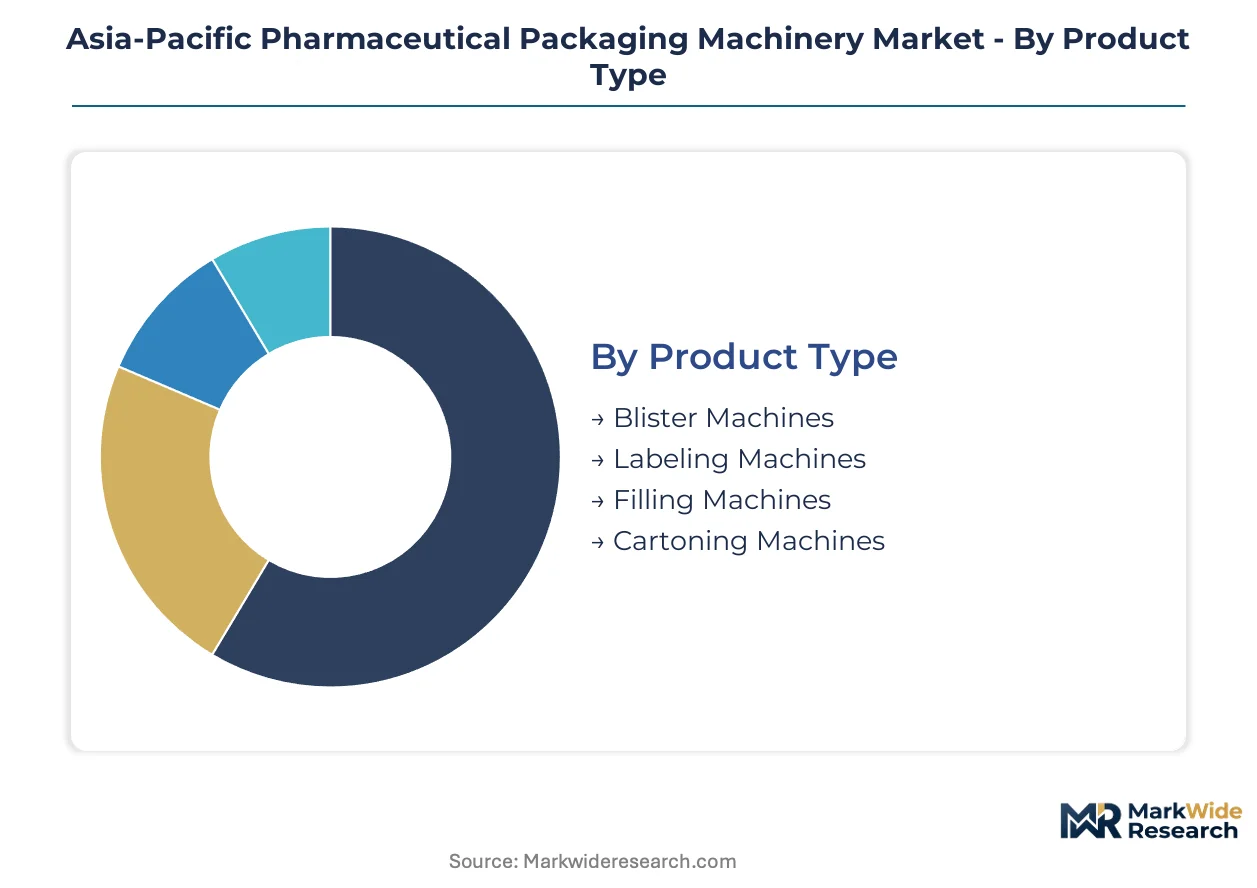
Packaging machinery segmentation across Asia-Pacific reflects divergent regulatory pressures and manufacturing scale. Equipment specifications vary sharply between high-volume generic producers and sterile biologics facilities.
Product Type:
Supply concentration for fabricated frames and servo drives shapes procurement patterns across equipment categories.
- Blister Machines:Thermoforming and cold-forming systems protect oral solid doses from tropical humidity. Demand concentrates in India's contract manufacturing clusters around Hyderabad and Ahmedabad, where CDSCO serialization mandates force continuous line upgrades.
- Filling Machines:Aseptic liquid and powder dosing systems integrate isolator barriers and single-use fluid paths. China's NMPA GMP Annex 1 enforcement is electrifying procurement of restricted access barrier systems for biologics production in Suzhou and Shanghai biopharma parks.
- Labeling Machines:Wrap-around and booklet applicators with vision verification for 2D barcode compliance.
- Cartoning Machines:Horizontal and vertical case packers with leaflet insertion for patient information.
Blister machines absorb the bulk of installed capacity; filling machines are expanding most quickly.
Technology:
Automation intensity correlates directly with labor cost trajectories and contamination control requirements.
- Automated:Servo-driven motion platforms with HMI interfaces and serialized data management execute 50-600 units per minute. Korean biopharma manufacturers specify all-electric architectures for cleanroom environments to eliminate compressed air contamination risk.
- Smart Packaging:IoT-enabled systems with real-time cold-chain monitoring and blockchain traceability. Temperature-sensitive monoclonal antibody output across South Korea and Singapore drives adoption for biologics distribution security.
- Semi-Automated:Operator-assisted systems with manual loading and automated sealing for mid-scale batches.
- Manual:Benchtop units for clinical trial packaging and orphan drug production.
Automated systems dominate capital deployment; smart packaging is gaining share fastest.
End User:
Customer scale determines equipment financing structures and service contract terms.
- Contract Manufacturers:Multi-client facilities require rapid format changeover and validated cleaning protocols. Mumbai and Hyderabad clusters are shifting toward equipment-as-a-service subscriptions to preserve working capital for competitive tendering.
- Biotech Firms:Emerging innovators prioritize isolator-based filling and robotic decontamination for sterile injectables. Singapore and Australia's cell and gene therapy expansion creates demand for cryogenic vial handling systems.
- Pharmaceutical Companies:Integrated manufacturers with captive packaging operations and legacy line estates.
- CMO:Dedicated contract manufacturing organizations with long-term client agreements and dedicated lines.
Contract manufacturers represent the largest installed base; biotech firms show the steepest expansion trajectory.
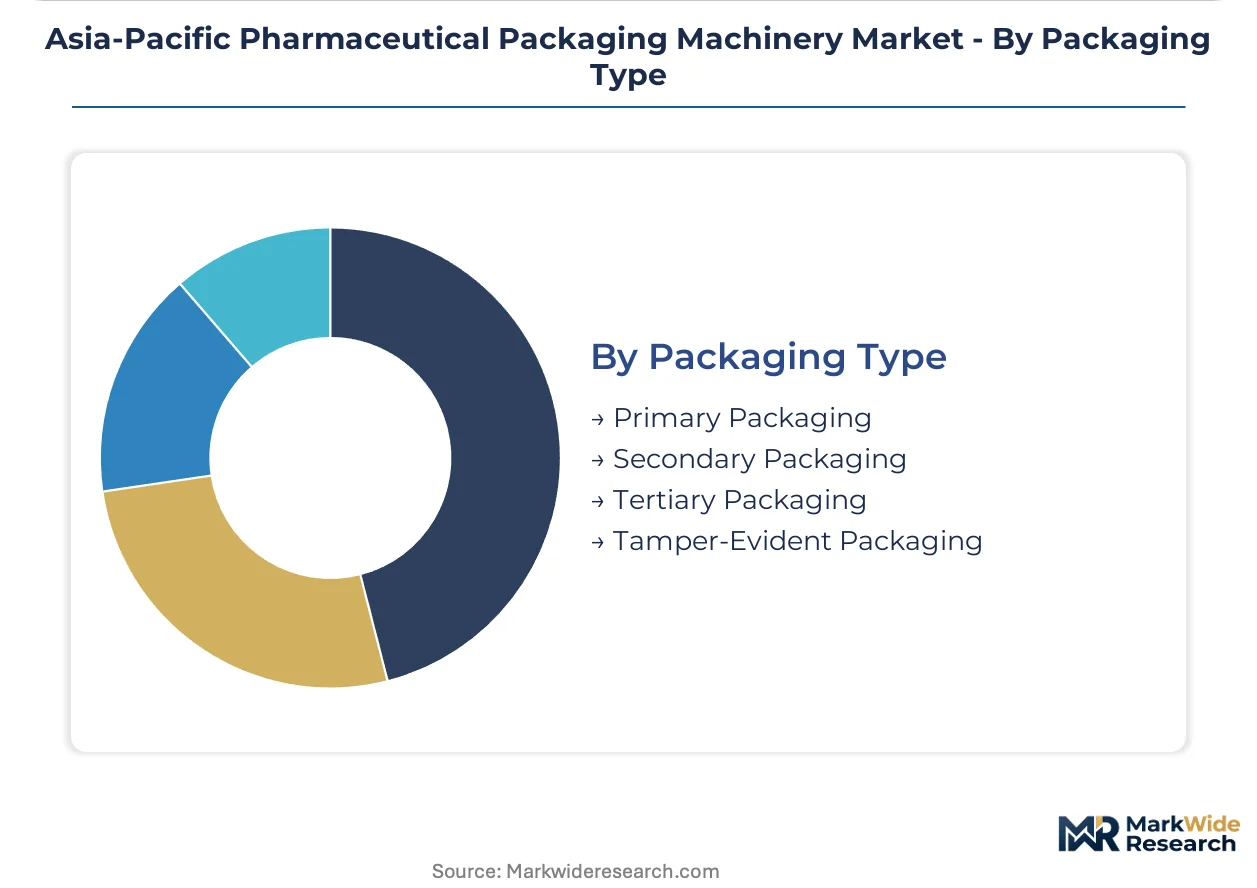
Packaging Type:
Regulatory validation burden increases with each packaging hierarchy level.
- Primary Packaging:Direct drug-contact layers including blisters, vials, and prefilled syringes. Grade 316L stainless steel volatility compresses margin predictability for fabricators serving mid-tier Indian exporters.
- Secondary Packaging:Cartons, labels, and leaflets with serialization aggregation. Japan's PMDA maintains 18-24 month qualification protocols for novel robotic decontamination systems, delaying vendor revenue recognition.
- Tertiary Packaging:Shippers and pallets for distribution with temperature monitoring.
- Tamper-Evident Packaging:Seals and indicators for patient safety and anti-counterfeiting.
Primary packaging commands premium margin pools; secondary packaging faces the steepest compliance burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones in Telangana and Gujarat concentrate machinery procurement as contract manufacturers scale sterile injectable capacity. CDSCO serialization mandates and China's NMPA GMP Annex 1 enforcement are redirecting capital toward integrated track-and-trace and isolator-based filling systems across the region.
China
Suzhou and Shanghai biopharma parks drive isolator-based filling demand as NMPA enforces revised GMP Annex 1 standards on sterile manufacturing. The regulator's alignment with EU and PIC/S protocols compresses validation timelines for multinational machinery suppliers. Yangtze River Delta clusters are electrifying procurement of restricted access barrier systems and robotic decontamination equipment.
India
Hyderabad and Ahmedabad contract manufacturing clusters absorb the bulk of blister machine upgrades as CDSCO mandates 2D barcoding under Drugs and Cosmetics Act amendments. The PLI scheme for pharmaceutical manufacturing channels capital toward domestic machinery procurement with local content requirements. Mumbai generic producers are shifting toward equipment-as-a-service subscriptions to preserve working capital.
Japan
Kanto and Kansai pharmaceutical corridors sustain demand for validated high-speed lines as PMDA maintains 18-24 month qualification protocols for novel robotic systems. The regulator's stringent validation requirements favor suppliers with established local service networks. Osaka biologics facilities prioritize servo-driven motion platforms with documented cleanroom compliance.
South Korea
Seoul Capital Area biopharma manufacturers specify all-electric motion architectures to eliminate compressed air contamination risk in monoclonal antibody production. MFDS oversight of temperature-sensitive biologics distribution drives IoT-enabled smart packaging adoption. Busan-Ulsan clusters are expanding cryogenic vial handling capacity for cell and gene therapy packaging.
Vietnam
Emerging pharmaceutical parks around Ho Chi Minh City and Hanoi offer first-mover positioning for modular packaging lines with rapid format changeover capabilities. The country's national pharmaceutical regulator is harmonizing GMP standards with ASEAN guidelines. Northern industrial zones are attracting Indian and Korean contract manufacturers seeking lower-cost sterile manufacturing alternatives.
Asia-Pacific Pharmaceutical Packaging Machinery Market Competitive Environment
Top-tier vendors anchor premium-tier positioning with integrated vision inspection and robotics, while mid-tier fabricators compete on format flexibility and regional service density. The vendor base stratifies across three tiers: European multinationals with full-line integration capability, Asia-Pacific specialists in thermoforming and capsule filling, and emerging domestic players capturing PLI-linked procurement. Dominant competitive moves include strategic partnerships for local assembly rights and portfolio diversification into medical device packaging adjacent segments.
Within the European multinational tier, Robert Bosch GmbH and MULTIVAC Group represent archetypes of technology leadership through integrated automation and thermoforming expertise respectively. ACG Worldwide occupies a position as the dominant India-based specialist in capsule filling and blister packaging systems for emerging markets. Among German fabricators, Uhlmann Group and Körber AG exemplify consolidated engineering conglomerates with breadth across pharmaceutical and healthcare packaging verticals.
| Leading Market Players |
|---|
| Marchesini Group S.p.A. |
| MULTIVAC Group |
| Robert Bosch GmbH |
| Uhlmann Group |
| Körber AG |
| Romaco Pharmatechnik GmbH |
| I.M.A Industria Macchine Automatiche S.p.A |
| ACG Worldwide |
| Optima Packaging Group GmbH |
| Others |
Value Chain & Pricing Dynamics
Precision servo programming expertise scarcity in South Korea and Japan widens labor-cost differentials across the Asia-Pacific pharmaceutical packaging machinery market, stretching pricing-tier spreads between premium isolator-integrated systems and economy-grade mechanical lines.
Pricing Analysis
Lead-time premiums command substantial price spreads in the Asia-Pacific pharmaceutical packaging machinery market, with German-sourced servo motors and vision sensors carrying 12-16 week delivery windows that inflate contract values. Three-tier pricing structure across premium, standard, and economy levels segments buyers by validation burden and automation intensity, with CDSCO-mandated serialization compliance and NMPA GMP Annex 1 certification as the primary differentiation drivers. Pricing pressure stems from stainless steel input volatility compressing fabricator margins, particularly for mid-tier Indian exporters serving generic pharmaceutical markets. Contract manufacturers in Mumbai and Hyderabad exhibit acute price sensitivity, favoring equipment-as-a-service subscriptions over capital purchases, while biotech firms in Singapore and Seoul prioritize validated isolator technology with lower elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Bavarian and Baden-Württemberg suppliers of precision servo motors and vision sensors, exposing Asia-Pacific OEMs to euro-denominated cost pressure and extended procurement cycles. Geographic supply concentration centers on Germany for motion control components, Japan for precision bearings and cleanroom-rated drive systems, and China for fabricated stainless steel frames and electrical enclosures. Raw material dependencies rest on Grade 316L stainless steel, rare-earth magnets for torque motors, and specialized optical glass for vision inspection modules. Supply chain risk hinges on regulatory restriction exposure as Japan's PMDA maintains stringent 18-24 month validation protocols that delay revenue recognition and strain working capital. Distribution runs through authorized regional service networks with local assembly partnerships, particularly in India's pharmaceutical special economic zones and China's Yangtze River Delta biopharma clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around certified servo programming engineers and validated isolator technology are propping pricing power for incumbent vendors across the Asia-Pacific pharmaceutical packaging machinery market.
For Market Incumbents: Cement technology leadership by deepening captive production of motion control components to offset German supplier concentration, and expand certified service engineer training programs in Hyderabad and Suzhou to capture PLI-linked domestic procurement. The threat of emerging Korean and Chinese equipment makers with government-backed certification fast-tracks demands accelerated local content integration. Isolator technology R&D represents the critical defensive lever against modular competitors. For New Entrants and Emerging Players: The price-point gap between premium European isolator systems and economy-grade Indian fabrications creates entry space for mid-tier automated lines with rapid format changeover targeting Vietnam's underpenetrated pharmaceutical parks. White-space targets include cryogenic vial handling for Singapore's cell and gene therapy expansion and equipment-as-a-service financing for working-capital-constrained Mumbai generic producers. A partnership-based go-to-market angle with established regional system integrators accelerates validation credibility. For Investors and Strategic Acquirers: Re-rating potential sits with Asia-Pacific specialists possessing thermoforming expertise and established CDSCO validation track records given India's serialization mandate enforcement accelerating replacement cycles. Long-term viability over the next decade favors vendors with demonstrated NMPA GMP Annex 1 compliance and local assembly rights in China. The signal to watch as inflection indicator is MFDS adoption of EU-aligned sterile manufacturing standards expanding isolator demand in South Korea.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | Secures PLI scheme eligibility in India while reducing euro-denominated component exposure. |
| Isolator Technology Certification | Unlocks NMPA GMP Annex 1 compliance for China's Suzhou and Shanghai biopharma parks. |
| Equipment-as-a-Service Launch | Captures working-capital-constrained contract manufacturers in Mumbai and Hyderabad clusters. |
| Servo Programming Academy | Addresses regional engineer scarcity constraining multi-axis motion control deployment. |
| Cryogenic Handling Development | Positions for Singapore and Australia cell and gene therapy packaging expansion. |
Study Parameters
Multi-period observation of CDSCO serialization compliance timelines, NMPA GMP Annex 1 enforcement patterns, and biologics capacity buildouts anchored the trend analysis, supplemented by interviews with packaging machinery procurement directors, regulatory affairs leads at contract manufacturers, plant engineers at biopharma facilities, and aftermarket service heads. Secondary validation drew from FDA warning letter databases, NMPA regulatory filings, MFDS biologics approval records, and trade customs data for pharmaceutical machinery imports. Bottom-up equipment shipment tracking and top-down pharmaceutical manufacturing investment flows were triangulated to establish market sizing.
Input-output matrices mapped machinery unit demand against biologics production capacity, serialization mandate phase-in schedules, and sterile manufacturing regulatory enforcement intensity across the projection horizon. Segmentation dimensions modeled included equipment type, automation tier, end-user archetype, and packaging hierarchy level, with regional regulatory cluster as the industry-specific overlay. CAGRs were derived from regression analysis of historical capital expenditure patterns against forward-looking biopharma facility announcements, incorporating isolator technology penetration curves and smart packaging adoption rates as pharmaceutical-specific forecast inputs.
Underlying measurement precision varies by segment; automated and smart packaging systems carry tighter precision than manual and semi-automated categories due to more visible procurement pipelines. Forecasts reflect assumptions around regulatory enforcement continuity, stainless steel price stability, and German component supply availability, with tariff escalation or validation protocol extensions as primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Powder Packing Machine Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
Flow Wrap Machines Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Thermal Laminating Machine Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Emboss Coding Machine Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Tray Former Machines Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Automatic Auger Fillers Market