
 Aseptic Filling Machines Market | 2026-2036
Aseptic Filling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Aseptic Filling Machines Market Outlook
Stainless steel contact surfaces are ceding ground to single-use polymer assemblies in biopharma filling lines, a substitution that is realigning capital expenditure patterns toward disposable-ready machine architectures. Krones AG leverages its integrated blow-fill-seal platform to dominate high-speed dairy and beverage installations across European bottling corridors. Syntegon sustains technology leadership in isolator-based pharmaceutical systems through intensive R&D spending on robotic decontamination interfaces. GEA Group anchors its competitive position with modular skid designs that reduce cleanroom footprint and accelerate biotech client validation timelines.
An aseptic filling machine is a closed-system packaging apparatus engineered to transfer sterile product into pre-sterilized containers within an ISO 5 classified environment, typically employing HEPA-filtered unidirectional airflow, automated vial handling, and in-line integrity testing at fill speeds exceeding 400 units per minute. Its primary purpose is to eliminate microbial contamination risk during the final manufacturing stage of parenteral drugs, liquid nutritionals, and shelf-stable beverages. Liquid Filling systems command the largest installed base due to universal applicability across intravenous solutions and ready-to-drink formulations, though Vial Filling architectures are capturing disproportionate investment as monoclonal antibody pipelines expand. Pharmaceutical end users represent the most margin-rich demand pool, with isolator-integrated lines carrying pricing premiums of roughly forty percent over conventional restricted access barrier systems.
FDA guidance on sterile drug products produced by aseptic processing and EU GMP Annex 1 mandates for contamination control strategy documentation are compelling manufacturers to retrofit legacy lines or procure new equipment with enhanced environmental monitoring and closed-system design. The WHO's updated good manufacturing practices for sterile pharmaceutical products further tightens international baseline expectations for particulate and bioburden control. Stakeholders must weigh total cost of ownership against speed-to-market advantages as regulatory divergence between FDA isolator standards and EMA barrier system interpretations complicates unified platform strategies across Atlantic supply chains.
Market Dynamics
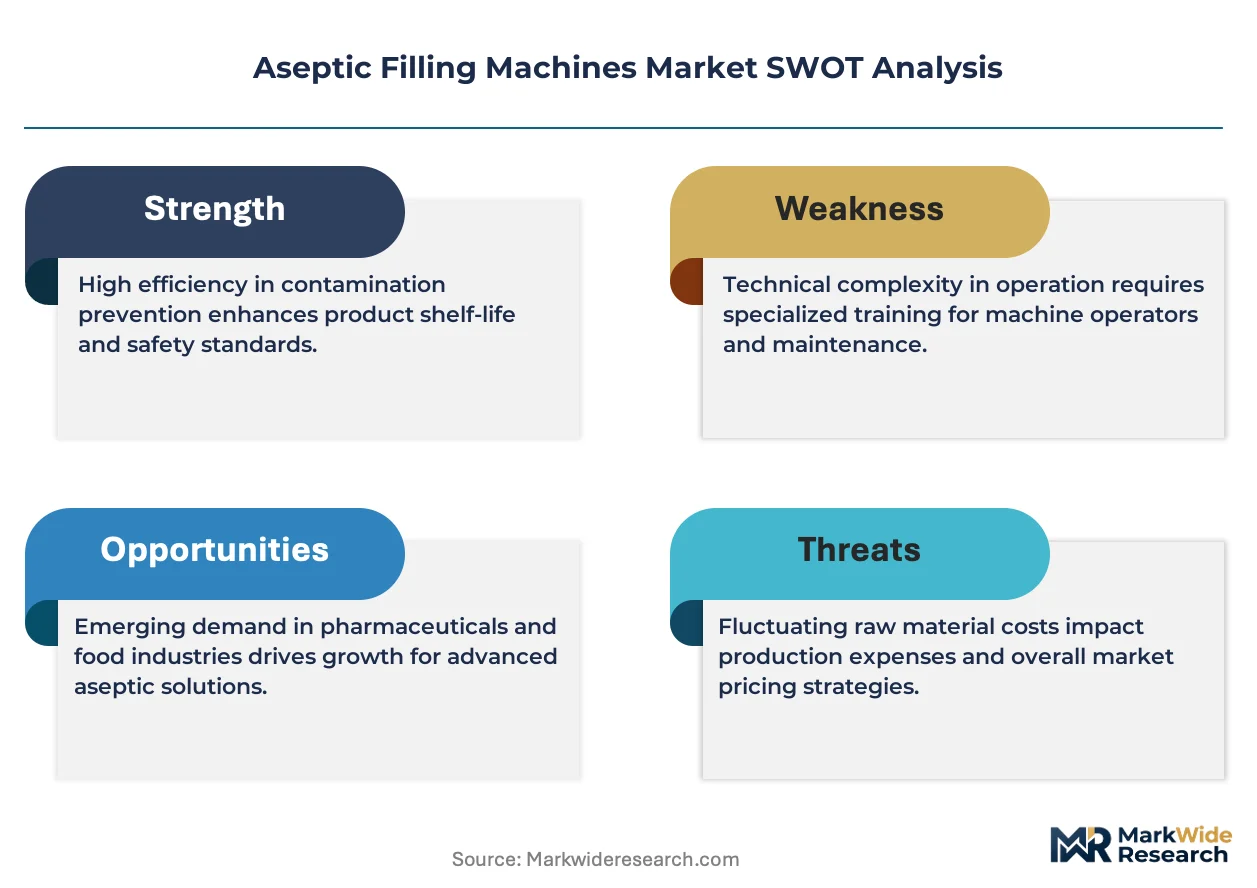
Single-use polymer assemblies are displacing stainless steel contact surfaces across biopharma filling lines, forcing capital expenditure reallocation toward disposable-ready machine architectures and compressing traditional equipment replacement cycles.
Growth Catalysts
- EU GMP Annex 1 revisions:Mandates for contamination control strategy documentation compel pharmaceutical manufacturers to retrofit legacy lines or procure isolator-integrated systems with enhanced environmental monitoring capabilities.
- Monoclonal antibody pipeline expansion:Biologics manufacturing is driving disproportionate investment into vial filling architectures capable of handling high-value, low-volume parenteral drugs with precision dosing requirements.
- German packaging technology clusters:Concentrated engineering expertise around Stuttgart and Karlsruhe accelerates client validation timelines and reduces equipment commissioning periods for European biotech firms.
Market Restraints
- High-purity polymer supply concentration:Specialized fluoropolymer and platinum-cured silicone tubing production concentrates among a limited supplier base, exposing filling line OEMs to input cost volatility and extended lead times.
- Cleanroom infrastructure requirements:ISO 5 classified environments demand substantial facility investment, restricting market entry for mid-tier pharmaceutical manufacturers in emerging markets.
- Regulatory divergence between FDA isolator standards and EMA barrier interpretations:Atlantic supply chains face compliance complexity that complicates unified platform strategies and extends validation timelines.
Strategic Opportunities
- India's biopharma manufacturing expansion:CDSCO's alignment with international GMP standards and production-linked incentive schemes create openings for modular skid designs that reduce cleanroom footprint.
- Cell and gene therapy manufacturing:Personalized medicine workflows require flexible, small-batch filling systems with rapid changeover capabilities that legacy high-speed lines cannot accommodate.
- WHO GMP guideline harmonization:Updated sterile pharmaceutical product standards in developing markets elevate baseline expectations and drive replacement demand for non-compliant legacy equipment.
Industry Challenges
- Validation engineer scarcity:Specialized expertise in isolator-based system qualification and continuous process verification remains concentrated among experienced practitioners, extending project timelines.
- Legacy system integration complexity:Retrofitting robotic decontamination interfaces into existing restricted access barrier configurations demands extensive mechanical and software adaptation.
- Equipment qualification documentation burden:FDA guidance on sterile drug products produced by aseptic processing requires exhaustive contamination control strategy files that strain quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aseptic Filling Machines Market |
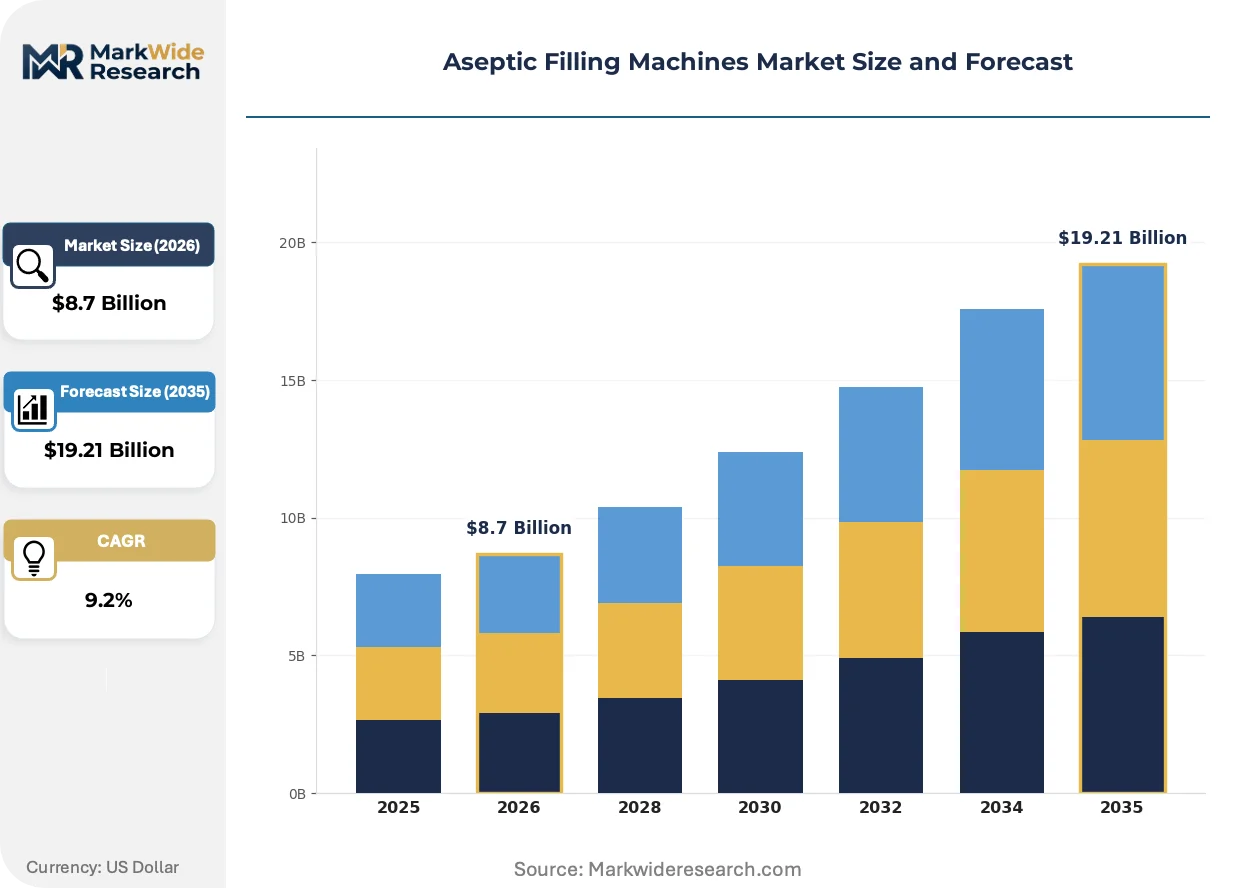
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Filling, Powder Filling, Vial Filling, Ampoule Filling End User: Pharmaceutical, Biotechnology, Food & Beverage, Cosmetics Technology: Ultra High Temperature, Sterilization, Microfiltration, Hot Fill Application: Vaccines, Dairy Products, Nutraceuticals, Sauces |
| Companies Covered | KHS GmbH, Syntegon, Tetra Pak, Ronchi Mario S.p.A., Scholle IPN, Krones AG, GEA Group, Accutek Packaging Equipment, Sidel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aseptic Filling Machines Market Strategic Shifts
Automation architectures are converging with closed-system design principles to eliminate human intervention points, while regulatory pressure intensifies around environmental monitoring and data integrity. Equipment vendors must now engineer for both speed and demonstrable sterility assurance.
Isolator-based robotic decontamination interfaces are integrating hydrogen peroxide vapor sterilization cycles with automated vial handling to achieve six-log microbial reduction without human access. Biologics contract manufacturers in Switzerland and Massachusetts are deploying these systems for high-potency compound containment. This convergence is integrating sterility assurance with occupational exposure limits, compressing the traditional trade-off between operator safety and production throughput.
EMA's updated interpretation of barrier system classifications under EU GMP Annex 1 is forcing pharmaceutical manufacturers to requalify existing installations against stricter airborne particulate and viable monitoring thresholds. German and French regulators are conducting unannounced inspections focused on continuous viable particle detection. Small-molecule injectable producers in Southern Europe are responding by retrofitting legacy lines with real-time environmental monitoring suites rather than risking batch rejection.
Service unbundling is separating equipment hardware from validation support and consumable supply contracts. Large pharmaceutical buyers in the United States are negotiating multi-site framework agreements that standardize machine specifications while fragmenting aftermarket service among regional specialists. This procurement restructuring is most visible among generic injectable manufacturers seeking to reduce total cost of ownership without sacrificing regulatory defensibility.
Aseptic Filling Machines Market Segmentation
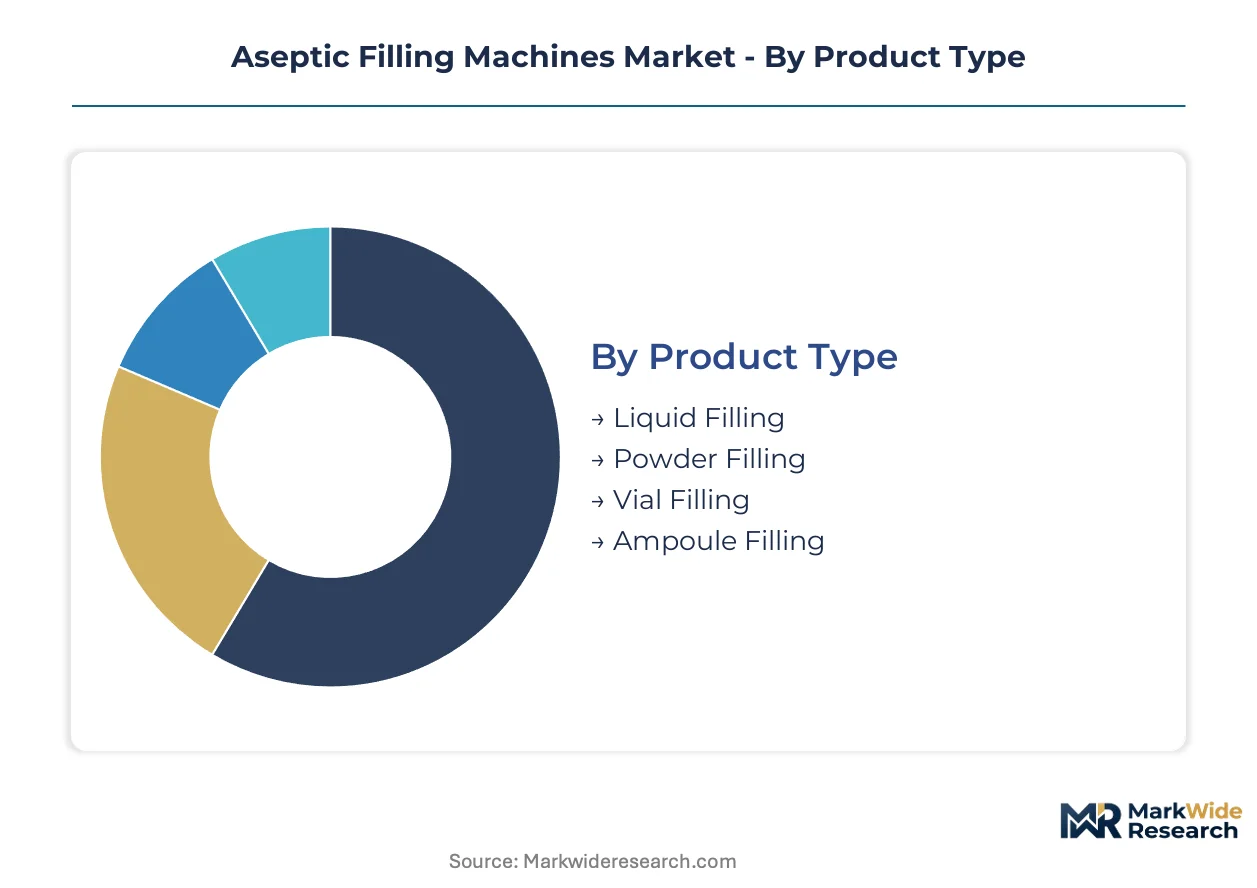
Segmentation in aseptic filling machines reflects divergent capital requirements, regulatory burdens, and operational constraints across pharmaceutical, food, and emerging therapeutic applications. Equipment specifications vary dramatically between high-speed dairy lines and isolator-integrated biologics systems.
Product Type:
Capital intensity escalates sharply with containment sophistication, as isolator-integrated architectures demand substantially higher upfront investment than open restricted-access configurations.
- Liquid Filling:Stainless steel pump assemblies and peristaltic dosing modules handle intravenous solutions, ophthalmic drops, and ready-to-drink beverages at throughputs exceeding 400 units per minute. Pharmaceutical manufacturers in Germany and Switzerland deploy these systems for large-volume parenteral production where batch sizes justify continuous operation economics.
- Vial Filling:Robotic handling interfaces and in-process checkweighing integrate with isolator enclosures to protect high-value monoclonal antibodies from environmental contamination. Massachusetts and Basel-area biologics contract manufacturers are expanding installed capacity here as pipeline molecules advance toward commercialization.
- Powder Filling:Auger-based dosing with containment isolators addresses antibiotic and lyophilized product requirements.
- Ampoule Filling:Specialized flame-sealing stations follow blow-fill-seal or form-fill-seal sequences for small-volume injectables.
Most installed capacity flows through Liquid Filling. Expansion is steepest in Vial Filling.
End User:
Margin profiles and validation timelines diverge substantially across customer categories, with pharmaceutical buyers accepting longer qualification periods in exchange for sterility assurance premiums.
- Pharmaceutical:Parenteral drug manufacturers operate under FDA and EMA sterile processing guidance, requiring isolator-integrated lines with continuous viable particle monitoring. German engineering clusters around Stuttgart supply these customers with modular skid designs that compress validation timelines.
- Biotechnology:Cell and gene therapy workflows demand flexible, small-batch systems with rapid changeover capabilities for personalized medicine applications. CDSCO-aligned manufacturers in India are procuring disposable-ready architectures to avoid stainless steel cleaning validation burdens.
- Food & Beverage:Extended shelf-life dairy and beverage producers prioritize throughput economics over containment sophistication.
- Cosmetics:Preservative-free skincare and ophthalmic cosmetic formulations require aseptic processing with lower regulatory stringency than pharmaceutical equivalents.
Pharmaceutical buyers command the highest equipment pricing. Biotechnology is expanding most quickly.
Technology:
Process selection determines energy consumption, thermal degradation risk, and compatibility with sensitive biological actives.
- Sterilization:Hydrogen peroxide vapor and moist heat sterilization cycles achieve six-log microbial reduction for isolator enclosures and product contact surfaces. Swiss and German vendors integrate these modules with robotic decontamination interfaces to eliminate human intervention.
- Ultra High Temperature:Flash heating to 135-150°C followed by aseptic cooling preserves liquid nutritional products without refrigeration. European dairy processors deploy these systems for ESL milk and extended-shelf-life beverage production.
- Microfiltration:Membrane-based sterile filtration removes microorganisms from heat-sensitive biologics without thermal degradation.
- Hot Fill:Elevated-temperature filling into pre-sterilized containers suits acidified sauces and certain beverage categories with lower sterility assurance requirements.
Sterilization technology carries the heaviest capital burden. Ultra High Temperature is climbing the fastest among food-sector adopters.
Application:
Demand concentration reflects epidemiological priorities, consumer health trends, and supply chain restructuring in perishable categories.
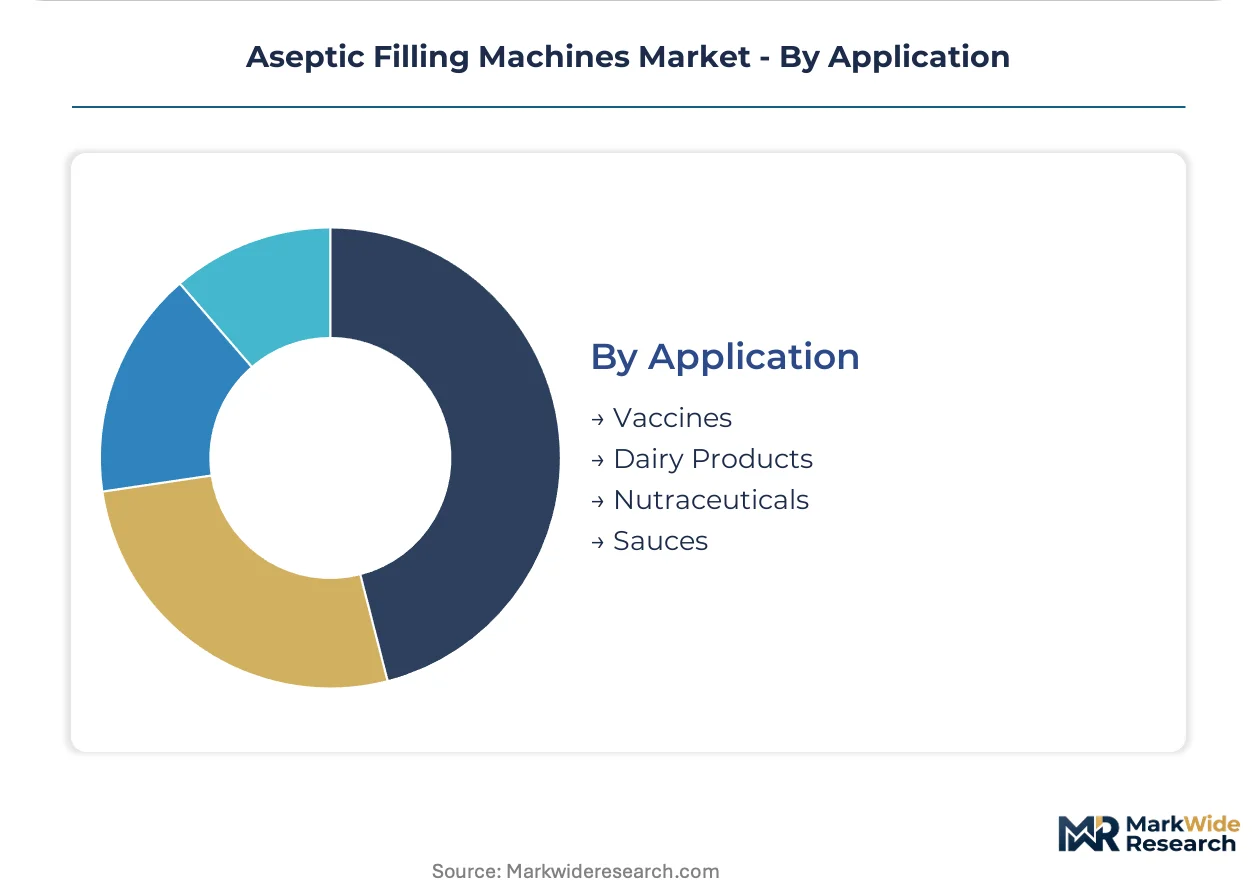
- Vaccines:Pandemic preparedness investments and routine immunization programs drive demand for high-speed vial and prefilled syringe filling with absolute contamination control. WHO GMP guideline harmonization in developing markets is accelerating replacement of legacy equipment.
- Dairy Products:ESL milk, drinkable yogurts, and liquid nutritionals require aseptic filling to enable ambient distribution. German and French processors are retrofitting lines with real-time environmental monitoring to satisfy unannounced EMA inspections.
- Nutraceuticals:Probiotic and functional beverage formulations demand gentle processing to preserve viable cultures.
- Sauces:Viscous product handling with clean-in-place systems addresses condiment and cooking sauce applications.
Vaccine applications command the most stringent specifications. Nutraceuticals are gaining share fastest as functional food categories expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's engineering corridor around Stuttgart anchors advanced aseptic filling technology development. German clusters supply isolator-integrated systems to biopharma manufacturers worldwide. Regional demand concentrates in pharmaceutical hubs across four continents.
Germany
Stuttgart and Karlsruhe host dense concentrations of packaging machinery engineering expertise. EU GMP Annex 1 revisions drive retrofit demand from domestic pharmaceutical manufacturers. KHS GmbH and Syntegon anchor technology clusters supplying isolator-based systems across European biotech corridors.
United States
Massachusetts and California biologics contract manufacturers expand vial filling capacity for monoclonal antibody commercialization. FDA guidance on sterile drug products produced by aseptic processing mandates enhanced environmental monitoring documentation. Greater Boston hosts specialized validation engineering talent pools that compress equipment commissioning timelines.
Switzerland
Basel-area biopharma manufacturing drives demand for high-containment isolator systems. Swissmedic maintains stringent sterility assurance standards that elevate equipment specifications. Swiss contract manufacturers deploy robotic decontamination interfaces for high-potency compound handling.
India
Maharashtra and Telangana biopharma clusters expand aseptic filling capacity for export markets. CDSCO alignment with international GMP standards and production-linked incentive schemes accelerate equipment procurement. Hyderabad-based manufacturers favor modular skid designs that reduce cleanroom footprint and validation burden.
China
Yangtze River Delta pharmaceutical manufacturers upgrade filling lines to meet NMPA sterile processing requirements. Domestic vaccine producers drive demand for high-speed vial and prefilled syringe systems. Shanghai-area engineering centers develop localized isolator platforms for regional biotech clients.
Aseptic Filling Machines Market Competitive Environment
Capacity expansion dominates the current landscape as pharmaceutical manufacturers retrofit legacy lines to meet tightened contamination control standards. The vendor base stratifies across three tiers: diversified industrial conglomerates with integrated packaging platforms, specialized pharmaceutical machinery pure-plays, and regional fabricators serving emerging market price points. German engineering clusters concentrate tier-one capabilities. Competitive positioning hinges on modular architecture design and validation support bundling.
Within the diversified industrial tier, Krones AG exemplifies integrated blow-fill-seal platform specialization, while GEA Group anchors modular skid design capabilities. Syntegon occupies a position among isolator-based pharmaceutical system specialists. These three represent divergent strategic archetypes: beverage-dominant integrated platforms, flexible biopharma modular systems, and high-containment pharmaceutical isolators. Geographic origin clusters visibly—German GmbH and AG structures concentrate tier-one engineering, while US-based Accutek Packaging Equipment and Italian S.p.A. structures populate specialized and regional tiers respectively.
| Leading Market Players |
|---|
| KHS GmbH |
| Syntegon |
| Tetra Pak |
| Ronchi Mario S.p.A. |
| Scholle IPN |
| Krones AG |
| GEA Group |
| Accutek Packaging Equipment |
| Sidel |
| Others |
Value Chain & Pricing Dynamics
Validation engineer scarcity in Greater Boston and Basel-area biotech corridors compresses commissioning timelines for isolator-integrated systems, widening labor-cost differentials between premium-tier German engineering and mid-market Indian fabrication by roughly thirty percent across equivalent machine specifications.
Pricing Analysis
Input-cost pass-through from specialized fluoropolymer and platinum-cured silicone tubing concentrates pricing power among tier-one German and Swiss OEMs. Three-tier pricing structure across isolator-integrated premium, restricted-access-barrier standard, and open-system economy levels separates pharmaceutical certification grades. Pricing pressure stems from CDSCO-aligned Indian manufacturers procuring modular skid designs at compressed capital expenditure points. Generic injectable producers exhibit highest price sensitivity; monoclonal antibody contract manufacturers accept forty percent premiums for sterility assurance documentation.
Supply Chain Analysis
Freight costs for precision-engineered isolator enclosures and HEPA filtration assemblies from Stuttgart and Karlsruhe engineering clusters to Massachusetts biologics corridors add seven to twelve percent to landed equipment costs. Manufacturing concentration centers on Germany, Switzerland, and China, with Yangtze River Delta facilities supplying localized platforms for domestic vaccine producers. Component sourcing draws from Italian pneumatic systems, Japanese servo motors, and US control software. Single-source vulnerability in high-purity polymer tubing exposes OEMs to extended lead times. Distribution runs through direct sales for pharmaceutical tier, regional agents for food and beverage segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU GMP Annex 1 retrofit demand in Western Europe and CDSCO-aligned greenfield capacity expansion in India, where production-linked incentive schemes offset validation documentation burdens.
For Market Incumbents: Lock in isolator-integrated system standards through intensive R&D spending on robotic decontamination interfaces before FDA-EMA regulatory divergence hardens into incompatible certification requirements. Deepen backward integration into high-purity polymer supply through captive sourcing agreements with limited fluoropolymer producers to mitigate input cost volatility threatening margin compression in standard-tier equipment. For New Entrants and Emerging Players: Begin with modular skid designs targeting Maharashtra and Telangana biopharma clusters seeking reduced cleanroom footprint and accelerated CDSCO validation timelines. Cell and gene therapy manufacturing workflows present the most penetrable white space, as legacy high-speed lines cannot accommodate small-batch flexibility requirements for personalized medicine applications. For Investors and Strategic Acquirers: Biologics contract manufacturers are the most active acquirer in this space, consolidating isolator-based filling capacity to capture monoclonal antibody commercialization pipelines. Long-term viability hinges on exposure to mRNA and cell therapy modality shifts rather than small-molecule injectable stagnation. Watch for unannounced EMA inspection intensity in Southern Europe as signal for retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Integrated Platform Development | EU GMP Annex 1 revisions mandate contamination control strategy documentation for pharmaceutical manufacturers. |
| Robotic Decontamination Interface R&D | Syntegon and Swiss contract manufacturers deploy hydrogen peroxide vapor sterilization cycles for six-log microbial reduction. |
| Modular Skid Design Localization | Hyderabad-based manufacturers reduce cleanroom footprint to satisfy CDSCO-aligned international GMP standards. |
| Single-Use Polymer Assembly Integration | Biopharma filling lines displace stainless steel contact surfaces to compress cleaning validation timelines. |
| Real-Time Environmental Monitoring Retrofit | German and French processors satisfy unannounced EMA inspections with continuous viable particle detection suites. |
Study Parameters
Bottom-up pharmaceutical and biotechnology end-use modeling reconciled against top-down packaging machinery OEM production tracking forms the analytical core of this study. Primary interviews with validation engineers, cleanroom facility managers, biologics manufacturing executives, and regulatory affairs specialists at FDA and EMA-inspected sites combined with secondary validation from FDA guidance documents, EU GMP Annex 1 revision drafts, CDSCO circulars, and WHO sterile pharmaceutical product standards. Trade data from German mechanical engineering associations and Swiss packaging machinery exports anchored supply-side triangulation against demand-side procurement patterns.
Historical trendline analysis of installed base replacement cycles and greenfield capacity announcements informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type containment sophistication, end-user regulatory stringency tier, sterilization technology thermal profile, and application sterility assurance level. CAGRs derived from equipment procurement pipeline visibility and contract manufacturer expansion announcements, with sensitivity analysis around monoclonal antibody pipeline advancement rates and vaccine pandemic preparedness funding continuity.
Caveats apply where FDA-EMA regulatory divergence on isolator versus barrier system interpretations, high-purity polymer supply concentration disruptions, or validation engineer scarcity extending commissioning timelines could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Corrugated Box Printer Slotter Machine Market
Packaging Machinery
Automated Poly Bagging Machines Market
Packaging Machinery
Pallet Stretch Wrapping Machines Market
Packaging Machinery
Aerosol Filling Machines Market
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
Cosmetic Packaging Machinery Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Thermal Laminating Machine Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Tray Packing Machine Market