
 Unresectable Hepatocellular Carcinoma Market | 2026-2036
Unresectable Hepatocellular Carcinoma Market Size, Share, and Industry Trends Forecast 2026-2036
Unresectable Hepatocellular Carcinoma Market Analytics
China is reconfiguring its hepatocellular carcinoma treatment infrastructure through expanded biologics manufacturing capacity and centralized procurement reforms. Bristol-Myers Squibb dominates the immuno-oncology segment with its checkpoint inhibitor portfolio. Merck & Co. leverages extensive clinical trial networks across Asia-Pacific to sustain pipeline momentum. Bayer AG anchors the targeted therapy landscape with established kinase inhibitor platforms.
Unresectable hepatocellular carcinoma constitutes advanced liver cancer that cannot be surgically removed due to tumor burden, vascular invasion, or insufficient hepatic reserve, typically managed through systemic pharmacotherapy rather than curative intervention. The condition demands agents capable of modulating angiogenic signaling and immune surveillance simultaneously, reflecting its molecular heterogeneity and propensity for intrahepatic dissemination. Combination therapy represents the fastest-expanding treatment type as clinicians sequence immunotherapy with targeted agents to overcome resistance mechanisms. The intravenous administration route commands premium positioning due to infusion center economics and payer bundling structures, while oral regimens occupy cost-sensitive channels.
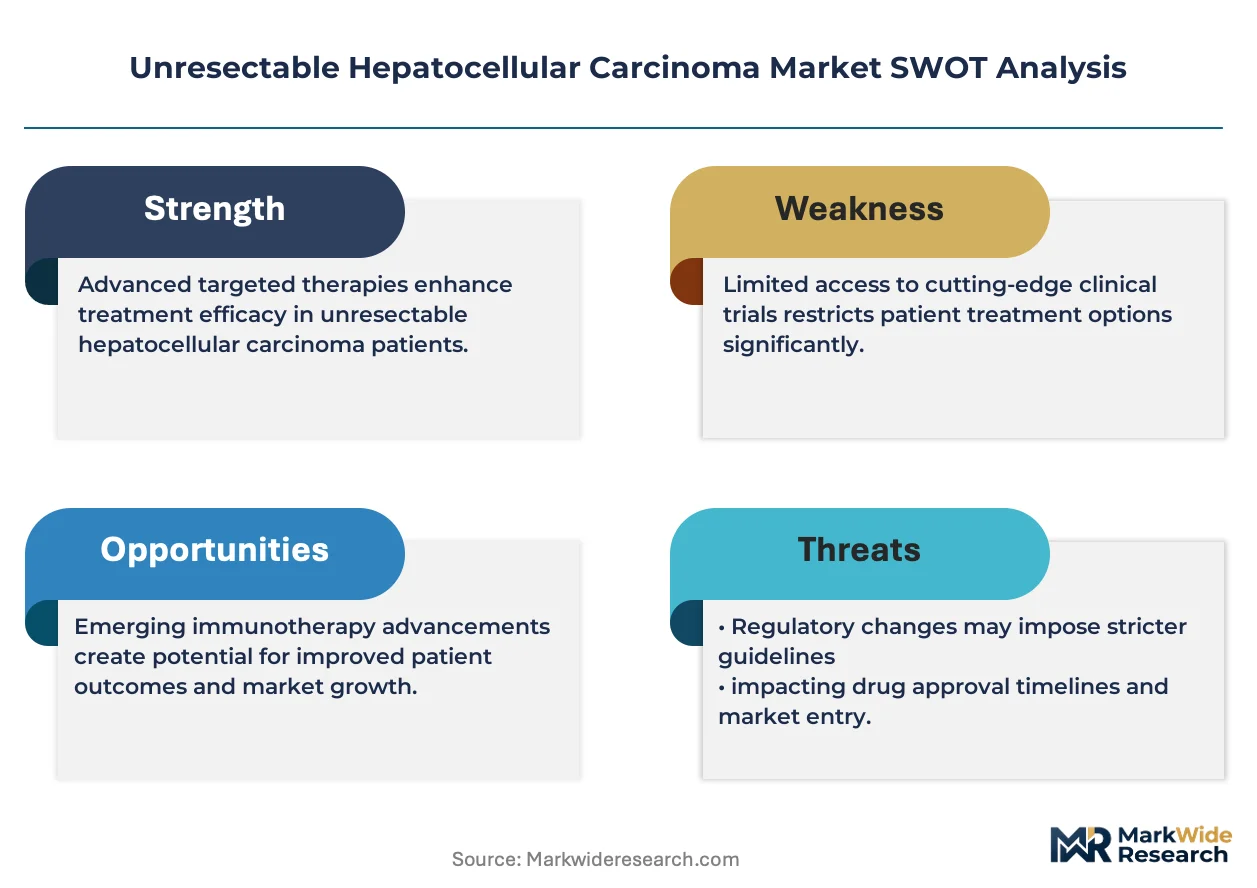
The FDA's accelerated approval framework and the EMA's conditional marketing authorization pathway shape development timelines and commercial launch sequencing for novel agents in this indication. China's NMPA breakthrough therapy designation and national reimbursement list negotiations determine market access velocity and pricing ceilings for multinational sponsors. Stakeholders must monitor evolving biomarker-driven patient stratification criteria and their impact on label expansion opportunities and competitive positioning.
Market Dynamics
Combination immunotherapy protocols are restructuring treatment hierarchies in unresectable hepatocellular carcinoma, as clinicians sequence checkpoint inhibitors with anti-angiogenic agents to circumvent resistance mechanisms that limit monotherapy durability.
Growth Catalysts
- FDA Accelerated Approval Pathway:The breakthrough therapy designation compresses development timelines for novel immuno-oncology agents, enabling earlier commercial access while confirmatory trials continue.
- China's Centralized Procurement Reforms:Volume-based procurement mechanisms expand patient access to biologics by negotiating price ceilings directly with manufacturers, stimulating demand across tertiary hospital networks.
- Biomarker-Driven Stratification:PD-L1 expression profiling and ctDNA monitoring enable precision patient selection, improving response rates and supporting label expansion opportunities for combination regimens.
Market Restraints
- Infusion Center Economics:Intravenous administration requires specialized infrastructure and staffing, limiting treatment capacity in community oncology settings and rural geographies.
- Reimbursement Compression:Medicare's bundled payment structures for oncology services constrain margins on high-cost immunotherapy, pressuring pricing strategies in the United States.
- Hepatic Reserve Limitations:Child-Pugh classification thresholds exclude substantial patient populations from systemic therapy, narrowing addressable markets for novel agents.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administration platforms reduce infusion center dependency and expand treatment access to ambulatory settings, capturing patients in remote geographies.
- Neoadjuvant Therapy Expansion:Pre-surgical systemic treatment to enable surgical conversion represents an underpenetrated indication with substantial unmet need and premium pricing potential.
- Real-World Evidence Infrastructure:EHR-integrated outcomes registries support post-marketing surveillance and accelerate label updates, creating competitive differentiation through data generation capabilities.
Industry Challenges
- Immunotherapy Resistance Mechanisms:Primary and acquired resistance to checkpoint inhibition necessitates complex biomarker strategies and combination trial designs that extend development timelines.
- Cross-Functional Talent Scarcity:Shortages of hepatology-oncology specialists and immuno-oncology clinical trialists constrain site activation and patient enrollment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unresectable Hepatocellular Carcinoma Market |
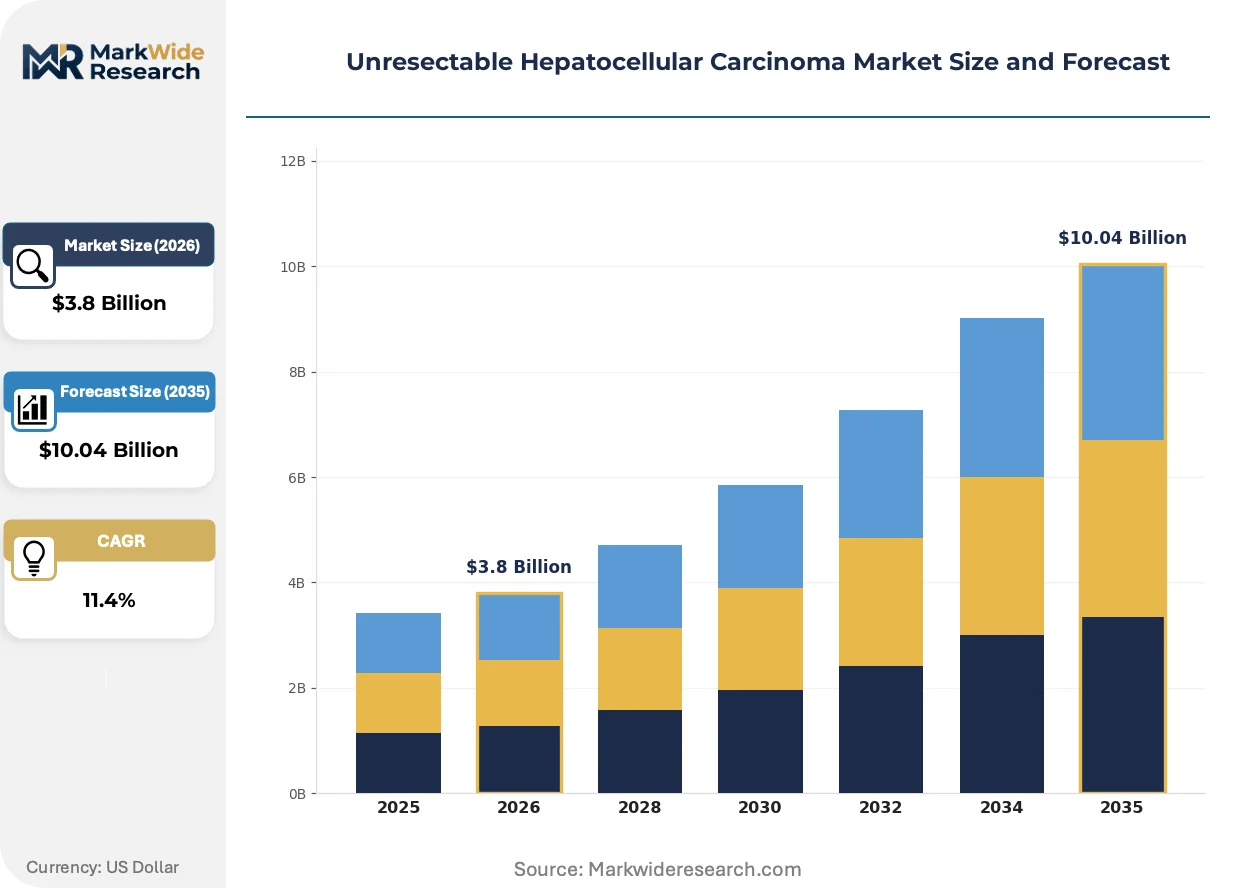
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Sorafenib, Lenvatinib, Regorafenib, Nivolumab Treatment Type: Monotherapy, Combination Therapy, Targeted Therapy, Immunotherapy Administration Route: Oral, Intravenous, Subcutaneous, Intra-arterial End User: Hospitals, Specialty Clinics, Research Institutions, Homecare |
| Companies Covered | Eisai Co. Ltd, Pfizer Inc., Bristol-Myers Squibb Company, AstraZeneca PLC, Eli Lilly and Company, Bayer AG, Merck & Co. Inc., Novartis AG, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unresectable Hepatocellular Carcinoma Market Evolving Landscape
Digital biomarker platforms and decentralized trial infrastructure are compressing traditional development paradigms, while regulatory frameworks adapt to accommodate novel endpoints and real-time safety monitoring.
Artificial intelligence-enabled radiomics is digitizing tumor response assessment, extracting quantitative imaging features from CT and MRI scans that predict treatment outcomes earlier than RECIST criteria. Academic medical centers in the United States and Germany are deploying these algorithms to stratify patients for combination versus sequential therapy. The technology is digitizing clinical decision workflows, reducing inter-reader variability and accelerating protocol amendments in adaptive trial designs.
China's NMPA breakthrough therapy designation and conditional approval pathways are compressing the gap between pivotal trial completion and market launch, creating regulatory arbitrage opportunities for sponsors with parallel development strategies. The policy shift enables earlier revenue recognition but demands robust post-marketing commitment frameworks. Multinational sponsors are responding by establishing dedicated China development organizations with autonomous decision-making authority.
Oncology procurement in European hospital systems is consolidating through tender-based frameworks that bundle immunotherapy across tumor types, displacing brand-loyal purchasing with outcome-weighted selection criteria. Germany's university hospitals and France's public hospital networks are piloting indication-agnostic checkpoint inhibitor contracts with risk-sharing provisions. The restructuring concentrates purchasing power among centralized pharmacy committees, compressing field force effectiveness and demanding account-based engagement models.
Unresectable Hepatocellular Carcinoma Market Segmentation
Unresectable hepatocellular carcinoma demands precise patient stratification across therapy selection, treatment sequencing, and care delivery settings. Segmentation reveals where clinical practice diverges from trial evidence and where infrastructure investments unlock access.
Therapy Area:
The use-case spectrum spans established kinase inhibitors through checkpoint inhibitors, with selection driven by line of therapy, hepatic reserve status, and prior treatment exposure.
- Sorafenib:The first approved systemic agent for this indication, sorafenib remains a backbone therapy in resource-constrained settings and for patients with contraindications to immunotherapy. Demand concentrates in China and India where centralized procurement has compressed pricing, though hepatotoxicity limits utility in Child-Pugh B populations.
- Lenvatinib:Demonstrated non-inferiority to sorafenib with a distinct toxicity profile favoring patients with higher baseline blood pressure and preserved cardiac function. Japanese and South Korean tertiary centers have adopted lenvatinib as preferred first-line therapy based on regional subset analyses from pivotal trials.
- Regorafenib:Standard second-line option following progression on sorafenib, requiring careful hand-foot skin reaction management through dose interruption protocols. Prescribing concentrates in European comprehensive cancer centers with dedicated hepatology-oncology nursing support.
- Nivolumab:Checkpoint inhibitor with accelerated approval based on tumor response rate, now positioned in combination regimens rather than monotherapy following confirmatory trial readouts. United States academic medical centers lead combination protocol development with anti-angiogenic partners.
The dominant share belongs to kinase inhibitors, while immunotherapy combinations are closing the gap fastest.
Treatment Type:
Cost tier differentiation separates premium combination regimens from accessible monotherapy options, with reimbursement policy determining real-world utilization patterns.
- Monotherapy:Single-agent kinase inhibition or checkpoint blockade, selected for patients with limited performance status or contraindications to combination toxicity. Medicare bundled payments in the United States favor oral monotherapy in community oncology settings where infusion capacity is constrained.
- Combination Therapy:Checkpoint inhibitor plus anti-angiogenic agent protocols, now standard of care in first-line settings across NCCN and ESMO guidelines. Tertiary hospitals in Germany and France have established dedicated combination therapy units with hepatology-oncology co-management.
- Targeted Therapy:Precision approaches directed at specific molecular alterations including FGFR4 and MET amplifications, currently concentrated in clinical trial populations. Academic medical centers in Boston and Heidelberg maintain molecular profiling pipelines to identify eligible candidates.
- Immunotherapy:PD-1 and PD-L1 directed agents, with durvalumab plus tremelimumab combinations gaining traction following regulatory approvals. China's NMPA breakthrough therapy designation has accelerated access in Shanghai and Beijing hospital networks.
Combination therapy commands the premium reimbursement tier, though monotherapy retains volume leadership in cost-sensitive channels.
Administration Route:
Customer type segmentation distinguishes infusion-dependent hospital protocols from patient-administered oral regimens, with geography determining infrastructure availability.
- Oral:Kinase inhibitors enabling outpatient management without infusion center dependency, preferred by patients with rural residence or limited transportation access. India's tier-2 city oncology units have expanded oral therapy capacity through telemedicine monitoring protocols.
- Intravenous:Checkpoint inhibitors and combination regimens requiring infusion center infrastructure, concentrated in tertiary hospitals with pharmacy compounding capabilities. United States community oncology practices struggle with capacity constraints as patient volumes shift from oral to infused therapy.
- Subcutaneous:Emerging delivery platforms for immunotherapy agents, with development programs targeting reduced infusion center burden and patient convenience. European hospital systems in the Netherlands and Denmark are piloting subcutaneous nivolumab in ambulatory care settings.
- Intra-arterial:Locoregional chemotherapy delivery via hepatic artery infusion, reserved for patients with preserved liver function and localized intrahepatic disease. Japanese interventional radiology centers in Osaka and Tokyo maintain specialized expertise in this modality.
Intravenous administration holds institutional preference, though subcutaneous alternatives are gaining share fastest among ambulatory care innovators.
End User:
Volume concentration varies dramatically across settings, with hospital-based care dominating systemic therapy delivery while homecare remains underdeveloped.
- Hospitals:Comprehensive cancer centers and tertiary general hospitals managing complex cases with combination regimens, adverse event monitoring, and multidisciplinary tumor boards. China's provincial hospital networks in Guangdong and Jiangsu have established dedicated hepatobiliary oncology departments.
- Specialty Clinics:Community oncology practices and hepatology-focused ambulatory centers handling stable patients on oral therapy or routine immunotherapy infusions. United States value-based care organizations in Florida and Texas are consolidating hepatocellular carcinoma management into specialty clinic networks.
- Research Institutions:Academic medical centers conducting phase I and II combination trials, with patient access contingent on biomarker eligibility and prior therapy history. National Cancer Institute-designated centers in Maryland and Texas lead immuno-oncology protocol development.
- Homecare:Limited to oral medication administration and supportive care, with expansion constrained by hepatocellular carcinoma complexity and monitoring requirements. Home nursing services in Germany's integrated care regions are piloting oral therapy monitoring with remote laboratory integration.
Hospitals capture the dominant patient volume, though specialty clinics are expanding capacity most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor the United States as the dominant geography, while China's NMPA reforms and Europe's EMA conditional authorizations reshape access velocity across distinct regulatory environments.
United States
Medicare reimbursement policies favor novel immunotherapy access, driving demand concentration in tertiary oncology centers. The FDA's breakthrough therapy designation compresses development timelines for checkpoint inhibitors. Academic medical centers in Boston and Houston lead combination protocol development with hepatology-oncology co-management models.
China
Centralized procurement reforms expand patient access to biologics through volume-based price negotiations. The NMPA breakthrough therapy designation accelerates market launch sequencing for multinational sponsors. Provincial hospital networks in Guangdong and Jiangsu have established dedicated hepatobiliary oncology departments with expanded manufacturing capacity.
Germany
University hospitals pilot indication-agnostic checkpoint inhibitor contracts with outcome-weighted selection criteria. The EMA's conditional marketing authorization pathway shapes commercial launch sequencing for novel agents. Comprehensive cancer centers in Heidelberg and Munich maintain molecular profiling pipelines for biomarker-driven stratification.
Japan
Regional subset analyses from pivotal trials drive adoption of lenvatinib as preferred first-line therapy. The PMDA's sakigake designation system accelerates access for innovative oncology agents. Tertiary centers in Osaka and Tokyo maintain specialized expertise in intra-arterial locoregional delivery modalities.
United Kingdom
NICE technology appraisals determine reimbursement access for combination immunotherapy regimens. The MHRA's post-Brexit regulatory autonomy enables tailored approval pathways for hepatocellular carcinoma agents. London-based academic medical centers lead real-world evidence infrastructure development for post-marketing surveillance.
Unresectable Hepatocellular Carcinoma Market Competitive Landscape
Checkpoint inhibitor specialists and targeted therapy anchors split the market between immunotherapy combinations and established kinase inhibition platforms. The competitive structure consolidates around multinational pharmaceutical conglomerates with oncology-focused portfolios. Two strategic archetypes dominate: immuno-oncology developers sequencing combination regimens, and targeted therapy incumbents defending kinase inhibitor positioning. Capacity expansion in biologics manufacturing and strategic partnerships for biomarker co-development represent the dominant competitive moves reshaping positioning.
Within the immuno-oncology tier, Bristol-Myers Squibb and Merck & Co. occupy positions as archetypal checkpoint inhibitor developers, while Bayer AG anchors the targeted therapy landscape as a representative kinase inhibitor incumbent. These three companies exemplify the strategic divergence between immunotherapy combination developers and established targeted therapy platforms, with each archetype pursuing distinct regulatory and commercial pathways to address hepatic reserve limitations and resistance mechanisms.
| Leading Market Players |
|---|
| Eisai Co. Ltd |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| Eli Lilly and Company |
| Bayer AG |
| Merck & Co. Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Network & Pricing Analysis
Jiangsu province's biologics manufacturing clusters determine downstream pricing power through capacity allocation decisions and centralized procurement negotiations. Volume-based procurement reforms in China compress margins for kinase inhibitors while immunotherapy combinations retain premium positioning in tertiary hospital networks. Price differentiation between oral and infused regimens reflects infrastructure dependency rather than manufacturing cost alone.
Pricing Analysis
Geographic price spreads between Shanghai and Mumbai exceed those between Shanghai and Berlin due to divergent reimbursement architectures and procurement mechanisms. Three-tier pricing structure across premium combination regimens, standard kinase inhibitors, and economy oral generics dominates the landscape. Pricing pressure stems from Medicare bundled payment compression in the United States and China's volume-based procurement mandates. Community oncology practices exhibit highest price sensitivity due to constrained infusion center economics, while academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Extended payment terms from Chinese hospital networks to domestic biologics manufacturers now stretch beyond 180 days, forcing working capital recourse to supply-chain finance facilities. Manufacturing concentrates in China, Switzerland, and the United States for active pharmaceutical ingredients and finished dose forms. Key inputs include recombinant protein expression systems, sterile fill-finish capacity, and cold-chain distribution infrastructure. Single-source vulnerability around specialized bioreactor equipment creates bottleneck risk. Distribution runs through hospital pharmacy committees and centralized procurement platforms rather than wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of hepatology-oncology specialists capable of managing combination therapy toxicity constrains site activation velocity and creates competitive advantage for sponsors with dedicated clinical trial infrastructure. Bridging this capability gap demands targeted capability-building investments rather than generic expansion.
For Market Incumbents: Build clinical data moats through real-world evidence infrastructure integrated with EHR systems at NCI-designated centers. Defend against biosimilar encroachment by securing preferred positioning on China's national reimbursement list and expanding subcutaneous formulation pipelines. Capacity addition in Singapore and Switzerland reduces tariff exposure while maintaining quality credentials for FDA and EMA submissions. For New Entrants and Emerging Players: Build out neoadjuvant therapy development programs targeting surgical conversion populations currently excluded from systemic therapy labels. India's tier-2 city oncology units represent the most penetrable geography due to oral therapy preference and telemedicine monitoring adoption. Go-to-market positioning through hepatology-focused specialty clinics rather than comprehensive cancer centers reduces competitive friction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors immuno-oncology platform companies with biomarker co-development capabilities over single-asset kinase inhibitor developers. Long-term viability across the projection horizon depends on pipeline diversification beyond PD-1 combinations into novel targets such as LAG-3 and TIGIT. Acquisition targets should demonstrate regulatory affairs expertise across FDA, EMA, and NMPA pathways. The signal to watch is NMPA breakthrough therapy designation velocity as predictor of China revenue recognition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Co-Development Partnership | PD-L1 and ctDNA stratification capabilities accelerate patient enrollment at MD Anderson and Memorial Sloan Kettering. |
| Subcutaneous Formulation Development | Self-administration platforms bypass infusion center constraints in United States community oncology practices. |
| Real-World Evidence Infrastructure | EHR-integrated registries at German university hospitals support label expansion and post-marketing surveillance. |
| China Development Organization Autonomy | Dedicated NMPA submission teams compress gap between pivotal trial completion and breakthrough therapy designation. |
| Neoadjuvant Therapy Expansion | Pre-surgical systemic treatment addresses surgical conversion populations with substantial unmet need. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient flow modeling and top-down market sizing triangulated volume estimates across therapy lines and administration routes.
Forecast inputs included treatment sequencing patterns, biomarker prevalence rates, and regulatory approval velocity across the analysis window. Segmentation dimensions modeled encompass treatment line, administration route, hepatic reserve status, and regional regulatory cluster. CAGRs derived from patient population growth, therapy penetration curves, and pricing trajectory assumptions. Industry-specific inputs incorporated NMPA breakthrough therapy designation timelines and Medicare bundled payment evolution.
Practitioners should monitor NMPA policy shifts, FDA confirmatory trial readouts, and biomarker-driven label expansion decisions for early signals of forecast revision. The analysis reflects assumptions regarding regulatory pathway continuity and reimbursement stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Paraneoplastic Syndromes Market
Oncology
Stomach Cancer Treatment Market
Oncology
Glioblastoma Market
Oncology
Tumor Ablation Market
Oncology
Glottic Cancer Treatment Market
Oncology
Metastatic Breast Cancer Market
Oncology
Colorectal Cancer Treatment Market
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Liposarcoma Treatment Market
Oncology
Global Cancer Profiling Market
Oncology
Oncology Apoptosis Modulators Market
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
Breast Cancer Brachytherapy Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
Asia Pacific Cancer Immunotherapy Market