
 Europe Radiotherapy Patient Positioning Market | 2026-2036
Europe Radiotherapy Patient Positioning Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Radiotherapy Patient Positioning Market Foresight
Software-defined motion management is hardening as a recurring revenue layer atop hardware installations across European radiotherapy suites. Elekta leverages its integrated oncology informatics platform to bundle positioning software with linac service contracts. Orfit Industries anchors its competitive stance through specialized thermoplastic immobilization systems that dominate head-and-neck protocols. C-RAD competes on real-time surface-guided tracking, a modality gaining traction in stereotactic workflows.
Europe radiotherapy patient positioning encompasses mechanical, software, and consumable systems engineered to immobilize patients with sub-millimeter reproducibility during fractional radiation delivery, typically achieving positioning tolerances of one to two millimeters for cranial and extracranial treatments. These systems serve the clinical imperative of sparing healthy tissue while escalating tumoricidal dose through external beam radiation, brachytherapy, and stereotactic radiosurgery applications. Head supports and body frames command durable replacement cycles and represent established margin pools, while motion management technology captures accelerated investment as clinics pursue hypofractionated regimens requiring tighter positional control. Software integration across 3D imaging and laser alignment modules is deepening vendor stickiness and expanding service attach rates.
EMA device oversight and the EU MDR framework are elevating clinical evidence requirements for positioning accessories, compressing timelines for legacy product recertifications. CE marking under strengthened notified body scrutiny is filtering smaller suppliers and concentrating procurement authority among tier-one vendors with dedicated regulatory affairs functions. France's ANSM and Germany's BfArM are enforcing post-market surveillance obligations that favor manufacturers with embedded quality management systems. Stakeholders must weigh regulatory compliance costs against the strategic value of maintaining broad European market access as MDR transition deadlines enforce portfolio rationalization.
Market Dynamics
The EU MDR recertification deadline is compressing vendor timelines and filtering smaller suppliers, concentrating procurement authority among tier-one manufacturers with embedded quality management systems and dedicated regulatory affairs functions.
Growth Catalysts
- Hypofractionated regimens:Stereotactic body radiotherapy and ultra-hypofractionated protocols demand sub-millimeter positioning reproducibility, driving replacement of legacy mechanical systems with integrated motion management platforms across German university hospital networks.
- MDR compliance deadlines:Strengthened notified body scrutiny under the EU Medical Device Regulation is accelerating portfolio rationalization among established vendors, creating captive replacement demand for CE-marked positioning accessories.
- Surface-guided radiation therapy:Real-time optical tracking technology is displacing fiducial-based workflows in cranial and thoracic applications, expanding addressable procedure volumes in France's comprehensive cancer centers.
Market Restraints
- Notified body capacity constraints:EMA-authorized conformity assessment organizations face backlogs exceeding 18 months for Class IIa positioning devices, delaying market entry for iterative product improvements.
- Specialized polymer feedstock concentration:Medical-grade thermoplastic polyurethane formulations for immobilization masks depend on German and Benelux chemical suppliers, exposing molders to input cost volatility.
- Linac vendor bundling:Integrated positioning system contracts tied to linear accelerator procurement compress standalone accessory margins and limit third-party vendor access to radiotherapy suite budgets.
Strategic Opportunities
- Central and Eastern Europe:Poland, Hungary, and the Czech Republic exhibit radiotherapy infrastructure gaps with positioning system penetration rates trailing Western European benchmarks by 40-50 percentage points.
- Software-as-a-service motion analytics:Cloud-based positioning quality assurance platforms enable recurring revenue streams independent of hardware replacement cycles, particularly attractive to mid-cap cancer centers.
- EU Green Deal procurement criteria:Emerging sustainability scoring for medical device tenders creates differentiation pathways for manufacturers with recyclable thermoplastic immobilization systems and reduced packaging footprints.
Industry Challenges
- Medical physics staffing shortages:Qualified radiotherapy physicists capable of commissioning surface-guided positioning systems remain scarce across NHS trusts and French public hospital networks, extending implementation timelines.
- Legacy linac interoperability:Retrofitting electromagnetic tracking and optical surface guidance onto decade-old linear accelerators requires custom mechanical adapters and proprietary software bridges, inflating integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Radiotherapy Patient Positioning Market |
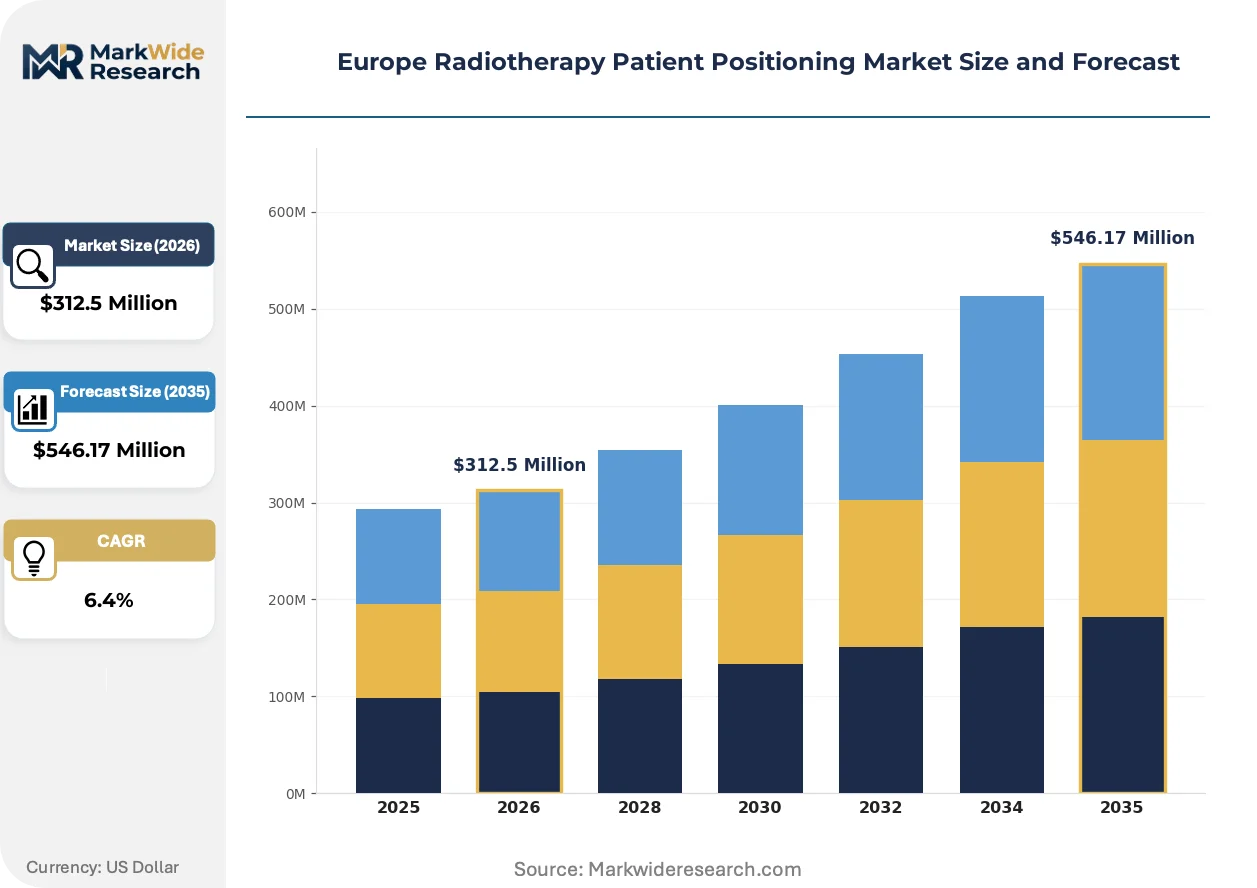
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolsters, Cushions, Head Supports, Body Frames End User: Hospitals, Clinics, Cancer Centers, Research Institutes Technology: 3D Imaging, Laser Alignment, Motion Management, Software Integration Application: External Beam Radiation, Brachytherapy, Total Body Irradiation, Stereotactic Radiosurgery |
| Companies Covered | Elekta, Orfit Industries, Qfix, CDR Systems, Eckert & Ziegler BEBIG, Roper Technologies-CIVCO, C-RAD, Candor ApS, MacroMedics BV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Radiotherapy Patient Positioning Market Shifts & Advancements
Artificial intelligence-enabled positioning verification is compressing daily setup times while elevating reproducibility standards, reshaping competitive advantage toward vendors with embedded machine learning competencies.
Deep learning-based auto-contouring and positioning verification algorithms are rewriting clinical workflow economics in European radiotherapy departments. University hospital networks in Germany and the Netherlands are deploying these tools to reduce daily setup verification from 15 minutes to under 5 minutes per fraction. The technology is compressing staffing requirements and enabling higher patient throughput without proportional capital expansion.
The EU AI Act's risk classification framework for medical devices is elevating documentation burdens for positioning software with autonomous decision-making capabilities. Manufacturers must maintain post-market performance monitoring systems and algorithmic change control protocols. French ANSM and German BfArM are enforcing these obligations most stringently, favoring vendors with pre-existing quality management system maturity.
Hospital procurement departments are unbundling positioning system maintenance from linear accelerator service contracts, creating standalone competitive tenders for software updates and calibration services. This pattern is most visible in NHS England trusts and Spanish regional health systems, where specialized positioning vendors are capturing service revenue previously monopolized by linac OEMs through multi-year performance-based agreements.
Europe Radiotherapy Patient Positioning Market Segmentation
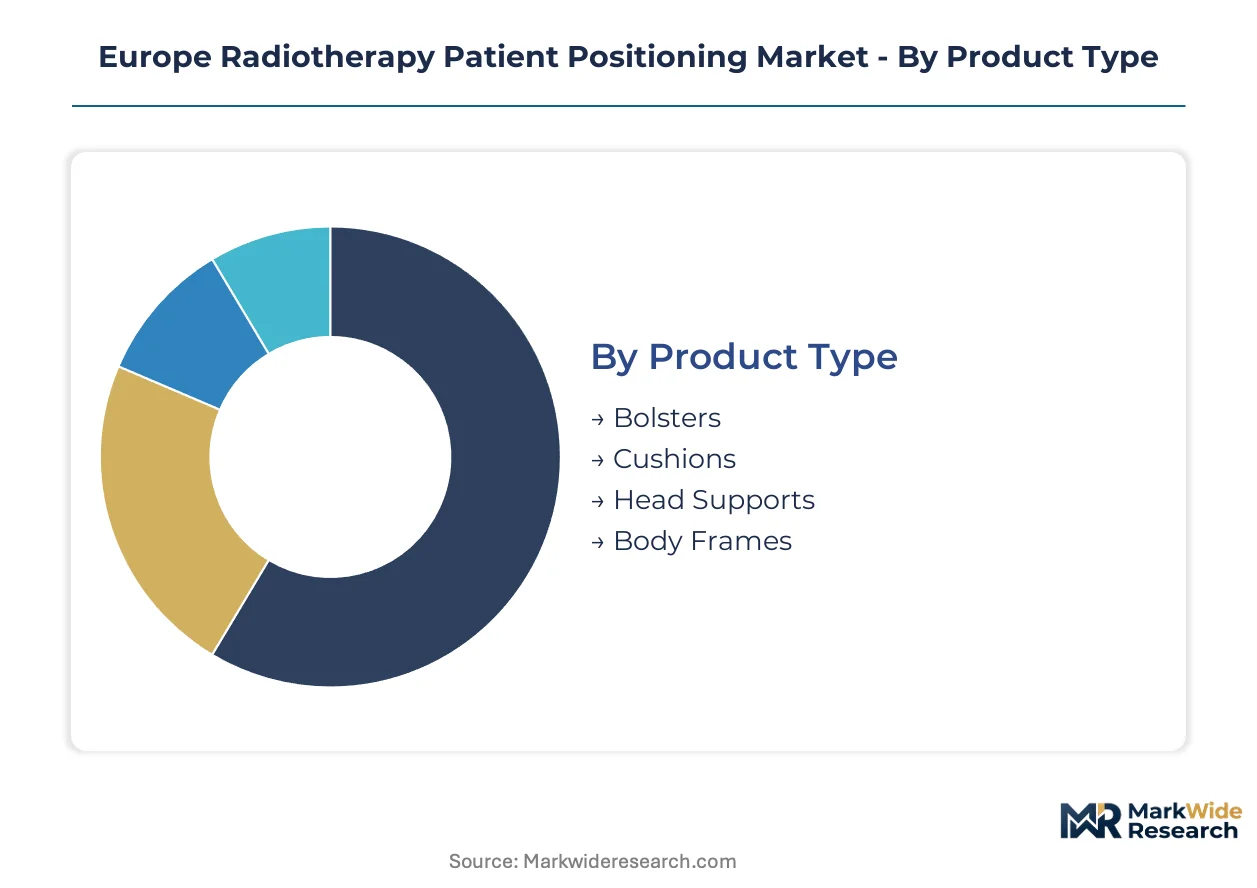
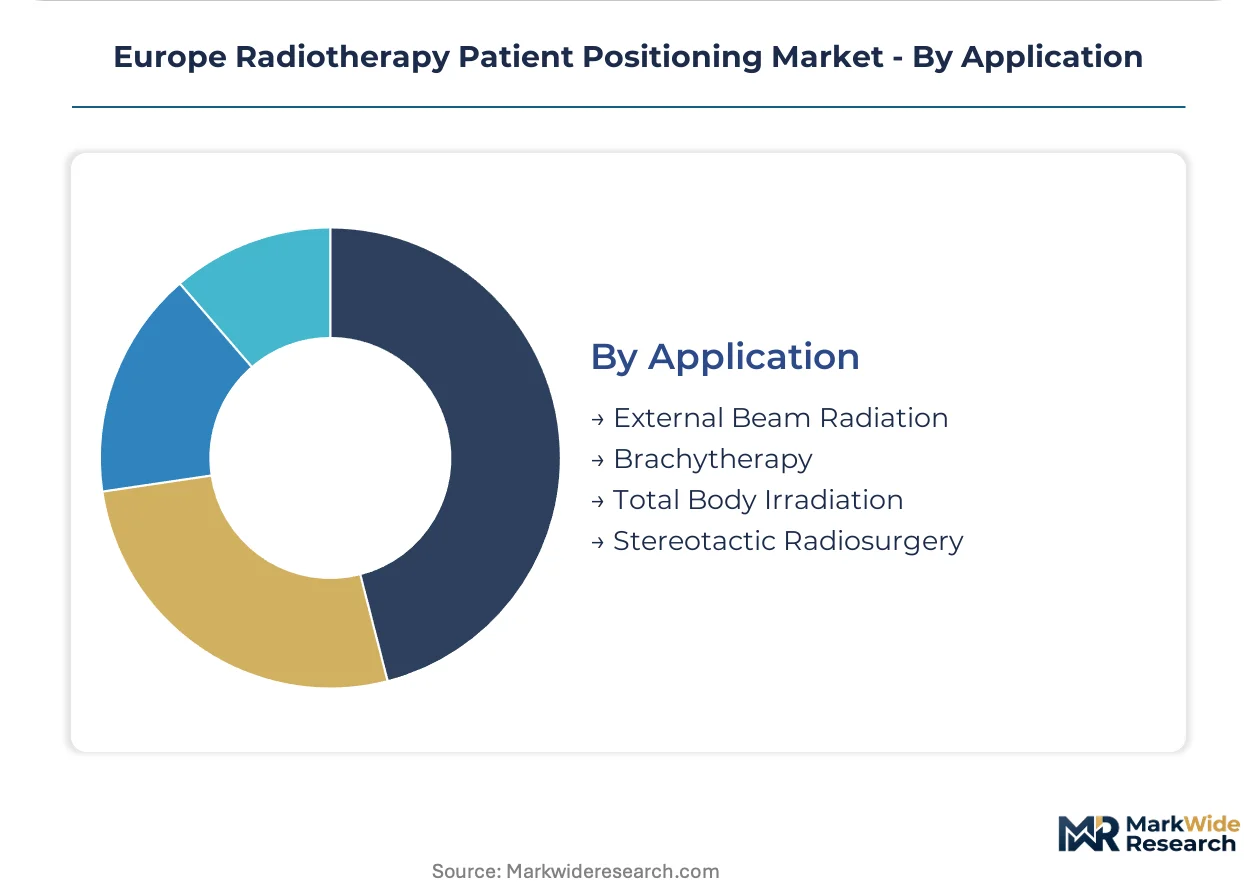
Patient positioning systems in European radiotherapy exhibit distinct integration profiles across product categories, with some segments functioning as standalone purchases while others embed deeply into linac vendor ecosystems. Understanding these structural boundaries clarifies procurement authority and margin capture for equipment manufacturers.
Product Type:
Mechanical positioning components span standalone accessories that cancer centers source independently versus systems bundled with linear accelerator contracts, creating divergent margin and replacement dynamics.
- Head Supports:Specialized cranial immobilization devices using thermoplastic masks and adjustable indexing achieve sub-millimeter reproducibility for brain and head-and-neck protocols. German university hospital networks and France's comprehensive cancer centers drive replacement demand as these consumables degrade through repeated sterilization cycles.
- Motion Management:Real-time tracking platforms integrating optical surface guidance and electromagnetic monitoring represent the deepest embedded category, typically sold through linac OEM channels with multi-year service attachments. French ANSM and German BfArM enforcement of EU MDR post-market surveillance obligations favor tier-one vendors with dedicated regulatory affairs functions for this high-risk class.
- Bolsters:Angled foam and vacuum-formed positioning aids for extremity and pelvic setup.
- Cushions:Standardized and custom-molded patient comfort systems for prolonged treatment fractions.
- Body Frames:Rigid indexing systems for torso immobilization in extracranial stereotactic workflows.
Volume placements concentrate in Head Supports; the faster expansion belongs to Motion Management.
End User:
Procurement scale and decision-making authority vary sharply across institutional types, with concentrated buying power in national health systems contrasting fragmented clinic-level purchasing.
- Cancer Centers:Comprehensive oncology institutions with dedicated radiotherapy departments command the largest positioning system budgets and longest replacement cycles. NHS England trusts and Spain's regional health systems are unbundling positioning maintenance from linac service contracts, creating standalone competitive tenders that specialized vendors exploit.
- Hospitals:General acute care facilities with embedded radiation oncology units typically purchase through group purchasing organizations or national procurement frameworks. Poland, Hungary, and the Czech Republic exhibit infrastructure gaps with positioning penetration trailing Western European benchmarks, creating expansion opportunity.
- Clinics:Outpatient radiation therapy facilities with limited capital budgets favor refurbished or entry-level positioning systems.
- Research Institutes:Academic medical centers commissioning experimental positioning protocols for clinical trials.
Cancer Centers absorb the dominant share of capital positioning investments; Clinics are climbing the fastest as independent radiation therapy networks proliferate across Southern and Eastern Europe.
Technology:
Technology layers in positioning systems stratify by software dependency and regulatory complexity, with pure hardware modules facing lighter MDR burdens than algorithm-driven platforms.
- Software Integration:Oncology informatics platforms bundling positioning verification, imaging fusion, and workflow management command recurring revenue streams independent of hardware replacement. The EU AI Act's risk classification framework elevates documentation burdens for autonomous positioning algorithms, favoring vendors with pre-existing quality management maturity.
- 3D Imaging:Cone-beam CT and stereoscopic X-ray verification systems integrated into positioning workflows enable daily adaptive radiotherapy. German and Dutch university hospital networks deploy these tools to compress setup verification from fifteen minutes to under five minutes per fraction.
- Laser Alignment:Optical positioning reference systems for initial patient setup and isocenter verification.
- Motion Management:Respiratory gating and intrafraction tracking technologies for thoracic and abdominal targets.
3D Imaging dominates current installation volumes; Software Integration is gaining share fastest as clinics pursue SaaS motion analytics and cloud-based quality assurance platforms.
Application:
Clinical application segments diverge by positioning precision requirements, with hypofractionated protocols demanding tighter tolerances and driving technology substitution.
- External Beam Radiation:Conventional fractionated therapy represents the largest installed base of positioning systems, though margin pressure intensifies as procurement consolidates through linac vendor bundling. CE marking under strengthened notified body scrutiny filters smaller suppliers, concentrating authority among tier-one manufacturers.
- Stereotactic Radiosurgery:Ultra-precise cranial and extracranial ablation demands sub-millimeter reproducibility and real-time motion compensation. Surface-guided radiation therapy is displacing fiducial-based workflows in France's comprehensive cancer centers and German university networks.
- Brachytherapy:Internal radiation delivery requiring specialized applicator positioning and imaging verification.
- Total Body Irradiation:Extended-field conditioning protocols for hematologic malignancies with large-field setup challenges.
External Beam Radiation maintains the broadest installed footprint; Stereotactic Radiosurgery shows the steepest expansion trajectory as hypofractionated regimens proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European radiotherapy positioning procurement, with university hospital networks there driving integrated motion management adoption ahead of national peers. France's comprehensive cancer centers and NHS England trusts follow as concentrated demand clusters, each shaped by distinct reimbursement and regulatory frameworks.
Germany
German university hospital networks in Bavaria and North Rhine-Westphalia drive replacement demand for thermoplastic immobilization systems as repeated sterilization cycles degrade mask integrity. BfArM enforces EU MDR post-market surveillance obligations that favor tier-one vendors with embedded quality management systems. Munich's Klinikum rechts der Isar and Heidelberg University Hospital commission experimental positioning protocols for ultra-hypofractionated regimens.
France
France's comprehensive cancer centers in Île-de-France and Auvergne-Rhône-Alpes expand surface-guided radiation therapy installations for stereotactic workflows. ANSM applies stringent scrutiny to CE marking applications for Class IIa positioning devices, filtering smaller suppliers from procurement shortlists. Gustave Roussy in Villejuif and Centre Léon Bérard in Lyon anchor clinical validation networks for optical tracking technology.
United Kingdom
NHS England trusts unbundle positioning system maintenance from linear accelerator service contracts, creating standalone competitive tenders for software updates and calibration services. MHRA alignment with EU MDR timelines compresses recertification windows for legacy mechanical positioning accessories. The Royal Marsden and University College London Hospitals anchor adoption of deep learning-based positioning verification in the Greater London cluster.
Netherlands
Dutch university medical centers in Amsterdam and Rotterdam deploy cone-beam CT integrated positioning workflows to compress daily setup verification times. The Dutch Healthcare Authority enforces value-based procurement criteria that elevate total cost-of-ownership calculations over capital expenditure minimization. Erasmus MC and Amsterdam UMC validate cloud-based positioning quality assurance platforms for multi-site deployment.
Poland
Polish regional oncology centers exhibit positioning system penetration rates trailing Western European benchmarks by 40-50 percentage points, creating expansion opportunity for entry-tier equipment. The Polish Office for Registration of Medicinal Products aligns device oversight with EU MDR transition timelines, though notified body capacity constraints delay market entry. Warsaw's Maria Sklodowska-Curie National Research Institute and Krakow's Jagiellonian University Medical College anchor emerging adoption clusters.
Europe Radiotherapy Patient Positioning Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European radiotherapy positioning landscape. Integrated linear accelerator manufacturers bundle positioning hardware with multi-year service contracts, compressing standalone accessory margins for independent vendors. Three archetypes dominate: linac OEMs with captive positioning divisions, specialized thermoplastic immobilization manufacturers, and optical tracking technology developers. Competitive moves concentrate on M&A to secure regulatory affairs capabilities and strategic partnerships to bypass linac vendor procurement channels.
Among Sweden-based oncology equipment specialists, Elekta exemplifies the integrated platform archetype, bundling positioning software with informatics and linear accelerator service contracts. Orfit Industries, a Belgian manufacturer, occupies a position within specialized thermoplastic immobilization, anchoring competitive stance through head-and-neck protocol dominance. C-RAD, also Swedish, represents the optical surface guidance tier, competing on real-time tracking modalities for stereotactic workflows.
| Leading Market Players |
|---|
| Elekta |
| Orfit Industries |
| Qfix |
| CDR Systems |
| Eckert & Ziegler BEBIG |
| Roper Technologies-CIVCO |
| C-RAD |
| Candor ApS |
| MacroMedics BV |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between CE-marked Class IIa motion management platforms and legacy mechanical accessories manifests in divergent margin structures and procurement channel strategies across European radiotherapy suites. Premium-tier vendors with embedded quality management systems command service-attach rates exceeding commodity positioning hardware, while supply chain configurations concentrate polymer feedstock sourcing in Germany and Benelux chemical corridors.
Pricing Analysis
Margin tightening in mechanical positioning accessories reflects linac vendor bundling practices that compress standalone procurement budgets. Three-tier pricing structure across premium integrated platforms, standard thermoplastic systems, and economy refurbished equipment stratifies by certification level and after-sales service bundling. NHS England trusts and French public hospital networks exhibit acute price sensitivity for consumable immobilization masks, while German university hospitals prioritize total cost-of-ownership over capital expenditure minimization.
Supply Chain Analysis
Regional distribution centers in Germany and the Netherlands anchor hub-and-spoke fulfillment networks for thermoplastic immobilization systems across Western European cancer centers. Medical-grade polyurethane formulations draw from German and Benelux chemical suppliers, creating single-source vulnerability for specialized polymer feedstocks. Distribution runs through specialized medical device wholesalers with cold-chain capabilities for temperature-sensitive positioning materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface-guided radiation therapy is displacing fiducial-based positioning workflows, compressing timelines for vendors with legacy mechanical portfolios to demonstrate optical tracking integration.
For Market Incumbents: Cement regulatory affairs capabilities ahead of EU MDR recertification deadlines to filter smaller competitors from procurement shortlists. Deepen backward integration into thermoplastic polymer compounding to offset feedstock cost volatility from Benelux suppliers. Prioritize software companion development for AI-enabled positioning verification to defend service contract renewals against standalone SaaS entrants. For New Entrants and Emerging Players: EU MDR transition timelines in Poland, Hungary, and the Czech Republic open a window for entry-tier positioning systems in underpenetrated Central European oncology networks. Target independent radiation therapy clinics in Southern Europe with refurbished motion management platforms and performance-based calibration service agreements. Pursue strategic partnerships with regional distributors to bypass linac OEM procurement channels. For Investors and Strategic Acquirers: Re-rating potential sits with optical surface guidance specialists given ANSM and BfArM enforcement of post-market surveillance obligations that favor quality management maturity. Acquisition targets should demonstrate embedded machine learning competencies for autonomous positioning algorithms and established CE marking pathways for Class IIa software. Watch for NHS England trust unbundling patterns as inflection indicator for standalone service revenue capture.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR recertification deadlines filter smaller suppliers from French and German procurement shortlists. |
| Software Companion Development | AI-enabled positioning verification compresses setup times for Dutch university medical centers. |
| Hospital System Partnership | Multi-year performance agreements with NHS England trusts capture service revenue from linac OEMs. |
| Backward Integration | In-house polymer compounding reduces exposure to German and Benelux feedstock price volatility. |
| Geographic Expansion | Central European infrastructure gaps in Poland and Hungary create positioning system penetration opportunity. |
Research Methodology
Document review covered regulatory filings with EMA and national competent authorities, complemented by interviews with radiotherapy physicists, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Secondary sources included EU MDR transition guidance documents, notified body certification databases, hospital procurement tender records, and trade data for medical-grade polymer imports. Bottom-up equipment installation counts triangulated against top-down cancer center capacity estimates across the analysis window.
Historical adoption curves for surface-guided radiation therapy cross-referenced against expert panel assessments of hypofractionated regimen proliferation. Segmentation modeling incorporated product type, end-user institution scale, technology layer, and clinical application dimensions. CAGRs derived from iterative reconciliation of replacement cycle assumptions with capital budget elasticity parameters for university hospital networks and comprehensive cancer centers.
The model assumes a particular technology adoption path; alternative pathways for electromagnetic tracking integration would alter the outlook for optical surface guidance market share. Forecasts reflect documented assumptions regarding MDR transition compliance rates and notified body capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Radiotherapy Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Sterile Oncology Injectable Market
Oncology
Germany Radiotherapy Market
Oncology
Cancer Supportive Care Products Market
Oncology
Osteosarcoma Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
America Cancer Immunotherapy Market
Oncology
Precision Oncology Market
Oncology
Metastases Spinal Tumor Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Oncology Devices Market