
 Bone Cancer Market | 2026-2036
Bone Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Cancer Market Analysis
EMA's priority medicines scheme is realigning the cost-of-entry calculus for European developers of bone sarcoma therapies. Amgen Inc. leverages its biologics manufacturing scale to sustain supply chain advantages across oncology indications. Novartis AG anchors its competitive position through specialized radioligand therapy infrastructure. Bayer AG differentiates via targeted alpha therapy platforms that occupy a narrow but defensible technical niche.
Bone cancer encompasses primary malignant neoplasms arising from osseous tissue, including osteosarcoma, chondrosarcoma, and Ewing sarcoma, characterized by abnormal mesenchymal cell proliferation with metastatic potential to lung and bone. These malignancies require multimodal intervention combining surgical resection with systemic therapy to achieve limb salvage and survival endpoints. Immunotherapy commands the fastest expansion within the technology dimension, driven by checkpoint inhibitor development in refractory sarcoma subtypes. Targeted therapy captures concentrated margin pools where biomarker-selected patient populations justify premium positioning. Surgery retains volume leadership across product types, though reimbursement pressure on procedural economics intensifies globally.
FDA oncology center of excellence standards, EMA's adaptive pathways framework, and WHO essential medicines list inclusion criteria collectively shape clinical trial design, label expansion strategies, and market access timelines for bone cancer therapeutics. National health technology assessment bodies in Germany, France, and England apply divergent cost-effectiveness thresholds that fragment pricing power across European markets. Stakeholders must monitor evolving biomarker definitions and companion diagnostic requirements that will determine which pipeline assets secure priority review and formulary placement.
Market Dynamics
Precision oncology protocols are compressing clinical trial timelines and fragmenting patient eligibility criteria, forcing developers to rebuild commercial infrastructure around biomarker-selected cohorts rather than broad histologic labels.
Growth Catalysts
- EMA Adaptive Pathways:The framework accelerates conditional approval for bone sarcoma therapies with promising early-phase data, reducing time-to-revenue for European developers.
- Radioligand manufacturing scale-up:Specialized production facilities for alpha-emitting isotopes are expanding treatment access beyond academic medical centers into community oncology networks.
- Limb salvage surgery demand:Patient preference for functional preservation over amputation is expanding the addressable population for neoadjuvant systemic therapy.
Market Restraints
- Isotope supply concentration:Production of actinium-225 and lead-212 concentrates at fewer than six government-funded reactors worldwide, creating single-point-of-failure vulnerability.
- Biomarker assay fragmentation:Discordant PD-L1 scoring algorithms across diagnostic platforms complicate patient selection for checkpoint inhibitor trials.
- Reimbursement heterogeneity:Germany's IQWiG assessment methodology applies divergent cost-effectiveness thresholds than France's HAS or England's NICE, fragmenting pricing power.
Strategic Opportunities
- Japan's regenerative medicine framework:PMDA's conditional approval pathway for tissue-engineered bone grafts creates first-mover advantage for limb reconstruction adjuvants.
- Real-world evidence integration:FDA's Project Facilitate is enabling external control arm construction from electronic health records, reducing placebo-arm enrollment requirements.
- Companion diagnostic co-development:Pre-IDE alignment with CDER on CDx validation protocols secures simultaneous label expansion for drug and test.
Industry Challenges
- Sarcoma pathology subspecialist scarcity:Fellowship-trained bone tumor pathologists concentrate at fewer than forty US institutions, creating diagnostic bottleneck and trial enrollment delays.
- Cold-chain logistics for radiopharmaceuticals:Half-life decay kinetics of therapeutic isotopes require same-day synthesis-to-infusion coordination that strains standard oncology pharmacy infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Cancer Market |
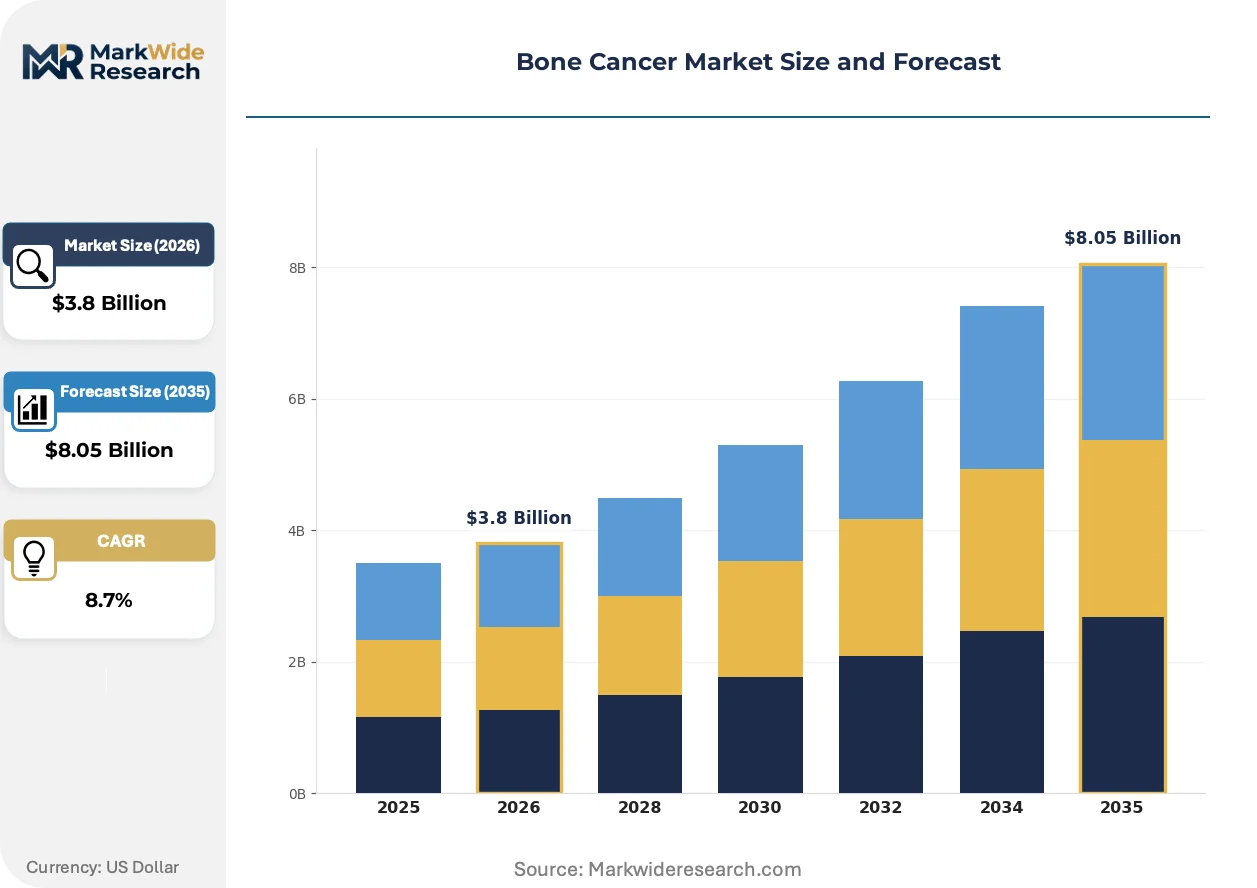
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Radiation Therapy, Chemotherapy, Targeted Therapy End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Technology: Immunotherapy, Gene Therapy, Biologics, Small Molecules Application: Diagnosis, Treatment, Prognosis, Research |
| Companies Covered | Amgen Inc., Novartis AG, Bayer AG, Merck & Co. Inc., Pfizer Inc., Bristol-Myers Squibb Company, Eli Lilly and Company, Johnson & Johnson Services Inc., Debiopharm Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Cancer Market Emerging Trajectories
Biologic mechanism understanding is shifting therapeutic development from cytotoxic chemotherapy toward targeted payload delivery, with radioligand and antibody-drug conjugate platforms capturing disproportionate pipeline investment.
Alpha-emitting radioligand therapy is converging with precision dosimetry software to enable tumor-absorbed dose personalization. Academic medical centers in the United States are adopting 3D voxel-based calculations to replace standard activity dosing. This convergence is compressing the therapeutic index gap between efficacy and bone marrow toxicity, expanding retreatment eligibility.
FDA's breakthrough therapy designation pathway is compressing development timelines for novel bone sarcoma agents by enabling rolling review and more frequent agency interaction. The industrial consequence is front-loaded CMC investment before phase II completion. Small-to-mid cap developers with limited quality systems infrastructure are most affected, driving contract manufacturing organization consolidation.
Patient advocacy networks are displacing traditional physician referral as the primary information channel for clinical trial awareness. Sarcoma Foundation of America and similar organizations now coordinate direct-to-patient genomic testing programs that bypass community oncology gatekeepers. This behavioral shift is most visible in the United States, where decentralized trial models are expanding geographic access beyond major metropolitan centers.
Bone Cancer Market Segmentation
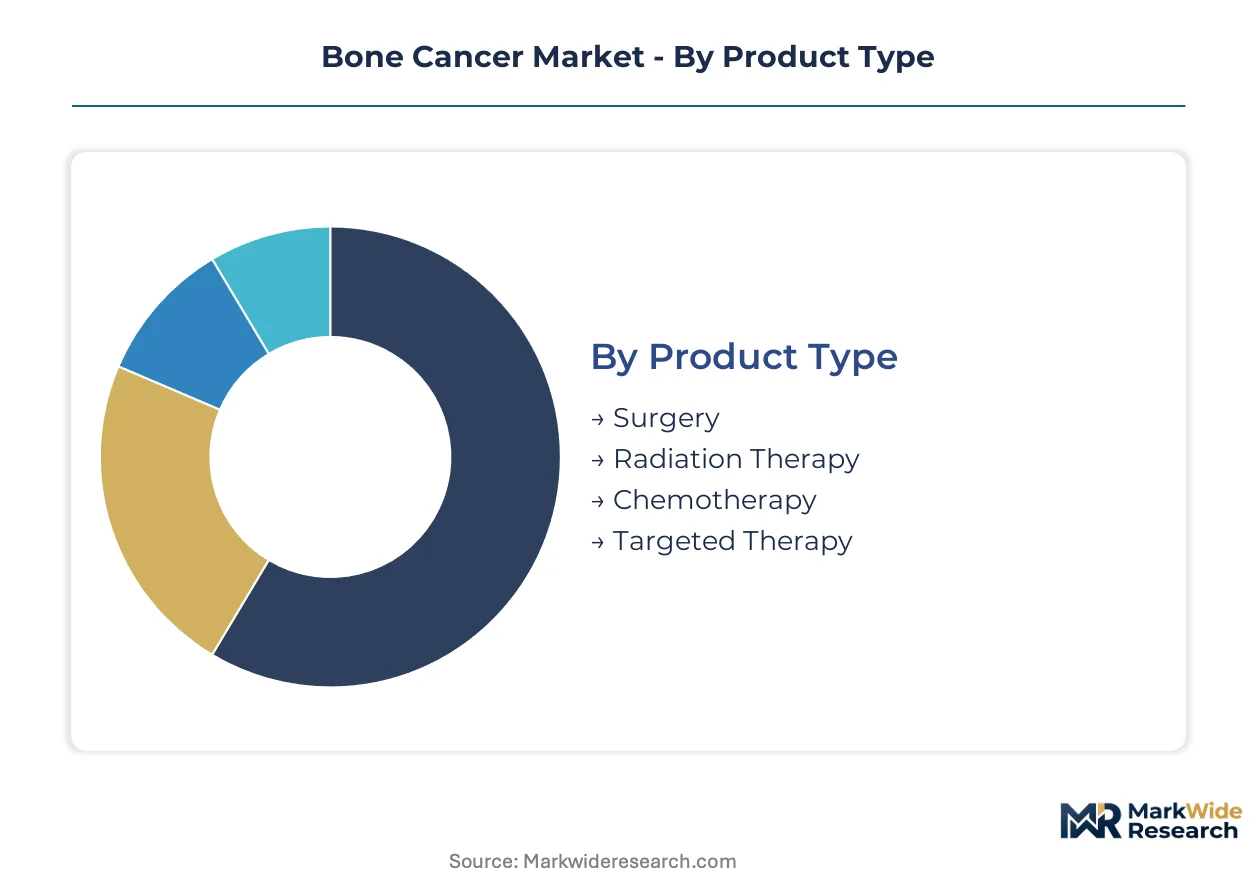
Bone cancer treatment selection hinges on multimodal staging requirements that vary sharply by patient age, tumor histology, and metastatic status. Segmentation reveals where reimbursement complexity concentrates and which modalities command premium positioning through specialized infrastructure demands.
Product Type:
Surgical resection carries the heaviest regulatory burden through joint commission accreditation and CMS procedural quality metrics, while systemic therapies navigate FDA oncology center of excellence standards and EMA conditional approval pathways.
- Surgery:Limb-sparing resection with endoprosthetic reconstruction dominates osteosarcoma protocols. Demand clusters at US academic medical centers with fellowship-trained musculoskeletal oncology programs, constrained by subspecialist scarcity and operating room block allocation.
- Radiation Therapy:Proton beam and intensity-modulated techniques reduce dose to surrounding tissue in pelvic and spinal primaries. Adoption spreads from MD Anderson and Memorial Sloan Kettering into community networks as proton center construction accelerates in Texas, Florida, and California.
- Chemotherapy:Neoadjuvant methotrexate-doxorubicin-cisplatin regimens remain standard for conventional osteosarcoma.
- Targeted Therapy:Denosumab for giant cell tumor and PARP inhibitors for BRCA-mutated subsets occupy narrow label indications.
Surgery sits at the top of the volume ranking, with targeted therapy climbing the fastest.
End User:
Site-of-care economics fragment procurement patterns, with 340B drug pricing distorting hospital-based infusion margins and ASC carve-outs shifting radiation delivery toward outpatient settings.
- Hospitals:Comprehensive cancer centers anchor complex case referral networks. NCI-designated institutions in Boston, Houston, and Seattle capture high-acuity sarcoma volumes through multidisciplinary tumor board infrastructure.
- Clinics:Community oncology practices handle stable-dose chemotherapy administration and surveillance imaging. Medicare reimbursement compression for E&M codes is forcing consolidation into hospital-owned networks.
- Ambulatory Surgical Centers:Limited to diagnostic biopsy and port placement procedures.
- Home Care:Oral targeted agents and supportive care medications shift delivery away from infusion centers.
Hospitals retain the dominant revenue share, though home care is expanding most quickly.
Technology:
Platform selection determines manufacturing complexity, with biologics requiring FDA CBER oversight and gene therapies navigating the regenerative medicine advanced therapy designation.
- Immunotherapy:Checkpoint inhibitors in refractory sarcoma subtypes command development investment. PD-1/PD-L1 trials concentrate at US sites with centralized biomarker testing, limited by discordant assay platforms.
- Gene Therapy:CAR-T and oncolytic viral approaches remain investigational for bone malignancies. Manufacturing scale constraints limit access to approved cell therapies at specialized academic centers.
- Biologics:Monoclonal antibodies and fusion proteins dominate targeted therapy pipelines.
- Small Molecules:Tyrosine kinase inhibitors offer oral administration advantages in maintenance settings.
Biologics lead current revenue contribution, with immunotherapy showing the steepest expansion trajectory.
Application:
Functional purpose shapes regulatory pathway selection, with diagnostic innovations qualifying for FDA breakthrough device designation and therapeutic applications commanding priority review vouchers.
- Diagnosis:Advanced imaging and liquid biopsy platforms enable molecular subtyping. FDG-PET/CT staging at major US centers guides neoadjuvant response assessment.
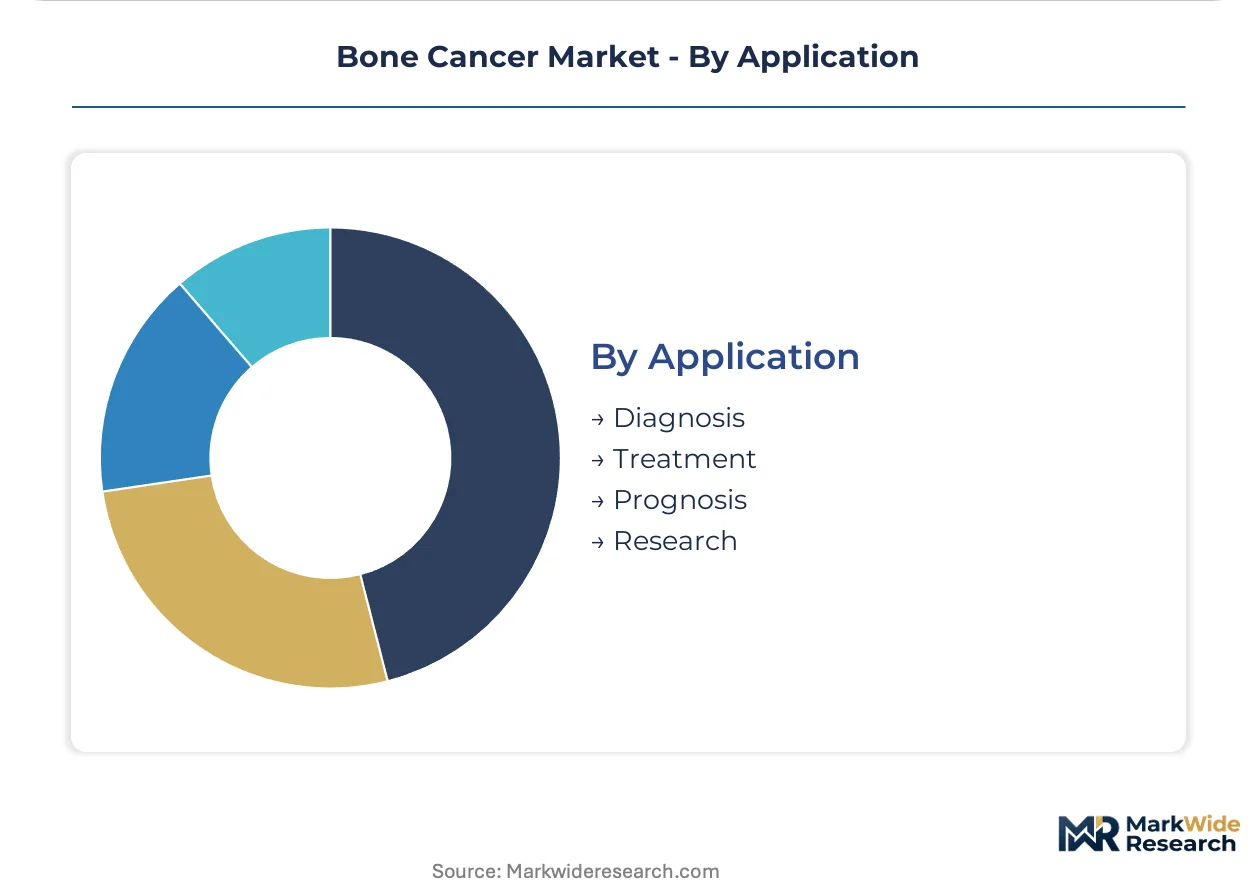
- Treatment:Curative-intent multimodal protocols drive the largest absolute spending. Limb salvage algorithms integrate surgical, radiation, and systemic components.
- Prognosis:Minimal residual disease monitoring and circulating tumor DNA assays are entering clinical validation.
- Research:Biobanking and clinical trial infrastructure supports biomarker discovery.
Treatment captures the dominant share, with diagnosis gaining ground fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained musculoskeletal oncologists concentrate at fewer than forty US academic institutions, creating diagnostic bottlenecks that shape regional market access patterns across major economies.
United States
NCI-designated comprehensive cancer centers in Houston, Boston, and Seattle anchor sarcoma referral networks through multidisciplinary tumor board infrastructure. FDA's breakthrough therapy designation pathway accelerates novel agent review timelines for developers targeting refractory subtypes. Proton beam construction in Texas, Florida, and California expands radiation delivery beyond legacy academic sites into community networks.
Germany
IQWiG assessment methodology applies stringent cost-effectiveness thresholds that compress reimbursement margins for systemic therapies relative to neighboring markets. EMA's priority medicines scheme enables conditional approval pathways that reduce time-to-market for bone sarcoma developers. The Heidelberg and Berlin-Brandenburg clusters concentrate pathology subspecialist expertise and radioligand manufacturing infrastructure.
Japan
PMDA's regenerative medicine framework creates conditional approval pathways for tissue-engineered bone grafts used in limb reconstruction protocols. METI funding programs support domestic alpha-emitting isotope production to reduce import dependency. The Kanto region around Tokyo hosts the densest concentration of sarcoma-specialized surgical programs in Asia-Pacific.
Switzerland
Swissmedic's alignment with EMA centralized procedures streamlines market access for developers seeking premium pricing in a concentrated high-income market. Basel and Zurich anchor specialized radiopharmaceutical manufacturing and precision oncology research clusters. The country's compact geography enables same-day radioligand synthesis-to-infusion logistics that match isotope half-life constraints.
United Kingdom
NICE technology appraisals apply quality-adjusted life year thresholds that restrict formulary placement for high-cost targeted therapies in bone malignancies. The NHS England specialized commissioning framework concentrates sarcoma surgery at fifteen designated centers in London, Birmingham, and Manchester. Real-world evidence integration through NHS Digital supports external control arm construction for FDA-aligned trial designs.
Bone Cancer Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the bone cancer therapeutic landscape, creating a tiered structure where scale advantages in biologics manufacturing clash with nimble radiopharmaceutical development. Large-cap pharmaceutical groups anchor the premium tier through specialized infrastructure investments in radioligand therapy and targeted alpha platforms. Mid-cap oncology specialists occupy the innovation vector through checkpoint inhibitor development in refractory sarcoma subtypes. Consolidation pressure intensifies as contract manufacturing organization partnerships become essential for small developers lacking quality systems infrastructure to support rolling FDA review.
Among the diversified pharmaceutical groups, Amgen Inc., Novartis AG, and Bayer AG exemplify distinct competitive archetypes within the bone cancer market. Amgen represents the biologics manufacturing scale player leveraging supply chain advantages across oncology indications. Novartis anchors the specialized radioligand therapy infrastructure position through targeted payload delivery platforms. Bayer occupies the targeted alpha therapy niche, representing the technical specialization archetype in a narrow but defensible market segment.
| Leading Market Players |
|---|
| Amgen Inc. |
| Novartis AG |
| Bayer AG |
| Merck & Co. Inc. |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Eli Lilly and Company |
| Johnson & Johnson Services Inc. |
| Debiopharm Group |
| Others |
Supply Flow & Price Mechanics
Actinium-225 spot pricing volatility cascades through radioligand therapy supply chains, compressing margins at compounding pharmacies while academic medical centers absorb cost pass-through via bundled episode-based reimbursement. This raw-material cost pressure stratifies treatment access across community oncology networks and NCI-designated comprehensive cancer centers.
Pricing Analysis
Bundled episode-based reimbursement dominates high-acuity bone sarcoma care, while unbundled fee-for-service persists in diagnostic biopsy and surveillance imaging. Three-tier pricing structure across premium, standard, and economy levels reflects subspecialist concentration, proton beam availability, and biomarker testing integration. Pricing pressure stems from Medicare reimbursement compression for E&M codes and 340B drug pricing distortions. Community oncology practices exhibit highest price sensitivity due to infusion margin erosion, whereas academic medical centers leverage negotiated payer contracts to offset cost volatility.
Supply Chain Analysis
Single-source vulnerability sits with actinium-225 and lead-212 production concentrated at fewer than six government-funded reactors in the United States, Russia, and Germany. Radiopharmaceutical manufacturing draws from specialized isotope suppliers, GMP-certified compounding facilities, and cold-chain logistics providers. Tariff exposure on imported isotopes from Eastern European production sites amplifies supply risk. Distribution runs through hub-and-spoke radiopharmacy networks that coordinate same-day synthesis-to-infusion logistics to match isotope half-life decay kinetics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bone cancer therapeutics function as a regulatory compounder where FDA breakthrough therapy designation and EMA adaptive pathways accelerate commercial timelines and expand addressable patient populations.
For Market Incumbents: Deepen radioligand manufacturing infrastructure to capture alpha-emitting isotope supply chain advantages before reactor capacity constraints harden. Anchor position through companion diagnostic co-development with CDER pre-IDE alignment, while expanding fellowship-trained musculoskeletal oncology programs to relieve diagnostic bottlenecks threatening trial enrollment velocity. For New Entrants and Emerging Players: Community oncology practices underserved by centralized biomarker testing infrastructure represent the most penetrable entry point. Target decentralized trial models enabled by patient advocacy network coordination, with direct-to-patient genomic testing programs bypassing traditional physician referral gatekeepers as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap oncology specialists possessing checkpoint inhibitor pipelines in refractory sarcoma subtypes but lacking quality systems infrastructure for rolling FDA review. Five-to-ten-year viability hinges on contract manufacturing organization consolidation trends. Watch for FDA Project Facilitate expansion enabling external control arm construction as the inflection signal for reduced clinical trial cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | CDER pre-IDE alignment secures simultaneous label expansion for drug and biomarker test. |
| Radioligand Manufacturing Scale-Up | Specialized alpha-emitting isotope production expands treatment access beyond academic medical centers. |
| Real-World Evidence Integration | FDA Project Facilitate enables external control arm construction from electronic health records. |
| Decentralized Trial Model Expansion | Patient advocacy network coordination bypasses geographic constraints of legacy site-based enrollment. |
| Subspecialist Fellowship Program Investment | Fellowship-trained bone tumor pathologists relieve diagnostic bottlenecks at fewer than forty US institutions. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down epidemiological triangulation anchor market sizing across the analysis window.
Granularity-level framing applies treatment line, tumor histology, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from epidemiological trend extrapolation, pricing elasticity assumptions, and technology diffusion curves. Forecast inputs incorporate biomarker prevalence rates, reimbursement pathway probabilities, and manufacturing capacity constraints for alpha-emitting isotopes.
Underlying measurement precision varies by segment; immunotherapy pipeline assets carry tighter precision than gene therapy investigational programs due to clinical validation maturity. Forecasts reflect documented assumptions regarding regulatory approval timelines, payer access negotiations, and isotope supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Liposarcoma Treatment Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
North America Proton Therapy Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
North America Kidney Cancer Therapeutics and Diagnostics Market
Oncology
Tumor Infiltrating Lymphocytes Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
Europe Proton Therapy Market
Oncology
Hadron Therapy Market
Oncology
Asia Pacific Cancer Immunotherapy Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Global Interventional Oncology Market
Oncology
Vulvar Cancer Market
Oncology
Lung Cancer Treatment Market
Oncology
Global Genomics in Cancer Care Market
Oncology
Precision Oncology Market