
 PD1 Non-Small Cell Lung Cancer Treatment Market | 2026-2036
PD1 Non-Small Cell Lung Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
PD1 Non-Small Cell Lung Cancer Treatment Market Analytics
The FDA's accelerated approval pathway is recalibrating the cost-of-entry calculus for PD1 inhibitor developers, demanding larger confirmatory trials and stricter post-market surveillance. Merck & Co. leverages its first-mover advantage in pembrolizumab to sustain dominance across multiple NSCLC indications. Bristol-Myers Squibb Company anchors its portfolio through nivolumab's entrenched position in second-line settings. Roche Holding AG differentiates via atezolizumab's distinct PD-L1 mechanism and companion diagnostic integration.
PD1 Non-Small Cell Lung Cancer Treatment encompasses monoclonal antibodies targeting the programmed cell death protein 1 receptor, administered primarily via intravenous infusion at weight-based dosing schedules to restore T-cell mediated anti-tumor immunity. These therapies function as immune checkpoint inhibitors that block PD1 binding to PD-L1/PD-L2 ligands expressed on cancer cells, thereby preventing immune evasion in NSCLC. Pembrolizumab and nivolumab occupy the mature core of the product landscape with established reimbursement, while cemiplimab represents the fastest-expanding segment through its recent frontline approvals. The metastatic patient category generates the deepest revenue pools, though early-stage adjuvant applications are attracting disproportionate R&D investment.
The FDA, EMA, and China's NMPA collectively shape market access through divergent evidentiary requirements for overall survival endpoints and biomarker-defined patient subsets. The FDA's Project Optimus initiative is forcing dose-optimization studies that extend development timelines, while EMA's parallel scientific advice streamlines European entry for sponsors with robust Phase III data. Stakeholders must monitor evolving PD-L1 expression cutoffs across regulatory jurisdictions, as threshold shifts directly alter addressable patient populations and label expansions.
Market Dynamics
The FDA's Project Optimus initiative is forcing dose-optimization studies that extend development timelines and recalibrate R&D resource allocation across the PD1 inhibitor pipeline. This regulatory pressure compounds with biomarker threshold shifts to reshape competitive positioning in frontline NSCLC therapy.
Growth Catalysts
- Medicare reimbursement protocols:The US Centers for Medicare & Medicaid Services favors immuno-oncology protocols through established billing codes, concentrating demand in oncology clinics and academic medical centers.
- PD-L1 companion diagnostics:Integrated diagnostic development is accelerating patient stratification and enabling precision enrollment in registrational trials.
- China's NMPA accelerated pathways:The regulator's breakthrough therapy designation compresses review timelines for domestic and multinational sponsors with robust Phase III data packages.
Market Restraints
- Plasma-derived raw material concentration:Supply of high-quality immunoglobulins concentrates among a limited supplier base in North America and Europe, creating input cost volatility for biosimilar developers.
- EMA evidentiary requirements:The agency's stricter overall survival endpoint demands extend confirmatory trial durations and inflate development expenditures relative to FDA pathways.
- Small-molecule TKI substitution:Targeted therapies for EGFR/ALK-mutant NSCLC subsets displace checkpoint inhibitors in biomarker-defined patient populations.
Strategic Opportunities
- Perioperative adjuvant settings:Early-stage NSCLC applications represent underpenetrated addressable populations with premium pricing potential and differentiated clinical trial endpoints.
- Subcutaneous formulation development:Route-of-administration innovation is compressing infusion center burden and enabling community oncology channel expansion.
- Japan's PMDA sakigake designation:The priority review framework offers expedited access for first-in-class mechanisms with Japan-specific clinical data packages.
Industry Challenges
- Immuno-oncology talent scarcity:Specialized biostatisticians and translational medicine professionals command premium compensation, constraining mid-cap sponsor expansion.
- Post-market surveillance infrastructure:FDA-mandated real-world evidence collection requires substantial pharmacovigilance investment and data platform integration.
- PD-L1 assay harmonization delays:Discordant scoring between diagnostic platforms complicates clinical trial enrollment and label expansion strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PD1 Non-Small Cell Lung Cancer Treatment Market |
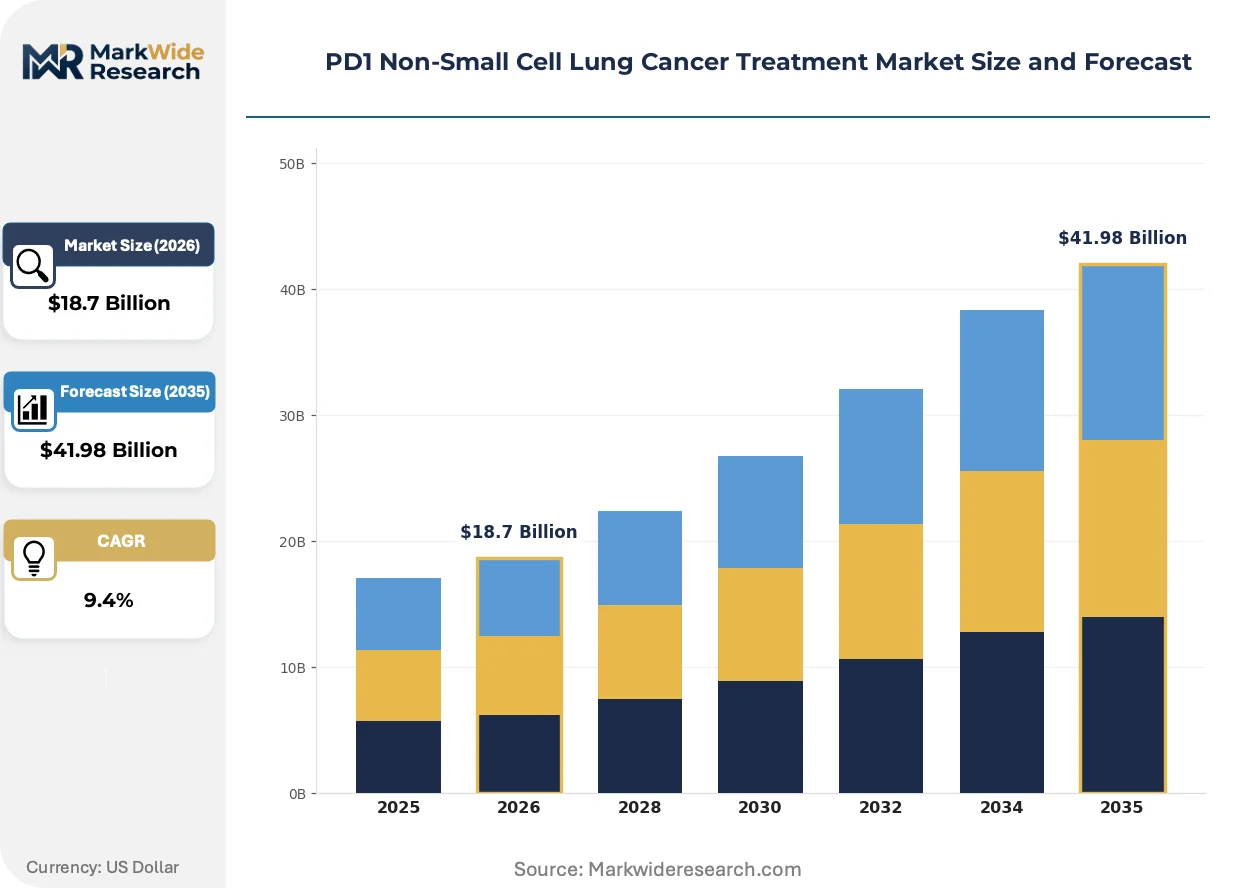
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pembrolizumab, Nivolumab, Cemiplimab, Atezolizumab Administration Mode: Intravenous, Subcutaneous, Oral, Intramuscular Patient Type: Early-stage, Locally advanced, Metastatic, Refractory End User: Oncology Clinics, Hospitals, Research Institutes, Home Care |
| Companies Covered | AstraZeneca plc, GlaxoSmithKline plc, Merck & Co., Ono Pharmaceutical Co., Ltd., Regeneron Pharmaceuticals, Bristol-Myers Squibb Company, Pfizer Inc., Innovent Biologics, Roche Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PD1 Non-Small Cell Lung Cancer Treatment Market Evolving Landscape
Biomarker-driven trial design is compressing development timelines while regulatory convergence around overall survival endpoints is elevating evidentiary standards. These forces are reshaping how sponsors allocate R&D capital across the PD1 inhibitor landscape.
Fixed-dose subcutaneous pembrolizumab formulations are overtaking weight-based intravenous infusion as the preferred administration modality in US oncology clinics. Community-based practices are adopting subcutaneous delivery to reduce chair time and infusion center capacity constraints. This route shift is enabling treatment decentralization and expanding addressable sites of care beyond academic medical centers.
The FDA's Project Optimus initiative mandates dose-finding studies that extend Phase I/II timelines and demand larger patient exposure cohorts. Sponsors must now generate robust exposure-response relationships before pivotal trial initiation, inflating early-development costs. This policy shift most acutely affects combination therapy programs where dose selection complexity multiplies across agent pairings.
Integrated delivery networks are consolidating oncology procurement decisions under centralized pharmacy and therapeutics committees. Community oncology practices are losing formulary autonomy as health system consolidation accelerates across the United States. This concentration is most visible in Medicare Advantage–dominated markets where payer-provider vertical integration steers therapy selection toward contracted manufacturers.
PD1 Non-Small Cell Lung Cancer Treatment Market Segmentation
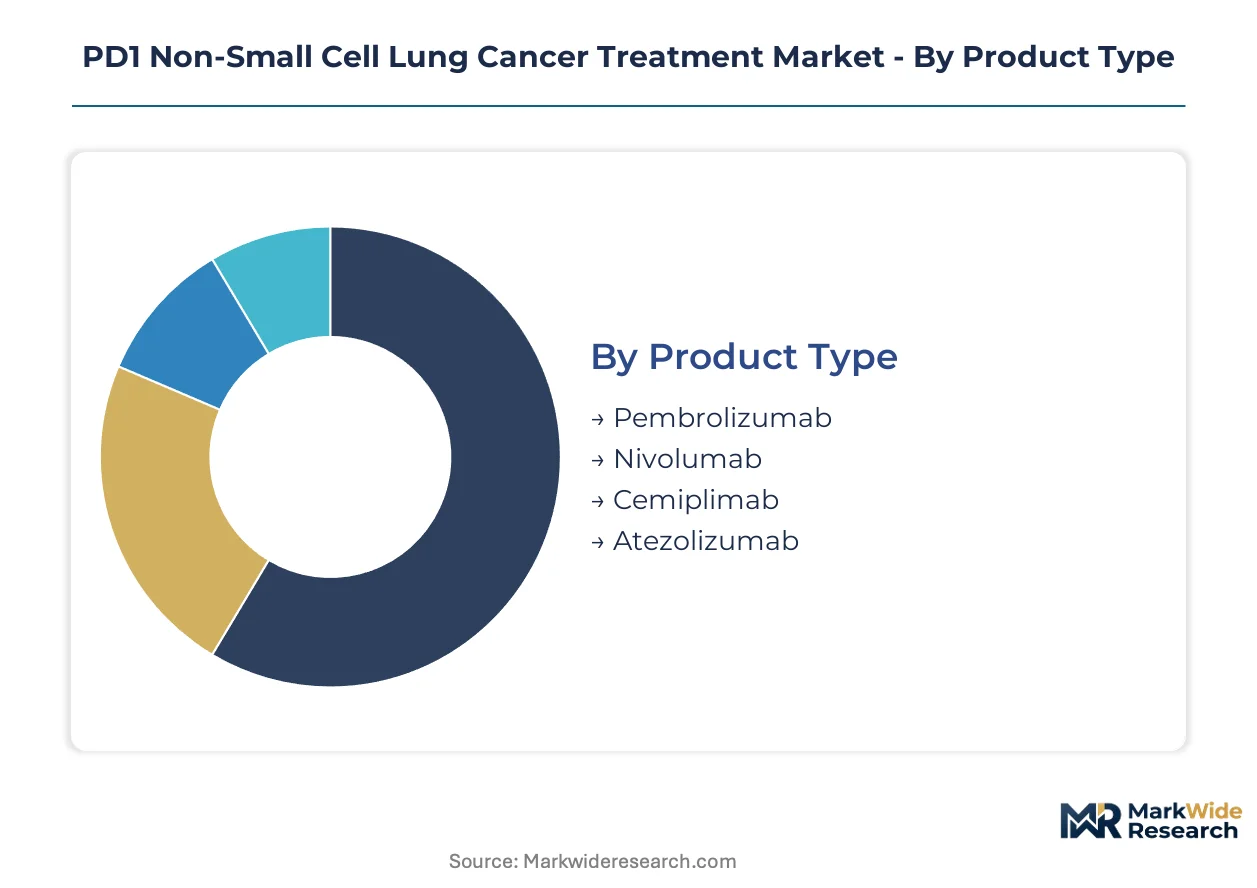
Segmentation in the PD1 NSCLC market determines reimbursement pathways, clinical trial design, and site-of-care economics. Each dimension—product mechanism, delivery route, disease stage, and care setting—carries distinct regulatory requirements and margin profiles that reshape competitive strategy.
Product Type:
Physician familiarity and companion diagnostic integration drive formulary placement decisions across hospital systems.
- Pembrolizumab:A humanized IgG4 monoclonal antibody targeting PD-1 with established PD-L1 companion diagnostic pairing. Demand concentrates in US oncology clinics where Medicare reimbursement codes favor first-line NSCLC protocols, though FDA-mandated dose-optimization studies under Project Optimus extend development timelines for combination regimens.
- Nivolumab:A fully human IgG4 PD-1 inhibitor with entrenched positioning in second-line settings. European adoption lags due to EMA's stricter overall survival endpoint requirements, compressing addressable populations relative to US markets.
- Cemiplimab:A high-affinity PD-1 blocker with recent frontline approvals in NSCLC. The antibody's engineered half-life supports extended dosing intervals.
- Atezolizumab:A PD-L1-targeting monoclonal antibody with distinct mechanism from PD-1 agents. Roche's integrated diagnostic platform enables precision enrollment.
Pembrolizumab leads on scale; cemiplimab leads on momentum.
Administration Mode:
Site-of-care economics and patient throughput determine route selection in consolidated health systems.
- Intravenous:Weight-based infusion remains standard for pembrolizumab and nivolumab in academic medical centers. Chair time constraints limit community oncology expansion.
- Subcutaneous:Fixed-dose formulations reduce infusion center burden and enable treatment decentralization. US community practices adopt subcutaneous delivery fastest.
- Oral:No approved oral PD1 agents exist; small-molecule checkpoint inhibitors remain in preclinical stages.
- Intramuscular:Investigational depot formulations seek to extend dosing intervals beyond current subcutaneous capabilities.
Intravenous infusion dominates current volume; subcutaneous delivery climbs fastest.
Patient Type:
Disease stage dictates trial endpoint requirements and pricing power in adjuvant versus metastatic settings.
- Metastatic:Established PD1 indications with mature reimbursement and largest treated populations. Overall survival endpoints satisfy FDA and EMA requirements.
- Early-stage:Perioperative adjuvant applications attract disproportionate R&D investment. Premium pricing potential exists with event-free survival endpoints.
- Locally advanced:Consolidation therapy after chemoradiation represents intermediate addressable population.
- Refractory:Heavily pretreated patients drive demand for combination trials and novel mechanisms.
Metastatic patients generate deepest revenue pools; early-stage adjuvant settings show steepest expansion trajectory.
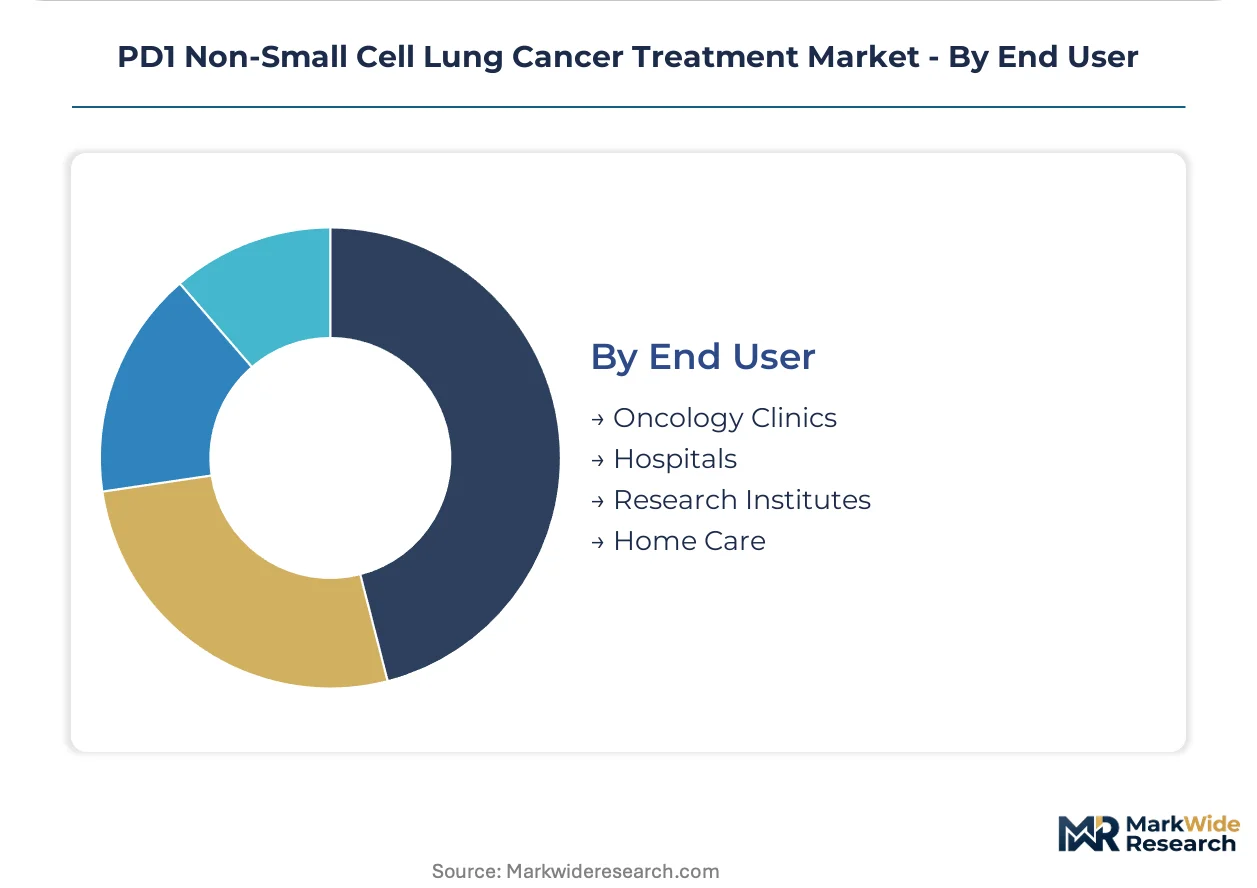
End User:
Procurement consolidation under integrated delivery networks reshapes site-of-care distribution.
- Oncology Clinics:Community-based practices drive subcutaneous adoption to reduce capacity constraints. Medicare Advantage vertical integration steers therapy selection.
- Hospitals:Academic medical centers administer complex combination regimens and manage immune-related adverse events. Centralized pharmacy committees control formulary access.
- Research Institutes:Phase I/II trial sites generate exposure-response data for dose-optimization studies.
- Home Care:Subcutaneous self-administration remains investigational; infrastructure for cold-chain biologics in home settings is limited.
Oncology clinics lead on patient volume; home care shows slowest penetration due to cold-chain requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology biostatisticians and immuno-oncology trial specialists concentrate in the United States, Germany, Japan, China, and the United Kingdom. These talent pools anchor regional R&D investment and regulatory submission capacity.
United States
Medicare Advantage vertical integration steers therapy selection toward contracted manufacturers in oncology clinics. The FDA's Project Optimus initiative mandates dose-optimization studies that extend Phase I/II timelines. Boston and San Francisco biotech clusters host the densest concentration of Phase I/II trial sites generating exposure-response data.
Germany
Academic medical centers in Baden-Württemberg and Bavaria administer complex combination regimens for immune-related adverse event management. EMA's stricter overall survival endpoint requirements compress addressable populations relative to US markets. The Munich and Heidelberg oncology hubs coordinate multicenter trials across the German-speaking region.
Japan
PMDA's sakigake priority review framework offers expedited access for first-in-class mechanisms with Japan-specific clinical data packages. METI coordinates domestic biologics manufacturing capacity expansion. The Kanto region around Tokyo anchors translational medicine infrastructure for PD-L1 companion diagnostic development.
China
NMPA's breakthrough therapy designation compresses review timelines for sponsors with robust Phase III data packages. Domestic sponsors leverage cost advantages in biosimilar development. Shanghai and Beijing biotech clusters concentrate immuno-oncology manufacturing capacity and clinical trial enrollment.
United Kingdom
NHS England's Cancer Drugs Fund enables provisional reimbursement for promising immuno-oncology therapies pending NICE appraisal. The MHRA operates accelerated access pathways post-Brexit. London and Cambridge anchor precision medicine research integrating genomic stratification with checkpoint inhibitor protocols.
PD1 Non-Small Cell Lung Cancer Treatment Market Competitive Landscape
The competitive structure tilts toward integrated pharmaceutical conglomerates with diagnostic capabilities and biologics manufacturing scale. Large-cap sponsors dominate through first-mover advantages in frontline indications and established PD-L1 companion diagnostic pairings. Mid-cap biotech specialists and emerging biosimilar developers constitute secondary archetypes. Capacity expansion in subcutaneous formulation manufacturing and strategic partnerships for perioperative adjuvant trials represent dominant competitive moves.
Among integrated pharmaceutical conglomerates, Merck & Co., Bristol-Myers Squibb Company, and Roche Holding AG occupy positions exemplifying the scale-driven archetype. These entities anchor the competitive landscape through entrenched reimbursement relationships and multi-indication portfolios. Merck & Co. represents first-mover consolidation in pembrolizumab-based protocols. Bristol-Myers Squibb Company exemplifies second-line positioning through nivolumab's established presence. Roche Holding AG anchors the PD-L1 mechanism differentiation strategy with integrated diagnostic platforms.
| Leading Market Players |
|---|
| AstraZeneca plc |
| GlaxoSmithKline plc |
| Merck & Co. |
| Ono Pharmaceutical Co., Ltd. |
| Regeneron Pharmaceuticals |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Innovent Biologics |
| Roche Holding AG |
| Others |
Value Network & Pricing Analysis
Pharmaceutical conglomerates with integrated diagnostic platforms anchor supply-side pricing power through captive manufacturing of monoclonal antibodies and companion diagnostic pairings. This ownership structure enables premium capture in frontline NSCLC settings while compressing margins for biosimilar developers dependent on plasma-derived immunoglobulin spot markets.
Pricing Analysis
Bundled pricing for PD1 inhibitor plus companion diagnostic testing dominates US oncology clinics, while unbundled component pricing persists in European markets where EMA evidentiary requirements fragment reimbursement decisions. Three-tier pricing structure across premium frontline protocols, standard second-line regimens, and economy biosimilar tiers separates Merck's pembrolizumab from Bristol-Myers Squibb's nivolumab and emerging follow-on biologics. Cost compression in the biosimilar tier is intensifying because China's Innovent Biologics and domestic sponsors exploit manufacturing scale advantages. Medicare Advantage plans demonstrate highest price sensitivity through centralized pharmacy committee formulary controls, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with North American and European plasma collection networks for immunoglobulin feedstock used in biosimilar development. Biologics manufacturing concentrates in the United States, Ireland, and Singapore for fill-finish operations, while active pharmaceutical ingredient production anchors in China and South Korea. Supply chains draw from recombinant cell lines, chromatography resins, and single-use bioreactor components as critical inputs. Tariff exposure on Chinese-sourced raw materials threatens cost structures for mid-cap developers. Distribution runs through specialty pharmacy channels and hospital-based outpatient infusion centers with cold-chain integrity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PD1 NSCLC treatment market functions as a stable compounder sustained by Medicare reimbursement tailwinds and irreversible substitution of chemotherapy in frontline protocols. Pricing power concentrates with incumbents possessing integrated diagnostic capabilities and established PD-L1 companion diagnostic pairings.
For Market Incumbents: Lock in formulary positioning through subcutaneous formulation manufacturing capacity expansion in US community oncology channels. Prioritize perioperative adjuvant trial investment to capture premium pricing in early-stage settings before biosimilar entry erodes metastatic margins. Threats from China's NMPA-accelerated domestic sponsors and EMA's stricter overall survival requirements demand defensive patent estate management and European regulatory affairs scale. For New Entrants and Emerging Players: Begin with Japan's PMDA sakigake priority review pathway for first-in-class mechanisms, leveraging expedited access with Japan-specific clinical data packages. Target China's NMPA breakthrough therapy designation for domestic manufacturing partnerships, exploiting compressed review timelines and local cost structures. White-space exists in subcutaneous self-administration infrastructure and home care cold-chain logistics for biologics distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap biotech specialists with Phase II perioperative adjuvant assets and subcutaneous formulation platforms lacking commercial infrastructure. Five-to-ten year viability hinges on successful navigation of FDA Project Optimus dose-optimization mandates and EMA evidentiary convergence. Signal to monitor: PD-L1 assay harmonization agreements between diagnostic platform vendors that would streamline clinical trial enrollment and de-risk development timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Perioperative Adjuvant Trial Advancement | Event-free survival endpoints unlock premium pricing in early-stage NSCLC populations. |
| Subcutaneous Formulation Manufacturing Scale-Up | Fixed-dose delivery reduces infusion center burden and expands community oncology access. |
| Companion Diagnostic Platform Integration | Roche's PD-L1 assay pairing with atezolizumab demonstrates precision enrollment advantages. |
| NMPA Breakthrough Therapy Pathway Navigation | Domestic Chinese sponsors compress development timelines through regulator collaboration. |
| Biosimilar Pipeline Diversification | Plasma-derived immunoglobulin supply constraints favor recombinant platform investment. |
Research Methodology
Multiple input streams — primary interviews with oncology drug development executives, formulary directors at integrated delivery networks, and payer access specialists; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases; plus customs and trade data on biologics imports — were reconciled through bottom-up patient-flow modeling and top-down revenue triangulation.
Historical prescription volume trajectories were cross-referenced against panel input from hospital procurement managers and GPO contracts analysts to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include treatment line, administration route, patient disease stage, and regional regulatory cluster. CAGRs were derived from exposure-response relationships in dose-optimization studies and biomarker-defined enrollment trends. Forecast inputs incorporated PD-L1 expression cutoff shifts across jurisdictions and subcutaneous adoption curves in US community practices.
Caveats apply where FDA Project Optimus mandate expansion, EMA overall survival endpoint requirement changes, or China NMPA domestic biologics policy shifts could materially shift the outlook. Forecasts reflect assumptions on biomarker assay harmonization timelines and Medicare Advantage vertical integration penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
North America Kidney Cancer Therapeutics and Diagnostics Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Radiotherapy Market
Oncology
Asia-Pacific Cancer Biomarkers Market
Oncology
Metastatic Cancer Drug Market
Oncology
Global Cancer Treatment Market
Oncology
Stomach Cancer Treatment Market
Oncology
Paraneoplastic Syndromes Market
Oncology
South Korea Radiotherapy Market
Oncology
Liposarcoma Treatment Market
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Head and Neck Cancer Drugs Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
Head and Neck Cancer Market