
 Asia-Pacific Radiation Oncology Market | 2026-2036
Asia-Pacific Radiation Oncology Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Radiation Oncology Market Insights
Hospital procurement channels across Southeast Asia is tilting toward bundled service contracts that pair equipment with decade-long maintenance agreements. Varian Medical Systems leverages its installed base of linear accelerators to lock in recurring revenue streams across Australian and South Korean hospital networks. Elekta AB anchors its position through deep partnerships with Japan's academic radiation oncology departments, where research funding sustains premium pricing for stereotactic systems.
Radiation oncology encompasses the clinical use of ionizing radiation to treat malignant tumors, employing linear accelerators that generate X-ray or electron beams with energies ranging from 4 to 25 MeV to destroy cancer cells while sparing surrounding healthy tissue. The discipline serves as a cornerstone of multimodal cancer care, with roughly half of all cancer patients receiving radiation therapy during their treatment course. Linear accelerators and proton therapy systems command the dominant share of capital expenditure, reflecting their technical complexity and the concentrated expertise required for operation and maintenance. Intensity Modulated Radiation Therapy and Stereotactic Radiosurgery represent the fastest-expanding technology segments, driven by precision demands in brain tumor and lung cancer protocols where dose conformity directly correlates with reduced toxicity profiles.
Japan's PMDA maintains stringent device approval pathways that filter out lower-tier equipment vendors, while Australia's TGA alignment with MDR-equivalent standards elevates compliance costs for market entry. China's NMPA accelerates review timelines for domestically manufactured linear accelerators under its medical device innovation pathway, reshaping competitive dynamics for foreign suppliers. Stakeholders must weigh regulatory harmonization progress against the fragmentation of reimbursement schemes that govern patient access across the region's diverse healthcare systems.
Market Dynamics
China's NMPA innovation pathway for domestically manufactured linear accelerators is compressing procurement timelines for foreign equipment vendors while accelerating hospital network expansion across tier-one cities. This regulatory acceleration sits at the center of competitive restructuring across the region.
Growth Catalysts
- India's PLI scheme for medical devices:Domestic production incentives for linear accelerators reduce import dependency and lower total cost of ownership for hospital procurement committees evaluating capital budgets.
- Proton therapy capacity expansion:Cancer research centers across Thailand, Singapore, and Malaysia are installing dedicated proton facilities to serve high-complexity cases previously referred to overseas treatment hubs.
- Intensity Modulated Radiation Therapy protocols:Clinical adoption of IMRT for lung and brain tumor treatments drives replacement cycles for older cobalt-60 units in Australian and South Korean hospital networks.
Market Restraints
- Specialized physicist shortage:Training pipelines for medical physicists and radiation therapists lag equipment installation rates across Southeast Asian markets, constraining operational capacity.
- Import concentration for precision components:Multi-leaf collimators and klystron tubes depend on concentrated European and North American supplier bases, exposing procurement to currency volatility and lead time extension.
- Japan's PMDA device approval pathways:Stringent clinical data requirements filter lower-tier vendors and extend registration timelines, elevating compliance costs for novel stereotactic system entrants.
Strategic Opportunities
- Vietnam's underpenetrated provincial hospital networks:Government health infrastructure programs target equipping regional oncology centers with basic linear accelerator capacity outside Ho Chi Minh City and Hanoi corridors.
- Artificial intelligence treatment planning convergence:Integration of automated contouring algorithms with existing linear accelerator fleets promises workflow compression and staff productivity gains for high-volume departments.
- Telemedicine-enabled remote physics support:Satellite consultation models allow centralized academic centers to extend quality assurance oversight to distributed radiation oncology units in archipelago geographies.
Industry Challenges
- Legacy cobalt-60 unit decommissioning:Disposal of radioactive source materials requires specialized handling protocols and regulatory coordination that extend facility renovation timelines.
- Interoperability with hospital information systems:Linear accelerator data exchange with electronic medical record platforms demands custom interface development, complicating deployment in mixed-vendor environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Radiation Oncology Market |
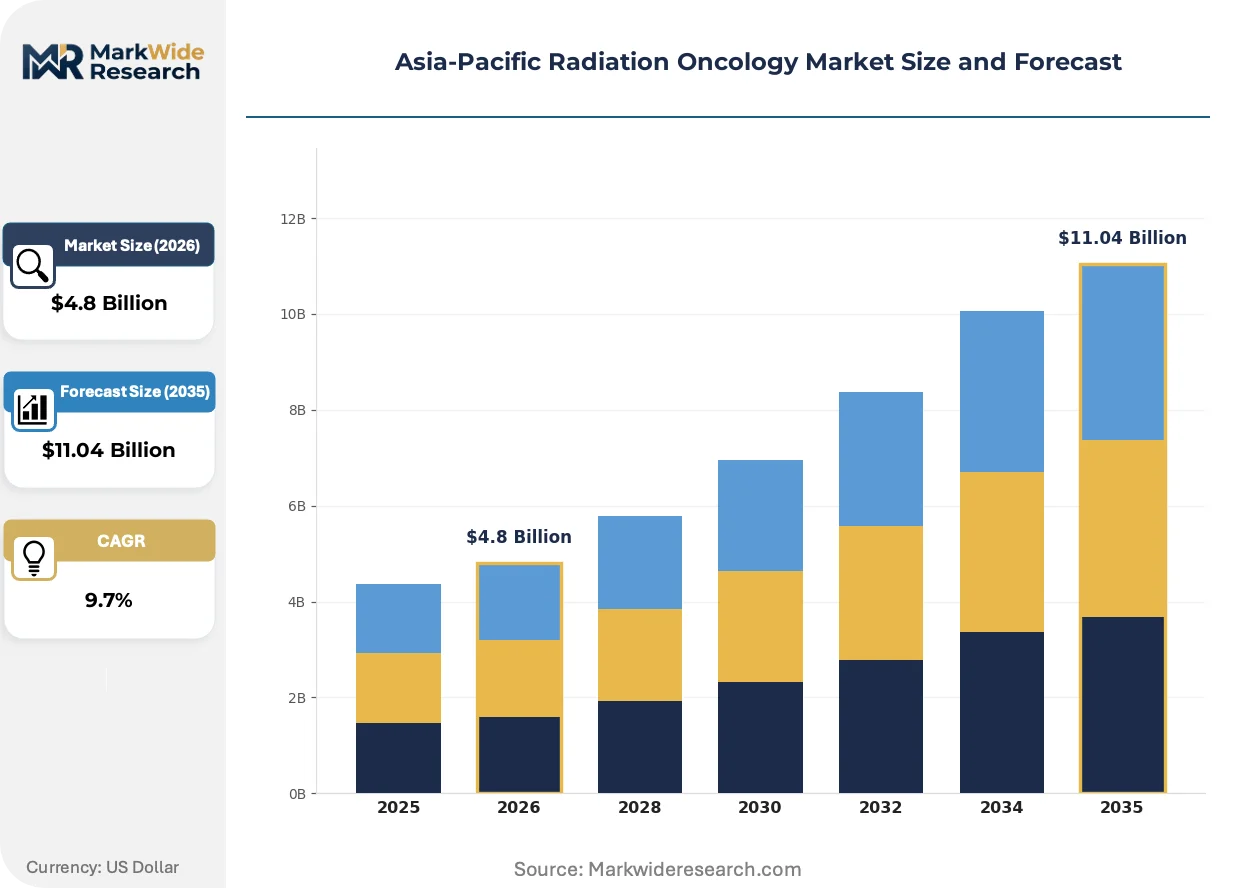
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, Brachytherapy, Treatment Planning Systems, Radiation Therapy Equipment Technology: 3D Conformal Radiotherapy, Intensity Modulated Radiation Therapy, Stereotactic Radiosurgery, Proton Therapy End User: Hospitals, Academic Institutions, Cancer Research Centers, Imaging Centers Application: Breast Cancer, Lung Cancer, Prostate Cancer, Brain Tumors |
| Companies Covered | Varian Medical Systems Inc, Elekta AB, Accuray Incorporated, IBA Worldwide, Becton Dickinson and Co, Mevion Medical Systems, NTP Radioisotopes, Siemens Healthineers, Nordion, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Radiation Oncology Market Trends and Innovations
Adaptive radiation therapy systems that modulate treatment plans based on daily anatomical changes are compressing the gap between diagnostic imaging and therapeutic delivery. This convergence of imaging and treatment modalities is restructuring capital allocation priorities across hospital procurement committees.
Magnetic resonance-guided linear accelerators combine real-time soft-tissue visualization with beam delivery, enabling motion-compensated treatment of abdominal and thoracic tumors. Major academic centers in Japan and Australia are prioritizing these systems for liver and pancreatic protocols. Cobalt-60 teletherapy units are rendering obsolete for curative-intent treatments in markets where reimbursement supports premium technology acquisition.
Australia's TGA alignment with MDR-equivalent standards elevates documentation requirements for software-as-medical-device components in treatment planning systems. This regulatory harmonization accelerates audit complexity for vendors maintaining multi-jurisdiction product registrations. Stereotactic radiosurgery platforms face extended conformity assessment timelines, prompting suppliers to front-load clinical evidence generation.
Hospital procurement committees across Southeast Asia are unbundling equipment acquisition from service agreements, competitively tendering maintenance contracts separately from capital purchases. This disintermediation of bundled pricing exposes pure-service providers to margin pressure while rewarding vendors with captive spare parts logistics. The shift is most visible in Indonesian and Philippine private hospital chains seeking operational expenditure flexibility.
Asia-Pacific Radiation Oncology Market Segmentation
Equipment replacement cycles and technology migration patterns vary sharply across radiation oncology hardware categories. Understanding these temporal dynamics helps procurement committees align capital budgets with clinical upgrade pathways and regulatory compliance timelines.
Product Type:
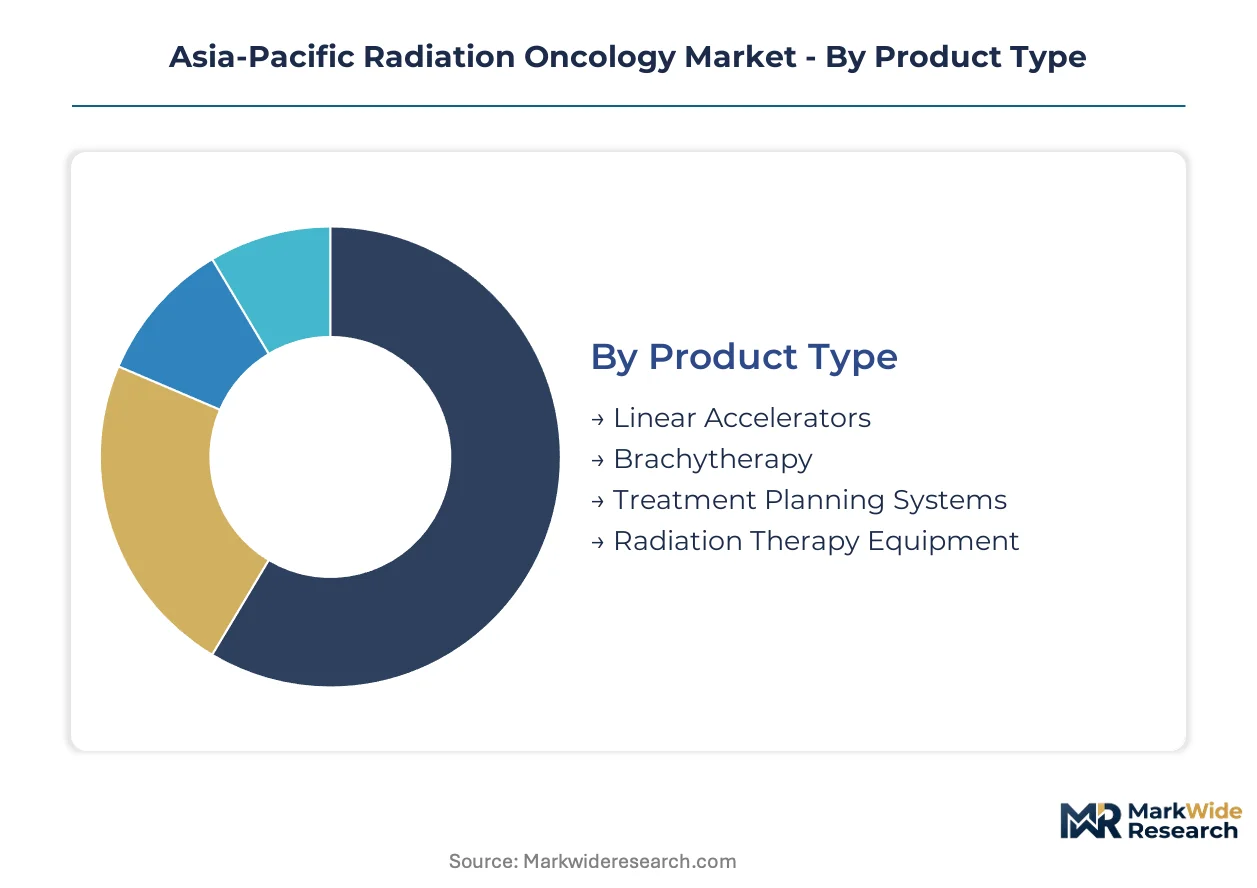
Linear accelerators turn over every 10-15 years with mid-cycle software upgrades, while brachytherapy systems persist 20+ years due to simpler mechanical architectures and shielding investments.
- Linear Accelerators:These devices generate X-ray or electron beams through microwave-accelerated electrons striking high-density targets. China's tier-one hospital networks are retiring cobalt-60 units for linear accelerator replacements under NMPA innovation pathway accelerations. India's PLI scheme is compressing total cost of ownership for domestically manufactured units.
- Brachytherapy:Internal radiation delivery systems place sealed radioactive sources directly within tumor cavities or adjacent tissue. Southeast Asian provincial hospitals favor these systems for cervical and prostate protocols where infrastructure constraints limit external beam capacity.
- Treatment Planning Systems:Software platforms integrating CT/MRI datasets with dose calculation algorithms for beam optimization.
- Radiation Therapy Equipment:Ancillary hardware encompassing immobilization devices, imaging verification systems, and quality assurance phantoms.
Linear accelerators dominate installed base. Treatment planning systems are where expansion concentrates.
Technology:
Capital intensity stratifies sharply across modalities, with proton therapy requiring 50-100x the infrastructure investment of 3D conformal systems.
- 3D Conformal Radiotherapy:Beam shaping through multi-leaf collimators conforms dose distributions to tumor geometry in three dimensions. Australian and South Korean hospital networks are phasing out these systems for IMRT upgrades where reimbursement supports premium technology acquisition.
- Intensity Modulated Radiation Therapy:Inverse planning algorithms modulate beam intensity across multiple angles to sculpt dose around critical structures. Japan's academic radiation oncology departments sustain premium pricing for these systems through research funding and complex case referrals.
- Stereotactic Radiosurgery:High-dose precision delivery to intracranial targets using rigid frame or frameless fixation systems.
- Proton Therapy:Charged particle beams deposit energy at Bragg peak depths with minimal exit dose.
3D conformal radiotherapy dominates installed base. Proton therapy is where expansion concentrates.
End User:
Procurement authority and budget cycles diverge between centralized health systems and fragmented private networks.
- Hospitals:General and specialized medical centers with dedicated radiation oncology departments operating linear accelerator fleets. China's tier-one hospital networks are building standalone radiation oncology towers with multiple vault configurations.
- Academic Institutions:University-affiliated medical centers combining clinical service with residency training and protocol development. Japan's PMDA stringent device approval pathways filter equipment vendors to established suppliers with extensive clinical data packages.
- Cancer Research Centers:Specialized facilities prioritizing experimental protocols and technology evaluation.
- Imaging Centers:Diagnostic facilities extending into therapeutic services through linear accelerator partnerships.
Hospitals dominate installed base. Cancer research centers are where expansion concentrates.
Application:
Dose conformity requirements and fractionation schedules drive technology selection across tumor sites.
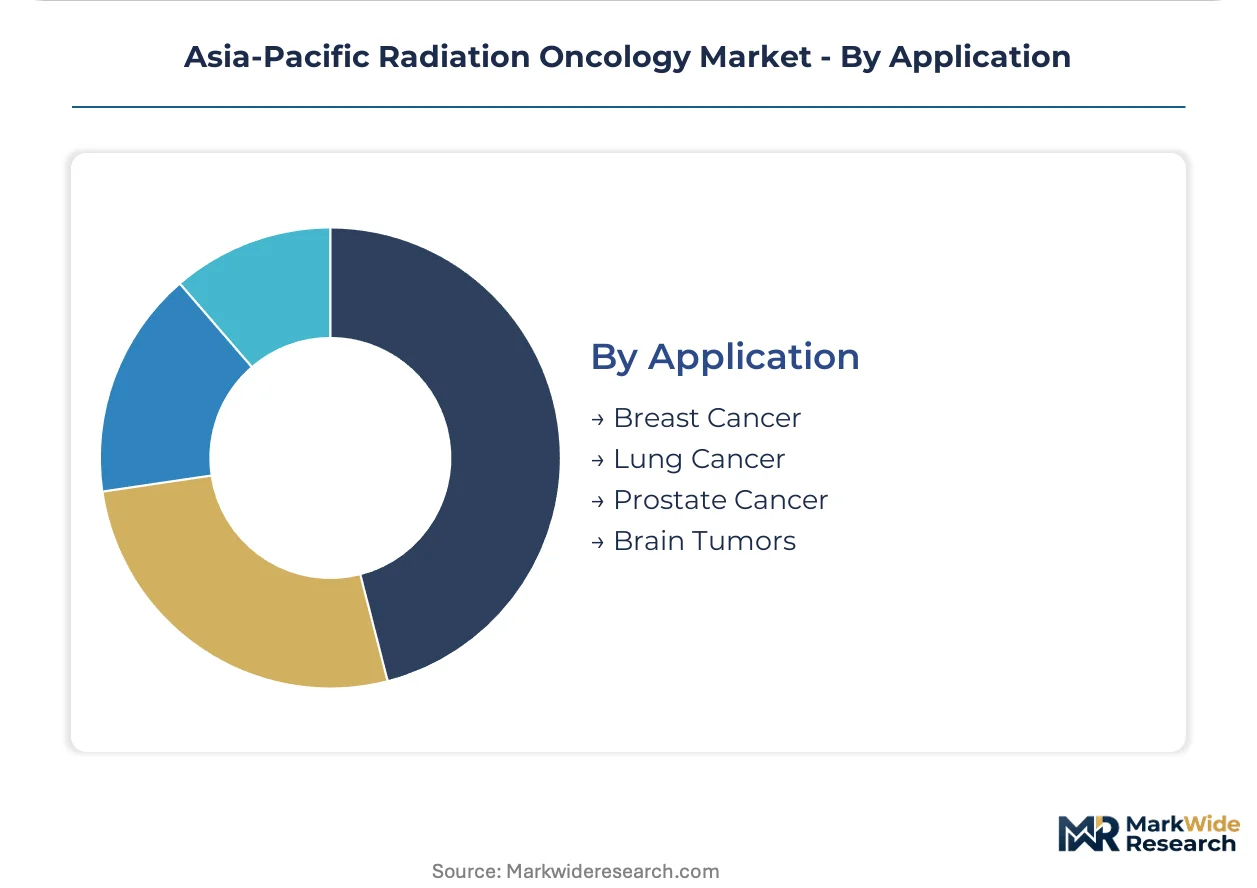
- Breast Cancer:Adjuvant and neoadjuvant radiation protocols following lumpectomy or mastectomy. Australian hospital networks prioritize hypofractionated schedules requiring advanced image guidance capabilities.
- Lung Cancer:Thoracic irradiation for non-small cell and small cell carcinomas with motion management challenges. China's high lung cancer incidence is accelerating stereotactic body radiation therapy adoption in tier-one cities.
- Prostate Cancer:Definitive and salvage radiation with dose escalation protocols.
- Brain Tumors:Primary and metastatic intracranial malignancies requiring sharp dose gradients.
Breast cancer dominates installed base. Lung cancer is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Kunming high-speed rail corridor underwrites China's central role in Asia-Pacific radiation oncology equipment distribution, connecting manufacturing clusters in the Yangtze River Delta to provincial hospital networks across the interior.
China
Tier-one hospital networks in Beijing, Shanghai, and Guangzhou are constructing dedicated radiation oncology towers with multiple vault configurations. The NMPA innovation pathway accelerates review timelines for domestically manufactured linear accelerators, compressing procurement cycles for hospital procurement committees. The Yangtze River Delta cluster around Shanghai anchors domestic production capacity under the medical device innovation pathway.
Japan
Academic radiation oncology departments in Tokyo, Osaka, and Nagoya sustain premium pricing for stereotactic systems through research funding and complex case referrals. The PMDA maintains stringent device approval pathways that filter lower-tier equipment vendors and extend registration timelines for novel entrants. The Kanto region around Tokyo concentrates the highest density of proton therapy facilities and stereotactic radiosurgery capacity.
India
Domestic production incentives under the PLI scheme reduce import dependency and lower total cost of ownership for hospital procurement committees evaluating capital budgets. CDSCO regulatory harmonization with international standards streamlines approval pathways for foreign equipment vendors establishing local manufacturing. Maharashtra and Karnataka host emerging linear accelerator assembly operations serving South Asian markets.
Australia
Hospital networks in Sydney, Melbourne, and Brisbane are phasing out cobalt-60 units for IMRT upgrades where reimbursement supports premium technology acquisition. The TGA alignment with MDR-equivalent standards elevates documentation requirements for software-as-medical-device components in treatment planning systems. The Southeast corridor between Sydney and Melbourne concentrates the majority of stereotactic body radiation therapy capacity.
South Korea
Replacement cycles for older cobalt-60 units accelerate as MFDS reimbursement frameworks expand coverage for intensity modulated radiation therapy protocols. The Seoul Capital Area dominates installed base concentration, with Busan-Ulsan emerging as a secondary hub for proton therapy capacity expansion. Government health technology assessment programs prioritize image-guided linear accelerator acquisitions in major metropolitan hospital networks.
Asia-Pacific Radiation Oncology Market Competitive Landscape
On the supply side, the industry is consolidating around equipment vendors with captive service infrastructure and installed base lock-in capabilities. The competitive terrain stratifies into three tiers: integrated system manufacturers with full hardware-software-service portfolios, specialized proton therapy developers with heavy infrastructure requirements, and regional assemblers leveraging domestic content incentives. Dominant competitive moves include long-term maintenance contract bundling with equipment sales and strategic partnerships with academic medical centers for clinical evidence generation.
Within the integrated system tier, Varian Medical Systems and Elekta AB exemplify vendors with extensive installed bases across Australian and Japanese hospital networks. Siemens Healthineers occupies a position bridging diagnostic imaging and therapeutic delivery modalities. These three entities represent the archetype of vendors capturing recurring revenue through decade-long service agreements and mid-cycle software upgrade pathways.
| Leading Market Players |
|---|
| Varian Medical Systems Inc |
| Elekta AB |
| Accuray Incorporated |
| IBA Worldwide |
| Becton Dickinson and Co |
| Mevion Medical Systems |
| NTP Radioisotopes |
| Siemens Healthineers |
| Nordion |
| Others |
Pricing and Supply Chain Analysis
German and Swiss precision component suppliers for multi-leaf collimators and klystron tubes concentrate upstream margin capture, forcing downstream equipment vendors to absorb currency volatility or pass through cost escalations to hospital procurement committees across Southeast Asia.
Pricing Analysis
Volume-discount tiering structures separate premium linear accelerator configurations with decade-long service bundling from standard systems with modular upgrade pathways and economy-tier cobalt-60 replacements. Price differentiation hinges on FDA-equivalent certification tiers and after-sales service density, with Australia's TGA-aligned MDR standards elevating documentation costs for software-as-medical-device components. Cost compression in standard-tier equipment intensifies as India's PLI scheme accelerates domestic manufacturing alternatives. Provincial hospital networks in Vietnam and Indonesia exhibit highest price sensitivity, while Japan's academic medical centers sustain premium tolerance through research funding channels.
Supply Chain Analysis
Supplier-financing facilities from European component vendors extend payment terms for multi-leaf collimator assemblies, easing working capital pressure on Asian equipment assemblers. Manufacturing concentration centers on Germany, Switzerland, and the United States for precision radiation hardware, with China expanding domestic linear accelerator production under NMPA innovation pathway accelerations. Raw material dependencies include high-purity tungsten for beam collimation, microwave-grade ceramics for klystron tubes, and superconducting magnets for proton therapy gantries. Single-source vulnerability in precision electron beam welding creates chokepoint exposure. Distribution runs through hospital procurement committees and government health infrastructure programs with tender-based allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities emerge across provincial hospital networks as government health infrastructure programs decentralize radiation oncology capacity beyond tier-one city corridors.
For Market Incumbents: Entrench installed base lock-in through captive spare parts logistics and decade-long maintenance contract renewal acceleration. Vertical integration into domestic assembly operations within India and China defends margin position against PLI-scheme beneficiaries. Threat of NMPA-favored domestic manufacturers demands accelerated software upgrade pathways to sustain switching costs. For New Entrants and Emerging Players: Vietnam's provincial oncology centers outside Ho Chi Minh City and Hanoi corridors represent the most penetrable entry point for basic linear accelerator capacity. Telemedicine-enabled remote physics support models address the specialized physicist shortage constraining operational scale. Go-to-market execution should anchor on government health infrastructure tender participation with localized service partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed proton therapy developers facing heavy infrastructure deployment timelines and extended reimbursement negotiation cycles. Long-term viability across the analysis window favors vendors with software-integrated hardware portfolios and recurring revenue density. Monitor NMPA approval velocity for domestically manufactured linear accelerators as inflection signal for foreign supplier displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| AI Treatment Planning Integration | Automated contouring algorithms compress workflow timelines for high-volume Japanese and Australian departments. |
| Domestic Manufacturing Partnership | PLI scheme alignment in India reduces import dependency and total cost of ownership for hospital buyers. |
| Proton Therapy Capacity Expansion | Thailand and Malaysia cancer research centers capture high-complexity cases previously referred overseas. |
| Telemedicine Physics Support | Satellite consultation models extend quality assurance oversight to distributed Indonesian and Philippine units. |
| Service Contract Unbundling Response | Separate maintenance tendering in Southeast Asian private chains demands operational expenditure flexibility. |
Research Methodology
The analysis maps linear accelerator hardware, proton therapy systems, brachytherapy platforms, and treatment planning software, each validated through hospital procurement managers, biomedical engineers, and GPO contracts specialists. Primary interviews with radiation oncology department heads and medical physicists across China, Japan, India, Australia, and South Korea combined with secondary validation from NMPA and PMDA device registration databases, hospital procurement records, and MFDS reimbursement framework documents. Bottom-up equipment installation tracking and top-down health expenditure triangulation anchored market sizing.
Assumption sets held regulatory approval timelines and reimbursement expansion trajectories fixed while varying domestic manufacturing incentive intensity and physicist training pipeline throughput across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user category, and application site with regional regulatory cluster overlays. CAGRs derived from equipment replacement cycle analysis and technology migration pattern correlation with named tumor incidence trends. Forecast inputs incorporated PLI scheme uptake rates and proton therapy facility commissioning schedules.
Practitioners should monitor NMPA approval velocity shifts, PLI scheme expansion scope, and physicist training program graduation rates for early signals of competitive restructuring. Forecasts reflect documented assumptions about reimbursement framework stability and regulatory harmonization progress. Macroeconomic currency volatility, tariff escalation on precision components, or technological breakthroughs in adaptive radiation therapy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Thyroid Cancer Market
Oncology
Metastatic Cancer Drug Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
Global Proton Therapy Market
Oncology
Small Cell Lung Cancer (SCLC) Treatment Market
Oncology
Global Particle Therapy Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Triple-Negative Breast Cancer Market
Oncology
Oncology Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market