
 Metastatic Cancer Drug Market | 2026-2036
Metastatic Cancer Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Metastatic Cancer Drug Market Foresight
A widening capability gap in biologics manufacturing scale is reorganizing competitive hierarchies across the metastatic cancer drug landscape. Pfizer Inc. leverages its multi-product cell culture infrastructure to supply blockbuster monoclonal antibodies at cost positions smaller rivals cannot match. F. Hoffmann-La Roche Ltd. anchors its position through sustained dominance in HER2-targeted and PD-L1 franchises across major markets. Novartis AG differentiates via radioligand therapy production, a segment where manufacturing complexity itself becomes a moat.
Metastatic cancer drugs comprise pharmaceutical agents designed to inhibit, arrest, or reverse the progression of malignant disease that has disseminated from a primary tumor site to distant organs, typically requiring systemic administration to achieve therapeutic concentrations across vascularized tissues. These agents function through mechanisms including immune checkpoint blockade, targeted kinase inhibition, cytotoxic DNA interference, or hormone receptor modulation, with formulation stability and bioavailability parameters dictating route of administration and dosing frequency. Immunotherapies command premium positioning as the fastest-expanding drug type, though chemotherapy agents retain substantial volume due to established reimbursement pathways and broad histologic applicability. The intravenous route still dominates administration, yet subcutaneous formulations are gaining structural importance as pressure mounts to shift care delivery from infusion centers toward lower-cost settings.
The FDA accelerates metastatic cancer drug review through breakthrough therapy and priority voucher programs, while the EMA's adaptive pathways pilot shapes European access timelines for conditional approvals. The IRA's Medicare price negotiation provisions are restructuring US commercialization assumptions for oncology products reaching designated eligibility thresholds. Stakeholders must monitor how manufacturing scale constraints intersect with evolving payer evidence requirements to determine which therapeutic modalities secure sustainable market access.
Market Dynamics
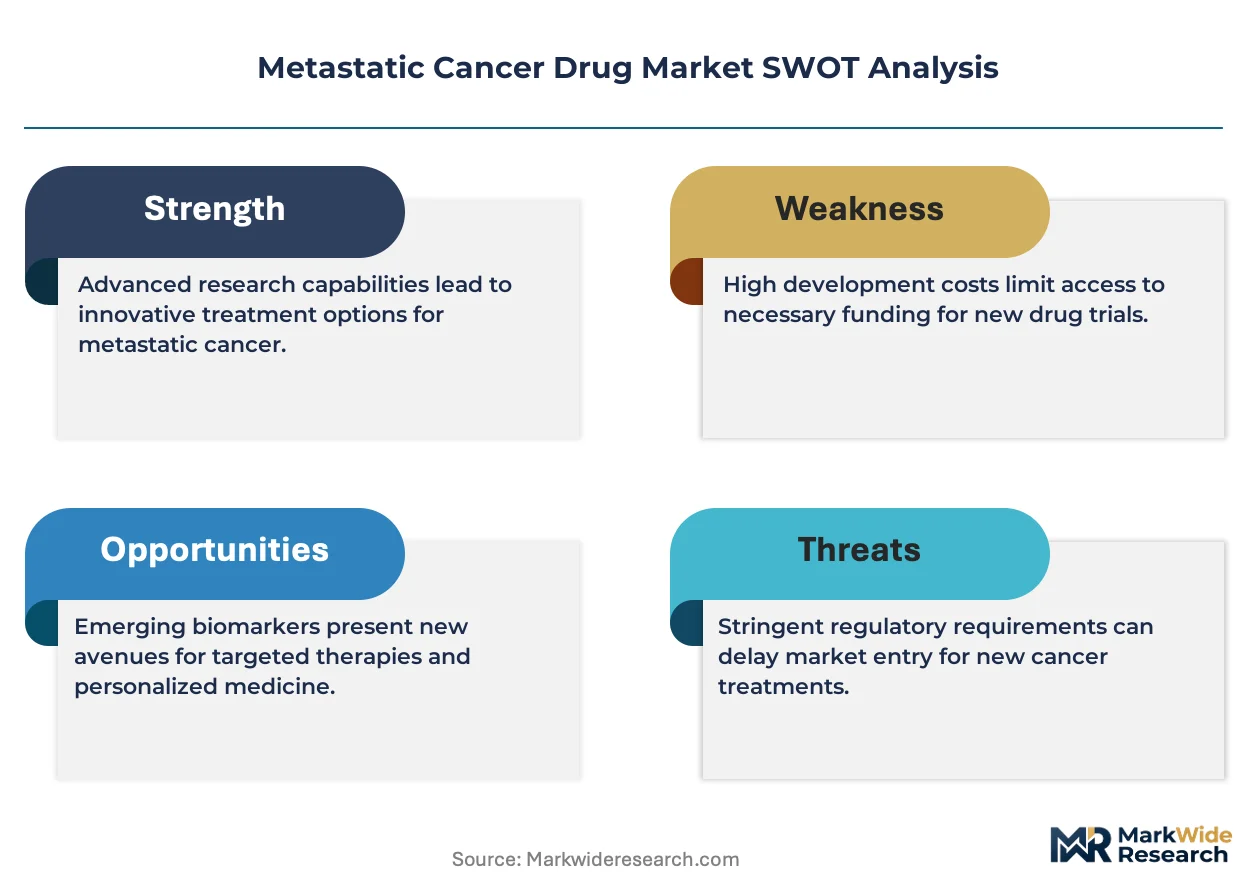
The metastatic cancer drug landscape is reconfiguring around manufacturing scale asymmetries, where multi-product biologics infrastructure determines which players can supply blockbuster therapies at cost positions smaller rivals cannot replicate. This structural concentration is compressing margins for non-integrated developers while rewarding asset-heavy incumbents with sustainable access to oncology clinic networks.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The FDA's accelerated review pathway compresses development timelines for agents demonstrating substantial improvement over existing options, expanding eligible treatment populations and hastening commercial launch windows.
- Radioligand Therapy Manufacturing:Complex isotope handling and radiochemistry capabilities create defendable production moats, with specialized facilities in the United States and Switzerland anchoring supply for this high-value modality.
- Medicare Infusion Center Expansion:United States oncology clinics are scaling intravenous capacity to accommodate rising patient volumes, creating pull-through demand for administered therapies with established reimbursement codes.
Market Restraints
- Plasma-Derived Raw Material Concentration:Biologics manufacturing depends on plasma fractionation inputs sourced predominantly from United States collection centers, exposing supply chains to geographic disruption risks.
- EMA Conditional Approval Evidence Requirements:European confirmatory trial obligations create regulatory friction for therapies approved under adaptive pathways, delaying full market access until post-marketing studies complete.
- Small-Molecule Kinase Inhibitor Substitution:Oral targeted agents are displacing intravenous chemotherapy in several histologies, eroding volume for traditional cytotoxic infusions with entrenched reimbursement.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered biologics enable care migration from infusion centers to home settings, opening access to patients in rural United States regions distant from specialized cancer centers.
- IRA Medicare Price Negotiation Exemption Window:Small-molecule drugs face negotiation eligibility after nine years versus thirteen for biologics, creating incentive structure favoring large-molecule investment through 2030.
- Combination Immunotherapy Protocols:Pairing PD-1/PD-L1 checkpoint inhibitors with novel targeted agents or cancer vaccines expands addressable populations beyond monotherapy-responsive segments.
Industry Challenges
- Radiochemistry Talent Scarcity:Radioligand therapy production requires specialized nuclear pharmacy expertise that academic programs are not producing at scale, constraining manufacturing expansion timelines.
- Legacy Clinical Trial Infrastructure:Decentralized trial models clash with established site-based oncology research networks, creating friction in patient recruitment and data collection for novel agents.
- Multi-Product Biologics Facility Validation:Switching cell culture lines between monoclonal antibody campaigns demands extensive cleaning validation and regulatory filing, compressing operational flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metastatic Cancer Drug Market |
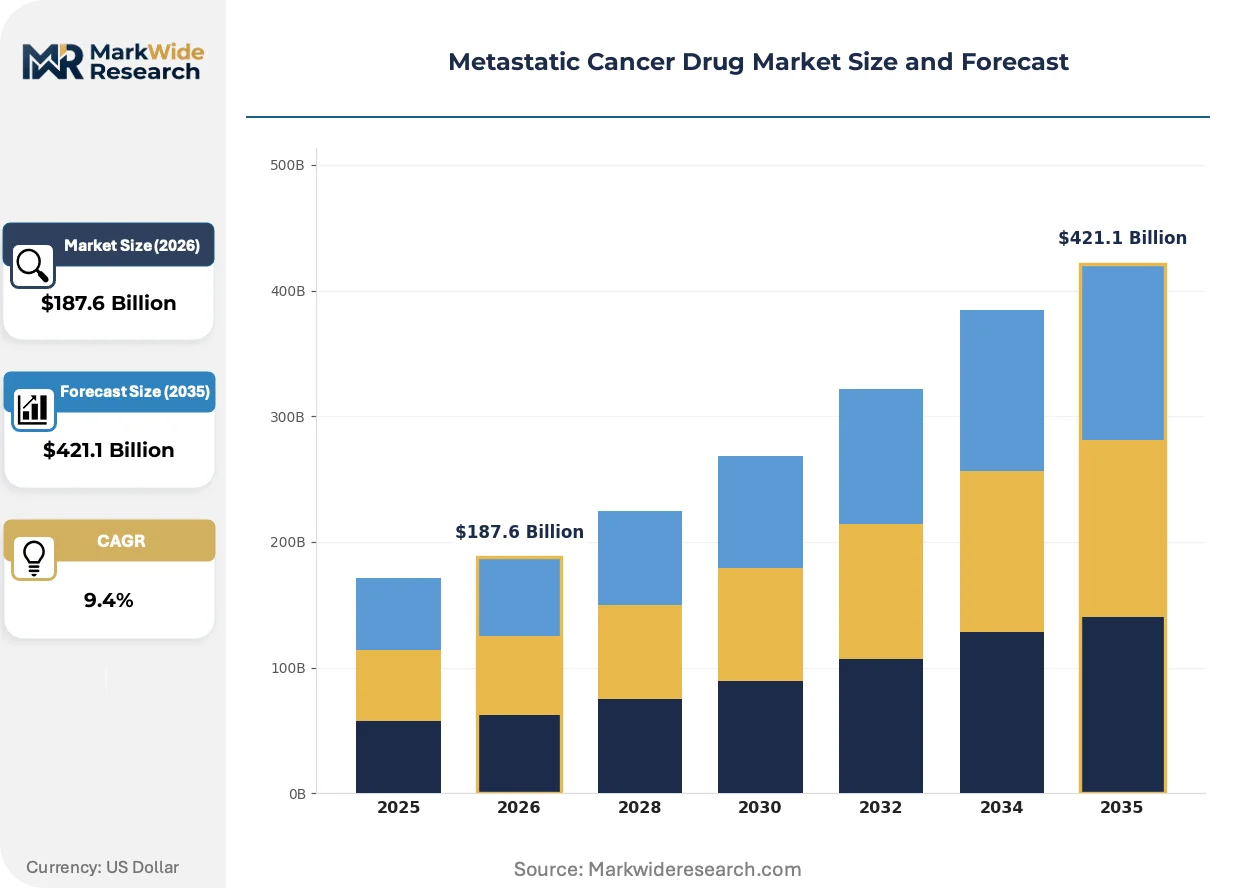
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $421.1 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Monoclonal Antibodies, Chemotherapy Agents, Targeted Therapies, Immunotherapies Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Oncology Clinics, Homecare Settings, Research Institutions Technology: Biologics, Small Molecule Drugs, Combination Therapies, Novel Drug Delivery |
| Companies Covered | Pfizer Inc., F. Hoffmann-La Roche Ltd., Novartis AG, AstraZeneca, Merck & Co., Inc., Bristol-Myers Squibb Company, Eli Lilly and Company, Johnson & Johnson, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metastatic Cancer Drug Market Shifts & Advancements
Antibody-drug conjugate engineering is advancing payload potency and linker stability, reshaping therapeutic indices for solid tumor indications. These molecular refinements are expanding addressable patient populations beyond prior chemotherapy-refractory cohorts.
Antibody-drug conjugate technology is bifurcating the metastatic breast and lung cancer treatment paradigms. Oncology clinics in the United States and Germany are adopting these agents as second-line standards ahead of traditional chemotherapy sequences. This shift is compressing clinical development timelines as developers race to secure positioning before competitive ADCs saturate the same mechanisms.
The IRA's Medicare price negotiation provisions are restructuring United States commercialization assumptions for oncology products reaching designated eligibility thresholds. Small-molecule developers face compressed revenue windows, redirecting pipeline investment toward biologic modalities with longer exclusivity periods. This policy-driven portfolio rebalancing is most pronounced among mid-cap firms dependent on United States market access.
Patient preference for reduced clinic visit burden is accelerating subcutaneous formulation adoption across immunotherapy classes. United States payers are favoring these alternatives in prior authorization protocols, displacing intravenous equivalents in formulary positioning. This behavioral shift is most visible in melanoma and lung cancer segments where treatment duration extends across multiple years.
Metastatic Cancer Drug Market Segmentation
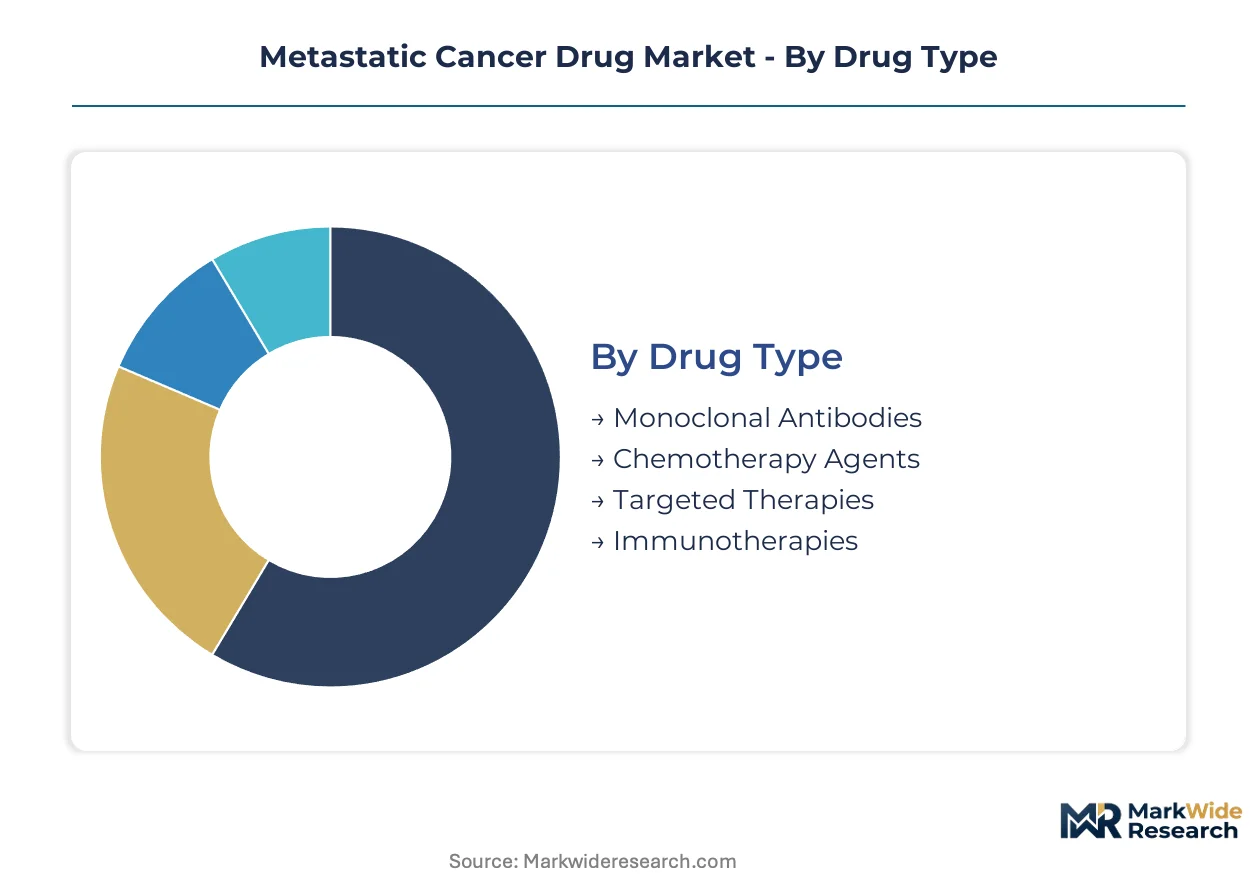
Segmentation in the metastatic cancer drug market reveals how therapeutic modality, delivery mechanism, and care setting intersect to determine commercial viability. Manufacturing scale requirements and reimbursement pathways vary dramatically across these dimensions, creating distinct competitive arenas.
Drug Type:
Domestic demand concentrates in immunotherapy and monoclonal antibody segments within the United States, while chemotherapy agents retain stronger export orientation toward emerging markets with constrained payer budgets.
- Immunotherapies:Engineered biologics that activate host immune responses against tumor antigens through checkpoint blockade or adoptive cell transfer. United States oncology clinics drive demand concentration as Medicare reimbursement for infused immunotherapies remains favorable against oral alternatives.
- Monoclonal Antibodies:Targeted protein therapeutics binding specific tumor-associated antigens to inhibit signaling or flag malignant cells for immune destruction. HER2 and PD-L1 franchises anchor United States and German hospital procurement, though biosimilar pressure is compressing margins in European markets.
- Chemotherapy Agents:Cytotoxic small molecules interfering with DNA replication or mitotic spindle formation. Demand persists in India and Brazil where cost constraints limit biologic penetration.
- Targeted Therapies:Kinase inhibitors and hormone modulators blocking oncogenic signaling pathways. Oral bioavailability enables home administration, expanding addressability in rural United States regions distant from infusion infrastructure.
Monoclonal antibodies hold the largest share; momentum sits with immunotherapies.
Administration Route:
Cost tier stratification separates hospital-based intravenous delivery from lower-acuity oral and subcutaneous alternatives, with reimbursement differentials determining prescribing patterns.
- Intravenous:Direct vascular infusion achieving immediate bioavailability for cytotoxic or biologic agents. United States infusion center expansion is pulling demand toward this route for combination regimens requiring precise dosing control.
- Subcutaneous:Depot formulations enabling self-administration with sustained pharmacokinetic profiles. Patient preference for reduced clinic burden is accelerating United States payer authorization for melanoma and lung cancer indications.
- Oral:Small-molecule formulations with gastrointestinal absorption. Kinase inhibitors are displacing intravenous cytotoxics in chronic myeloid leukemia and gastrointestinal stromal tumors.
- Intramuscular:Depot injections for hormonal agents in prostate and breast cancer. Limited to luteinizing hormone-releasing hormone agonists with established depot technologies.
Intravenous administration retains volume leadership; subcutaneous formulations are climbing the fastest.
End User:
Customer type fragmentation splits procurement between integrated health systems and independent oncology practices, with site-of-care policies reshaping distribution economics.
- Oncology Clinics:Specialized ambulatory centers administering infused therapies under physician supervision. United States community oncology networks are consolidating to negotiate favorable biologic purchasing terms.
- Hospitals:Acute care institutions managing complex metastatic cases with comorbidities. 340B drug pricing program participation shapes procurement patterns for covered entities.
- Homecare Settings:Patient residences enabling oral or subcutaneous administration. United States payers are expanding home infusion benefits for select biologics to reduce total cost of care.
- Research Institutions:Academic medical centers conducting early-phase clinical trials. Investigator-sponsored studies drive off-label utilization patterns that later influence regulatory submissions.
Oncology clinics hold the largest share; momentum sits with homecare settings.
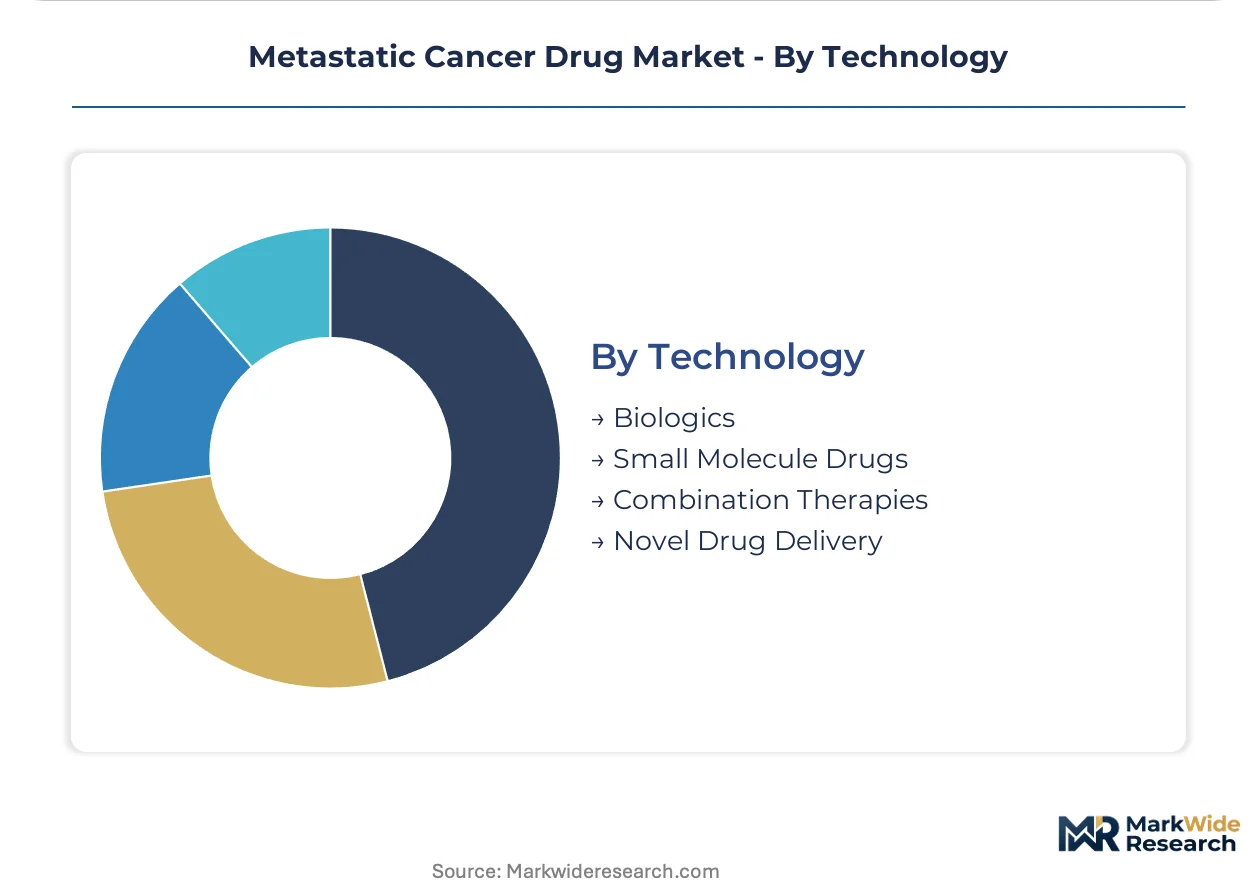
Technology:
Supply concentration in biologics manufacturing creates asymmetric access to capacity-constrained production networks, while small-molecule chemistry faces IRA-driven investment reallocation.
- Biologics:Large-molecule therapeutics produced in mammalian cell culture or microbial fermentation systems. Multi-product facilities in the United States and Switzerland anchor global supply for monoclonal antibodies.
- Combination Therapies:Protocols pairing checkpoint inhibitors with targeted agents, chemotherapy, or radiation. FDA breakthrough designations are compressing development timelines for PD-1 combination regimens.
- Small Molecule Drugs:Synthetic organic compounds with defined chemical structures. IRA Medicare price negotiation eligibility at nine years is redirecting pipeline investment toward biologic modalities.
- Novel Drug Delivery:Antibody-drug conjugates, radioligand therapies, and nanoparticle formulations. Radiochemistry capabilities in the United States and Switzerland constrain manufacturing expansion for radioligand agents.
Biologics hold the largest share; combination therapies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across oncology markets. United States buyers absorb premium pricing for novel immunotherapies, while Indian and Brazilian procurement prioritizes cost-minimized chemotherapy agents.
United States
Medicare reimbursement for infused biologics sustains demand concentration in oncology clinics. The IRA's price negotiation provisions compress revenue windows for small-molecule drugs reaching nine-year eligibility. Boston and San Francisco biotech clusters anchor radioligand therapy manufacturing expansion.
Germany
Hospital procurement networks drive demand for HER2-targeted monoclonal antibodies through centralized tendering. EMA adaptive pathways accelerate conditional approvals for breakthrough oncology agents. The Rhine-Ruhr region concentrates radiochemistry expertise for novel drug conjugate production.
Japan
Aging demographics expand addressable patient populations for chronic administration regimens. PMDA's sakigake designation system compresses review timelines for innovative cancer therapies. The Kanto region around Tokyo hosts specialized infusion center networks for immunotherapy delivery.
India
Cost-constrained public health programs sustain volume demand for generic chemotherapy agents. CDSCO accelerated approval pathways for oncology drugs reduce time-to-market for domestic manufacturers. Hyderabad and Ahmedabad clusters specialize in small-molecule active pharmaceutical ingredient synthesis.
Switzerland
Specialized biologics manufacturing infrastructure commands premium positioning in global supply chains. Swissmedic's streamlined review processes attract developers seeking rapid European market entry. The Basel region anchors multi-product monoclonal antibody production for international distribution.
Metastatic Cancer Drug Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in metastatic cancer drug supply. Pfizer Inc., F. Hoffmann-La Roche Ltd., and Novartis AG occupy positions where multi-product biologics infrastructure determines sustainable cost positions. Strategic moves concentrate on radioligand therapy manufacturing scale-up and subcutaneous formulation development to capture site-of-care migration.
Among Swiss and German pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd. and Novartis AG exemplify archetypes where manufacturing complexity itself creates competitive separation. United States-based Pfizer Inc. occupies a position representing integrated biologics supply chain control. These entities anchor tiered competitive positioning where facility validation capabilities and isotope handling expertise constrain rival expansion timelines.
| Leading Market Players |
|---|
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| AstraZeneca |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Eli Lilly and Company |
| Johnson & Johnson |
| Amgen Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between United States oncology clinics and biologics manufacturers lock in multi-year supply commitments while anchoring price visibility for infused immunotherapies. These contractual structures insulate blockbuster monoclonal antibody producers from spot-market volatility while exposing non-integrated developers to margin compression when raw material costs fluctuate.
Pricing Analysis
After-sales revenue from patient support programs and adherence monitoring services drives lifetime value for metastatic cancer drug portfolios. Three-tier pricing structure across premium, standard, and economy levels separates novel biologics with FDA breakthrough designation from biosimilar equivalents and generic chemotherapy agents. Pricing pressure stems from the IRA's Medicare negotiation provisions compressing revenue windows for small-molecule drugs. Community oncology practices in rural United States regions exhibit highest price sensitivity, while academic medical centers anchor demand for premium-tier immunotherapies regardless of cost.
Supply Chain Analysis
Plasma fractionation capacity in the United States anchors global supply for monoclonal antibody production, creating a chokepoint where geographic concentration exposes manufacturers to collection center disruption risks. Mammalian cell culture media, single-use bioreactor systems, and isotope-handling infrastructure for radioligand therapies constitute critical input dependencies. Single-source vulnerability runs through Swiss and United States-based multi-product biologics facilities where regulatory validation timelines constrain rapid capacity expansion. Distribution runs through specialized cold-chain logistics networks serving oncology clinic networks and hospital infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough therapy designation and IRA-driven portfolio reallocation are accelerating disruption in metastatic cancer drug development, compressing commercialization timelines while redirecting investment toward biologic modalities with extended exclusivity periods.
For Market Incumbents: Fortify manufacturing scale advantages by expanding multi-product cell culture capacity in United States and Swiss hubs before radiochemistry talent scarcity constrains rival expansion. Deepen backward integration into plasma fractionation inputs to mitigate geographic supply disruption risks from concentrated United States collection centers. Lock in long-term offtake contracts with consolidating community oncology networks to defend channel access against emerging subcutaneous formulation competitors. For New Entrants and Emerging Players: Homecare administration support services represent an under-served layer where incumbent biologics manufacturers under-invest in patient training and remote monitoring infrastructure. Target rural United States regions distant from specialized cancer centers where subcutaneous immunotherapy formulations enable care migration from infusion centers. Pursue partnership-based go-to-market models with home health agencies rather than direct oncology clinic channel builds. For Investors and Strategic Acquirers: Radioligand therapy specialists with validated isotope-handling capabilities and existing FDA approvals present acquisition targets with defendable manufacturing moats. Long-term viability over the next decade hinges on portfolio positioning toward combination immunotherapy protocols and novel drug delivery platforms rather than single-agent chemotherapy substitutes. Monitor EMA conditional approval conversion rates as a signal of European market access durability for therapies approved through adaptive pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Radioligand Therapy Manufacturing Scale-Up | Specialized isotope-handling capabilities in United States and Swiss facilities constrain rival entry timelines. |
| Subcutaneous Formulation Development | Self-administered biologics enable care migration from infusion centers to home settings in rural United States regions. |
| Combination Immunotherapy Protocol Advancement | FDA breakthrough designations compress development timelines for PD-1 checkpoint inhibitor pairings with novel targeted agents. |
| Plasma Fractionation Backward Integration | Upstream control over United States collection center networks mitigates geographic concentration risks in biologics supply chains. |
| Community Oncology Network Consolidation Partnerships | Long-term offtake agreements with consolidating United States clinic systems defend channel access against emerging competitors. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare reimbursement databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market size estimates across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs before finalization. The analytical framework segmented the market by drug type, administration route, end user, and technology platform across the projection horizon. CAGRs were derived from treatment line expansion rates, biosimilar penetration curves, and regional regulatory cluster adoption patterns. Modeled inputs included infusion center capacity expansion in United States markets and radiochemistry talent pipeline constraints for radioligand therapy manufacturing.
Forecasts assume regulatory continuity in FDA breakthrough therapy pathways and EMA adaptive approval frameworks; material policy shifts would require re-modeling. Specific risk factors that could revise projections include IRA Medicare negotiation timeline acceleration, plasma collection center disruption events, and radiochemistry workforce expansion failures. Practitioners should keep alternative scenarios live as payer evidence requirements and manufacturing scale constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Immuno-Oncology Market
Oncology
Global HER-2 Negative Breast Cancer Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Tumor Infiltrating Lymphocytes Market
Oncology
Tumor Embolization Market
Oncology
Thymus Cancer Market
Oncology
Colorectal Cancer Screening Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Global Proton Therapy Market
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Lung Cancer Treatment Market
Oncology
Global Particle Therapy Market
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Precision Oncology Market