
 Gallbladder Cancer Treatment Market | 2026-2036
Gallbladder Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Gallbladder Cancer Treatment Market Intelligence
The bundling of diagnostic assays with targeted therapies is consolidating treatment pathways for specific patient cohorts. F. Hoffmann-La Roche leverages its extensive portfolio in both diagnostics and oncology to offer integrated solutions. Eli Lilly and Company specializes in developing novel small-molecule inhibitors for defined genetic mutations. Bristol-Myers Squibb dominates the immunotherapy space with its foundational checkpoint inhibitors.
Gallbladder cancer treatment encompasses a range of medical interventions designed to manage or eliminate malignant neoplasms originating in the gallbladder's epithelial lining. Therapeutic strategies often involve cytotoxic agents that disrupt DNA replication or targeted molecules that interfere with specific signaling pathways like EGFR or HER2. Immunotherapy, particularly checkpoint inhibitors, represents the fastest-growing therapy area, displacing older chemotherapy regimens in certain patient populations. Treatment administration is concentrating within Specialized Cancer Centers, which possess the infrastructure for complex intravenous drug delivery and patient monitoring.
Market access for new oncological drugs is governed by stringent approval processes from agencies like the US FDA, the European Medicines Agency (EMA), and China's NMPA. These bodies mandate extensive clinical trial data demonstrating safety and efficacy, which directly influences development timelines and costs. Stakeholders must now decide whether to prioritize biomarker-driven niche indications or pursue broader approvals in combination therapies.
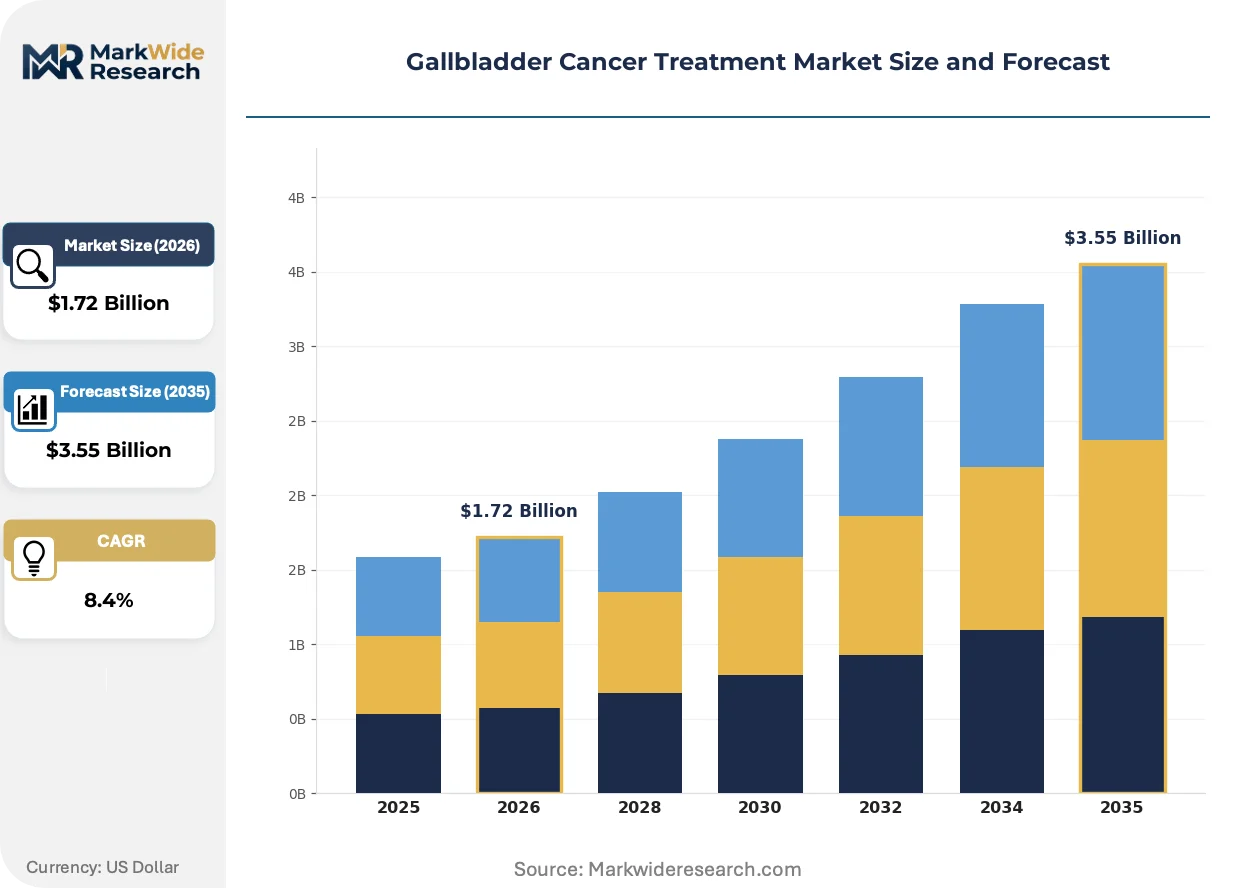
Market Dynamics
The convergence of diagnostics and therapeutics is the central force shaping the gallbladder cancer treatment landscape. This shift toward biomarker-driven personalization is altering clinical trial design, regulatory pathways, and the commercial strategies of pharmaceutical firms globally.
Growth Catalysts
- Advances in Genomics:Progress in next-generation sequencing allows for the rapid identification of actionable mutations like EGFR or HER2, enabling the use of targeted therapies and expanding the addressable patient population for these drugs.
- Expedited Approval Pathways:Regulatory frameworks, including the US FDA's Breakthrough Therapy designation and the EMA's PRIME scheme, accelerate the review process for promising oncological drugs, facilitating earlier market entry.
- Specialized Center Expansion:The increasing concentration of care within Specialized Cancer Centers in countries like the United States and Germany improves patient access to complex treatments and clinical trials, driving therapy utilization.
Market Restraints
- High Treatment Costs:The substantial price of novel immunotherapies and targeted agents creates significant financial barriers for healthcare systems and patients, limiting access in markets without robust reimbursement frameworks.
- Tumor Heterogeneity:The genetic diversity within and between gallbladder tumors complicates the development of universally effective therapies, leading to variable patient responses and limiting the success of monotherapies.
- Stringent Clinical Data Requirements:Regulatory bodies such as the EMA and China's NMPA mandate extensive clinical evidence for efficacy and safety, resulting in prolonged and costly development timelines for new oncological agents.
Strategic Opportunities
- Combination Therapy Regimens:Developing therapies designed for use in combination with existing checkpoint inhibitors or chemotherapies offers a path to improved efficacy and market differentiation, aligning with FDA guidance encouraging such trials.
- Liquid Biopsy Development:Investing in non-invasive liquid biopsy technologies for early detection, biomarker identification, and treatment monitoring presents a significant opportunity to guide therapy and improve patient outcomes.
- Emerging Market Penetration:Targeting regions in Asia with a higher incidence of gallbladder cancer through tailored pricing strategies and partnerships with local healthcare providers can unlock substantial volume growth.
Industry Challenges
- Biomarker Validation Complexity:Establishing the clinical utility of new biomarkers requires extensive validation, posing a significant hurdle for diagnostic and pharmaceutical developers seeking regulatory approval and payer coverage.
- Data Integration Hurdles:Integrating genomic data from diagnostic assays into hospital electronic health record systems remains a major operational challenge, hindering the seamless application of personalized medicine in routine clinical practice.
- Payer Reimbursement Fragmentation:Navigating inconsistent coverage policies for companion diagnostics and their associated targeted therapies across different national and private payers in the US and Europe complicates market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gallbladder Cancer Treatment Market |
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.55 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Adjuvant Therapy, Neoadjuvant Therapy, Palliative Care, Targeted Therapy, Immunotherapy Drug Class: Platinum Compounds, Antimetabolites, Tyrosine Kinase Inhibitors, Monoclonal Antibodies, Checkpoint Inhibitors Delivery Mode: Oral, Intravenous, Intraperitoneal, Subcutaneous, Transdermal End User: Specialized Cancer Centers, Oncology Clinics, Research Institutes, Community Clinics, Ambulatory Care Centers |
| Companies Covered | Eli Lilly and Company, Bristol-Myers Squibb, F. Hoffmann-La Roche, Pfizer, Novartis, AstraZeneca, Medtronic, Boston Scientific Corporation, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gallbladder Cancer Treatment Market Strategic Shifts & Innovations
The gallbladder cancer treatment market is being reshaped by the tightening integration of molecular diagnostics into standard clinical workflows. This movement is stratifying patient populations into smaller, more precisely defined cohorts, demanding new approaches to drug development and commercialization.
Companion diagnostics are tests designed to identify specific genetic markers, such as HER2 amplifications or EGFR mutations, prior to treatment. Specialized Cancer Centers are increasingly mandating these assays to guide the selection of targeted agents for patients with advanced or metastatic disease. The close pairing of a diagnostic test with a specific drug is consolidating treatment pathways, creating highly defined patient segments that require tailored therapeutic strategies.
Regulatory harmonization efforts, such as the US FDA's Project Orbis, are streamlining the global approval process for new oncology drugs. This initiative allows for concurrent submission and review of cancer therapies among international partners like Health Canada and Australia's TGA. The primary consequence is a reduction in duplicative clinical trials and a more predictable, accelerated path to market across multiple countries, particularly benefiting therapies for rare, biomarker-defined cancers.
A notable demand-side shift involves the adoption of evidence-based clinical pathways by major hospital networks and oncology group purchasing organizations. These structured care protocols standardize treatment decisions based on clinical evidence, efficacy, and financial value, often favoring therapies with companion diagnostics. This trend is most advanced in the United States and Germany, where reimbursement models increasingly reward adherence to standardized, high-value care models.
Gallbladder Cancer Treatment Market Segmentation
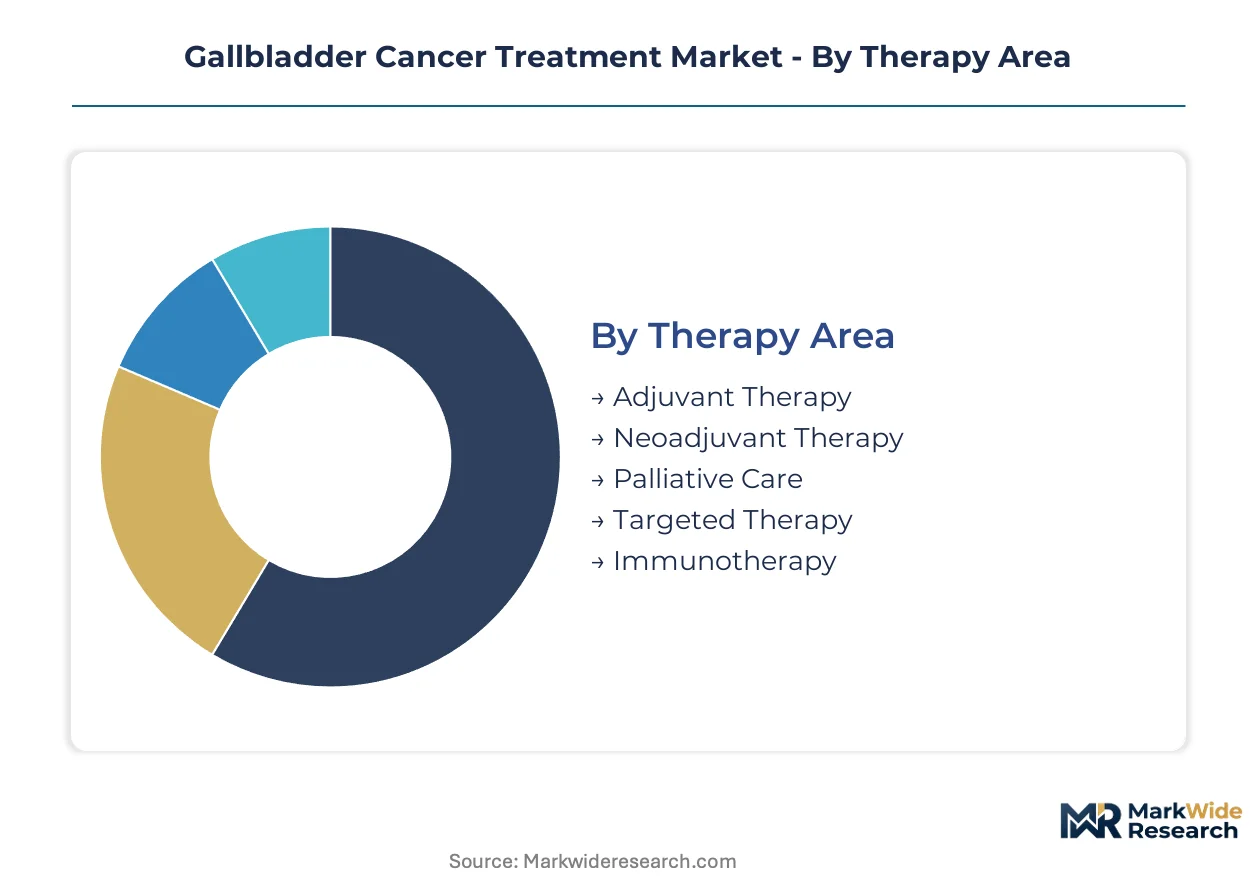
The gallbladder cancer treatment market categorizes therapies, drug classes, delivery methods, and end-user facilities to delineate distinct patient care pathways. These segmentations provide a granular view of where treatment resources are concentrated and how innovations are adopted. Understanding these divisions is crucial for tailoring strategies.
Therapy Area:
Segments within therapy area reflect varying capital investments and R&D expenditures required for market entry.
- Immunotherapy:This approach leverages checkpoint inhibitors to enhance the body's immune response against cancer cells. Demand concentrates in the United States and Germany, driven by supportive reimbursement for novel oncological treatments.
- Targeted Therapy:These treatments involve specific molecules designed to interfere with particular signaling pathways or genetic mutations like EGFR or HER2. Specialized Cancer Centers utilize these therapies, enabled by biomarker identification through next-generation sequencing.
- Adjuvant Therapy:Administered after primary treatment, this therapy aims to eliminate residual cancer cells and prevent recurrence.
- Neoadjuvant Therapy:Provided before main treatment, this strategy shrinks tumors, making them easier to remove.
- Palliative Care:Focused on relieving symptoms and improving quality of life for patients with advanced or incurable disease.
Adjuvant Therapy absorbs the bulk of installed capacity; Immunotherapy is expanding most quickly.
Drug Class:
The drug class segmentation highlights diverse mechanisms of action and their application focus in gallbladder cancer treatment.
- Checkpoint Inhibitors:These biological agents block immune checkpoints like PD-1 or CTLA-4, allowing the immune system to attack cancer cells. Specialized Cancer Centers frequently deploy these drugs, displacing older chemotherapy regimens.
- Tyrosine Kinase Inhibitors:Small-molecule drugs target specific tyrosine kinase enzymes involved in cancer cell growth and proliferation, particularly in tumors with EGFR or HER2 mutations. These inhibitors are increasingly prescribed for biomarker-positive patients.
- Platinum Compounds:Chemotherapy agents such as cisplatin or oxaliplatin induce DNA damage in cancer cells, inhibiting tumor growth.
- Antimetabolites:Drugs like gemcitabine or fluorouracil interfere with DNA and RNA synthesis, disrupting cell division.
- Monoclonal Antibodies:Biologic agents like trastuzumab target specific proteins on cancer cell surfaces, blocking their function.
Specific drug classes cater to distinct patient profiles, with Platinum Compounds addressing broad needs and Checkpoint Inhibitors focusing on niche.
Delivery Mode:
Delivery mode segments reflect varying patient convenience and infrastructure requirements for administration.
- Intravenous:This method administers drugs directly into the bloodstream via a vein, ensuring rapid bioavailability for complex oncological agents. Specialized Cancer Centers provide infrastructure for monitoring.
- Oral:Oral medications are taken by mouth, offering significant patient convenience and enabling self-administration outside clinical settings. Demand for oral therapies is rising in outpatient settings, driven by patient preference.
- Intraperitoneal:This mode involves delivering chemotherapy agents directly into the peritoneal cavity, allowing high local drug concentrations for abdominal cancers.
- Subcutaneous:Drugs administered via subcutaneous injection are delivered into the tissue under the skin, offering a less invasive alternative to intravenous infusions.
- Transdermal:This delivery method involves drug absorption through the skin via patches or gels, providing sustained release for palliative care.
While Intravenous remains the standard for potent agents, Oral modalities are gaining traction for enhanced patient comfort.
End User:
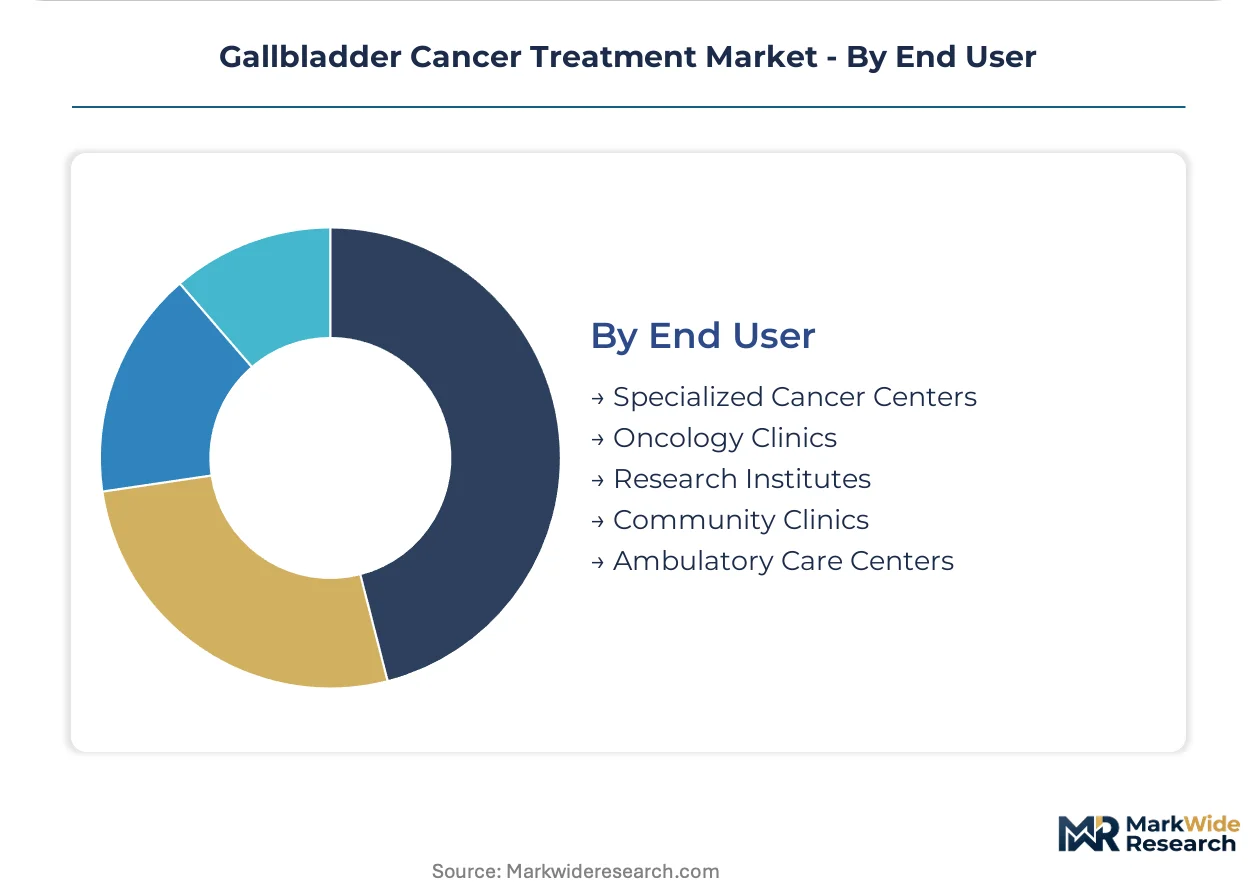
End user segmentation highlights specialized infrastructure and resource allocation required for gallbladder cancer treatment.
- Specialized Cancer Centers:These facilities offer comprehensive oncology services, including advanced diagnostics and clinical trials. Centers in the US and Germany are critical for complex intravenous drug delivery and rigorous patient monitoring.
- Oncology Clinics:Focused on outpatient cancer care, these clinics provide chemotherapy, targeted therapy, and immunotherapy administration, serving a broader regional patient base. They offer accessible treatment for standard regimens.
- Research Institutes:These institutions primarily focus on preclinical and clinical research, developing novel therapeutic agents and advancing cancer understanding.
- Community Clinics:Providing basic cancer screening, supportive care, and referrals, these clinics serve as initial points of contact.
- Ambulatory Care Centers:These facilities offer same-day medical procedures and treatments, including chemotherapy infusions, for patients not requiring hospitalization.
Specialized Cancer Centers drive innovation and complex care, while other settings ensure broader patient access to standard treatments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global gallbladder cancer treatment market shows a divide between regions driving innovation and those with high disease burden. Advanced economies like the United States and Germany lead in novel therapy consumption. This dynamic shapes R&D investment and market access strategies.
United States
The United States shows strong demand for advanced gallbladder cancer treatments, supported by high healthcare spending. US FDA's Breakthrough Therapy designation accelerates market entry for novel oncological drugs. Boston's biotech hub drives significant research into targeted therapies. Specialized Cancer Centers concentrate complex care delivery.
Germany
Germany demonstrates high adoption of personalized medicine and novel immunotherapies, supported by robust reimbursement frameworks. The EMA's PRIME scheme facilitates expedited review for promising oncological treatments. Munich's medical technology cluster focuses on integrating diagnostic assays with advanced therapeutic interventions.
Japan
Japan's aging population drives demand for effective gallbladder cancer treatments, with an increasing emphasis on precision medicine approaches. The PMDA streamlines approval processes for drugs targeting rare and orphan diseases. Tokyo's medical research institutions collaborate on genomic sequencing efforts to identify actionable mutations.
China
China faces a significant burden of gallbladder cancer, driving demand for accessible and innovative treatments amidst expanding healthcare infrastructure. China's NMPA accelerates review for innovative oncology drugs through priority pathways. Shanghai's biopharmaceutical parks attract investment for local development and manufacturing of cancer therapeutics.
India
India's growing patient pool for gallbladder cancer creates demand for affordable and effective treatment options. India's CDSCO simplifies regulatory pathways for biosimilars and generic oncology drugs. Bengaluru's medical technology startups develop cost-effective diagnostic assays for biomarker identification.
Gallbladder Cancer Treatment Market Key Industry Players
The competitive structure tilts toward a tiered landscape, with established pharmaceutical giants alongside specialized biotech firms. The market features large-cap diversified players, mid-size innovators focusing on niche indications, and emerging startups driving diagnostic integration. These firms often target biomarker-driven patient cohorts. Strategic partnerships for combination therapies and accelerated M&A activity for novel assets are dominant competitive moves. Companies are also expanding their portfolios through technology licensing.
Specialists in novel targeted therapies include Eli Lilly and Company, known for its focus on small-molecule inhibitors for defined genetic mutations. This company often targets specific signaling pathways. Bristol-Myers Squibb exemplifies a dominant position within the immunotherapy space, particularly with foundational checkpoint inhibitors. Its offerings are critical for immune-oncology treatment paradigms. F. Hoffmann-La Roche represents a diversified player leveraging an extensive portfolio in both diagnostics and oncology to offer integrated solutions. This approach consolidates treatment pathways for specific patient cohorts. These companies anchor innovation in personalized medicine pathways.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Bristol-Myers Squibb |
| F. Hoffmann-La Roche |
| Pfizer |
| Novartis |
| AstraZeneca |
| Medtronic |
| Boston Scientific Corporation |
| AbbVie |
| Others |
Cost & Logistics Intelligence
Active pharmaceutical ingredient (API) sourcing from Asian manufacturers influences the final cost structure of generic and biosimilar gallbladder cancer treatments. This dependency creates pricing tiers downstream, impacting market access for diverse patient populations.
Pricing Analysis
Cost-down pressure on established chemotherapy regimens accelerates due to increasing generic competition and evolving reimbursement policies. Value-based pricing models are increasingly adopted for novel targeted therapies and immunotherapies, reflecting their clinical efficacy and diagnostic integration. Price differentiation drivers include treatment efficacy, regulatory approval status from bodies like the US FDA, and the availability of companion diagnostics. Specialized Cancer Centers are less price-sensitive for breakthrough treatments, while broader oncology clinics prioritize cost-effectiveness for standard care.
Supply Chain Analysis
Biologics manufacturing for advanced immunotherapies rests on specialized facilities concentrated in the United States, Germany, and Ireland. Key raw material dependencies include cell culture media, specialized reagents for diagnostic assays, and proprietary drug delivery components. Geopolitical tensions impacting global shipping lanes present a structural risk to the timely supply of critical oncology drugs. Distribution runs through a highly controlled network, primarily involving specialized pharmaceutical distributors directly serving hospital pharmacies and oncology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gallbladder cancer treatment market is undergoing a significant consolidation play, with stringent clinical data requirements forcing smaller biotechs into strategic partnerships or acquisitions.
For Market Incumbents:To counter the threat of emerging generic competition, established pharmaceutical firms should prioritize investment in combination therapy trials for existing checkpoint inhibitors. Expanding market access strategies in underserved regions, particularly in Asia, represents a critical lever for volume growth. Pursuing expedited regulatory pathways like the US FDA's Breakthrough Therapy designation for novel indications can extend product lifecycles. Integrating companion diagnostics into existing portfolios strengthens a firm's position in personalized medicine.
For New Entrants and Emerging Players:Patients with rare genetic mutations in gallbladder cancer represent an underserved cohort for novel targeted therapies. Firms should focus on developing highly specific small-molecule inhibitors for these niche indications, leveraging advanced genomic sequencing. Partnering with Specialized Cancer Centers for early-phase clinical trials offers a targeted go-to-market angle. Developing non-invasive liquid biopsy technologies for early detection and treatment monitoring provides a significant white-space opportunity. Tailored pricing strategies for emerging markets can unlock substantial volume.
For Investors and Strategic Acquirers:Successful Phase 3 trial results for novel immunotherapies are the leading indicator that validates long-term market viability. Investors should target mid-sized biotech firms with strong intellectual property in biomarker-driven oncology or integrated diagnostic-therapeutic platforms. Expanded regulatory approvals from agencies like the EMA for combination regimens signal market maturity and reduced investment risk. A shift towards value-based reimbursement models across major healthcare systems warrants ongoing watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement for Combination Therapies | This initiative enhances efficacy and expands the addressable patient population for existing treatments. |
| Regulatory Approval via Expedited Pathways | Accelerated approval from bodies like the US FDA brings novel therapies to market faster. |
| Licensing Agreements for Diagnostic Technologies | These agreements integrate biomarker identification, streamlining patient selection for targeted drugs. |
| Manufacturing Scale-Up for Biologics | Increased production capacity supports growing demand for complex immunotherapy agents. |
| Partnerships for Emerging Market Penetration | Collaborations with local providers expand patient access in regions with high disease burden. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this market analysis. This was rigorously validated through primary interviews with oncologists, pharmaceutical R&D leads, specialized cancer center administrators, and regulatory affairs specialists. A comprehensive bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Data-stream reconciliation structured the analytical framework across the analysis window. Segmentation dimensions modeled included therapy area, drug class, delivery mode, end user, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected market drivers, incorporating inputs such as gallbladder cancer incidence rates and biomarker identification rates. This quantitative model provided robust market projections.
Revisions become necessary when significant clinical trial failures, unexpected reimbursement policy changes, or new competitive entries materialize. Forecasts reflect assumptions documented through extensive primary and secondary research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Asia Pacific Cancer Immunotherapy Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Metastatic Breast Cancer Market
Oncology
France Radiation Oncology Market
Oncology
Breast Cancer Therapy Market
Oncology
Europe Radiotherapy Market
Oncology
Thymus Cancer Market
Oncology
Adrenocortical Carcinoma Treatment Market
Oncology
Tumor Lysis Syndrome Market
Oncology
Solid Tumor Market
Oncology
Lung Cancer Treatment Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
America Cancer Immunotherapy Market
Oncology
Metastases Spinal Tumor Market
Oncology
North America Proton Therapy Market