
 Australia Cancer Treatment Market | 2026-2036
Australia Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Cancer Treatment Market Outlook
Software-defined biomarker testing and companion diagnostic subscriptions is rebalancing how pharmaceutical value gets captured in Australia. Roche Holdings AG leverages its diagnostics-oncology integration to anchor molecular profiling services alongside therapeutic portfolios. Novartis AG sustains leadership in radioligand therapy through specialized manufacturing partnerships with local nuclear medicine facilities. AstraZeneca differentiates via oncology R&D intensity directed at lung and gastrointestinal malignancies prevalent in Australian patient populations.
Cancer treatment encompasses systemic and localized therapeutic interventions designed to eliminate, control, or palliate malignant disease, utilizing cytotoxic agents, immune modulators, molecularly targeted compounds, and ionizing radiation delivered at doses measured in Gray units with millimeter-scale precision. Immunotherapy and targeted therapy represent the fastest-expanding product categories as TGA-approved checkpoint inhibitors and PARP inhibitors displace conventional chemotherapy in first-line settings for melanoma and ovarian cancer. Hospitals and specialized centers capture the dominant share of care setting value, though outpatient clinics are extending infusion capacity to reduce inpatient burden.
The Therapeutic Goods Administration governs clinical trial conduct and market authorization through its priority review and provisional approval frameworks, while the Pharmaceutical Benefits Scheme determines reimbursement access and pricing ceilings that directly shape prescribing patterns. State-level radiation safety regulations administered by health departments in Queensland, Western Australia, and South Australia impose facility licensing requirements that constrain radiotherapy capacity expansion. Stakeholders must monitor TGA alignment with FDA and EMA evidentiary standards as well as PBS listing timelines to anticipate competitive windows for novel modalities.
Market Dynamics
Therapeutic Goods Administration priority review pathways are compressing commercialization timelines for novel oncology modalities, reshaping how pharmaceutical firms sequence Australian market entry relative to other developed markets.
Growth Catalysts
- Expedited Approval Frameworks:TGA provisional approval and priority review mechanisms accelerate patient access to breakthrough therapies, reducing time-to-reimbursement under the Pharmaceutical Benefits Scheme.
- Metropolitan Hub Concentration:Sydney, Melbourne, and Brisbane treatment centers concentrate demand for precision oncology services, enabling economies of scale in molecular diagnostics deployment.
- Companion Diagnostic Integration:Software-defined biomarker testing platforms are embedding into clinical workflows, creating pull-through demand for targeted therapeutic portfolios.
Market Restraints
- Radiation Safety Licensing:State-level facility licensing requirements in Queensland, Western Australia, and South Australia constrain radiotherapy capacity expansion and capital deployment timelines.
- Reimbursement Ceiling Rigidity:Pharmaceutical Benefits Scheme pricing ceilings limit premium capture for innovative modalities, compressing margins on novel immunotherapy agents.
- Specialized Manufacturing Bottlenecks:Local nuclear medicine facility capacity restricts radioligand therapy supply, creating dependency on specialized manufacturing partnerships.
Strategic Opportunities
- Regional Hub Expansion:New South Wales and Victoria public hospital networks present whitespace for precision oncology service deployment beyond metropolitan cores.
- Outpatient Infusion Capacity:Ambulatory clinic channels offer alternative care settings to reduce inpatient burden and capture margin from episode-based reimbursement models.
- Diagnostic-Therapeutic Convergence:Integration of molecular profiling with therapeutic decision support creates subscription revenue models distinct from traditional pharmaceutical pricing.
Industry Challenges
- Radiopharmaceutical Supply Chain Complexity:Short half-life isotopes require just-in-time production coordination with nuclear medicine facilities, demanding specialized logistics infrastructure.
- Clinical Trial Recruitment Competition:Limited patient pools across melanoma and ovarian cancer indications intensify site activation timelines and investigator availability constraints.
- Legacy System Interoperability:Electronic health record fragmentation across state hospital networks impedes real-time biomarker result integration into treatment planning workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Cancer Treatment Market |
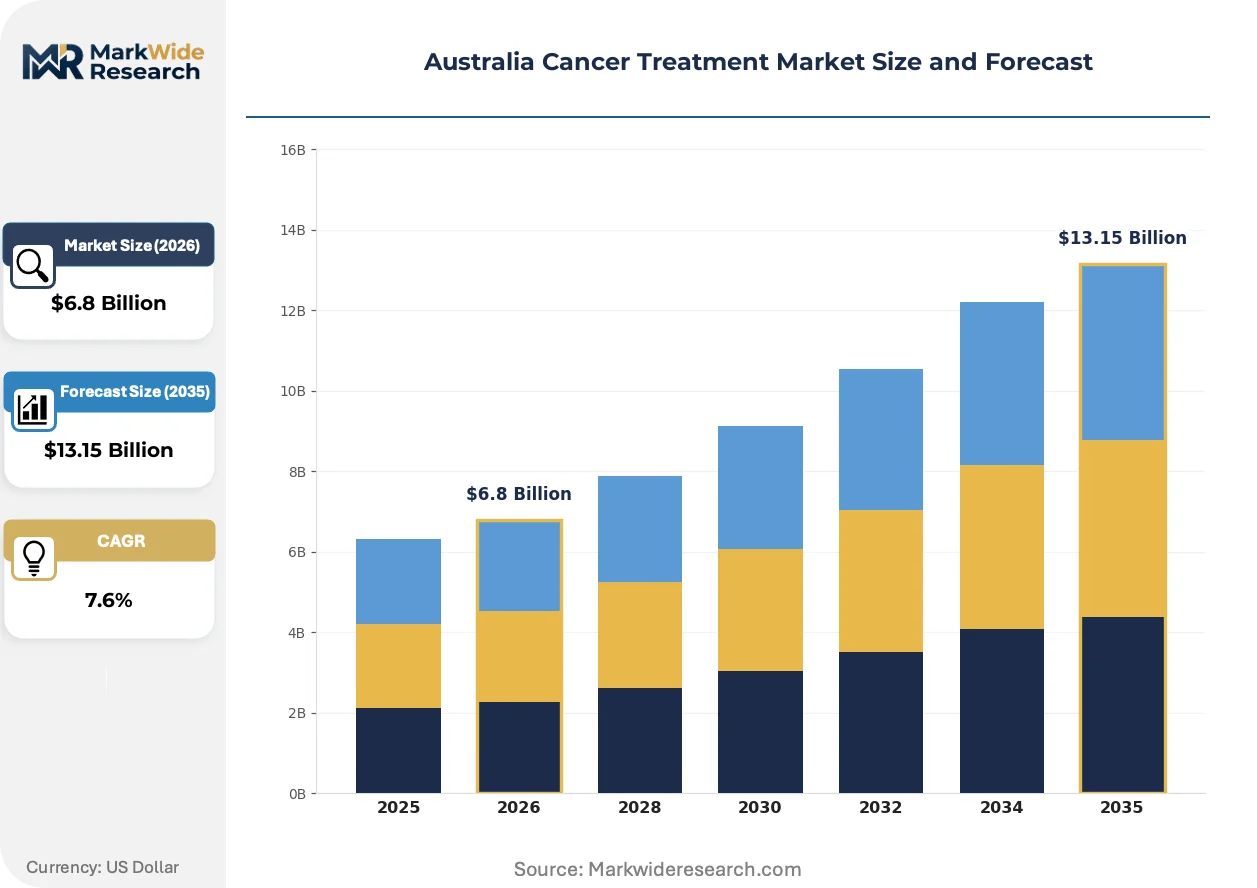
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiotherapy Treatment Stage: Prevention, Diagnosis, Treatment, Post-treatment Care Setting: Hospitals, Outpatient Clinics, Home Care, Specialized Centers End User: Patients, Healthcare Professionals, Insurance Providers, Caregivers |
| Companies Covered | Roche Holdings AG, Novartis AG, Pfizer Inc., Merck & Co., Inc., AstraZeneca, Johnson & Johnson, Bristol-Myers Squibb Company, AbbVie Inc., Telix Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Cancer Treatment Market Strategic Shifts
Software-defined diagnostic platforms are unifying molecular profiling with therapeutic selection algorithms, compressing the traditional sequential pathway from biopsy to treatment initiation across Australian oncology centers.
Artificial intelligence-enabled pathology analysis is unifying digital slide interpretation with genomic variant classification, enabling Royal College of Pathologists of Australasia-accredited laboratories to report comprehensive molecular profiles within shortened turnaround windows. Major teaching hospitals in Sydney and Melbourne are adopting these platforms at accelerated procurement cycles. This convergence is unifying diagnostic and therapeutic decision-making into single clinical encounters, reducing patient navigation burden.
TGA alignment with FDA and EMA evidentiary standards is reshaping trial design requirements for sponsors seeking Australian market authorization, particularly for checkpoint inhibitor and PARP inhibitor submissions. The regulator's acceptance of foreign clinical data reduces redundant local study requirements. Oncology sponsors are responding by sequencing Australian regulatory filings immediately following US and European submissions rather than deferring to later waves.
Episode-based reimbursement models are displacing fee-for-service chemotherapy administration across select private hospital networks in Victoria and Queensland. Bundled payment structures incentivize care coordination across medical oncology, pharmacy, and nursing functions. This shift is most visible in melanoma treatment pathways where immunotherapy regimens dominate first-line settings.
Australia Cancer Treatment Market Segmentation
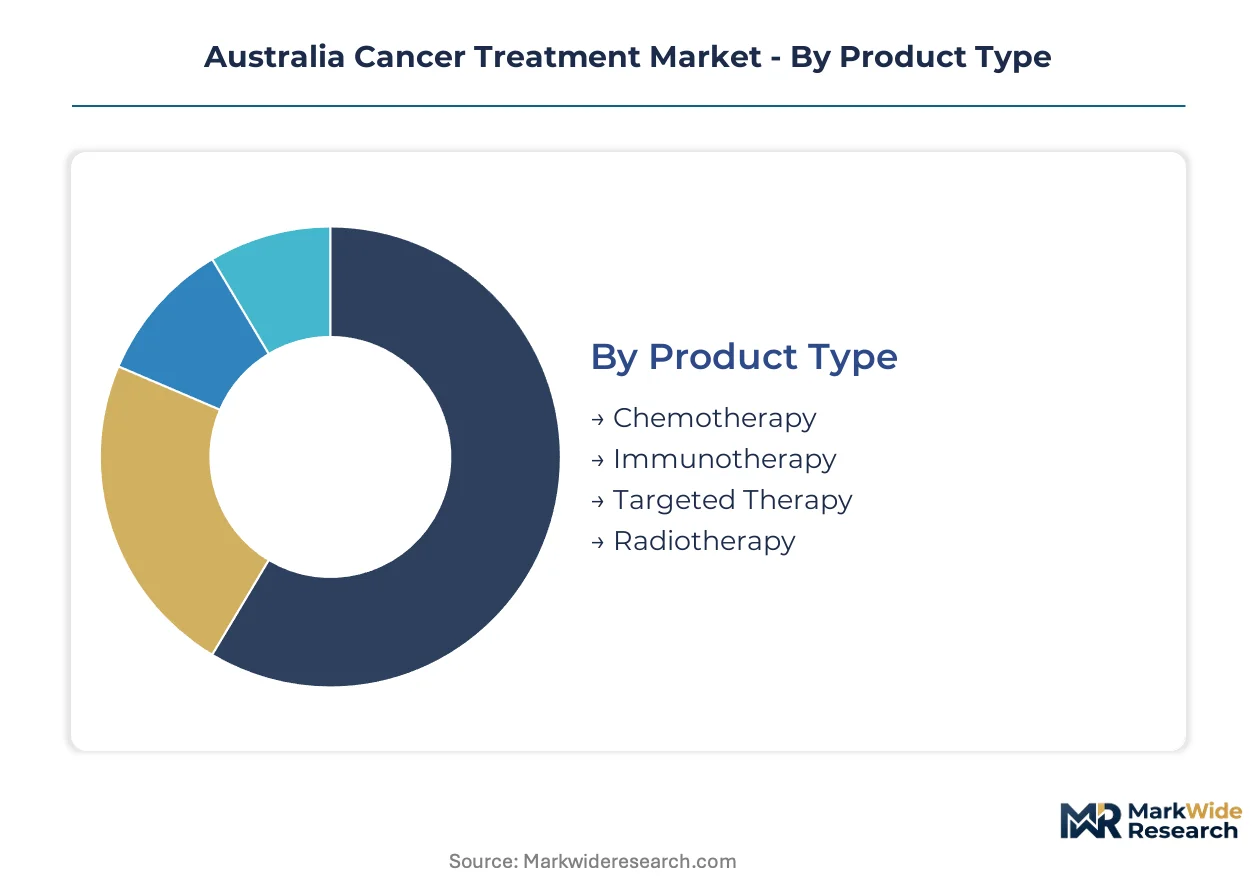
Segmentation in the Australia Cancer Treatment Market reveals how therapeutic innovation, care delivery economics, and reimbursement pathways intersect. Understanding these divisions exposes where pharmaceutical value capture concentrates and where structural bottlenecks constrain expansion.
Product Type:
Supply concentration in biologic manufacturing and radiopharmaceutical production facilities across New South Wales and Victoria shapes competitive positioning within each therapeutic modality.
- Immunotherapy:Checkpoint inhibitors and CAR-T cell therapies harness engineered immune responses against tumor antigens. Demand concentrates in metropolitan Sydney and Melbourne melanoma centers where TGA-approved pembrolizumab and nivolumab regimens displace first-line chemotherapy, constrained by cold-chain logistics requirements for cellular therapies.
- Targeted Therapy:Small-molecule inhibitors and monoclonal antibodies interrupt oncogenic signaling pathways with molecular precision. PARP inhibitors for BRCA-mutated ovarian cancer show fastest adoption in Brisbane teaching hospitals where companion diagnostic integration enables patient stratification.
- Chemotherapy:Cytotoxic alkylating agents, antimetabolites, and taxanes remain backbone therapy for hematologic malignancies and triple-negative breast cancer. PBS reimbursement ceilings compress margins on generic paclitaxel and carboplatin formulations.
- Radiotherapy:External beam and brachytherapy modalities deliver ionizing radiation measured in Gray units. State-level radiation safety licensing in Queensland and Western Australia restricts linear accelerator deployment timelines.
Today's leader: Immunotherapy. Tomorrow's challenger: Targeted Therapy.
Treatment Stage:
Cost tier differentiation separates high-margin therapeutic intervention from commoditized surveillance and supportive care functions across Australian oncology pathways.
- Treatment:Curative and palliative interventions spanning systemic therapy, surgery, and radiation. Revenue concentrates in hospital-based infusion centers where episode-based reimbursement models are displacing fee-for-service structures in Victorian private networks.
- Diagnosis:Imaging, biopsy, and molecular profiling services establish therapeutic eligibility. AI-enabled pathology platforms at Royal Melbourne Hospital and Royal Prince Alfred Hospital compress turnaround times for comprehensive genomic profiling.
- Prevention:Screening programs and risk-reduction interventions including HPV vaccination and tobacco cessation. Population health mandates drive public hospital participation in bowel and breast cancer screening.
- Post-treatment:Surveillance imaging, survivorship care, and recurrence monitoring. Community-based follow-up models in regional Queensland reduce tertiary center burden but fragment care coordination.
Today's leader: Treatment. Tomorrow's challenger: Diagnosis.
Care Setting:
Volume distribution across inpatient, ambulatory, and community channels reflects reimbursement incentives and capital intensity requirements for precision oncology infrastructure.
- Hospitals:Tertiary centers with integrated radiation oncology, surgical oncology, and clinical trial units. Public hospitals in New South Wales and Victoria anchor precision oncology service expansion through centralized molecular tumor boards.
- Specialized Centers:Dedicated cancer facilities with consolidated expertise in specific malignancies. Peter MacCallum Cancer Centre in Melbourne and Chris O'Brien Lifehouse in Sydney concentrate radioligand therapy capacity.
- Outpatient Clinics:Ambulatory infusion centers and day oncology units reducing inpatient bed utilization. Private clinic networks in Queensland extend capacity for immunotherapy administration outside hospital precincts.
- Home Care:Oral chemotherapy administration and supportive care delivery in residential settings. Oral PARP inhibitor and tyrosine kinase inhibitor regimens enable this shift, constrained by nursing visit reimbursement limitations.
Today's leader: Hospitals. Tomorrow's challenger: Specialized Centers.
End User:
Customer type segmentation distinguishes direct clinical decision-makers from financial intermediaries and informal care networks that shape treatment adherence and access patterns.
- Healthcare Professionals:Medical oncologists, radiation oncologists, and hematologists prescribing and administering therapy. Royal Australasian College of Physicians fellowship training pathways concentrate expertise in metropolitan hubs.
- Patients:Individuals receiving curative or palliative cancer care. Patient advocacy organizations in melanoma and ovarian cancer indications accelerate clinical trial recruitment and biomarker awareness.
- Insurance Providers:Private health insurers and Medicare Australia determining coverage scope and prior authorization requirements. Gap payment structures influence therapeutic selection in private hospital settings.
- Caregivers:Family members and informal support networks managing transportation, medication adherence, and adverse event monitoring. Regional patient travel assistance programs address geographic access barriers.
Today's leader: Healthcare Professionals. Tomorrow's challenger: Patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in cancer treatment production concentrate manufacturing capacity in jurisdictions with streamlined approval pathways and established nuclear medicine infrastructure. Australia captures radiopharmaceutical investment through TGA alignment with FDA evidentiary standards, reducing redundant clinical trial requirements.
New South Wales
Sydney metropolitan hospitals anchor precision oncology demand through centralized molecular tumor boards. The state health department's radiation safety licensing framework enables linear accelerator deployment at Chris O'Brien Lifehouse and Royal Prince Alfred Hospital. Public hospital networks in Western Sydney expand companion diagnostic integration beyond traditional metropolitan cores.
Victoria
Melbourne's Peter MacCallum Cancer Centre concentrates radioligand therapy capacity through specialized manufacturing partnerships with nuclear medicine facilities. State-level procurement reforms accelerate AI-enabled pathology platform adoption at Royal Melbourne Hospital. Regional hub expansion into Geelong and Ballarat extends precision oncology service deployment.
Queensland
Brisbane teaching hospitals drive fastest PARP inhibitor adoption through BRCA-mutated ovarian cancer patient stratification. The state radiation safety licensing requirements constrain radiotherapy capacity expansion timelines in regional centers. Private outpatient clinic networks extend immunotherapy infusion capacity outside hospital precincts.
Western Australia
Perth's tertiary centers manage geographic isolation through telemedicine-integrated molecular profiling workflows. State health department radiation facility licensing limits linear accelerator deployment to centralized metropolitan sites. FIFO medical oncology models address workforce scarcity in remote mining communities.
South Australia
Adelaide's specialized cancer facilities concentrate clinical trial recruitment for melanoma indications leveraging population-based screening data. State radiation safety regulations govern brachytherapy service expansion. Manufacturing partnerships with national nuclear medicine networks address radiopharmaceutical supply chain complexity.
Australia Cancer Treatment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated diagnostics-therapeutics groups capturing premium positioning in precision oncology while pure-play pharmaceutical firms compete on PBS reimbursement velocity. Market structure concentrates around three strategic archetypes: multinational conglomerates with diagnostics integration, mid-cap radiopharmaceutical specialists, and generic chemotherapy suppliers competing on manufacturing scale. Dominant competitive moves include diagnostic-therapeutic convergence partnerships and regional manufacturing joint ventures addressing radioligand supply constraints.
Within the multinational integrated tier, Roche Holdings AG and Novartis AG exemplify diagnostics-oncology convergence strategies, with the former anchoring molecular profiling services alongside therapeutic portfolios and the latter sustaining radioligand therapy leadership through specialized manufacturing partnerships. AstraZeneca occupies a position among R&D-intensive pharmaceutical groups directing oncology investment toward lung and gastrointestinal malignancies prevalent in Australian patient populations.
| Leading Market Players |
|---|
| Roche Holdings AG |
| Novartis AG |
| Pfizer Inc. |
| Merck & Co., Inc. |
| AstraZeneca |
| Johnson & Johnson |
| Bristol-Myers Squibb Company |
| AbbVie Inc. |
| Telix Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Public hospital network procurement consolidation across New South Wales and Victoria is concentrating purchasing power while tightening Pharmaceutical Benefits Scheme reimbursement ceilings, compressing margins on novel immunotherapy agents and forcing suppliers toward diagnostic-therapeutic bundling models.
Pricing Analysis
Capacity additions in Queensland and Western Australia are reshaping price floors for radiotherapy services as state-level radiation safety licensing delays constrain linear accelerator deployment. Episode-based reimbursement models in Victorian private networks displace fee-for-service structures, creating three-tier pricing stratification across premium immunotherapy, standard targeted therapy, and economy chemotherapy tiers. Cost compression in the chemotherapy segment intensifies due to generic paclitaxel and carboplatin PBS ceiling rigidity. Private health insurers demonstrate highest price sensitivity for outpatient infusion services, while specialized cancer centers retain pricing power for radioligand therapy.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume immunotherapy demand through cold-chain logistics partnerships concentrated in Sydney and Melbourne metropolitan hubs. Manufacturing capacity clusters in New South Wales and Victoria, with radiopharmaceutical production drawing from specialized nuclear medicine facilities at Peter MacCallum Cancer Centre and Royal Prince Alfred Hospital. Short half-life isotope requirements create single-source vulnerability for lutetium-177 and gallium-68 supply. Distribution runs through tertiary hospital procurement networks and private clinic group purchasing organizations, with regional hub expansion into Geelong and Ballarat extending geographic reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's TGA-FDA alignment on evidentiary standards creates a geographic-arbitrage opportunity for sponsors seeking faster commercialization timelines than European EMA pathways, while PBS pricing ceilings remain more rigid than US Medicare reimbursement flexibility.
For Market Incumbents: Anchor molecular profiling services alongside therapeutic portfolios to defend against diagnostic-therapeutic convergence pressure from Roche Holdings AG and Novartis AG. Deepen backward integration into companion diagnostic manufacturing through partnerships with Royal College of Pathologists of Australasia-accredited laboratories. Counter margin compression from PBS ceiling rigidity by shifting revenue toward subscription-based biomarker testing platforms. For New Entrants and Emerging Players: Launch via regional hub expansion into Western Sydney and Geelong where public hospital networks present whitespace for precision oncology deployment. Target PARP inhibitor and radioligand therapy segments where BRCA-mutated ovarian cancer patient stratification and nuclear medicine facility partnerships create penetrable entry points. Pursue TGA provisional approval pathways to compress time-to-reimbursement under PBS listing timelines. For Investors and Strategic Acquirers: Mid-cap radiopharmaceutical specialists with established TGA manufacturing partnerships are the most active acquisition targets in this space as multinational conglomerates seek radioligand therapy capacity. Long-term viability hinges on diagnostic-therapeutic convergence capabilities and AI-enabled pathology platform integration. Watch for TGA alignment shifts with FDA breakthrough therapy designation pathways as the inflection signal for regulatory arbitrage windows closing.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Convergence Partnership | Roche Holdings AG anchors molecular profiling services alongside therapeutic portfolios to capture subscription revenue. |
| Regional Hub Expansion | New South Wales public hospital networks extend precision oncology beyond Sydney metropolitan cores into Western Sydney. |
| AI-Enabled Pathology Platform Adoption | Royal Melbourne Hospital compresses genomic profiling turnaround through Royal College of Pathologists of Australasia-accredited laboratories. |
| Radioligand Therapy Manufacturing Partnership | Novartis AG sustains supply through specialized nuclear medicine facility agreements with Peter MacCallum Cancer Centre. |
| Episode-Based Reimbursement Transition | Victorian private networks displace fee-for-service structures with bundled payment models for melanoma immunotherapy pathways. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with medical oncologists, radiation oncologists, hospital procurement managers, and Pharmaceutical Benefits Scheme formulary directors with secondary validation through TGA submission databases, ClinicalTrials.gov records, PBS listing decisions, and state health department radiation safety licensing registers. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimates.
Segment-weighting approaches applied treatment stage, care setting, and therapeutic modality dimensions across the projection horizon, with CAGRs derived from historical PBS expenditure trends and TGA approval velocity analysis. Forecast inputs incorporated immunotherapy adoption curves in melanoma and ovarian cancer indications, radioligand therapy manufacturing capacity constraints, and AI-enabled pathology platform procurement cycles at major teaching hospitals.
Forecast precision tightens around the base case; tail outcomes carry wider variance under TGA regulatory alignment shifts or PBS reimbursement policy changes. Periodic stress-testing of base assumptions is recommended, particularly regarding state-level radiation safety licensing timelines and radiopharmaceutical supply chain disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Radiation Therapy Software Market
Oncology
Pancreatic Cancer Market
Oncology
Tumor Embolization Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Global Hurthle Cell Carcinoma Treatment Market
Oncology
North America Veterinary Oncology Market
Oncology
Ovarian Cancer Market
Oncology
Breast Cancer Brachytherapy Market
Oncology
PD1 Resistant Head and Neck Cancer Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Outpatient Oncology Infusion Market
Oncology
Colorectal Cancer Screening Market