
 Europe Gas Turbine Market | 2026-2036
Europe Gas Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gas Turbine Market Foresight
Power generation is decoupling from baseload-only contracting as European utilities add flexible gas turbines to backstop wind and solar variability. Siemens Energy dominates hydrogen-combustion development through its Berlin turbine R&D center. MAN Energy Solutions anchors the mechanical-drive segment with specialized compressor-train integrations for North Sea upstream operations. Ansaldo Energia competes on repowering expertise, extending unit life for aging Italian and Spanish combined-cycle plants.
Europe gas turbines are rotating thermal engines that convert pressurized combustion gases into shaft power through axial compressor-turbine arrangements, typically achieving firing temperatures exceeding 1,400°C in advanced heavy-duty configurations. Their primary purpose spans electricity generation, mechanical drive for pumps and compressors, and combined heat-and-power delivery across industrial facilities. Heavy-duty turbines occupy the largest installed base due to their 100-400 MW output range suited to utility-scale combined-cycle deployment. Aero-derivative turbines represent the fastest-expanding product category, as their rapid start-up capability aligns with grid-balancing requirements in markets with high renewable penetration. Cogeneration applications command premium margins where district heating networks in Denmark, the Netherlands, and Poland create sustained thermal offtake.
The EU Green Deal, F-Gas Regulation, and CE marking under the Machinery Directive collectively mandate progressive carbon-intensity reductions and refrigerant containment standards that reshape turbine procurement specifications. ECHA's REACH framework restricts certain nickel-alloy coatings and thermal-barrier materials, forcing OEM supply-chain requalification. National regulators in Germany, France, and Italy layer additional emissions-performance requirements through transposed Industrial Emissions Directive permits. Stakeholders must monitor hydrogen-blending readiness certifications and carbon-border-adjustment implementation timelines to align capital commitments with evolving compliance thresholds.
Market Dynamics
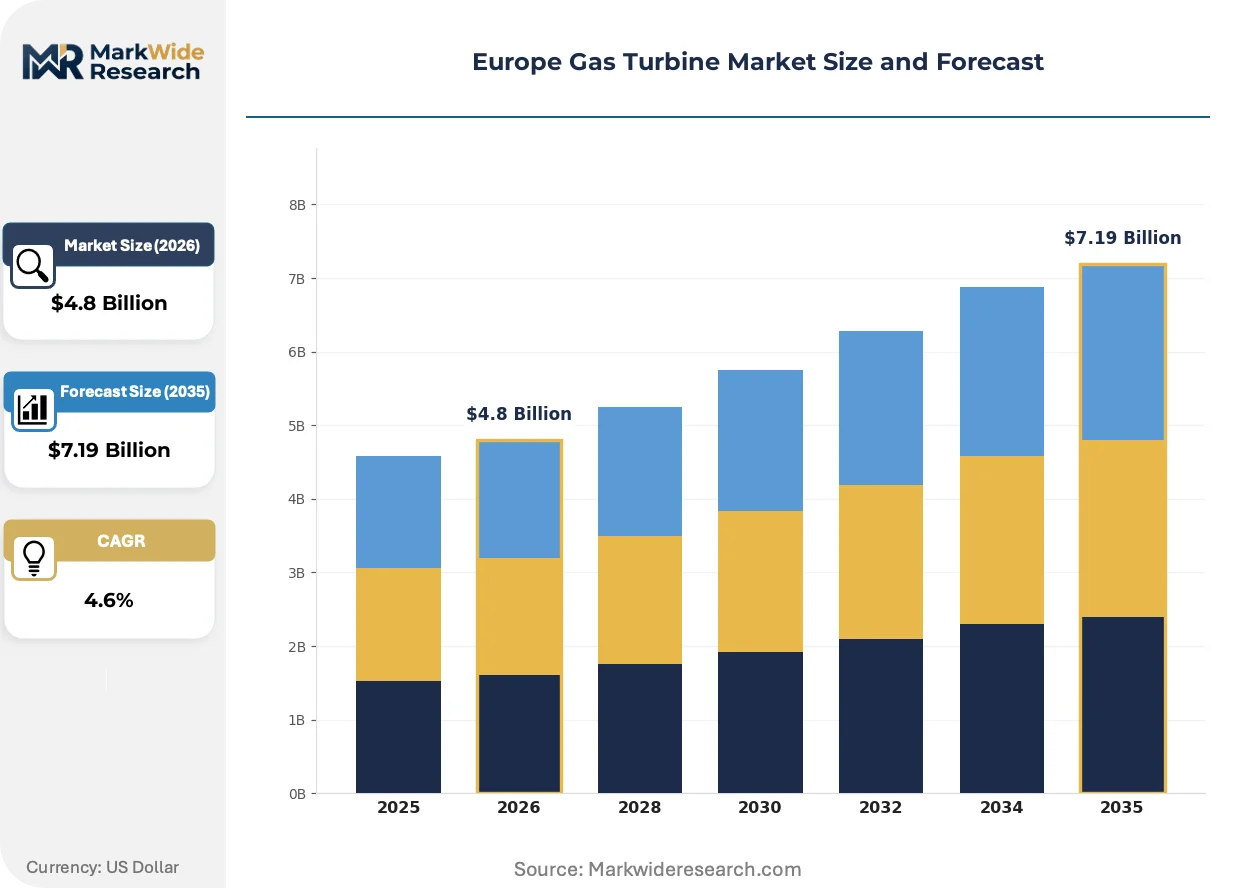
European utilities are retrofitting existing combined-cycle fleets for hydrogen co-firing to retain asset value under tightening EU Green Deal carbon budgets. This retrofit imperative is compressing OEM service backlogs and reshaping spare parts procurement priorities across the continent.
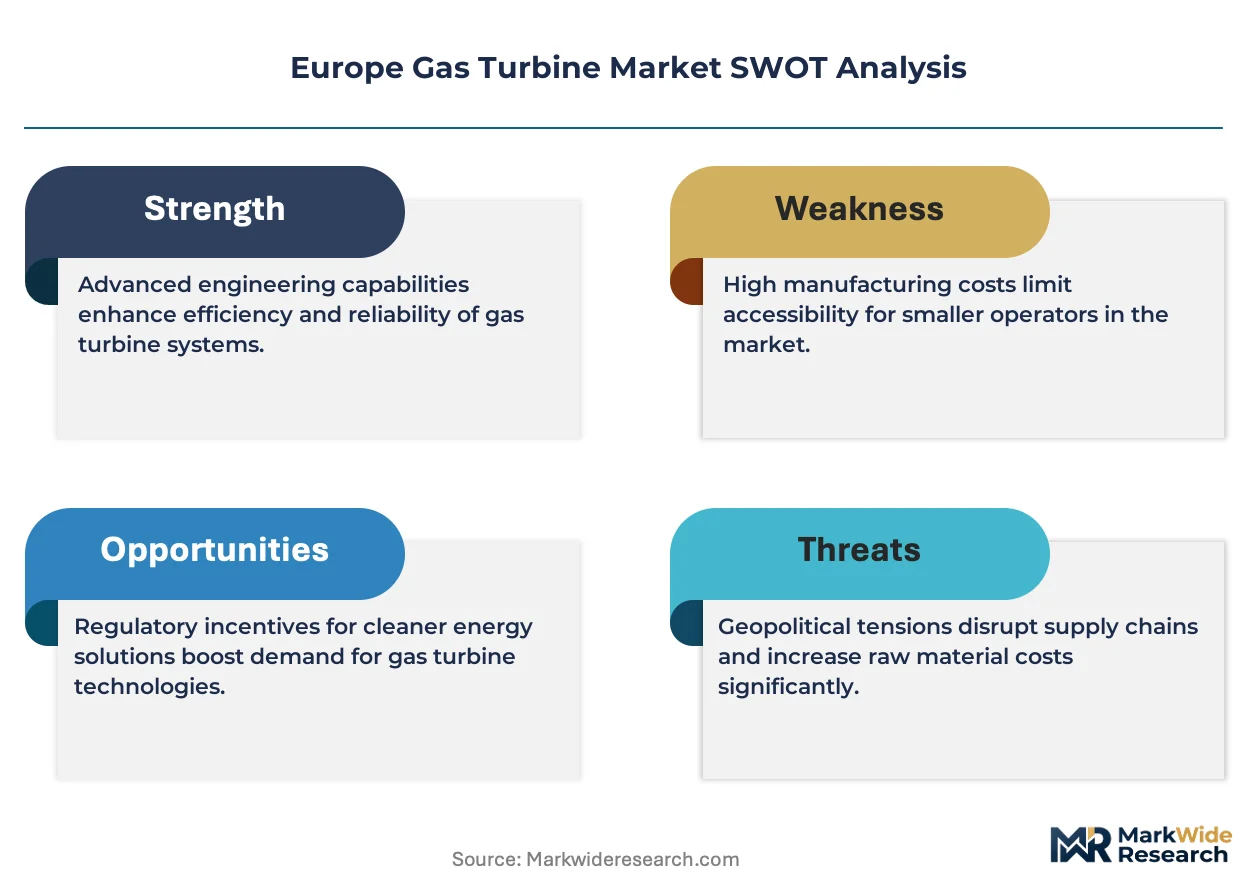
Growth Catalysts
- EU Green Deal carbon-intensity mandates:National regulators in Germany, France, and Italy are accelerating permitting for hydrogen-ready turbine upgrades to meet 2030 interim targets.
- Renewable intermittency balancing:Grid operators in Denmark and the Netherlands are procuring aero-derivative turbines for sub-10-minute ramping capability.
- District heating network expansion:Polish and Czech cogeneration operators are adding gas turbine capacity to serve municipal thermal offtake contracts.
Market Restraints
- Superalloy supply concentration:Precision-cast turbine blade sourcing depends on a concentrated German and Austrian supplier base vulnerable to energy cost volatility.
- F-Gas Regulation refrigerant containment:ECHA enforcement of turbine cooling system leak-rate standards is extending commissioning timelines for new installations.
- Battery storage substitution:Lithium-ion grid-scale deployments in Spain and Portugal are capturing frequency regulation contracts previously served by gas turbines.
Strategic Opportunities
- Hydrogen blending certification gaps:First-mover OEMs capturing TÜV and DNV hydrogen-readiness approvals for 50%+ H2 fuel mixes will secure preferential utility procurement.
- North Sea mechanical-drive retrofit:Aging compressor trains on Norwegian and UK offshore platforms require turbine replacement with integrated digital monitoring.
- Carbon border adjustment mechanism:CBAM implementation is incentivizing Italian and German industrial captives to source EU-manufactured turbines over imported alternatives.
Industry Challenges
- Turbine blade coating requalification:ECHA REACH restrictions on hexavalent chromium and certain thermal barrier formulations are forcing OEMs to revalidate decade-old material specifications.
- Legacy control system integration:Siemens SPPA and Alstom GT13 fleet operators face proprietary protocol barriers when retrofitting hydrogen fuel skids to 1990s-vintage units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gas Turbine Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Turbines, Aero-Derivative Turbines, Microturbines, Heavy-Duty Turbines Application: Power Generation, Oil & Gas Processing, Mechanical Drive, Cogeneration, Peaking Power End User: Independent Power Producers, Utilities, EPC Contractors, Oil Refiners, Chemical Manufacturers Deployment: Combined Cycle, Simple Cycle, Co-Firing, Repowering |
| Companies Covered | Kawasaki Heavy Industries, MAN Energy Solutions, General Electric Company, Rolls-Royce, Solar Turbines, Siemens Energy, Ansaldo Energia, Baker Hughes, Mitsubishi Power, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gas Turbine Market Shifts & Advancements
Gas turbine architecture is fragmenting into modular, hydrogen-adaptable subsystems that decouple combustion technology from generator packages. This decomposition is enabling faster upgrade cycles and opening aftermarket entry points for specialized component suppliers.
Dry low-emission combustion hardware is modularizing into swappable can-annular segments that utilities can field-replace without full rotor removal. German chemical manufacturers operating captive power plants are piloting this architecture to stage hydrogen blending increases from 25% to 75% across sequential outages. The approach is compressing major inspection intervals from 25,000 to 12,000 equivalent operating hours by isolating thermal damage to replaceable modules.
F-Gas Regulation phase-down schedules are mandating turbine cooling system redesigns to eliminate HFC refrigerants by 2030. OEM engineering teams are validating CO2-based cooling loops and air-cooled generator alternatives that add 2-3 percentage points to heat rate. Italian combined-cycle operators face the steepest compliance curve due to earlier national transposition deadlines.
Utility procurement is consolidating around long-term service agreements that bundle hydrogen retrofit roadmaps with baseline maintenance. French and Belgian grid operators are negotiating 15-year contracts with guaranteed heat rate degradation curves and H2-blending escalation clauses. This contracting shift is transferring technology risk from asset owners to OEM service divisions.
Europe Gas Turbine Market Segmentation
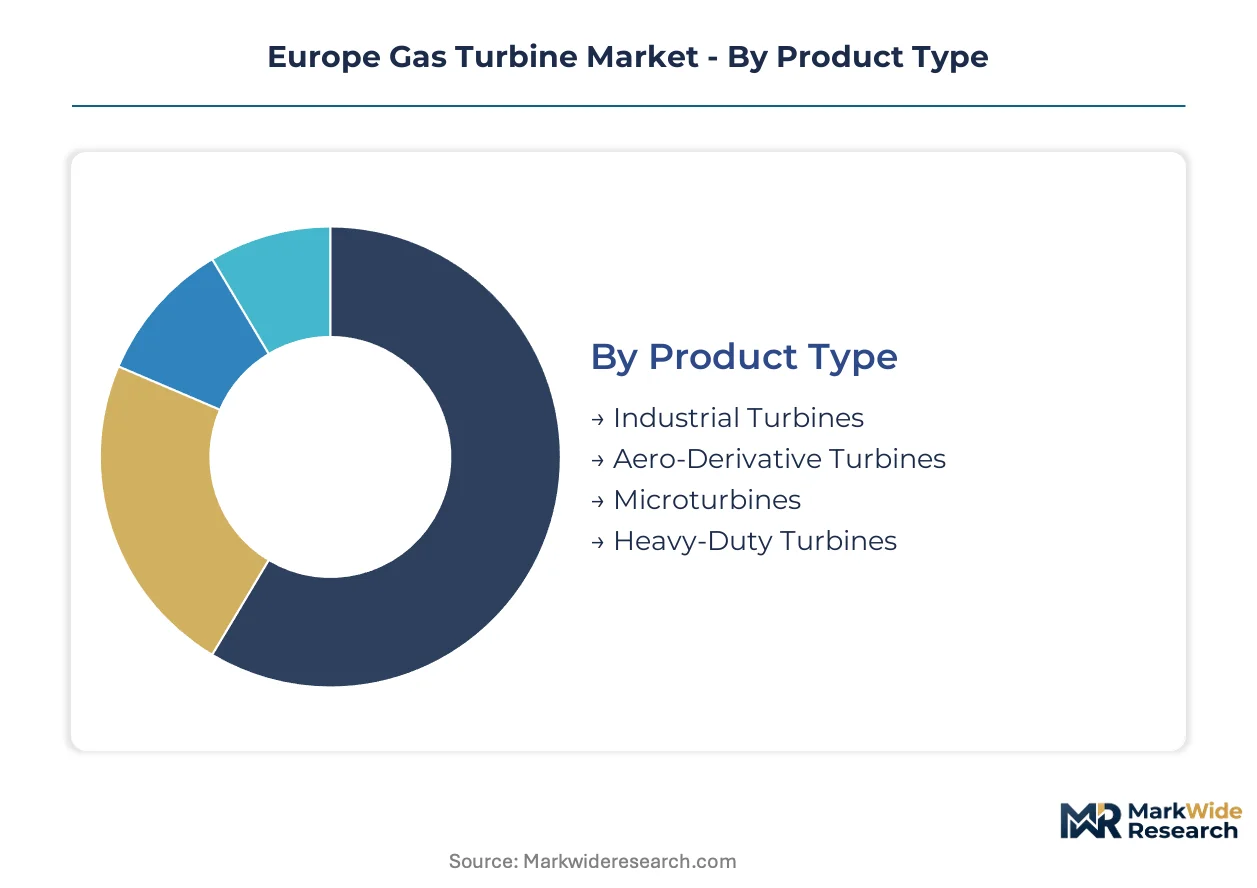
European gas turbine procurement diverges sharply across product architectures and duty cycles. Technology selection hinges on grid-balancing requirements, hydrogen readiness timelines, and thermal offtake availability.
Product Type:
Thermal efficiency and ramp-rate specifications differentiate competitive positioning across the hardware spectrum.
- Heavy-Duty Turbines:These 100-400 MW axial-flow machines achieve firing temperatures exceeding 1,400°C in advanced configurations. German utilities deploy them for baseload combined-cycle duty along the industrial corridor, though hydrogen retrofit roadmaps now constrain procurement decisions.
- Aero-Derivative Turbines:Aviation-derived cores deliver sub-10-minute start capability from cold iron. Danish and Dutch grid operators prioritize these units for renewable balancing services where rapid cycling frequency justifies premium capital cost.
- Industrial Turbines:Mid-scale units serve mechanical-drive and cogeneration duties across Polish and Czech district heating networks.
- Microturbines:Sub-1 MW recuperated designs address distributed generation and landfill-gas recovery at Italian and Spanish industrial sites.
Mature deployment sits with heavy-duty turbines. Newer deployment is concentrated in aero-derivative configurations.
Application:
Duty cycle and revenue structure shape technology selection across end-use cases.
- Power Generation:Utility-scale electricity production dominates installed capacity, with combined-cycle configurations capturing baseload and mid-merit dispatch. French and Belgian operators now require hydrogen-blending roadmaps in long-term service agreements.
- Cogeneration:Combined heat-and-power deployment achieves 80%+ fuel utilization where district heating infrastructure exists. Danish operators leverage municipal thermal offtake contracts to secure premium margins unavailable to pure power producers.
- Peaking Power:Fast-ramp duty for grid stabilization commands scarcity pricing during renewable shortfall events.
- Oil & Gas Processing:Mechanical-drive applications on North Sea platforms require integrated compressor-train configurations with digital monitoring suites.
- Mechanical Drive:Standalone pump and compressor duties serve pipeline and refinery operations across Germany and the Netherlands.
Revenue stability concentrates in cogeneration. Capacity expansion is climbing the fastest in peaking power applications.
End User:
Risk allocation and procurement sophistication vary markedly across buyer categories.
- Utilities:Vertically integrated grid operators in Germany, France, and Italy negotiate 15-year service agreements bundling maintenance with hydrogen retrofit commitments. Their scale commands customized performance guarantees and heat-rate degradation curves.
- Chemical Manufacturers:Captive power operators along Germany's industrial corridor face acute decarbonization pressure. These buyers prioritize hydrogen-ready turbines with staged blending capability from 25% to 75% H2.
- Independent Power Producers:Merchant developers face merchant price exposure and shorter contracting horizons.
- EPC Contractors:Turnkey project delivery specialists aggregate equipment procurement across multiple OEM relationships.
- Oil Refiners:Downstream operators seek mechanical-drive and cogeneration units for process steam and power integration.
Contract sophistication sits with utilities. Technology risk absorption is concentrating in chemical manufacturer procurement.
Deployment:
System architecture determines efficiency, flexibility, and retrofit pathway.
- Combined Cycle:Gas turbine-steam turbine integration achieves 60%+ net efficiency in utility-scale configurations. European operators are retrofitting existing fleets for hydrogen co-firing to retain asset value under EU Green Deal carbon budgets.
- Repowering:Life-extension and performance upgrade of aging units dominates Italian and Spanish market activity. Ansaldo Energia competes on repowering expertise, extending unit life for 1990s-vintage combined-cycle plants.
- Simple Cycle:Single-shaft configurations sacrifice efficiency for capital economy and deployment speed.
- Co-Firing:Hydrogen and synthetic fuel blending in modified combustion systems represents the dominant retrofit pathway.
Installed base concentration sits with combined cycle. Capital deployment is shifting toward repowering and co-firing configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe manufactures turbines across Germany, Italy, and Switzerland while consuming them most heavily in Germany's industrial corridor. Production concentrates where precision engineering clusters intersect with hydrogen R&D funding. Demand spreads across utility, chemical, and oil-gas processing applications with distinct national regulatory drivers.
Germany
Chemical manufacturers along the Rhine-Ruhr and Bavarian industrial zones drive captive power demand for hydrogen-ready turbines. The national transposition of the EU Green Deal accelerates permitting for 50% hydrogen-blending retrofits by 2030. Berlin hosts Siemens Energy's turbine R&D center, anchoring combustion technology development for continental export.
Italy
Repowering demand dominates as aging combined-cycle plants from the 1990s require life-extension upgrades. Ansaldo Energia anchors the domestic service ecosystem, leveraging expertise in legacy Alstom and Siemens fleet maintenance. The Po Valley industrial cluster sustains mechanical-drive procurement for petrochemical and refining operations.
United Kingdom
North Sea offshore platforms require integrated compressor-train turbine replacements with digital monitoring suites. The UK's Industrial Emissions Directive enforcement tightens NOx limits for existing installations. Aberdeen and the Scottish central belt concentrate mechanical-drive demand from upstream oil-gas operators.
Netherlands
Grid operators procure aero-derivative turbines for sub-10-minute ramping to balance North Sea wind variability. The national hydrogen backbone infrastructure supports blending trials at Rotterdam-area power stations. The Randstad urban corridor sustains district heating cogeneration with premium-margin thermal offtake contracts.
Poland
Municipal district heating network expansion drives cogeneration turbine deployment across Silesian and Warsaw metropolitan areas. EU cohesion funding accelerates coal-to-gas transitions in combined heat-and-power applications. The national energy security agenda prioritizes domestic gas-fired capacity over import-dependent alternatives.
Europe Gas Turbine Market Competitive Landscape
Top-tier vendors anchor hydrogen-combustion development, while mid-tier specialists concentrate on repowering and mechanical-drive integration. The vendor base stratifies across three tiers: full-service OEMs with integrated power plant capabilities, component specialists focused on combustion hardware, and regional service providers capturing aftermarket maintenance. Two dominant competitive moves are reshaping positioning: long-term service agreement bundling that transfers technology risk to OEMs, and hydrogen-readiness certification racing to secure utility procurement preference.
Within the full-service OEM tier, Siemens Energy, Ansaldo Energia, and MAN Energy Solutions occupy positions defined by distinct technical specializations. Siemens Energy exemplifies the hydrogen-combustion development archetype through its Berlin R&D concentration. Ansaldo Energia represents the repowering expertise model, extending unit life for aging Italian and Spanish combined-cycle fleets. MAN Energy Solutions anchors the mechanical-drive segment with integrated compressor-train configurations for North Sea upstream operations.
| Leading Market Players |
|---|
| Kawasaki Heavy Industries |
| MAN Energy Solutions |
| General Electric Company |
| Rolls-Royce |
| Solar Turbines |
| Siemens Energy |
| Ansaldo Energia |
| Baker Hughes |
| Mitsubishi Power |
| Others |
Supply & Pricing Matrix
Precision turbine blade foundry labor in the German and Austrian industrial corridors anchors cost differentials that widen spreads between premium OEM-certified units and economy-tier aftermarket alternatives. ECHA REACH compliance requalification expenses for thermal barrier coatings feed directly into tiered pricing structures, with hydrogen-readiness certification commanding additional premiums.
Pricing Analysis
Margin tightening in economy-tier aftermarket components reflects superalloy ingot cost volatility and concentrated German supplier pricing power. Three-tier pricing structure across premium OEM, certified-rebuild, and unlicensed aftermarket levels differentiates by CE marking compliance and TÜV hydrogen-blending certification status. Pricing pressure stems from battery storage substitution in Spanish and Portuguese frequency regulation markets. Merchant IPPs exhibit highest price sensitivity due to merchant price exposure, while German chemical manufacturers absorb premiums for staged hydrogen retrofit capability.
Supply Chain Analysis
Single-source vulnerability sits with precision-cast turbine blade suppliers concentrated in Germany and Austria. Superalloy sourcing draws from German foundries, Austrian vacuum-melting facilities, and Swedish powder-metallurgy specialists. Nickel-cobalt superalloy feedstock and ceramic thermal barrier coatings constitute critical input dependencies. Tariff exposure on Chinese rare-earth elements for high-temperature alloys presents structural supply risk. Distribution runs through OEM-authorized service centers and specialized industrial distributors serving EPC contractors and utility procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around hydrogen-combustion capability as EU Green Deal carbon-intensity mandates force out OEMs lacking TÜV certification progress. Smaller regional service providers face absorption into full-service OEM networks.
For Market Incumbents: Deepen hydrogen-combustion R&D concentration at Berlin and Munich engineering centers to outpace certification timelines. Secure long-term superalloy supply agreements with German and Austrian foundries before REACH requalification bottlenecks tighten. Battery storage substitution in Iberian frequency regulation markets threatens peaking-power revenue streams; offset through utility service agreement bundling that transfers technology risk. For New Entrants and Emerging Players: A 25-40% price-point gap between premium OEM and economy-tier repowering services creates entry space for specialized combustion hardware suppliers. Target Italian and Spanish repowering markets where Ansaldo Energia's legacy fleet dominance leaves modular retrofit white space. Pursue component-level aftermarket entry through swappable can-annular segment architectures that enable staged hydrogen blending without full rotor replacement. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier combustion hardware specialists given EU F-Gas Regulation cooling-system redesign mandates. Five-to-ten-year viability favors OEMs with integrated hydrogen roadmaps and captive German precision-casting supply. Watch TÜV and DNV hydrogen-readiness approval timelines as inflection signals for procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Turbine Retrofit | EU Green Deal compliance preserves asset value for German and Italian combined-cycle operators. |
| Long-Term Service Agreement Bundling | French and Belgian utilities transfer technology risk to OEMs through 15-year hydrogen-escalation contracts. |
| Superalloy Supply Integration | Backward control over German and Austrian foundry capacity secures blade sourcing against REACH volatility. |
| Modular Combustion Hardware Development | Swappable can-annular segments compress inspection intervals for chemical manufacturer captive plants. |
| F-Gas-Compliant Cooling System Redesign | CO2-based loops and air-cooled generators address Italian transposition deadlines ahead of continental phase-down. |
Research Methodology
IEA power generation databases, EIA international energy statistics, and EU industrial emissions filings formed the secondary backbone for demand quantification. Primary interviews with utility planning officers at German and French grid operators, EPC contractors active in combined-cycle deployment, and aftermarket service heads at OEM divisions validated capacity expansion timelines. Plant engineers at chemical manufacturers along the Rhine-Ruhr corridor and North Sea platform maintenance directors provided mechanical-drive demand inputs. Bottom-up and top-down triangulation cross-validated segment-level outputs against aggregate capacity projections.
Bottom-up modeling of individual project pipelines and top-down macroeconomic energy demand scenarios converged across the analysis window. Segmentation dimensions included product architecture (heavy-duty, aero-derivative, industrial, microturbine), application duty cycle (baseload, peaking, cogeneration, mechanical drive), and deployment configuration (combined cycle, simple cycle, repowering, co-firing). CAGRs derived from regression analysis of historical capacity additions against EU policy implementation timelines. Hydrogen blending roadmap commitments and F-Gas Regulation compliance curves served as industry-specific forecast modifiers.
Inputs from OEM service division disclosures and national regulatory filings were available through the study window; gaps in proprietary hydrogen-combustion test data introduce uncertainty bands around retrofit adoption rates. Forecasts reflect documented assumptions regarding EU Green Deal carbon-intensity trajectory and superalloy supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Construction Portable Generators Market
Generators
Digital Inverter Generator Market
Generators
Industrial Generator Market
Generators
Generator Sets Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Generator (Up to 20 Kva) Market
Generators
Europe Generator Sets Market
Generators
Commercial Standby Generator Sets Market
Generators
Wind Turbine Alternator Market
Generators
Asia Pacific Electric Generators Market
Generators
South America Portable Generator Market
Generators
East Africa Diesel Generator Market
Generators
Marine Gensets Market
Generators
Electric Generators Market
Generators
Europe Turbo Generator Market
Generators
Generator Sales Market