
 Asia-Pacific Diesel Generator Market | 2026-2036
Asia-Pacific Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Diesel Generator Market Outlook
Market Dynamics
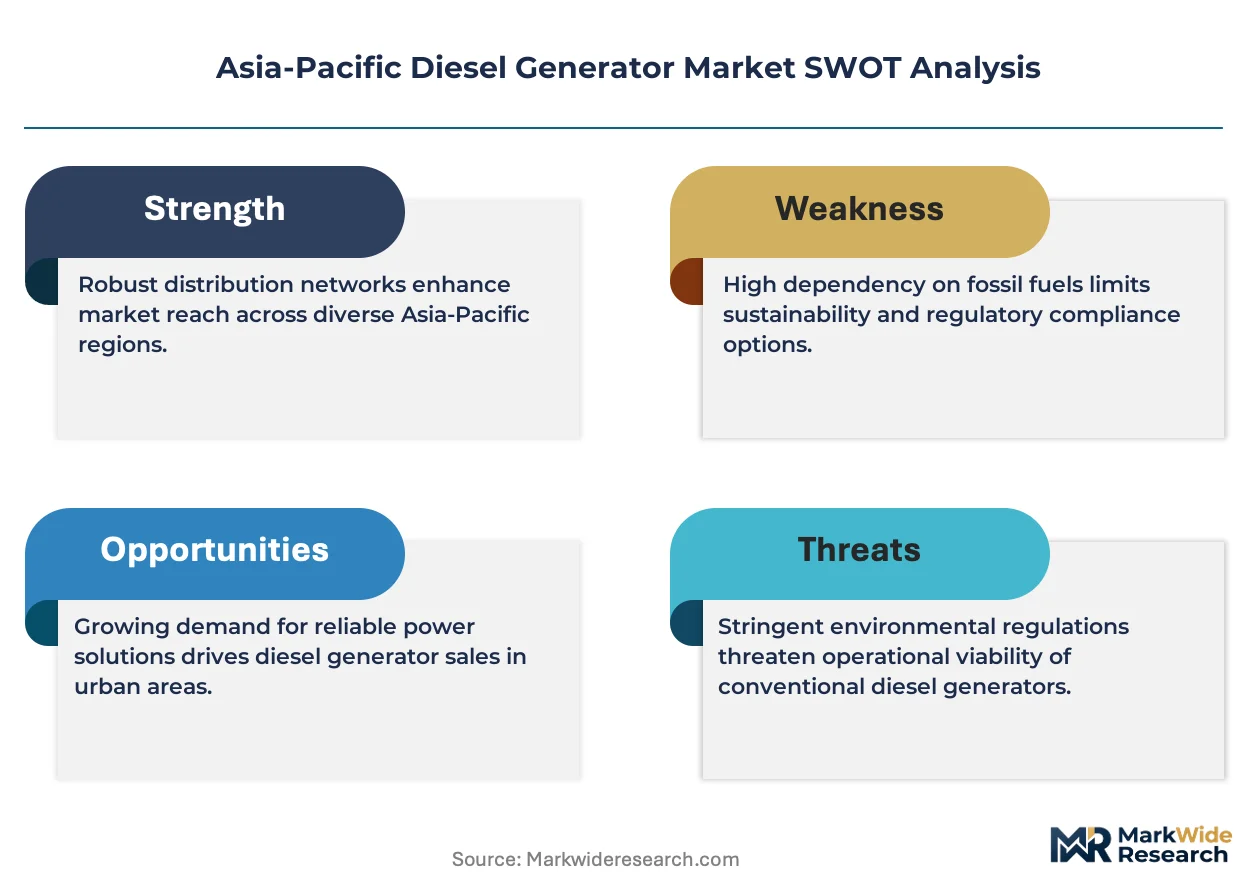
Capital-intensity divergence between integrated engine manufacturers and assembly-only operators is bifurcating competitive returns across the Asia-Pacific diesel generator landscape. Caterpillar Inc. leverages its captive engine foundry network to sustain margin structures that pure integrators cannot match. Cummins India Ltd. anchors its position through deep channel control across South Asian distribution nodes. Kirloskar Oil Engines Ltd. specializes in sub-500 kVA industrial units for domestic manufacturing clusters.
Product Architecture and Segment Structure
A diesel generator converts mechanical energy from compression-ignition engines into electrical power through synchronous alternators, typically operating at 50 Hz across Asia-Pacific grids with voltage ratings from 230 V single-phase to 11 kV three-phase configurations. Standby units command the largest installed base among product types because commercial facilities and healthcare infrastructure mandate uninterrupted backup protocols. The above 500 kVA capacity band captures disproportionate value share as mining and oil & gas operators in Australia and Indonesia specify heavy-duty prime power systems. Telecom end users represent the fastest-expanding demand pool as 5G rollouts accelerate tower electrification in Myanmar, Bangladesh, and the Philippines.
Regulatory Environment and Strategic Outlook
India's Central Pollution Control Board enforces emission standards under the Environment Protection Act that phase in stricter particulate limits for diesel gensets, while Australia's National Environment Protection Council maintains stationary engine codes that affect product certification pathways. China's Ministry of Ecology and Environment aligns non-road mobile machinery regulations with Stage IV equivalent limits, reshaping import eligibility for engines sourced from older technology tiers. Japan's METI administers Top Runner efficiency standards that elevate design thresholds for equipment sold into its domestic market. Stakeholders must monitor how Indonesia's nickel smelter buildout and Vietnam's grid reliability gaps alter procurement specifications before emission compliance timelines harden.
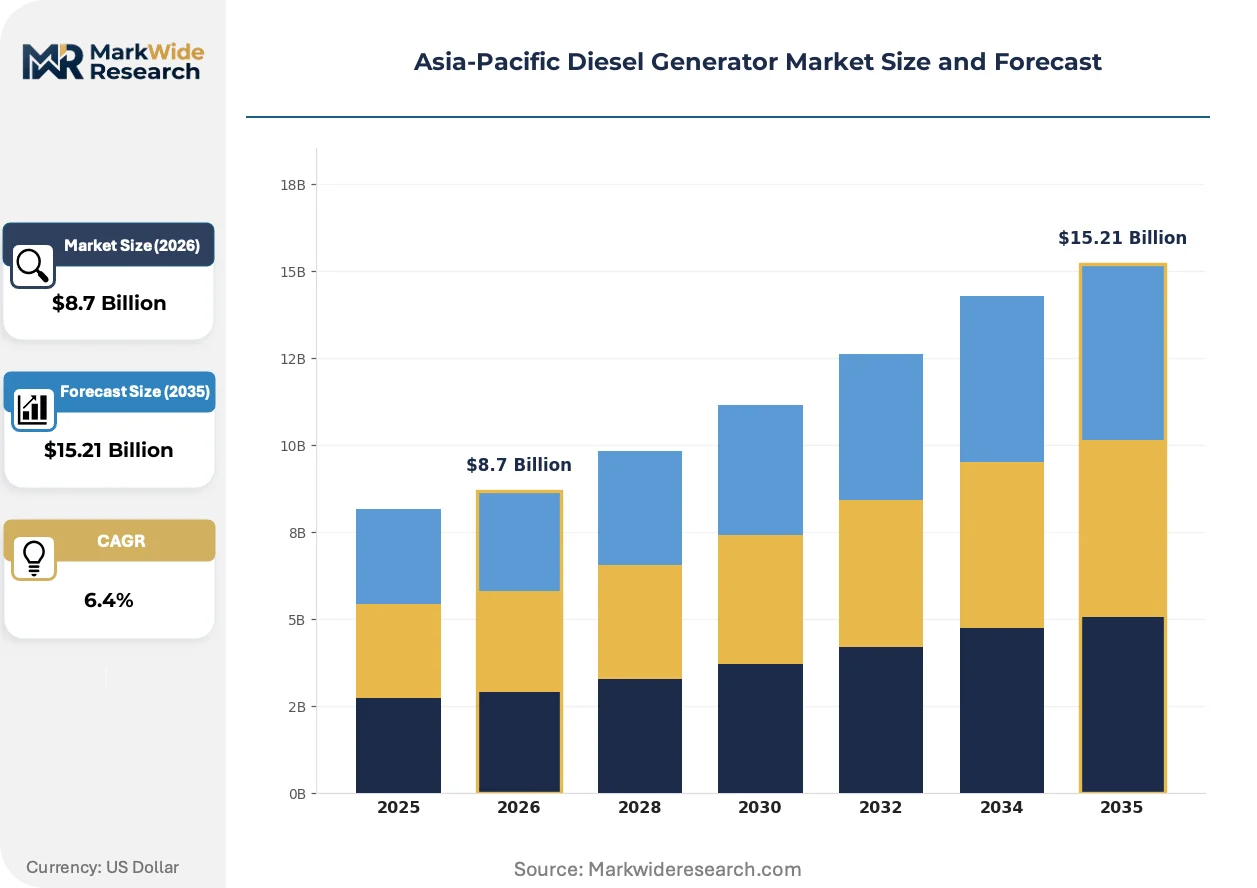
Market Dynamics
India's Bureau of Indian Standards emission phase-in for sub-800 kW gensets is compressing product lifecycles and forcing engine architecture redesigns across the entire Asia-Pacific supply base.
Growth Catalysts
- Data Center Buildout:Hyperscale operators in Singapore and Sydney are mandating N+1 redundancy standards that require redundant diesel backup at every facility node.
- CPCB Emission Deadlines:India's Central Pollution Control Board is accelerating genset replacement cycles in Delhi-NCR industrial corridors through mandatory PM retrofit mandates.
- Nickel Smelter Electrification:Indonesia's Morowali and Weda Bay processing zones require continuous prime power systems for HPAL refining operations where grid stability remains inadequate.
Market Restraints
- Steel and Copper Volatility:Alternator stator windings and engine block castings face input cost swings that erode fixed-price contract margins for assembly-only operators.
- Engine Supply Concentration:High-speed diesel engine production concentrates in Indian and Chinese foundries, creating single-source vulnerability for ASEAN integrators without captive casting capacity.
- BESS Substitution Threat:Lithium-ion battery energy storage systems are capturing telecom tower backup share in Bangladesh and Myanmar where diesel logistics costs exceed battery amortization.
Strategic Opportunities
- Vietnam Northern Industrial Zones:Bac Ninh and Hai Phong manufacturing clusters face 15-20% grid downtime, creating captive power demand for modular genset rental fleets.
- Dual-Fuel Retrofit Convergence:Natural gas-diesel blending kits are opening stranded gas pipeline corridors to genset operators in Australia's Queensland mining belt.
- MEE Stage IV Alignment:China's Ministry of Ecology and Environment standards harmonization is creating export pathway advantages for compliant engine manufacturers into Southeast Asian markets.
Industry Challenges
- Emission Calibration Talent Gap:CPCB and MEE compliance testing requires specialized exhaust after-treatment engineers that remain scarce outside Mumbai and Shanghai technical centers.
- Legacy Control System Integration:SCADA retrofit compatibility with 1990s-era genset paralleling gear is delaying smart-grid synchronization projects across Philippine commercial estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Diesel Generator Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Prime, Industrial End User: Construction, Mining, Oil & Gas, Telecom Capacity: Below 100 kVA, 100-300 kVA, 300-500 kVA, Above 500 kVA Installation: Onshore, Offshore, Permanent, Temporary |
| Companies Covered | Yanmar Co., Ltd., Cummins India Ltd., Caterpillar Inc., Generac Power Systems, MTU (Rolls Royce Power Systems), Cummins Inc., Mahindra Powerol, Kohler Co., Kirloskar Oil Engines Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Diesel Generator Market Strategic Shifts
Engine downsizing and digital load management are compressing physical footprints while expanding operational flexibility for space-constrained urban installations.
Containerized genset enclosures are miniaturizing through integrated cooling and exhaust routing that eliminates external silo infrastructure. Singapore data center operators are specifying these units for rooftop deployments where floorplate premiums exceed equipment cost differentials. The format is compressing site preparation timelines from weeks to days across Southeast Asian commercial developments.
India's BIS emission norms for gensets below 800 kW are tightening particulate matter limits through mandatory diesel particulate filter certification. Engine manufacturers must redesign combustion chambers and after-treatment packaging to maintain power density under stricter thermal constraints. Sub-500 kVA domestic manufacturers are responding with localized catalyst sourcing to preserve margin structures against imported compliant engines.
Telecom tower operators in Myanmar and Bangladesh are unbundling maintenance contracts from equipment procurement, separating CAPEX and OPEX decisions across 10-year asset lifecycles. Towercos now specify availability-based service agreements where integrators bear fuel and uptime risk. The model is concentrating procurement authority with regional fleet managers in Yangon and Dhaka rather than distributed site engineers.
Asia-Pacific Diesel Generator Market Segmentation
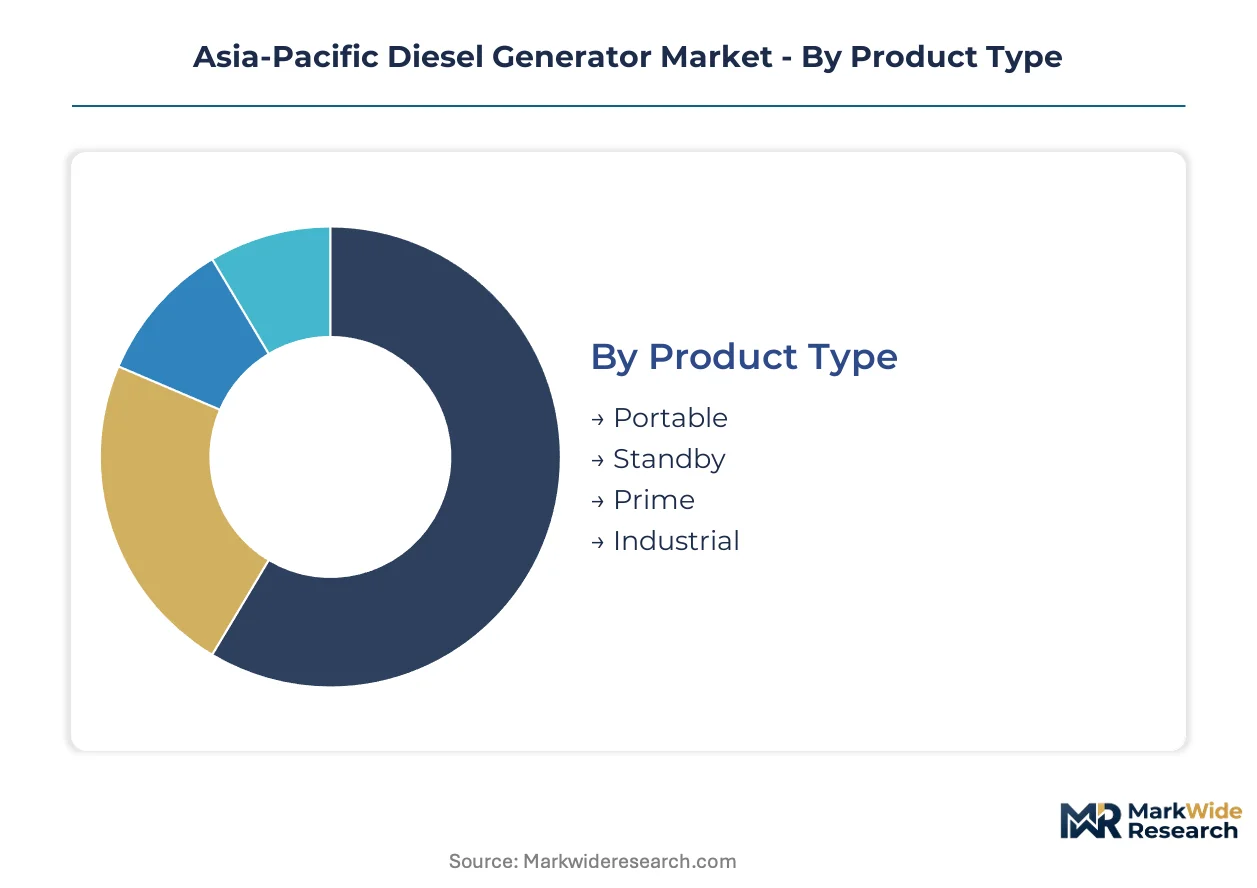
Segmentation in the Asia-Pacific diesel generator market reflects divergent regulatory pressures and operational intensity across end-use applications. Procurement specifications vary sharply between India's emission-controlled urban corridors and Indonesia's remote industrial zones.
Product Type:
India's BIS emission norms for sub-800 kW gensets and Australia's stationary engine codes create divergent certification burdens across product categories.
- Standby:Units designed for emergency power activation within 10 seconds of grid failure dominate commercial and healthcare installations. Singapore data center operators mandate N+1 redundancy configurations that specify these systems for every facility node, with containerized enclosures compressing rooftop deployment timelines.
- Prime:Continuous-duty systems rated for unlimited annual operating hours serve as primary power where grid infrastructure remains inadequate. Indonesia's Morowali and Weda Bay nickel processing corridors specify heavy-duty prime power configurations for HPAL refining operations facing 15-20% grid downtime.
- Portable:Trailer-mounted or skid-based units serve construction sites and temporary events requiring rapid relocation across project phases.
- Industrial:Fixed-installation systems engineered for manufacturing facilities integrate paralleling controls and remote monitoring for captive power plants.
Standby handles the majority of installed base volume; Prime is expanding most quickly on share as Indonesian smelter buildout accelerates.
End User:
Customer procurement authority is concentrating with regional fleet managers as tower operators in Myanmar and Bangladesh unbundle maintenance from equipment purchase.
- Telecom:5G rollout timelines in Myanmar, Bangladesh, and the Philippines are accelerating tower electrification programs. Towercos now specify availability-based service agreements where integrators absorb fuel cost and uptime risk across 10-year asset lifecycles.
- Mining:Australian and Indonesian extraction operators specify above-500 kVA heavy-duty systems for remote site electrification. Queensland mining belt operators are piloting natural gas-diesel dual-fuel retrofit kits to access stranded pipeline infrastructure.
- Construction:Temporary power demand fluctuates with infrastructure project pipelines across Vietnam's northern industrial zones.
- Oil & Gas:Upstream and midstream facilities require explosion-proof enclosures and extended fuel autonomy for offshore platform applications.
Mining commands the highest unit values; Telecom is gaining share fastest as tower densification outpaces other verticals.
Capacity:
Physical footprint constraints and emission after-treatment packaging are compressing power density thresholds in sub-500 kVA designs.
- Above 500 kVA:Heavy-duty synchronous alternators with 11 kV output capability serve mining and oil & gas prime power applications. These units capture disproportionate value share as Australian and Indonesian operators specify extended overhaul intervals and integrated paralleling gear.
- 100-300 kVA:Mid-range industrial units anchor Kirloskar Oil Engines' domestic manufacturing cluster specialization. India's BIS particulate matter limits are forcing combustion chamber redesigns to maintain thermal efficiency under stricter catalyst loading.
- Below 100 kVA:Compact single-phase and three-phase units serve small commercial backup and residential applications.
- 300-500 kVA:Transitional capacity band bridges light industrial and heavy commercial requirements with modular paralleling options.
Above 500 kVA handles the majority of revenue concentration; 100-300 kVA is climbing the fastest as Indian manufacturing clusters upgrade backup protocols.
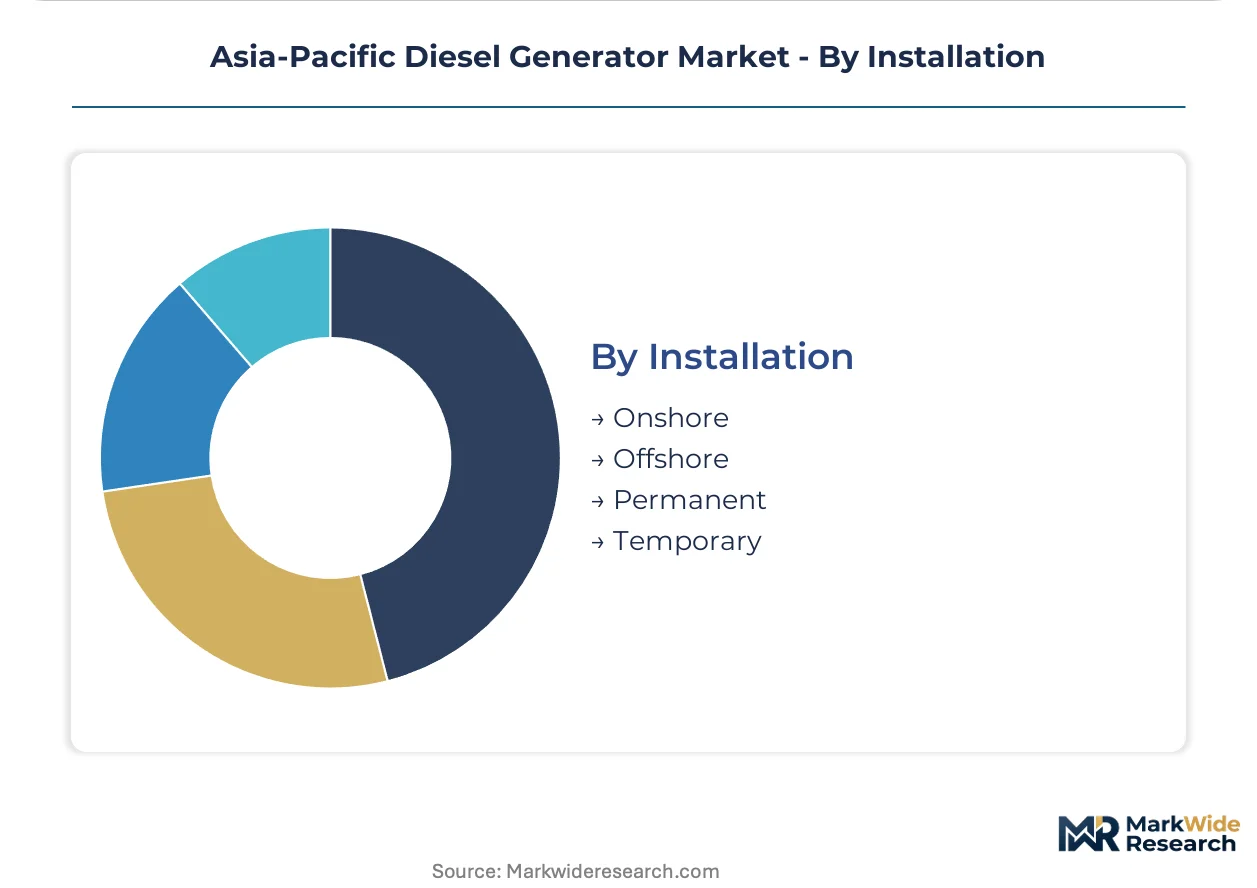
Installation:
Site preparation cost differentials between permanent foundation work and temporary skid mounting are reshaping procurement economics across Southeast Asian commercial developments.
- Permanent:Fixed concrete pad installations with integrated fuel storage and exhaust silos serve data centers and healthcare facilities requiring 20-year asset lifecycles. Singapore operators absorb floorplate premiums that exceed equipment cost differentials for rooftop containerized configurations.
- Temporary:Rapid-deployment skid or trailer formats eliminate external infrastructure requirements. Vietnam's Bac Ninh and Hai Phong manufacturing clusters are driving modular genset rental fleet expansion where grid reliability gaps create intermittent captive power demand.
- Onshore:Land-based installations across standard industrial and commercial sites with conventional environmental controls.
- Offshore:Marine-grade enclosures with corrosion-resistant coatings and enhanced fuel segregation for platform and vessel applications.
Permanent handles the majority of long-term installed capacity; Temporary is expanding most quickly on share as rental fleet operators capture manufacturing cluster demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian nickel processors demonstrate the lowest price elasticity, absorbing premium prime power systems without volume reduction, while Indian commercial buyers face acute sensitivity to fuel efficiency metrics that compress procurement budgets.
India
Delhi-NCR industrial corridors drive genset replacement cycles as BIS emission norms for sub-800 kW units force PM retrofit mandates. The Central Pollution Control Board accelerates compliance timelines through mandatory certification. Maharashtra manufacturing clusters upgrade backup protocols, expanding 100-300 kVA procurement for captive power plants.
Indonesia
Morowali and Weda Bay nickel processing zones require continuous prime power for HPAL refining operations facing severe grid instability. The Ministry of Energy and Mineral Resources oversees electrification standards for smelter developments. Sulawesi industrial corridors concentrate heavy-duty above-500 kVA installations as Chinese-backed processors expand refining capacity.
Vietnam
Bac Ninh and Hai Phong manufacturing clusters face 15-20% grid downtime, driving modular genset rental fleet expansion. The Ministry of Industry and Trade regulates captive power plant licensing for industrial zones. Northern industrial provinces absorb temporary installation formats as foreign electronics manufacturers seek backup reliability.
Australia
Queensland mining belt operators pilot natural gas-diesel dual-fuel retrofits to access stranded pipeline infrastructure. The National Environment Protection Council maintains stationary engine codes affecting product certification pathways. Western Australian extraction sites specify heavy-duty systems with extended overhaul intervals for remote site electrification.
Singapore
Hyperscale data center operators mandate N+1 redundancy standards requiring redundant diesel backup at every facility node. The Energy Market Authority regulates distributed generation interconnection standards. Jurong and Tuas industrial estates absorb containerized rooftop configurations where floorplate premiums exceed equipment cost differentials.
Asia-Pacific Diesel Generator Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive engine foundry capacity separating margin-sustainable operators from assembly-dependent competitors. The upper tier controls synchronous alternator and high-speed diesel engine production internally, while integrators without casting capacity face single-source vulnerability from Indian and Chinese foundry concentration. Three archetypes dominate: integrated engine-alternator manufacturers, regional assembly specialists, and rental fleet operators capturing intermittent demand. Competitive moves concentrate on backward integration into foundry operations and channel control across South Asian distribution nodes.
Among integrated manufacturers, Caterpillar Inc. and Cummins Inc. occupy positions exemplifying captive supply chain control, while Kirloskar Oil Engines Ltd. represents regional specialization in sub-500 kVA industrial configurations for domestic manufacturing clusters.
| Leading Market Players |
|---|
| Yanmar Co., Ltd. |
| Cummins India Ltd. |
| Caterpillar Inc. |
| Generac Power Systems |
| MTU (Rolls Royce Power Systems) |
| Cummins Inc. |
| Mahindra Powerol |
| Kohler Co. |
| Kirloskar Oil Engines Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive foundry capacity at Indian and Chinese engine manufacturers creates scale economies that assembly-only operators cannot replicate, compressing margin structures for integrators without backward integration into casting operations while elevating price floors for compliant equipment across Southeast Asian procurement corridors.
Pricing Analysis
After-sales service contracts and parts revenue anchor lifetime value for integrated manufacturers, with three-tier pricing structure across premium, standard, and economy levels differentiating on certification grade and after-treatment complexity. Price differentiation stems from BIS emission compliance tier and geographic delivery cost to remote Indonesian smelter sites. Cost compression in sub-500 kVA segments is intensifying because localized catalyst sourcing requirements are raising input costs for domestic Indian manufacturers. Mining operators in Australia and Indonesia demonstrate the lowest price sensitivity, absorbing premium prime power systems, while Vietnamese manufacturing clusters face acute fuel efficiency pressure that compresses procurement budgets.
Supply Chain Analysis
Port congestion at Singapore and Shanghai container terminals elevates inbound logistics costs for alternator stator windings and exhaust after-treatment catalysts sourced from European suppliers. Engine block castings and high-speed diesel power units concentrate in Indian and Chinese foundries, while synchronous alternator production centers on domestic facilities across South Asia. Raw material dependencies include copper for windings, steel for enclosures, and rare earth elements for permanent magnet alternators. Single-source vulnerability from ASEAN integrators without captive casting capacity represents the dominant supply chain risk. Distribution runs through authorized dealer networks controlled by Cummins India and regional fleet operators capturing rental demand in Vietnam's northern industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through BIS emission certification creates defensive moats for compliant manufacturers, as switching costs for industrial buyers escalate when retrofit timelines compress and approved supplier lists narrow.
For Market Incumbents: Secure captive foundry capacity expansion in Maharashtra and Tamil Nadu industrial corridors to defend margin structures against pure integrators facing single-source engine vulnerability. Deepen channel control across Bangladesh and Myanmar distribution nodes before towercos consolidate procurement authority with regional fleet managers. Battery energy storage substitution in telecom backup applications represents the priority threat requiring dual-fuel retrofit investment. For New Entrants and Emerging Players: Differentiate on containerized rooftop deployment speed for Singapore data center operators absorbing floorplate premiums that exceed equipment cost differentials. Target Vietnam's Bac Ninh and Hai Phong manufacturing clusters with modular rental fleet formats where 15-20% grid downtime creates intermittent captive power demand. Pursue availability-based service agreements that unbundle maintenance from equipment procurement, absorbing fuel and uptime risk across 10-year asset lifecycles. For Investors and Strategic Acquirers: Regional assembly specialists with deep channel control across South Asian distribution nodes present acquisition targets with embedded customer lock-in through emission certification timelines. Long-term viability hinges on backward integration into foundry operations or exclusive engine supply agreements that insulate against Indian and Chinese foundry concentration. Watch CPCB and MEE compliance deadline acceleration as the inflection signal indicating replacement cycle velocity and certified equipment scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Maharashtra and Tamil Nadu casting investments insulate margin structures against input cost volatility for engine block production. |
| Dual-Fuel Retrofit Development | Natural gas-diesel blending kits open stranded pipeline corridors in Queensland mining belt to genset operators facing BESS substitution. |
| Containerized Enclosure Miniaturization | Singapore data center rooftop deployments compress site preparation timelines from weeks to days under N+1 redundancy mandates. |
| Availability-Based Service Agreements | Towercos in Yangon and Dhaka shift fuel and uptime risk to integrators, concentrating procurement authority with regional fleet managers. |
| Localized Catalyst Sourcing | Domestic Indian manufacturers preserve margin structures against imported compliant engines through BIS-certified after-treatment supply chains. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers at Indonesian nickel smelters, aftermarket service heads at Indian genset distributors, procurement officers at Singapore data center operators, and fleet managers at Bangladeshi towercos, then refined through secondary validation against BIS certification databases, CPCB emission compliance records, Indonesian Ministry of Energy and Mineral Resources electrification standards, and customs trade data for engine and alternator imports. Bottom-up unit economics from manufacturing cluster installations were triangulated with top-down market sizing across product type and capacity segmentation dimensions.
Variance decomposition across product type, capacity band, end-use vertical, and installation format anchored the analytical framework over the projection horizon. CAGRs were derived from modeled unit shipments and average selling price trajectories. Industry-specific forecast inputs included grid reliability metrics from Vietnam's northern industrial provinces, HPAL refining power demand intensity from Morowali and Weda Bay processing zones, and 5G tower densification timelines across Myanmar, Bangladesh, and the Philippines.
The analysis sits within stated boundaries; outcomes outside BIS and MEE compliance timeline adherence, nickel smelter buildout velocity, or BESS cost parity achievement would require recalibration. Forecasts reflect documented assumptions regarding emission regulation phase-in schedules and industrial electrification patterns. Practitioners should keep alternative scenarios live as battery energy storage substitution economics and stranded gas pipeline accessibility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
China Generator Sets Market
Generators
Wind Power Generators Market
Generators
Gulf Cooperation Council (GCC) Diesel Generator Market
Generators
Silent Generator Market
Generators
Power Generator for Military Market
Generators
Containerized Solar Generators Market
Generators
Portugal Gas Generator Market
Generators
Europe Diesel Generator Market
Generators
Asia-Pacific Portable Generator Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Military Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Tri Fuel Generators Market
Generators
Marine Gensets Market
Generators
Industrial Generator Sets Market
Generators
Industrial Generator Market