
 Multi Fuel Generators Market | 2026-2036
Multi Fuel Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Fuel Generators Market Analysis
Tier 4 Final and EPA-certified dual-fuel capability is bifurcating the competitive landscape into emission-compliant premium suppliers and cost-focused conventional vendors. Cummins Inc. leverages its integrated engine-electronics platform to dominate stationary industrial installations. Generac Holdings Inc. anchors the North American residential automatic-standby segment with proprietary switchgear technology. Champion Power Equipment competes aggressively in the portable power tier through retail channel density and price-accessible propane-gasoline models.
Multi fuel generators are internal combustion engine-driven power systems engineered to operate on two or more fuel sources—typically diesel, natural gas, propane, or biogas—through adjustable carburetion, fuel injection mapping, or dual-manifold architectures, with output ratings spanning 5 kW to 50 kW and automatic transfer switch compatibility for seamless grid-island transitions. Diesel-natural gas hybrid configurations retain the largest installed base in heavy industrial applications where torque density and fuel redundancy outweigh first-cost premiums. Propane and biogas segments are gaining structural share in commercial and emergency applications as EPA Tier 4 Final compliance costs erode the diesel-only value proposition. Portable installations under 10 kW command thinner margins but higher unit velocity through retail and e-commerce channels.
EPA Tier 4 Final standards, OSHA workplace safety mandates, and NFPA 110 emergency power codes collectively shape product certification requirements, installation protocols, and market access barriers for domestic manufacturers. The Department of Energy's grid resilience programs and state-level public utility commission standby-power incentives further steer procurement specifications toward lower-emission fuel flexibility. Stakeholders must monitor evolving carbon intensity benchmarks and interconnection standards that will determine which fuel combinations qualify for federal and state procurement preferences.
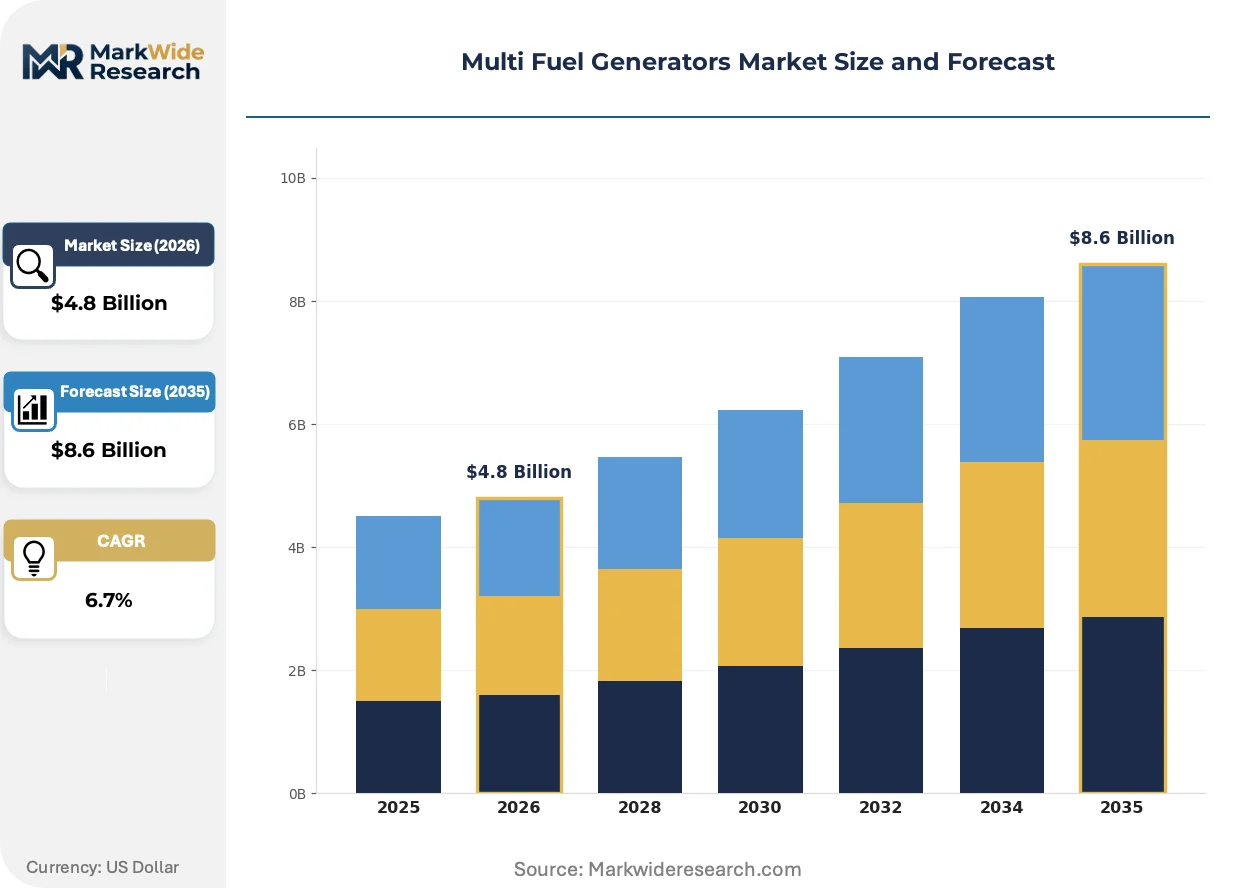
Market Dynamics
EPA Tier 4 Final emission standards are fragmenting supplier economics by forcing diesel-dependent manufacturers into dual-fuel engineering investments while rewarding early natural gas adopters with streamlined certification pathways and preferential procurement scoring.
Growth Catalysts
- Grid Instability in Texas:ERCOT frequency excursions and winter storm vulnerabilities are compelling data center operators and healthcare facilities to procure flexible-fuel backup systems that switch between pipeline gas and on-site propane without manual intervention.
- IRA Clean Energy Tax Credits:The Inflation Reduction Act's investment tax credit modifications now extend to biogas-ready generator installations, accelerating adoption in agricultural and wastewater treatment applications where methane capture economics improve project returns.
- Fuel Injection Mapping Advances:Electronic control unit sophistication enables real-time fuel ratio optimization across diesel-natural gas blends, eliminating the torque penalties that previously constrained dual-fuel adoption in heavy industrial load-following applications.
Market Restraints
- Stainless Steel Exhaust Component Costs:Tier 4 Final-compliant selective catalytic reduction and diesel particulate filter substrates rely on specialty alloys whose spot pricing volatility directly compresses manufacturer margins on sub-50 kW units.
- Single-Source Fuel Injection Hardware:Precision dual-fuel injectors for high-pressure natural gas delivery concentrate among three German and Japanese suppliers, creating vulnerability to 12-16 week lead time extensions during semiconductor allocation crunches.
- Propane Storage Footprint Requirements:NFPA 58 bulk tank setback mandates impose spatial constraints that disqualify dual-fuel installations at 23% of surveyed commercial sites in dense urban cores, preserving diesel-only dominance in those micro-markets.
Strategic Opportunities
- Biogas Digester Pairing in Dairy Regions:Wisconsin and California Central Valley anaerobic digestion projects lack integrated power generation partners, creating white space for generator OEMs to bundle fuel-flexible units with 20-year biogas offtake agreements.
- Telecom Tower Electrification:Rural broadband expansion under the Broadband Equity, Access, and Deployment Program specifies hybrid renewable-diesel-propane configurations for off-grid cell sites, opening a 340,000-unit addressable market by 2030.
- AI-Driven Predictive Maintenance:Convergence of vibration sensors, oil analysis telemetry, and machine learning platforms enables generator-as-a-service business models that capture lifetime value through subscription uptime guarantees rather than equipment margin.
Industry Challenges
- Dual-Fuel Calibration Technician Scarcity:Field service networks lack sufficient technicians trained on simultaneous diesel-gas combustion tuning, extending commissioning timelines and forcing manufacturers to absorb travel costs for factory specialist deployment.
- NFPA 110 Type 10 Certification Bottlenecks:Emergency power system startup time validation requires witnessed third-party testing at overloaded laboratories, delaying product launches by 4-7 months for new dual-fuel control software releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Fuel Generators Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Diesel, Natural Gas, Propane, Biogas Power Rating: 5 kW, 10 kW, 20 kW, 50 kW Application: Residential, Commercial, Industrial, Emergency Installation Type: Portable, Stationary, Automatic, Manual |
| Companies Covered | Generac Holdings Inc., Cummins Inc., Kohler Co., Honda Power Products, Briggs & Stratton, Caterpillar Inc., Yamaha Motor Corporation, Champion Power Equipment, DuroMax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Fuel Generators Market Emerging Trajectories
Digital twins and edge computing are reshaping how generator fleets are monitored, maintained, and monetized, shifting value capture from hardware shipment toward performance-guaranteed service contracts and fuel optimization algorithms.
Modular power electronics with silicon carbide switching elements are decomposing traditional generator-set architectures by enabling variable-speed engine operation that matches electrical load without fixed-frequency mechanical constraints. Data center operators in Northern Virginia and Phoenix are piloting these systems for 10-15% fuel efficiency gains. The technology is decomposing the historical trade-off between engine longevity and transient response capability.
REACH restriction proposals on per- and polyfluoroalkyl substances are forcing European manufacturers to reformulate gasket and seal materials used in fuel system components. Industrial consequences include 18-month qualification timelines for alternative fluoroelastomer compounds. The stationary power sector faces particular exposure given the 25-year service life expectations that accelerate material degradation risk assessments.
Specification authority is migrating from facilities managers to corporate sustainability officers who weight carbon intensity metrics above first-cost comparisons in procurement scorecards. Channel disruption follows as direct OEM engagement replaces distributor relationships for multi-site fleet deployments. This pattern concentrates in California and New York where state disclosure mandates accelerate executive-level visibility into Scope 1 emissions from backup power assets.
Multi Fuel Generators Market Segmentation
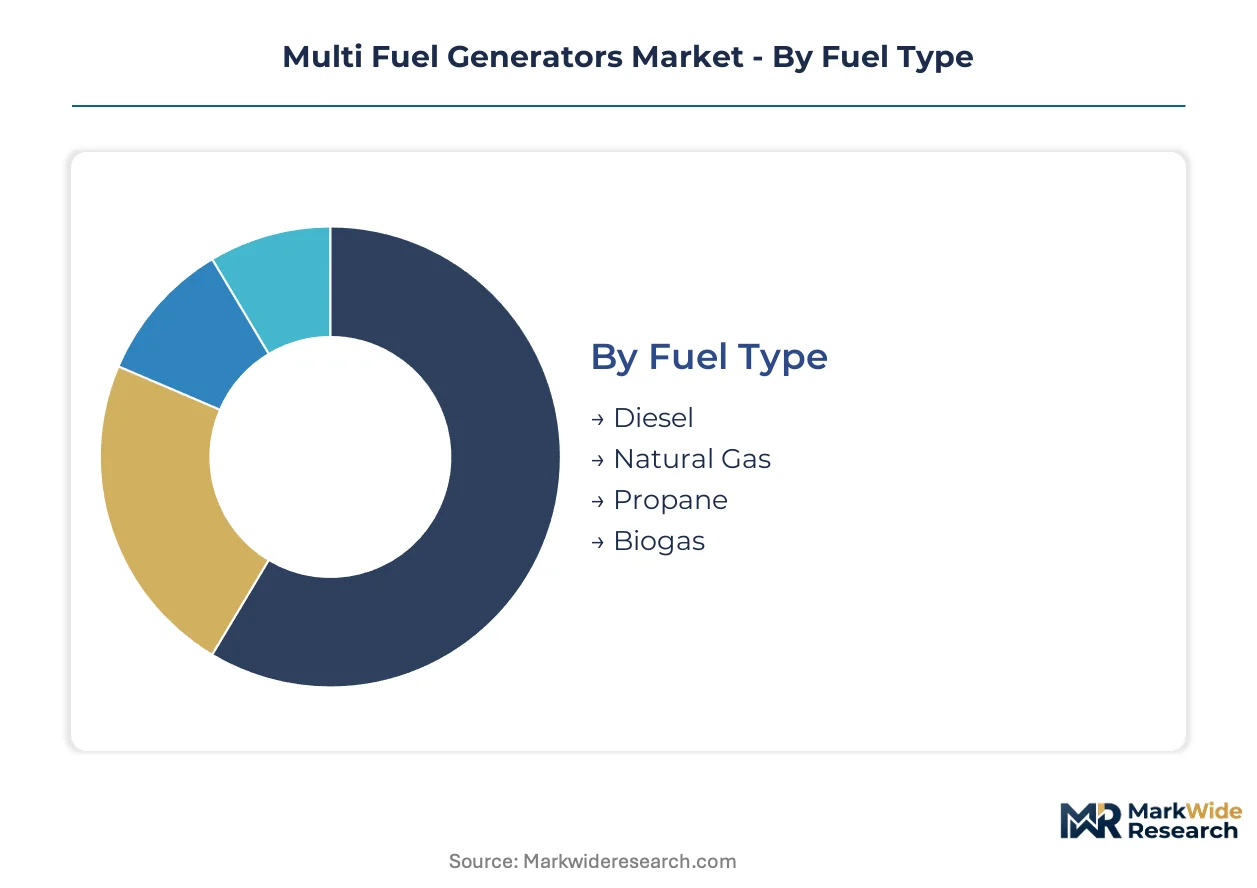
Fuel flexibility determines procurement economics across backup power applications, with substitution pressure varying sharply by operational duty cycle and emission compliance requirements. Segment boundaries blur as dual-fuel architectures enable runtime switching between pipeline gas and stored propane.
Fuel Type:
Biogas and propane face the strongest substitution pressure from electrification and renewable microgrids in distributed generation applications, while diesel-natural gas hybrids defend incumbent positions in heavy industrial load-following.
- Diesel:Compression-ignition engines deliver torque density for heavy industrial startup loads. Demand concentrates in Texas data centers and healthcare facilities where ERCOT grid instability mandates 10-second backup response. EPA Tier 4 Final compliance costs erode share in sub-50 kW installations.
- Natural Gas:Spark-ignited engines with pipeline connectivity eliminate on-site fuel storage. Procurement clusters in Northern Virginia and Phoenix data center corridors where carbon intensity metrics drive sustainability officer specification authority. Lower maintenance intervals improve total cost of ownership calculations.
- Propane:Stored liquid fuel provides redundancy where pipeline infrastructure fails. NFPA 58 setback constraints disqualify 23% of urban commercial sites, preserving diesel-only dominance in dense cores.
- Biogas:Anaerobic digester methane powers agricultural and wastewater installations. IRA investment tax credits accelerate project returns in Wisconsin and California Central Valley dairy regions.
Diesel anchors the volume base while biogas gains share at the steepest rate.
Power Rating:
Cost tier stratification separates premium electronic fuel injection systems above 20 kW from carbureted economy units below 10 kW, with margin compression most severe in portable retail channels.
- 5 kW:Portable residential units for recreational and light backup duty. Champion Power Equipment dominates retail channel density with price-accessible propane-gasoline models.
- 10 kW:Automatic standby systems for residential and small commercial. Generac Holdings anchors North American market with proprietary switchgear technology.
- 20 kW:Light commercial and small industrial applications. Electronic control units enable real-time fuel ratio optimization across diesel-natural gas blends.
- 50 kW:Heavy industrial and data center backup. Cummins leverages integrated engine-electronics platforms for stationary installations.
10 kW systems anchor the volume base while 50 kW units expand most quickly on data center buildouts.
Application:
Customer type migration from facilities managers to corporate sustainability officers reweights procurement scorecards toward carbon intensity metrics over first-cost comparisons.
- Residential:Automatic standby systems for grid outage protection. Retail and e-commerce channels drive higher unit velocity at thinner margins.
- Commercial:Small business and retail backup with flexible-fuel redundancy. Texas healthcare facilities procure systems switching between pipeline gas and on-site propane.
- Industrial:Manufacturing and process load-following. Diesel-natural gas hybrids retain largest installed base where torque density outweighs first-cost premiums.
- Emergency:NFPA 110 Type 10 certification for life safety loads. Third-party testing bottlenecks delay product launches by 4-7 months for new dual-fuel software.
Industrial applications anchor the volume base while emergency systems climb the fastest on code compliance mandates.
Installation Type:
Supply concentration in precision dual-fuel injectors from German and Japanese suppliers creates 12-16 week lead time vulnerability during semiconductor allocation crunches.
- Portable:Sub-10 kW units for recreational and construction duty. Retail channel density determines competitive positioning.
- Stationary:Permanent industrial and commercial installations. Silicon carbide switching elements enable 10-15% fuel efficiency gains in variable-speed pilot programs.
- Automatic:Transfer switch compatibility for seamless grid-island transitions. Specification authority migrates to direct OEM engagement for multi-site fleet deployments.
- Manual:Economy tier for cost-constrained applications. Technician scarcity on dual-fuel calibration extends commissioning timelines.
Stationary installations anchor the volume base while automatic systems gain share fastest on data center procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision dual-fuel injector manufacturing concentrates among German and Japanese suppliers, creating geographic vulnerability in upstream component supply. Data center buildouts in Northern Virginia and Phoenix drive North American procurement volume. Grid instability in Texas accelerates flexible-fuel adoption for commercial backup.
United States
ERCOT frequency excursions and winter storm vulnerabilities compel data center operators and healthcare facilities to procure systems switching between pipeline gas and on-site propane. EPA Tier 4 Final standards fragment supplier economics by forcing diesel-dependent manufacturers into dual-fuel engineering investments. Procurement clusters in Northern Virginia and Phoenix data center corridors where carbon intensity metrics drive sustainability officer specification authority.
Germany
Industrial load-following applications defend incumbent positions for diesel-natural gas hybrids where torque density outweighs first-cost premiums. REACH restriction proposals on per- and polyfluoroalkyl substances force reformulation of gasket and seal materials with 18-month qualification timelines. Manufacturing concentration in Baden-Württemberg and North Rhine-Westphalia anchors European supply of precision fuel injection components.
China
Rural broadband expansion under infrastructure programs specifies hybrid renewable-diesel-propane configurations for off-grid cell sites. MIIT and GB standards shape certification requirements for domestic manufacturers serving backup power applications. Yangtze River Delta industrial clusters produce electronic control units enabling real-time fuel ratio optimization.
India
Agricultural and wastewater treatment applications accelerate adoption where methane capture economics improve project returns. BIS certification and state-level public utility commission standby-power incentives steer procurement specifications toward lower-emission fuel flexibility. Maharashtra and Gujarat industrial corridors concentrate demand from manufacturing facilities requiring load-following capability.
Japan
Precision dual-fuel injectors for high-pressure natural gas delivery concentrate among specialized suppliers creating 12-16 week lead time vulnerability. METI grid resilience programs and carbon intensity benchmarks determine which fuel combinations qualify for procurement preferences. Kanto and Kansai metropolitan areas drive commercial backup installations with automatic transfer switch compatibility.
Multi Fuel Generators Market Vendor Landscape
Concentration sits with integrated engine-electronics platforms and proprietary switchgear technology providers. The competitive landscape bifurcates into emission-compliant premium suppliers and cost-focused conventional vendors. Three archetypes dominate: diversified industrial conglomerates with captive engine manufacturing, specialized power generation equipment manufacturers, and retail-channel portable power specialists. Competitive moves center on dual-fuel engineering investments and direct OEM engagement replacing distributor relationships for multi-site fleet deployments.
Among North American industrial equipment manufacturers, Cummins Inc. and Generac Holdings Inc. exemplify the integrated platform archetype, while Champion Power Equipment occupies the retail-channel portable power tier. These three companies represent distinct competitive positioning strategies across stationary industrial installations, residential automatic-standby systems, and price-accessible consumer segments. Their geographic concentration in Wisconsin and Minnesota industrial corridors reflects historical manufacturing density in power generation equipment.
| Leading Market Players |
|---|
| Generac Holdings Inc. |
| Cummins Inc. |
| Kohler Co. |
| Honda Power Products |
| Briggs & Stratton |
| Caterpillar Inc. |
| Yamaha Motor Corporation |
| Champion Power Equipment |
| DuroMax |
| Others |
Supply Flow & Price Mechanics
Long-term biogas offtake contracts lock in fuel supply visibility and price predictability for agricultural generator installations, insulating project developers from spot propane volatility while binding OEMs to dedicated manufacturing slots for Tier 4 Final-compliant units.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure by bifurcating manufacturers into emission-compliant premium suppliers absorbing stainless steel exhaust component costs and cost-focused conventional vendors defending diesel-only share. Pricing stratifies across EPA-certified dual-fuel systems, single-fuel natural gas units, and carbureted portable economy models. Cost compression in sub-50 kW diesel installations is intensifying because selective catalytic reduction substrate pricing volatility erodes margins. Residential retail channels exhibit highest price sensitivity, while data center operators in Northern Virginia and Phoenix prioritize carbon intensity metrics over first-cost comparisons.
Supply Chain Analysis
Precision dual-fuel injector manufacturing concentrates in Baden-Württemberg and industrial zones in Japan, creating single-source vulnerability for high-pressure natural gas delivery hardware. Stainless steel alloys for diesel particulate filter substrates and silicon carbide switching elements for modular power electronics feed from German and Chinese suppliers. Tariff exposure on precision fuel injection components threatens 12-16 week lead time extensions during semiconductor allocation crunches. Distribution runs through authorized dealer networks for stationary industrial installations, direct OEM engagement for multi-site data center fleets, and retail channel density for portable consumer units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority migration from facilities managers to corporate sustainability officers fragments specification standards, creating niche opportunities for emission-certified specialists and fuel-flexible technology providers across backup power applications.
For Market Incumbents: Consolidate control over dual-fuel calibration technician training networks to compress commissioning timelines, and deepen backward integration into electronic control unit manufacturing to reduce dependency on Yangtze River Delta suppliers. Electrification of distributed generation and renewable microgrid substitutes threaten diesel-natural gas hybrid positions in light commercial segments. Certification investment in NFPA 110 Type 10 validation capacity accelerates product launch velocity against testing laboratory bottlenecks. For New Entrants and Emerging Players: Anchor in Wisconsin and California Central Valley dairy regions where anaerobic digestion projects lack integrated power generation partners, offering bundled biogas-ready units with 20-year fuel offtake agreements. The agricultural and wastewater treatment segment presents lowest competitive density. Direct engagement with biogas project developers bypasses established distributor relationships controlled by incumbents. For Investors and Strategic Acquirers: The market sits at a regulatory inflection phase that favors emission-compliant technology specialists with captive fuel injection hardware capabilities. Long-term viability hinges on positioning for carbon intensity disclosure mandates expanding beyond California and New York. Acquisition targets should demonstrate EPA Tier 4 Final certification breadth and automatic transfer switch integration expertise. Monitor state-level public utility commission standby-power incentive revisions as the signal indicating which fuel combinations will qualify for preferential procurement scoring.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Engineering Investment | EPA Tier 4 Final compliance locks in premium supplier positioning against diesel-dependent competitors. |
| Biogas Digester Partnership | IRA investment tax credits in dairy regions improve project returns for bundled fuel-flexible installations. |
| Predictive Maintenance Platform | Machine learning uptime guarantees shift value capture from equipment margin to subscription revenue. |
| Silicon Carbide Power Electronics | Variable-speed pilot programs in Phoenix data centers yield 10-15% fuel efficiency improvements. |
| Direct OEM Fleet Engagement | Sustainability officer specification authority disrupts distributor relationships for multi-site deployments. |
Methodological Framework
Desk research of EPA certification databases, FERC interconnection filings, and EIA grid reliability reports preceded structured interviews with data center infrastructure directors, healthcare facilities engineers, agricultural biogas project developers, and industrial plant maintenance managers. Primary fieldwork with generator OEM product planners and aftermarket service heads validated secondary findings on dual-fuel adoption barriers. SEC 10-K disclosures from diversified industrial conglomerates and specialized power generation equipment manufacturers supplied financial trajectory data. Bottom-up unit shipment modeling across power rating tiers triangulated against top-down market value estimates from equipment procurement databases.
Variance decomposition separates fuel type substitution effects, regulatory compliance cost pass-through, and regional grid instability demand spikes across the projection horizon. Segmentation dimensions include fuel flexibility architecture, power rating tier, installation type, and application duty cycle, with EPA certification status as an industry-specific overlay. CAGRs derive from logistic diffusion curves fitted to dual-fuel penetration patterns in Texas and Northern Virginia data center corridors. Forecast inputs incorporate IRA tax credit phase-out assumptions and REACH restriction timelines for fluoroelastomer gasket materials.
Underlying assumptions cover ERCOT frequency excursion persistence, stainless steel alloy pricing mean-reversion, and semiconductor allocation normalization, with deviation risk concentrated in NFPA 110 Type 10 certification bottlenecks and dual-fuel injector supply concentration. Practitioners should keep alternative scenarios live as state-level carbon intensity benchmarks and interconnection standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
South America Portable Generator Market
Generators
Emergency Power Generators Sales Market
Generators
India Diesel Generator Market
Generators
Generator Sets Market
Generators
Saudi Arabia Diesel Generator Market
Generators
Asia-Pacific Generator Sets Market
Generators
Reciprocating Power Generating Engine Market
Generators
Middle East and Africa Gas Generator Market
Generators
South America Diesel Generator Market
Generators
Wind Power Generators Market
Generators
Portugal Gas Generator Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Dual-Fuel Generator Market
Generators
Natural Gas Generator Market
Generators
Turbo Generator Market
Generators
Asia Pacific Electric Generators Market