
 North West Europe Diesel Generator Market | 2026-2036
North West Europe Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
North West Europe Diesel Generator Market Analytics
Aftermarket service revenue is reshaping margin capture across the North West Europe diesel generator value chain. Cummins Inc. leverages its extensive parts and service network to sustain recurring income from long-tenured industrial installations. MTU Onsite Energy GmbH anchors premium positioning through factory-authorized overhaul programs for marine and data center fleets. Himoinsa S.L. competes on rapid-response maintenance contracts tailored to construction site mobility requirements.
Diesel generators in North West Europe comprise compression-ignition engine sets rated from ten kilowatts to multiple megawatts, typically integrating alternators, fuel systems, and electronic governors for frequency regulation. These units provide emergency backup, prime power, or grid-support functions across industrial, commercial, and marine environments where electrical continuity carries operational or safety-critical weight. Standby generators command the largest installed base as healthcare and data center operators prioritize regulatory-mandated redundancy, while hybrid systems represent the fastest-expanding technology category as operators seek to moderate runtime hours and fuel exposure. Industrial generators concentrate margin pools in the upper power band where customization, enclosure engineering, and exhaust after-treatment complexity elevate pricing authority.
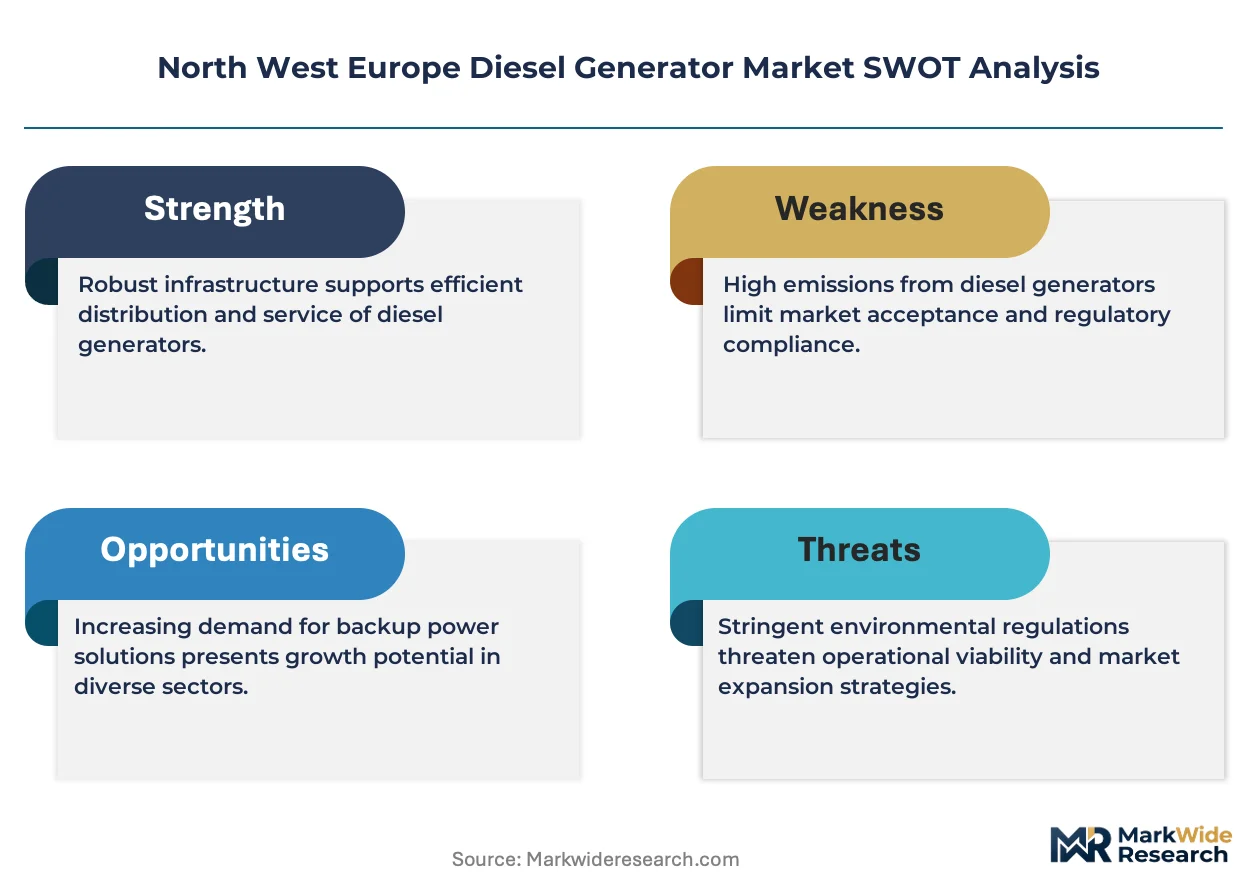
EU Stage V emissions regulations enforced by national type-approval authorities in Germany, the Netherlands, and the United Kingdom constrain engine certification and dictate selective catalytic reduction or diesel particulate filter fitment across non-road mobile and stationary applications. CE marking under the Machinery Directive and national implementation of the EU Green Deal's decarbonization pathways further condition product design and fleet replacement timing. Stakeholders must monitor evolving national bans on fossil-fuel backup in urban zones and assess hybrid architecture investments against stranded-asset risk in long-duration installations.
Market Dynamics
EU Stage V emissions standards are forcing a technology pivot across North West Europe, compressing conventional diesel generator margins while elevating hybrid-electric architectures and advanced after-treatment systems in procurement specifications.
Growth Catalysts
- Data center buildout:Cloud infrastructure investment across Ireland and the Netherlands sustains demand for megawatt-class standby installations with sub-ten-second start requirements.
- EU Green Deal implementation:National decarbonization pathways in Germany and the Netherlands accelerate fleet replacement timelines for aging prime-power generator bases.
- Port-industrial clustering:Rotterdam's maritime logistics hub generates continuous procurement of marine-certified generator sets for shore power and vessel auxiliary applications.
Market Restraints
- Platinum group metal cost volatility:Selective catalytic reduction catalyst substrates expose manufacturers to palladium and rhodium price swings that compress after-treatment margins.
- Engine supply concentration:Heavy dependence on a limited supplier base for sub-19kW Stage V-certified power units creates allocation bottlenecks during peak construction seasons.
- Electrochemical substitution:Lithium-ion battery energy storage systems with four-hour duration capability are capturing short-duration backup applications previously served by diesel gensets.
Strategic Opportunities
- Hybrid architecture penetration:Diesel-battery hybrid systems combining variable-speed engines with power electronics open margin pools in grid-support and peak-shaving applications.
- Service contract unbundling:Predictive maintenance platforms using IoT-enabled remote monitoring create recurring revenue streams independent of equipment sales cycles.
- Urban decarbonization carve-outs:Municipal fossil-fuel backup bans in Amsterdam and Rotterdam city centers drive demand for renewable-diesel-compatible generator configurations.
Industry Challenges
- Stage V certification timeline compression:National type-approval authorities in Germany and the Netherlands impose extended validation periods for novel after-treatment configurations, delaying product launches.
- Electronics-thermal integration complexity:Power electronics cooling requirements in hybrid systems demand thermal management expertise absent from traditional generator assembly workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North West Europe Diesel Generator Market |
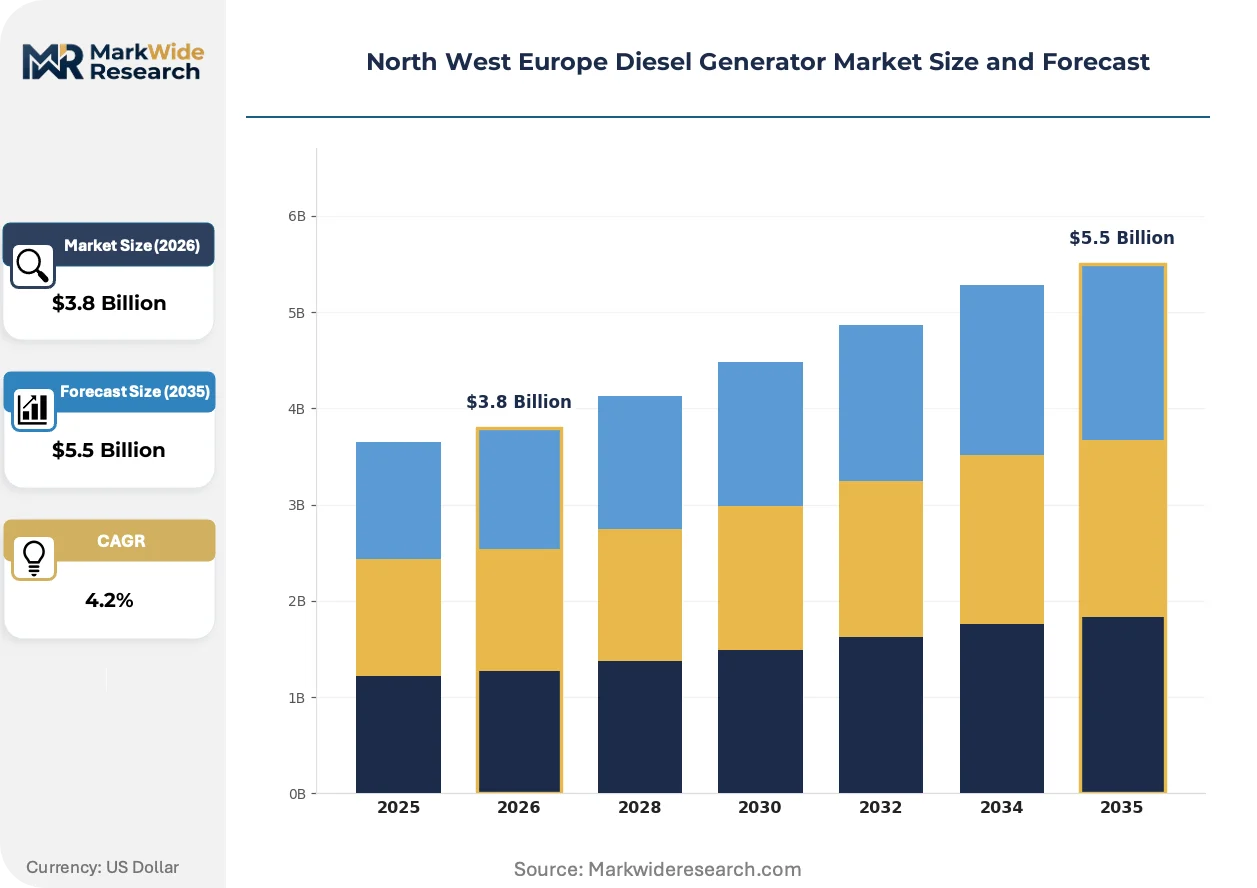
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Industrial Generators, Marine Generators End User: Construction, Healthcare, Telecommunications, Data Centers Application: Backup Power Supply, Prime Power Supply, Continuous Power Generation, Peak Shaving Technology: Air-Cooled, Water-Cooled, Digital Control, Hybrid Systems |
| Companies Covered | Atlas Copco Ltd., Caterpillar Inc., Cummins Inc., AJ Power Ltd., Kohler Co., Perkins Engines Company Limited, MTU Onsite Energy GmbH, Himoinsa S.L., F.G. Wilson, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North West Europe Diesel Generator Market Evolving Landscape
Technology convergence between power electronics and compression-ignition engines is redefining product architecture across North West Europe, compressing development cycles and elevating software competency requirements among incumbent manufacturers.
Variable-speed diesel generator technology with permanent magnet alternators and active rectification is rendering obsolete fixed-speed 1500 RPM synchronous machines in prime-power and grid-support applications. Data center operators in the Netherlands are specifying these configurations for load-following duty cycles. The technology is rendering obsolete traditional governor-based frequency regulation and the associated mechanical maintenance intervals.
EU Stage V emissions regulations enforced by Germany's KBA and the Netherlands' RDW constrain engine certification pathways and mandate selective catalytic reduction or diesel particulate filter fitment across non-road mobile machinery. Industrial generator OEMs are consolidating engine supplier relationships to secure type-approved power units. Marine and data center segments face the steepest compliance cost escalation due to extended runtime requirements and enclosure space constraints for after-treatment hardware.
Buying organizations are consolidating vendor relationships and demanding outcome-based availability guarantees rather than equipment-centric procurement. Large industrial operators in Ireland's pharmaceutical corridor now contract for guaranteed power continuity with penalty clauses, transferring operational risk to generator service providers. This model concentrates in data center and healthcare verticals where regulatory uptime mandates create liability exposure for facility operators.
North West Europe Diesel Generator Market Segmentation
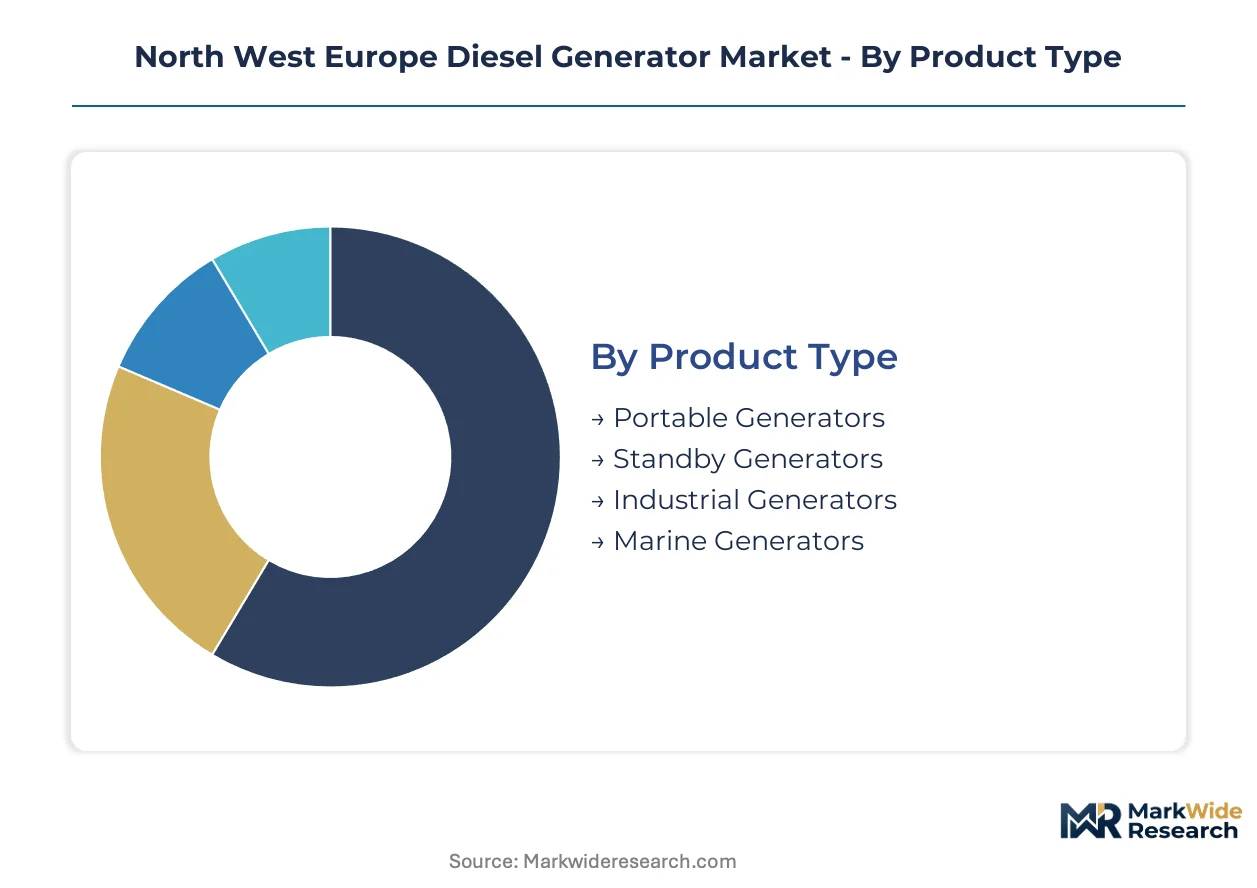
Segmentation in the North West Europe diesel generator market reveals distinct margin profiles and technology requirements across power classes and duty cycles. Procurement specifications diverge sharply between intermittent standby installations and continuous prime-power operations.
Product Type:
Cost tier separation defines competitive positioning across product categories, with enclosure engineering and emissions after-treatment driving price stratification.
- Standby Generators:Fixed-speed 1500 RPM synchronous machines with automatic transfer switches and sub-ten-second start capability. Healthcare operators in Ireland and data center developers in the Netherlands specify these for regulatory-mandated redundancy, with Stage V after-treatment now standard above 19kW.
- Industrial Generators:Custom-engineered skid-mounted or containerized sets from 500kW to multiple megawatts. Prime-power installations at Rotterdam's port-industrial cluster demand these configurations for extended runtime durability and fuel efficiency optimization.
- Portable Generators:Mobile trailer-mounted units rated 10-300kW for construction site flexibility.
- Marine Generators:Classification society-certified sets for vessel auxiliary and shore power applications.
Standby generators hold installed capacity. Industrial generators are rotating up the share rankings.
End User:
Application intensity varies dramatically by customer vertical, with uptime liability and regulatory exposure dictating specification stringency.
- Data Centers:Hyperscale cloud operators in Amsterdam's data center corridor procure megawatt-class N+1 redundant installations with lithium-ion hybrid integration. EU Green Deal implementation pressures these operators to minimize diesel runtime hours while maintaining Tier III/Tier IV certification.
- Healthcare:Hospital groups across Germany and the Netherlands require life-safety-grade backup with 72-hour fuel autonomy and seismic-rated enclosures. National building codes mandate these specifications for acute care facilities.
- Telecommunications:Mobile network operators deploy compact standby sets for base station resilience.
- Construction:Rental fleet operators favor portable units with rapid-deployment mobility.
Data centers command specification leadership. Healthcare maintains procurement volume stability.
Application:
Duty cycle classification determines engine loading profiles and maintenance interval economics.
- Backup Power Supply:Intermittent operation with annual test-run requirements dominates installed base. Data center operators in Ireland specify these for grid-failure ride-through, with remote monitoring integration now standard.
- Prime Power Supply:Continuous or extended-duration operation at variable load. Off-grid industrial facilities and remote construction camps in the Netherlands deploy these where grid extension is uneconomic.
- Continuous Power Generation:Base-load operation with scheduled maintenance windows.
- Peak Shaving:Grid-support duty cycles with frequent start-stop operation.
Backup power holds installed capacity. Peak shaving is climbing the fastest as grid services monetize.
Technology:
Thermal management architecture and control system sophistication separate premium from standard offerings.
- Hybrid Systems:Diesel-battery configurations with variable-speed engines and active rectification. Dutch data center operators specify these for load-following duty cycles, with power electronics enabling frequency regulation without mechanical governors.
- Digital Control:Electronic engine management with IoT-enabled predictive maintenance platforms. Industrial operators in Germany's pharmaceutical corridor contract for guaranteed availability through these systems.
- Water-Cooled:Closed-loop radiator or heat exchanger configurations for enclosed installations.
- Air-Cooled:Simplified thermal management for portable and lower-power standby applications.
Water-cooled architectures hold installed capacity. Hybrid systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across North West Europe. Irish data center operators absorb premium pricing for sub-ten-second start capability, while Dutch construction rental fleets negotiate aggressively on portable unit rates. German industrial buyers balance total cost of ownership against emissions compliance premiums.
Netherlands
Amsterdam's data center corridor sustains megawatt-class standby procurement as hyperscale cloud operators expand N+1 redundant installations. The Netherlands' RDW enforces Stage V type-approval with extended validation timelines for novel after-treatment configurations. Rotterdam's port-industrial cluster generates continuous demand for marine-certified generator sets serving shore power and vessel auxiliary applications.
Ireland
Pharmaceutical manufacturers in Cork and Dublin procure life-safety-grade backup systems with 72-hour fuel autonomy mandated by national building codes. The country's EPA implements EU Green Deal decarbonization pathways that accelerate fleet replacement timelines. Microsoft's and Amazon's hyperscale facilities in Greater Dublin anchor Europe's fastest-growing data center construction pipeline.
Germany
Industrial machinery OEMs in Bavaria and Baden-Württemberg specify prime-power generators for factory-floor resilience against grid instability. Germany's KBA imposes rigorous Stage V certification procedures that compress conventional diesel margins while elevating hybrid system specifications. The Rhine-Ruhr industrial corridor maintains dense installed bases requiring factory-authorized overhaul programs.
United Kingdom
Healthcare trusts across England and Scotland mandate seismic-rated enclosures and extended fuel autonomy for acute care facilities. The UK's Environment Agency enforces non-road mobile machinery regulations that align with EU Stage V standards post-Brexit. London's financial district sustains demand for Tier III/Tier IV certified installations with remote monitoring integration.
North West Europe Diesel Generator Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct player tiers: multinational engine manufacturers with captive generator assembly, specialized power system integrators with regional service density, and rental fleet operators with asset-heavy balance sheets. Competitive moves center on hybrid technology licensing partnerships and predictive maintenance platform acquisitions that unbind revenue from equipment sales cycles.
Within the multinational engine tier, Cummins Inc., Caterpillar Inc., and MTU Onsite Energy GmbH exemplify divergent strategic positions. Cummins represents the vertically integrated archetype with extensive parts and service networks sustaining recurring income. Caterpillar occupies the scale-driven position with global distribution infrastructure. MTU Onsite Energy anchors premium positioning through factory-authorized programs. Each exemplifies how engine supply concentration shapes downstream generator market structure.
| Leading Market Players |
|---|
| Atlas Copco Ltd. |
| Caterpillar Inc. |
| Cummins Inc. |
| AJ Power Ltd. |
| Kohler Co. |
| Perkins Engines Company Limited |
| MTU Onsite Energy GmbH |
| Himoinsa S.L. |
| F.G. Wilson |
| Others |
Value Network & Pricing Analysis
Rotterdam's port-industrial cluster concentrates Stage V-certified engine assembly capacity, translating upstream component scarcity into pricing leverage for prime-power installations serving maritime and data center buyers. Dutch RDW validation timelines extend procurement cycles, compressing margin buffers for OEMs while elevating aftermarket service premiums.
Pricing Analysis
Factory-authorized overhaul programs anchor lifetime value capture for premium generator OEMs serving marine and data center fleets. Three-tier pricing structure across premium, standard, and economy levels separates MTU Onsite Energy's certified service networks from Himoinsa's rapid-response construction contracts and Cummins' volume-driven parts distribution. Cost compression in sub-19kW portable units intensifies as Chinese engine suppliers expand CE-marked offerings. Dutch construction rental fleets exhibit highest price sensitivity, while Irish pharmaceutical operators absorb premiums for guaranteed availability contracting.
Supply Chain Analysis
EU dual-use export controls on permanent magnet alternators and active rectification power electronics constrain technology flows to non-EU assembly operations. Engine block casting and high-pressure common-rail fuel systems draw from Germany, Italy, and the United Kingdom, while selective catalytic reduction catalyst substrates rest on South African and Russian palladium-rhodium supply. Single-source vulnerability concentrates in sub-19kW Stage V power unit certification, where Germany's KBA and the Netherlands' RDW maintain exclusive type-approval authority. Distribution runs through factory-authorized dealer networks for industrial installations and rental fleet operators for portable construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story. EU Stage V certification requirements create switching costs that entrench incumbent OEMs with established type-approval pathways and factory-authorized service networks.
For Market Incumbents: Build certification-moat depth by securing extended validation partnerships with Germany's KBA and the Netherlands' RDW for novel hybrid after-treatment configurations. Acquire predictive maintenance platform capabilities to unbind revenue from equipment sales cycles. Lithium-ion battery substitution threatens short-duration standby applications; anchor defensive positioning through guaranteed availability contracting with Irish data center and German pharmaceutical operators. For New Entrants and Emerging Players: Pursue white-space penetration in renewable-diesel-compatible generator configurations serving Amsterdam and Rotterdam urban decarbonization carve-outs. Target construction rental fleet replacement cycles in the Netherlands where rapid-response maintenance contracts command premium positioning. Leverage IoT-enabled remote monitoring as differentiated go-to-market entry against incumbent parts-network scale. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors power electronics-thermal management specialists with hybrid architecture integration capabilities. Five-to-ten year viability hinges on stranded-asset risk assessment for conventional diesel-only installations against EU Green Deal decarbonization pathways. Acquire predictive maintenance platform operators with existing data center and healthcare customer density. Watch for municipal fossil-fuel backup ban acceleration as inflection indicator forcing fleet replacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Architecture Licensing | Variable-speed diesel-battery integration opens grid-support margin pools for Dutch data center operators. |
| Predictive Maintenance Platform Acquisition | IoT-enabled remote monitoring creates recurring revenue independent of Cummins-scale parts networks. |
| Renewable-Diesel Compatibility Certification | Amsterdam and Rotterdam urban decarbonization carve-outs demand HVO-compatible generator configurations. |
| Factory-Authorized Overhaul Program Expansion | MTU Onsite Energy's marine and data center service density anchors premium pricing in Ireland's pharmaceutical corridor. |
| Stage V Type-Approval Partnership Consolidation | Extended KBA and RDW validation timelines favor OEMs with established regulatory relationships. |
Research Methodology
The analysis maps standby, prime-power, and hybrid system configurations, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with data center infrastructure planners, healthcare facility managers, and port-industrial operators combined with secondary validation from EU type-approval authority filings, national building code implementations, and customs trade data for generator set imports. Bottom-up installation tracking and top-down macroeconomic triangulation anchored market sizing across power classes and duty cycles.
Assumptions held fixed include EU Stage V enforcement timelines and national Green Deal decarbonization pathway commitments, while fuel price volatility and battery substitution rates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass power rating tier, application duty cycle, end-use vertical, cooling architecture, and control system sophistication. CAGRs derived from regression analysis against historical installation data, cloud infrastructure capex disclosures, and pharmaceutical manufacturing capacity expansion announcements.
Sensitivities concentrate around regulatory acceleration of urban fossil-fuel backup bans and lithium-ion battery duration extension beyond four-hour capability. Forecasts reflect documented assumptions on emissions compliance cost trajectories and hybrid technology adoption curves. Material shifts in EU Green Deal implementation timelines or Stage V certification reciprocity agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Construction Portable Generators Market
Generators
Wind Power Generators Market
Generators
Industrial Generator Sets Market
Generators
Generator [Up to 100 Kva] Market
Generators
East Africa Diesel Generator Market
Generators
Heat Recovery System Generator Market
Generators
Middle East Portable Generator Market
Generators
North America Portable Generators Market
Generators
Portugal Gas Generator Market
Generators
Onboard Marine Gensets Market
Generators
Residential Gas Generator Market
Generators
Asia-Pacific Portable Generator Market
Generators
South America Gas Generator Market
Generators
Europe Gas Turbine Market
Generators
Electric Generators Market
Generators
Gas Generator Market