
 Middle-East and Africa Portable Generator Market | 2026-2036
Middle-East and Africa Portable Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Portable Generator Market Foresight
Middle Eastern manufacturing clusters for portable power equipment is decoupling from traditional European supply dependencies as regional assembly capacity expands. Generac Holdings Inc. sustains brand recognition across Gulf Cooperation Council markets through extensive distributor networks. Atlas Copco AB anchors its position in African mining and infrastructure sectors with ruggedized diesel generator lines. Yamaha Motor Co. Ltd differentiates through compact inverter technology suited for remote telecommunications installations.
A portable generator is a self-contained internal combustion or photovoltaic-electric machine that converts mechanical or solar energy into alternating-current electricity, typically rated between 1 kW and 15 kW for mobile deployment, designed to supply off-grid or backup power at construction sites, residential compounds, and remote industrial facilities. Conventional generators still occupy the largest installed base across the region due to lower capital outlay and familiar maintenance protocols, though inverter generators are gaining ground where fuel efficiency and noise restrictions matter. Diesel generators dominate the African mining and heavy construction segments where runtime duration and torque stability outweigh emissions concerns, while solar generators are emerging fastest in UAE and Saudi Arabian telecom tower applications where subsidy frameworks favor renewable integration.
Saudi Arabia's SFDA and the UAE's environmental regulator enforce emissions certification for imported power equipment, creating compliance barriers for uncertified manufacturers. South Africa's central energy regulator and Nigeria's standards bureau both mandate safety testing protocols that shape product specifications for equipment entering their markets. Stakeholders must monitor how evolving carbon-border mechanisms and local-content requirements will reshape sourcing decisions and aftermarket service obligations across the region.
Market Dynamics
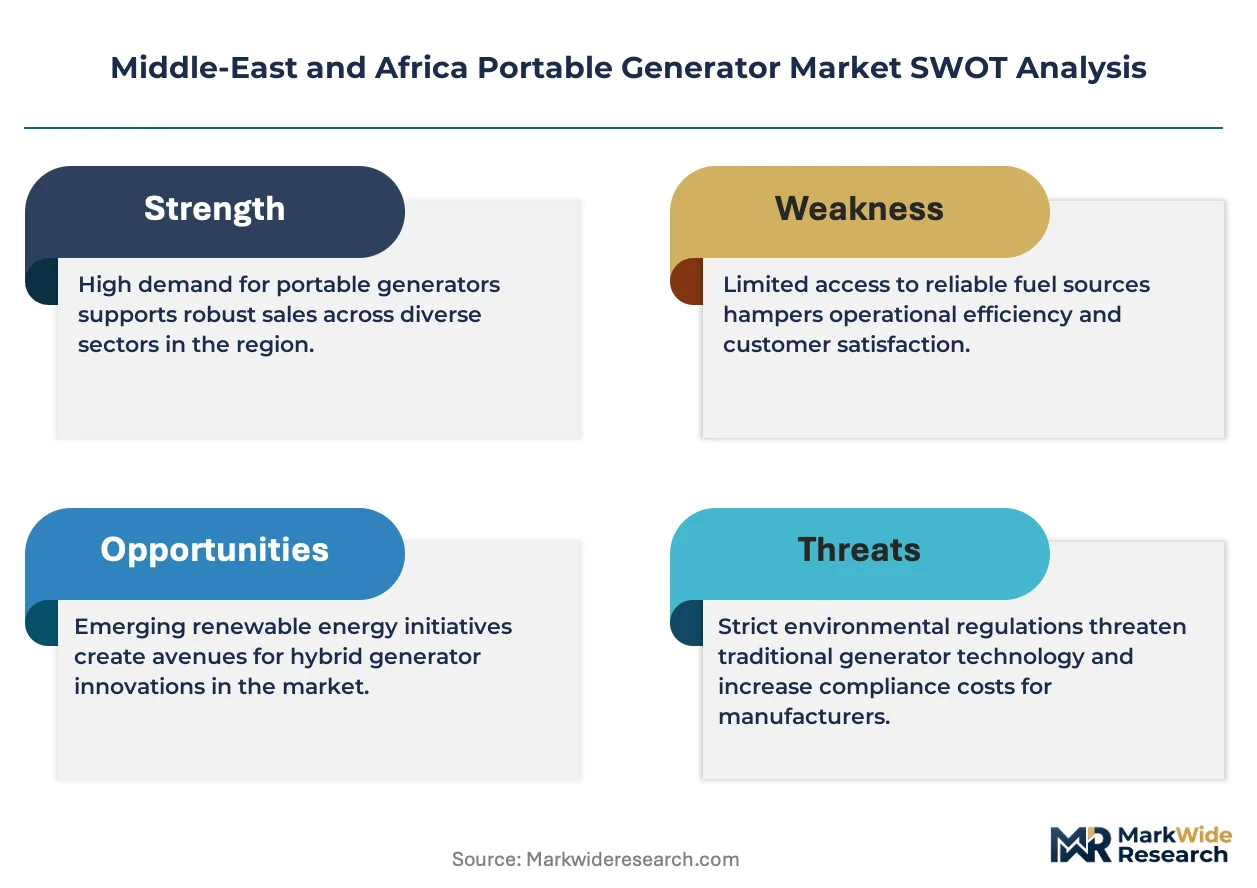
Grid instability across Nigeria's commercial centers and Saudi Arabia's giga-project construction zones is forcing distributed power procurement into capital expenditure plans previously reserved for grid-tied equipment.
Growth Catalysts
- Saudi Vision 2030 infrastructure mandates:Giga-project construction corridors require mobile power redundancy where grid connection timelines lag site activation schedules.
- Propane fuel-system retrofits:Cleaner-burning configurations satisfy UAE environmental regulator emissions protocols while maintaining runtime duration for construction fleets.
- South African mining belt electrification gaps:Underground operations and remote processing facilities depend on portable diesel units for torque-stable auxiliary power.
Market Restraints
- Diesel price volatility:Fuel cost swings compress rental margins for equipment lessors serving Nigerian construction sites.
- Chinese engine-block supply concentration:Regional assemblers remain dependent on single-source imports for sub-10 kW powertrain components.
- SFDA import certification timelines:Saudi equipment registration protocols extend product launch cycles by four to six months for uncertified manufacturers.
Strategic Opportunities
- Ethiopia's underpenetrated telecom tower market:Off-grid base stations in the Oromia and Amhara regions lack reliable backup power infrastructure.
- Solar-hybrid generator convergence:Photovoltaic-diesel hybrid systems capture UAE subsidy frameworks for renewable-integrated telecom applications.
- Direct-to-contractor digital channels:Equipment rental platforms are bypassing traditional distributor markups for South African construction SMEs.
Industry Challenges
- Certification documentation gaps:Nigerian standards bureau safety testing requirements lack harmonized protocols with Gulf Cooperation Council regimes, forcing duplicate compliance spend.
- Aftermarket technician scarcity:Inverter-generator electronic control module repair skills concentrate in UAE service hubs, leaving East African operators dependent on fly-in support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Portable Generator Market |
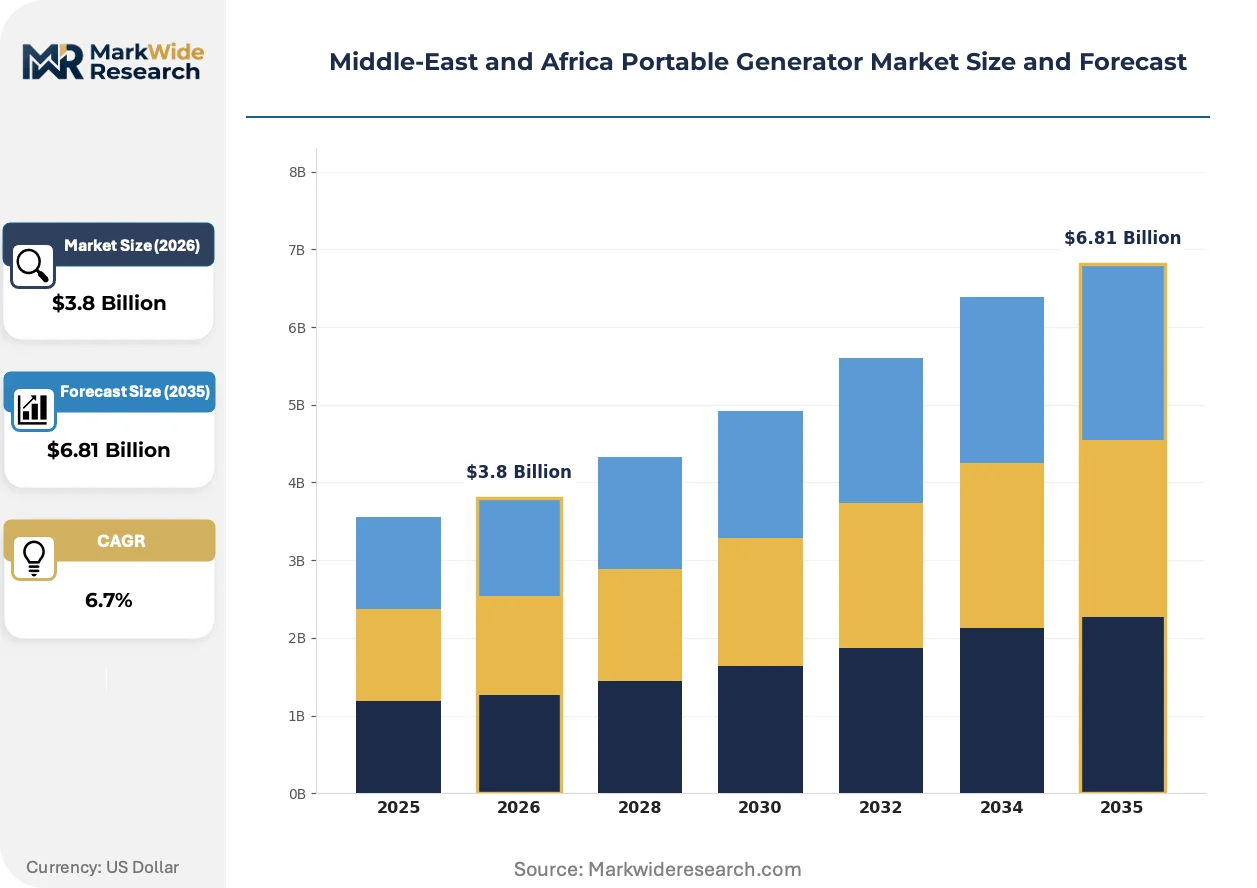
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverter Generators, Conventional Generators, Solar Generators, Diesel Generators Fuel Type: Gasoline, Diesel, Propane, Biogas Application: Residential Use, Commercial Use, Industrial Use, Emergency Backup End User: Construction, Recreational, Telecommunications, Events |
| Companies Covered | Atlas Copco AB, Generac Holdings Inc., Yamaha Motor Co. Ltd, Kohler Power Systems, Doosan Portable Power, Caterpillar Inc., Cummins Inc., Honda Middle East, Briggs & Stratton AG, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Portable Generator Market Shifts & Advancements
Equipment intelligence and fuel-flexibility are compressing the performance gap between conventional diesel architectures and next-generation hybrid systems across Middle Eastern and African deployment environments.
Remote monitoring telemetry is automating fleet management for rental operators serving Saudi construction sites. Embedded sensors transmit runtime, fuel consumption, and fault codes to centralized dashboards, enabling predictive maintenance scheduling. This capability is automating dispatch decisions that previously required manual site inspections, compressing response times for equipment failures in remote giga-project zones.
UAE environmental regulator tiered emissions standards are accelerating after-treatment retrofits for diesel generator imports. Selective catalytic reduction and diesel particulate filter mandates now apply to equipment above 19 kW rated output. Construction contractors in Dubai and Abu Dhabi are responding by shifting procurement toward certified-compliant units despite 15-20% capital cost premiums.
Telecom tower operators are unbundling power equipment procurement from engineering-procurement-construction contracts. MTN and Airtel Africa subsidiaries now source portable generators separately from civil works, enabling direct manufacturer relationships and standardized fleet specifications. This pattern is most visible in South Africa's Mpumalanga and Limpopo provinces where tower densification outpaces grid extension.
Middle-East and Africa Portable Generator Market Segmentation
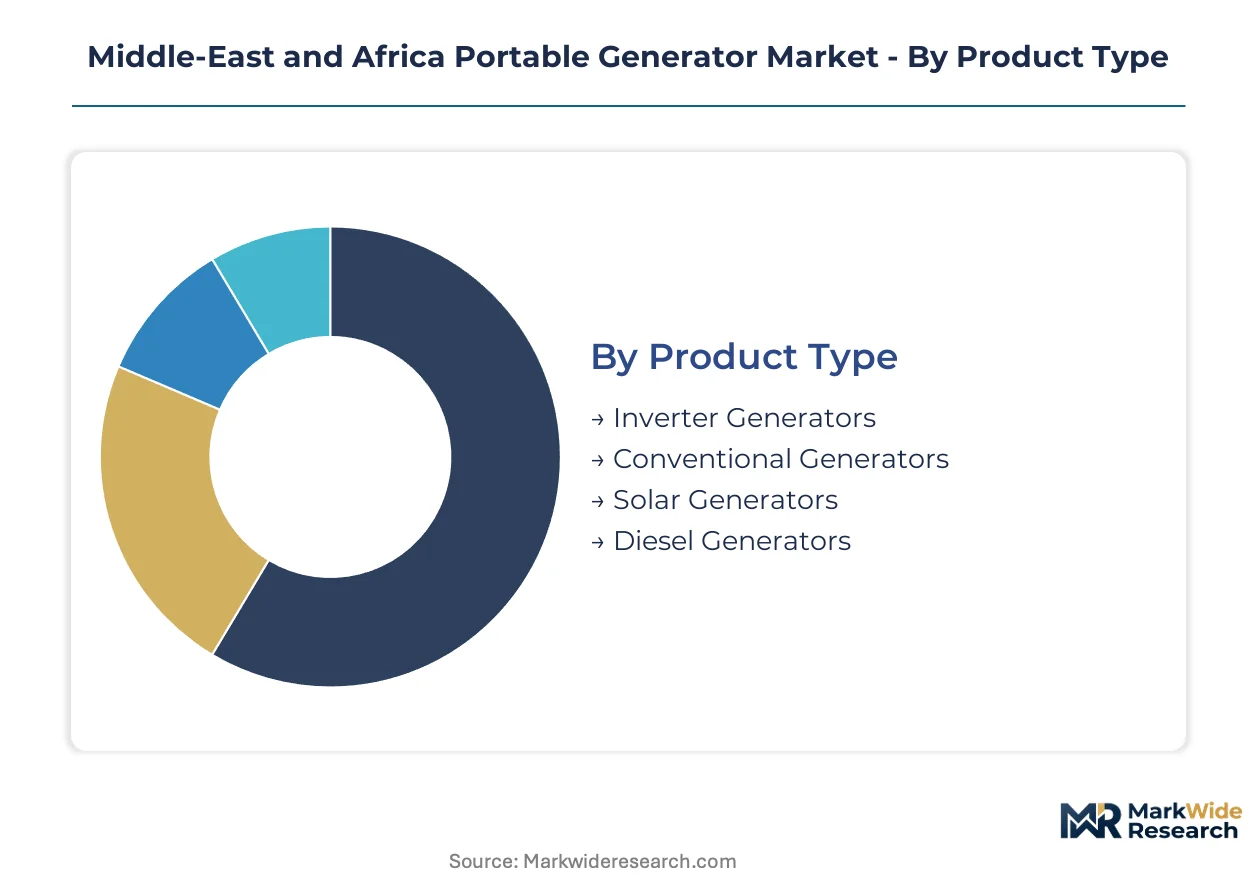
Portable generator procurement across the Middle-East and Africa fragments sharply by fuel availability, emissions constraints, and duty-cycle intensity. Equipment buyers optimize capital deployment differently when grid reliability, runtime duration, or noise restrictions dominate site requirements.
Product Type:
Capital intensity escalates dramatically as electronic control modules, after-treatment systems, and photovoltaic integration layers multiply component costs beyond bare-engine architectures.
- Conventional Generators:Mechanical alternator sets without electronic voltage regulation dominate rental fleets serving Nigerian construction corridors. Lower acquisition costs and familiar repair protocols sustain this segment despite fuel inefficiency.
- Diesel Generators:Compression-ignition architectures rated above 10 kW anchor South African mining operations where torque stability under sustained load outweighs emissions concerns. UAE environmental regulator tiered standards are forcing selective catalytic retrofits on new imports.
- Inverter Generators:Microprocessor-controlled output suits Saudi telecom tower installations where harmonic-sensitive electronics require clean power waveforms.
- Solar Generators:Photovoltaic-battery systems capture UAE subsidy frameworks for off-grid base stations in Dubai's desert corridor.
Most installed capacity flows through conventional mechanical sets. Expansion is steepest in inverter architectures.
Fuel Type:
Supply security and price volatility shape procurement patterns differently across geographies with varying refinery access and import dependency.
- Diesel:Distillate fuel dominates African mining and heavy construction where energy density per liter determines logistics economics for remote site resupply.
- Gasoline:Spark-ignition configurations concentrate in Saudi residential and recreational segments where lower first-cost outweighs runtime efficiency for intermittent use.
- Propane:LPG conversions satisfy UAE emissions protocols while maintaining thermal efficiency for Dubai construction fleets facing air quality mandates.
- Biogas:Anaerobic digester gas capture remains nascent, limited to Ethiopian agricultural processing facilities with captive waste streams.
Volume concentrates in diesel deliveries. Procurement velocity is climbing fastest for propane retrofits.
Application:
Duty-cycle predictability separates capital planning for continuous industrial loads from emergency procurement triggered by grid failure events.
- Industrial Use:Continuous-duty ratings above 15 kW serve Saudi giga-project concrete batching plants where grid connection lags site activation by 12-18 months.
- Emergency Backup:Automatic transfer switch integration protects Nigerian commercial centers against distribution network instability.
- Commercial Use:Retail and hospitality installations in South Africa's Mpumalanga province prioritize rapid deployment over fuel efficiency.
- Residential Use:Sub-5 kW units serve compound backup needs in Saudi Arabia's Riyadh periphery where summer cooling loads strain municipal capacity.
Equipment stock concentrates in industrial standby configurations. Deployment rates are accelerating most sharply for emergency backup systems.
End User:
Customer sophistication spans from price-sensitive rental contractors to engineering-procurement-construction consortia with standardized fleet specifications.
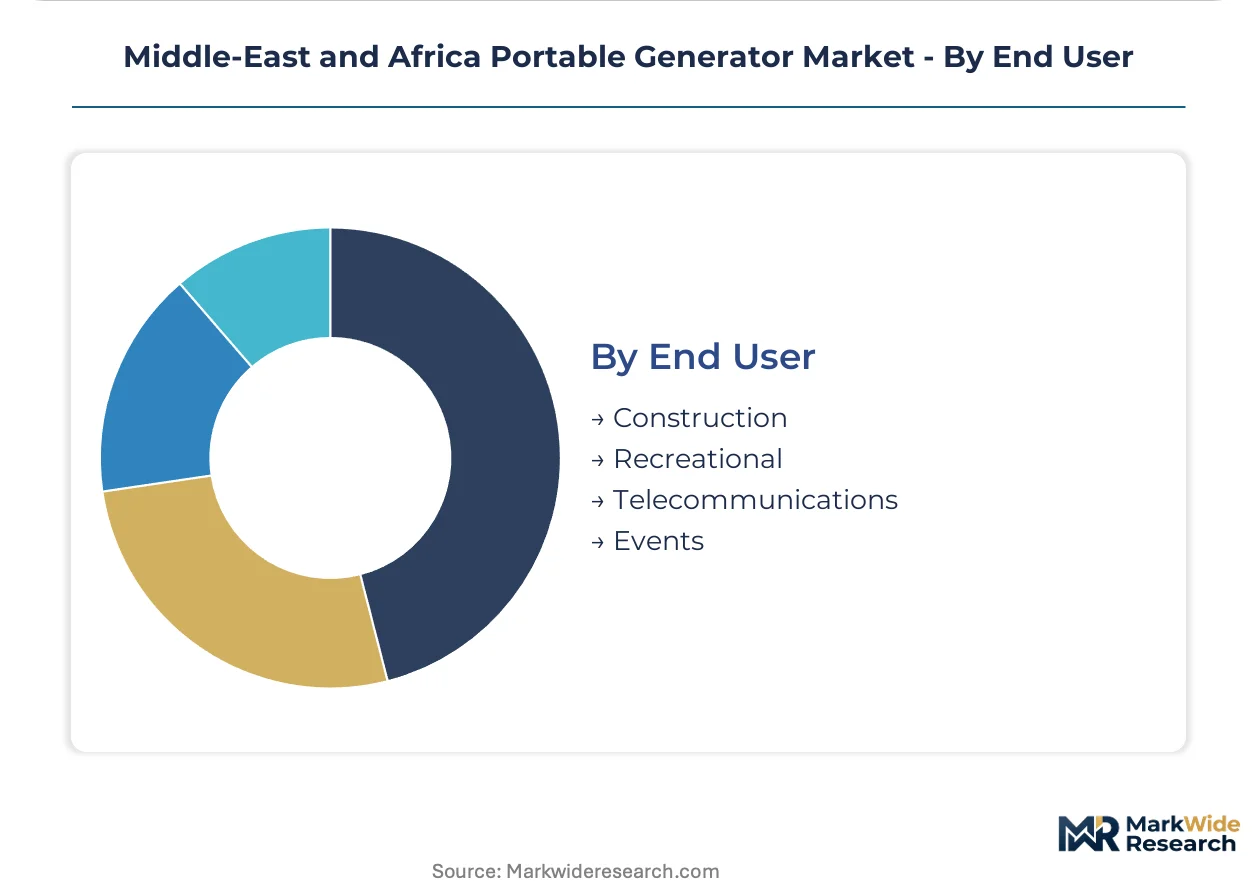
- Construction:General contractors across Saudi Arabia's Neom corridor specify mobile power redundancy in civil works contracts before grid energization.
- Telecommunications:MTN and Airtel Africa subsidiaries unbundle generator procurement from tower construction, enabling direct manufacturer relationships.
- Events:Temporary power rental houses serving Dubai exhibition centers prioritize rapid deployment and acoustic attenuation.
- Recreational:Camping and marine applications concentrate in South Africa's Western Cape leisure economy with seasonal demand spikes.
Construction channels absorb the largest equipment flows. Telecommunications procurement is scaling most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping portable generator assembly footprints across the Middle-East and Africa, as manufacturers relocate production to jurisdictions with streamlined certification timelines and lower compliance costs.
Saudi Arabia
Giga-project construction corridors around Neom and the Red Sea coast require mobile power redundancy where grid energization lags site activation by 12-18 months. The Saudi Food and Drug Authority enforces emissions certification protocols that extend product launch cycles for uncertified manufacturers. Riyadh-based distributors are expanding inventory buffers to serve contractor procurement spikes.
United Arab Emirates
Dubai and Abu Dhabi construction fleets face air quality mandates from the environmental regulator's tiered emissions standards. Selective catalytic reduction and diesel particulate filter requirements now apply to equipment above 19 kW rated output. Jebel Ali manufacturing zones are attracting regional assembly investment to bypass European supply dependencies.
South Africa
Mining operations in Mpumalanga and Limpopo provinces depend on portable diesel units for torque-stable auxiliary power at underground and remote processing facilities. The central energy regulator mandates safety testing protocols that shape product specifications for equipment entering the market. Cape Town service hubs concentrate inverter-generator electronic control module repair skills.
Nigeria
Commercial centers in Lagos and Abuja experience distribution network instability that forces automatic transfer switch integration into backup power procurement. The standards bureau maintains safety testing requirements that lack harmonized protocols with Gulf Cooperation Council regimes. Port Harcourt construction corridors absorb the largest rental fleet deployments.
Ethiopia
Telecom tower operators in Oromia and Amhara regions lack reliable backup power infrastructure for off-grid base stations. The national energy regulator is developing import standards for renewable-integrated power equipment. Addis Ababa procurement offices are unbundling generator sourcing from engineering-procurement-construction contracts.
Middle-East and Africa Portable Generator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solar-hybrid convergence and digital rental platforms. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with captive engine production, specialized power equipment manufacturers with regional distributor networks, and compact inverter technology specialists. Competitive intensity manifests through selective capacity expansion in UAE assembly zones and strategic partnerships between rental platforms and direct-to-contractor digital channels.
Among diversified industrial conglomerates, Atlas Copco AB and Caterpillar Inc. exemplify scale-driven positioning across African mining and infrastructure sectors. Generac Holdings Inc. represents the distributor-network archetype with Gulf Cooperation Council market presence. Yamaha Motor Co. Ltd occupies the compact technology specialist tier. These three anchors illustrate how geographic coverage, fuel-system flexibility, and control module sophistication separate competitive positions in procurement decisions.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Generac Holdings Inc. |
| Yamaha Motor Co. Ltd |
| Kohler Power Systems |
| Doosan Portable Power |
| Caterpillar Inc. |
| Cummins Inc. |
| Honda Middle East |
| Briggs & Stratton AG |
| Others |
Supply & Pricing Matrix
Photovoltaic-battery hybrid integration is compressing manufacturing cost curves while redrawing supplier geography across Middle Eastern assembly zones. Tiered emissions certification from UAE environmental regulators and Saudi SFDA protocols simultaneously gates market access and fragments pricing power across compliant and non-compliant equipment tiers.
Pricing Analysis
Distributor markups of 18-25% separate landed equipment costs from contractor-facing prices across Gulf Cooperation Council markets. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels reflects SFDA registration status and after-treatment system inclusion. Pricing pressure stems from Chinese engine-block import dependency compressing margins for regional assemblers serving Nigerian rental fleets. Construction contractors in Saudi giga-project corridors exhibit lowest price sensitivity due to mobilization timeline penalties, while South African mining procurement teams negotiate hardest on total cost of ownership.
Supply Chain Analysis
Certification documentation requirements from Saudi SFDA and UAE environmental regulators filter supplier pools before manufacturing economics determine winners. Chinese engine-block concentration for sub-10 kW powertrains, Indian alternator winding capacity, and Turkish after-treatment system assembly anchor upstream sourcing. Single-source vulnerability in electronic control module supply from East Asian foundries threatens inverter-generator production continuity. Distribution runs through Jebel Ali and Port Harcourt logistics hubs serving rental fleet operators and direct contractor procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through propane retrofit conversion kits and solar-hybrid premium tiers that capture UAE subsidy arbitrage. Component cost deflation in lithium-ion battery packs enables tier-climbing without proportional price erosion.
For Market Incumbents: Anchor Gulf Cooperation Council market position through captive certification investment that extends SFDA registration timelines for challengers. Deepen backward integration into after-treatment system production to capture tiered emissions retrofit demand from Dubai construction fleets. Solar-hybrid technology convergence threatens pure-diesel equipment margins; preemptive R&D allocation toward photovoltaic-diesel control architecture preserves pricing power. For New Entrants and Emerging Players: The premium-economy price-point gap in Ethiopian telecom tower backup power creates white-space entry opportunity. Target Oromia and Amhara region base stations with direct-to-operator digital procurement bypassing legacy distributor networks. Solar generator configurations with biogas backup capture agricultural processing captive fuel streams in Ethiopian highlands. For Investors and Strategic Acquirers: Roll-up economics work for regional distributor networks because certification fragmentation and aftermarket service obligations favor scaled compliance infrastructure. Five-to-ten year viability hinges on carbon-border mechanism expansion and local-content requirement enforcement across African mining jurisdictions. Acquisition target archetype: UAE-based assemblers with SFDA pre-certification and Jebel Ali logistics integration. Signal to watch: harmonization between Nigerian standards bureau protocols and Gulf Cooperation Council regimes eliminating duplicate compliance spend.| Strategic Initiative | Industry Significance |
|---|---|
| Propane Fuel-System Retrofit Certification | UAE environmental regulator tiered standards create 15-20% capital cost premium capture for compliant equipment. |
| Solar-Hybrid Generator Assembly Localization | Jebel Ali manufacturing zones bypass European supply dependencies while qualifying for renewable integration subsidies. |
| Direct-to-Contractor Digital Platform Launch | South African construction SMEs bypass traditional distributor markups through equipment rental platform aggregation. |
| Aftermarket Service Hub Expansion | Cape Town inverter-generator repair concentration addresses East African technician scarcity through regional fly-in support networks. |
| Ethiopian Telecom Tower Procurement Unbundling | Addis Ababa offices separating generator sourcing from EPC contracts enable direct manufacturer relationship establishment. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with secondary source validation. Equipment procurement directors at Saudi giga-project contractors, UAE-based distributor network heads, South African mining maintenance engineers, Nigerian rental fleet operators, and Ethiopian telecom infrastructure planners contributed operational perspective. Secondary sources included customs and trade flow databases, SFDA equipment registration filings, UAE environmental regulator emissions certification records, and power sector infrastructure development trackers. Bottom-up unit shipment modeling and top-down market sizing triangulated volume estimates across the projection horizon.
Segment-weighting approaches distributed total market value across fuel type, product architecture, application intensity, and end-user sophistication dimensions. CAGRs derived from logistic growth curve fitting to historical shipment trajectories, adjusted for regulatory inflection points and infrastructure investment announcements. Forecast inputs incorporated diesel price volatility scenarios, SFDA certification timeline distributions, and solar subsidy framework durability assumptions.
Caveats apply where diesel price spikes, Chinese engine-block export restrictions, or carbon-border mechanism implementation could materially shift the outlook. Forecasts reflect modeling assumptions around grid extension timelines and mining investment commitments. A model refresh is warranted upon material change in UAE tiered emissions enforcement intensity or Saudi local-content requirement expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
China Diesel Generator Market
Generators
Asia Pacific Electric Generators Market
Generators
Railway Generators Market
Generators
Saudi Arabia Diesel Generator Market
Generators
Europe Diesel Generator Market
Generators
Southeast Asia Portable Generator Market
Generators
North West Europe Diesel Generator Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Power Generator Rental Market
Generators
East Africa Diesel Generator Market
Generators
Global Portable Generator Market
Generators
Generator Sales Market
Generators
Nuclear Turbine Generators Market
Generators
Containerized Solar Generators Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Construction Prime Power Generators Market