
 South America Gas Generator Market | 2026-2036
South America Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
South America Gas Generator Market Analytics
Industrial energy buyers is bifurcating from commercial purchasers as the dominant procurement archetype across South America. Caterpillar Inc dominates heavy-duty stationary installations through its dealer network anchored in São Paulo and Santiago. Cummins Inc competes on modular power architecture for mining camps in Chile's Atacama region. General Electric Company leverages aeroderivative turbine technology for utility-scale distributed generation projects in Brazil.
Gas generators are internal combustion engine-driven or turbine-based electromechanical systems that convert natural gas, propane, or butane into electrical power through rotational energy, typically operating at 50 Hz or 60 Hz with thermal efficiencies ranging from 25% to 45% depending on engine class and cogeneration configuration. These systems provide prime, continuous, or standby power for facilities lacking grid reliability or operating beyond transmission infrastructure. Stationary generators occupy the dominant revenue position due to permanent industrial installations requiring sustained megawatt output. Mobile generators represent the fastest-expanding category as rental fleets serve construction and emergency response applications across Brazil and Argentina. Natural gas fuel types command the deepest margin pools where pipeline infrastructure exists, while propane segments capture premium pricing in remote Andean operations.
Brazil's ANP and INMETRO shape fuel quality standards and emissions certification for grid-interconnected gas generator installations. Argentina's Secretariat of Energy enforces dispatch regulations that influence backup power system sizing for critical infrastructure. Chile's Ministry of Energy promotes LNG-to-power frameworks that expand gas generator viability in mining regions previously dependent on diesel. Stakeholders must monitor regulatory divergence across Mercosur member states when configuring product portfolios and service networks.
Market Dynamics
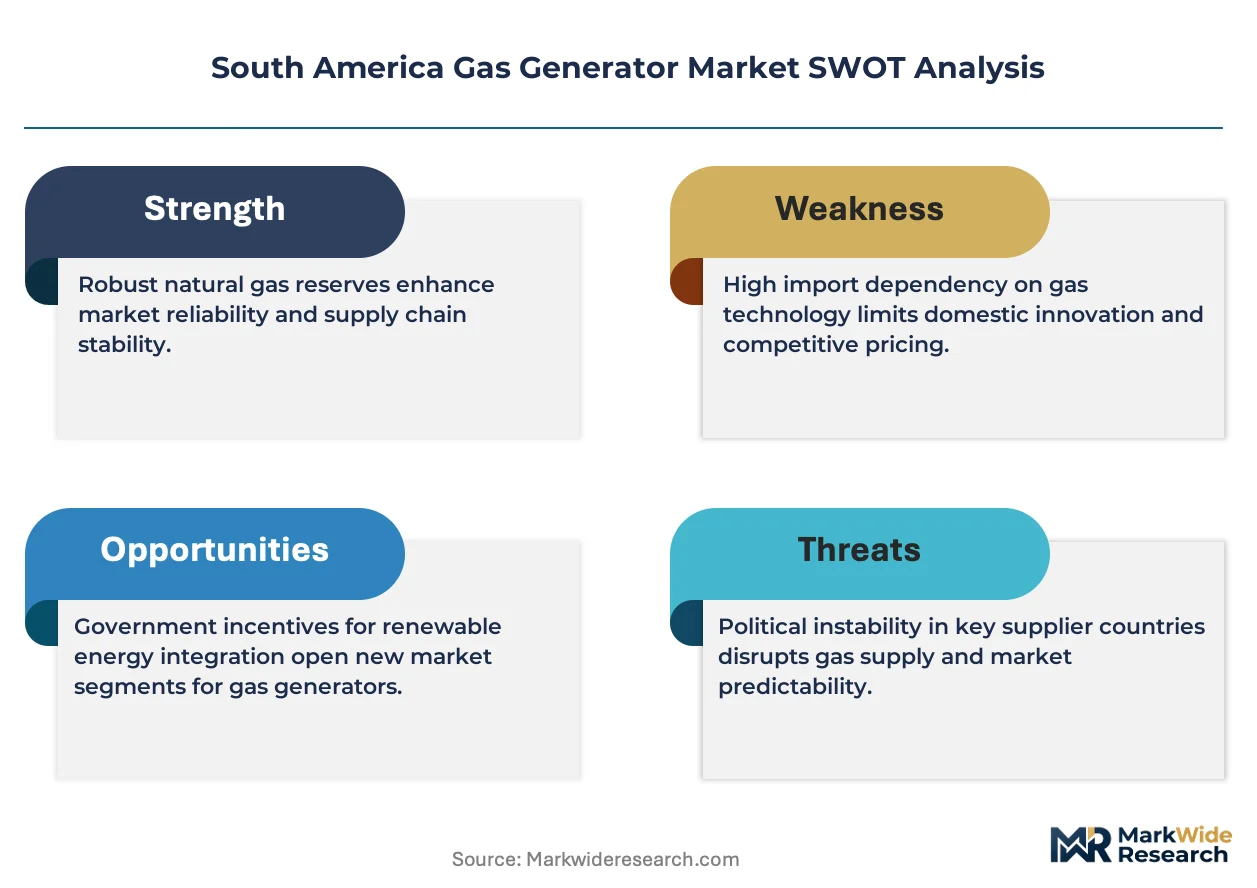
Mining electrification in Chile's Atacama and Peru's Andean corridors is pulling gas generator deployment patterns away from Brazil's industrial heartland, fragmenting procurement concentration across three distinct fuel infrastructure regimes.
Growth Catalysts
- ANP Pipeline Liberalization:Brazil's hydrocarbon regulator has opened natural gas distribution networks to third-party access, enabling stationary generators to tap pipeline supply previously reserved for utility-scale consumers.
- LNG-to-Power Frameworks:Chile's Ministry of Energy has established import terminal connectivity standards that allow mining operators to substitute diesel with regasified LNG for remote power generation.
- Cogeneration Retrofits:São Paulo's industrial parks are installing combined heat and power configurations that recover waste thermal energy from gas generator exhaust streams.
Market Restraints
- Pipeline Infrastructure Asymmetry:Argentina's domestic gas transmission network suffers from chronic underinvestment, forcing generators in Córdoba and Mendoza to rely on costlier compressed natural gas trucked from Vaca Muerta.
- Import Duty Cascades:Mercosur's common external tariff structure imposes layered levies on turbocharger and control system components sourced outside the customs union.
- Diesel Lock-In:Remote Andean mining camps retain sunk capital in liquid fuel storage and handling systems that resist conversion to gas generator architectures.
Strategic Opportunities
- Mobile Rental Fleets:Argentina's construction sector recovery is creating demand for trailer-mounted gas generator units that bypass permanent installation permitting timelines.
- Hybrid Microgrids:Solar PV and battery storage convergence with gas generator prime power is opening off-grid configurations for Colombia's Caribbean coastal tourism developments.
- Carbon Border Adjustments:The EU's impending CBAM on embedded emissions in imported minerals is incentivizing Chilean copper producers to document gas generator emissions against diesel baselines.
Industry Challenges
- Specialized Technician Scarcity:Brazil's INMETRO certification requirements for gas turbine maintenance exceed the supply of trained field engineers in the northern Amazon states.
- Fuel Quality Variance:Pipeline natural gas calorific value fluctuations across Peru's southern distribution network force generator operators to recalibrate combustion controls weekly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Gas Generator Market |
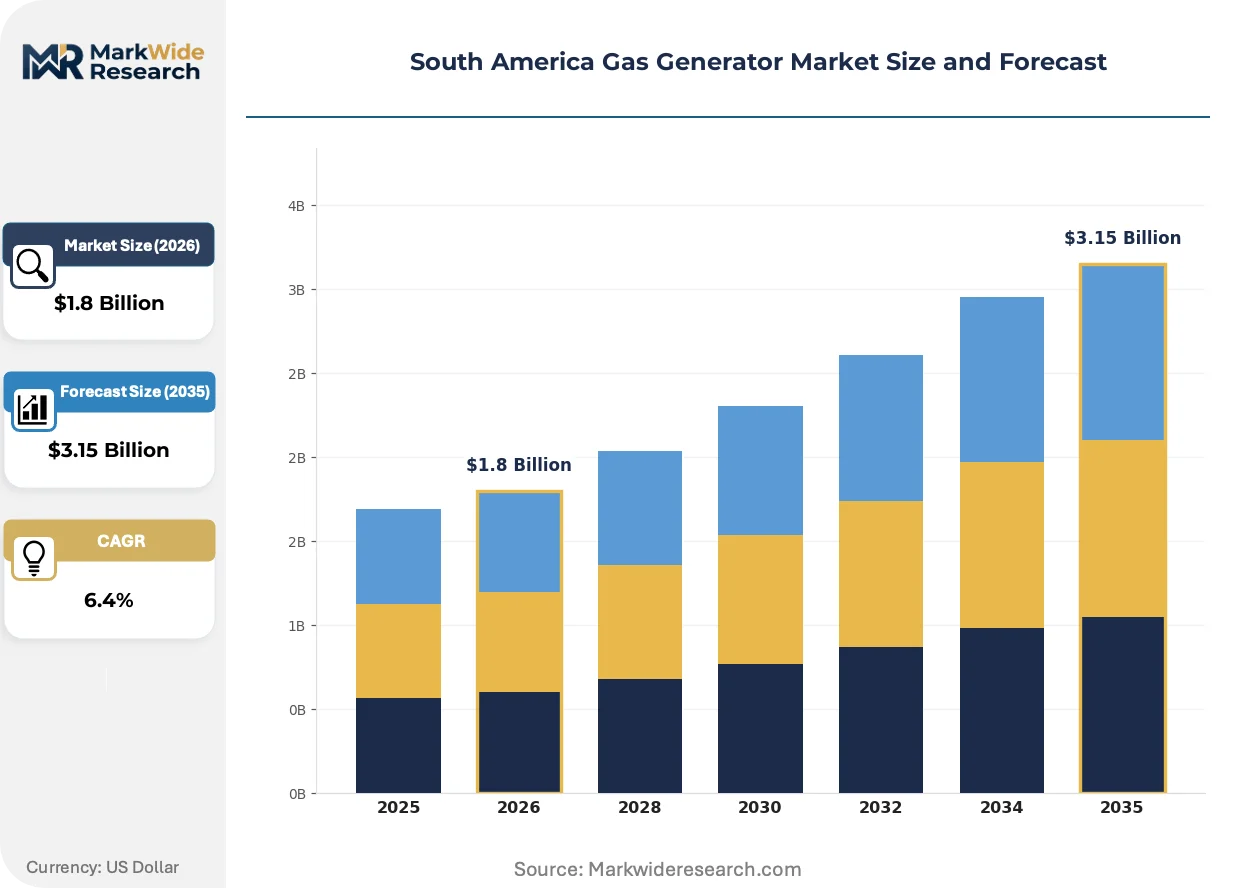
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Generators, Stationary Generators, Hybrid Generators, Portable Generators Power Rating: 10-50 kW, 51-100 kW, 101-250 kW, 251-500 kW End User: Commercial, Industrial, Residential, Construction Fuel Type: Natural Gas, Propane, Butane, Others |
| Companies Covered | Caterpillar Inc, Cummins Inc, Kohler Co, Generac Power Systems, General Electric Company, Yanmar Co, MTU Onsite Energy, Wärtsilä, Atlas Copco, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Gas Generator Market Evolving Landscape
Digital control architectures and modular power electronics are compressing generator set footprints while expanding operational flexibility for intermittent renewable integration across South American industrial sites.
Containerized turbine packages are miniaturizing aeroderivative gas generator systems previously restricted to permanent utility installations. Mining operators in Chile's Escondida district are deploying these skid-mounted units for rapid relocation between extraction phases. The technology is miniaturizing capital deployment timelines from 18-month civil works cycles to 90-day commissioning windows.
Chile's Ministry of Energy has mandated emissions monitoring telemetry for all grid-interconnected generators above 10 MW capacity. This regulation forces operators to install continuous exhaust gas analyzers linked to regional grid dispatch centers. Heavy industrial facilities in the Valparaíso region are responding by retrofitting selective catalytic reduction systems to existing engine fleets.
Rental power providers are unbundling long-term service contracts from equipment lease agreements. Brazilian construction conglomerates in Minas Gerais now source generator capacity from fleet operators while retaining independent maintenance vendors. This pattern is most visible in São Paulo's infrastructure project pipeline, where contractors optimize cash flow by separating capital and operating expenditures.
South America Gas Generator Market Segmentation
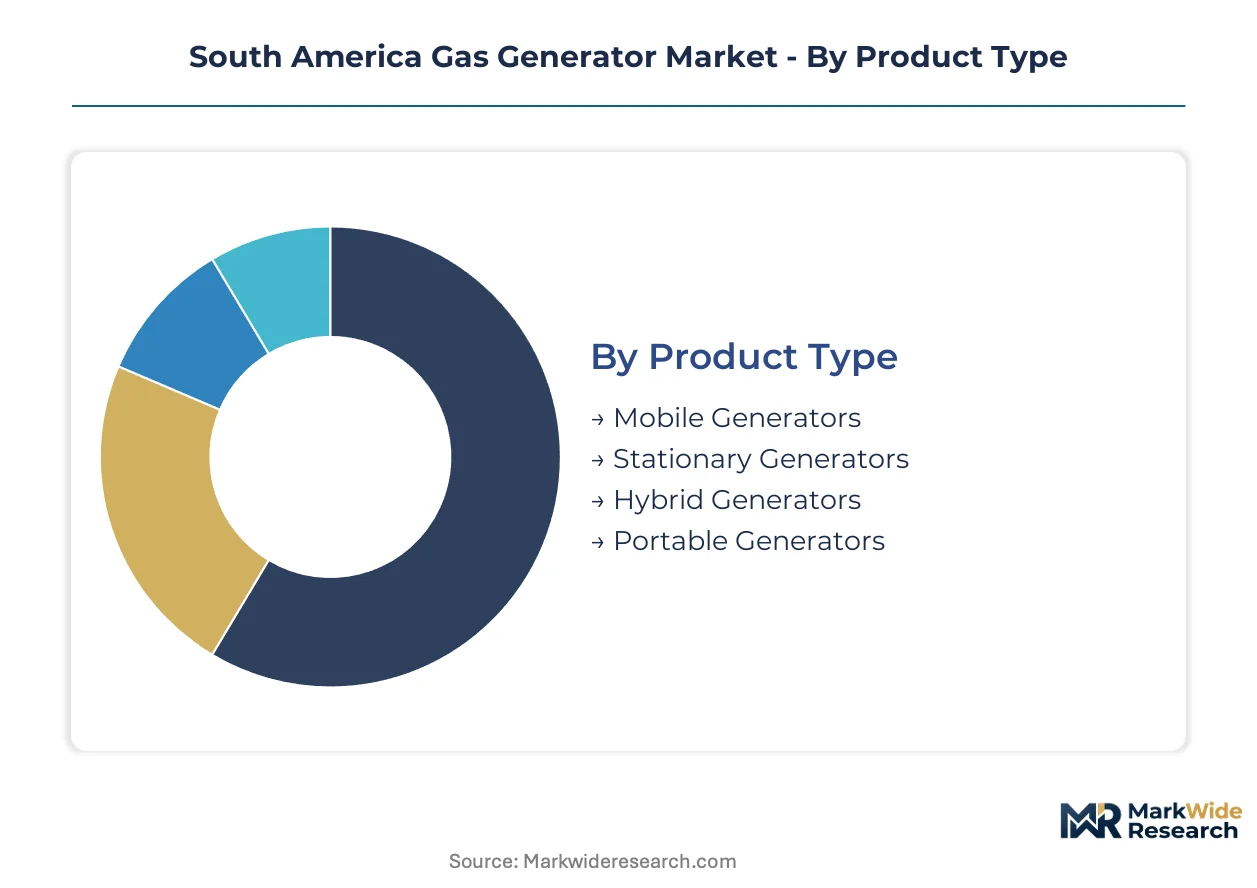
Segmentation in South America's gas generator market reflects divergent fuel infrastructure maturity and regulatory regimes across Brazil, Chile, and Peru. Procurement patterns fragment sharply between pipeline-connected industrial corridors and remote mining regions dependent on LNG or propane logistics.
Product Type:
ANP regulations in Brazil and Chile's Ministry of Energy emissions standards create divergent certification burdens for fixed versus mobile installations.
- Stationary Generators:Permanent electromechanical systems anchored to concrete foundations with continuous-duty prime power ratings. São Paulo's industrial parks and Minas Gerais manufacturing clusters concentrate procurement where pipeline natural gas enables baseload operation without fuel logistics constraints.
- Mobile Generators:Trailer-mounted or skid-mounted units designed for rapid deployment and relocation between sites. Argentina's construction recovery and Brazil's infrastructure project pipeline are pulling rental fleet expansion, bypassing permanent installation permitting timelines that stretch 12-18 months in coastal regulatory zones.
- Hybrid Generators:Integrated gas generator and battery storage architectures enabling load-following and renewable firming. Colombia's Caribbean tourism developments and Chilean mining microgrids are piloting configurations that reduce fuel consumption during low-load periods.
- Portable Generators:Compact units below 10 kW typically deployed for emergency residential backup or small commercial applications. Urban centers in southern Brazil and Argentina's Mendoza province show concentrated demand for grid-failure contingency.
Stationary generators handle the majority of throughput; mobile generators are gaining share fastest as rental models penetrate construction and emergency response verticals.
Power Rating:
Cost tier differentiation separates premium high-capacity installations from mid-range industrial workhorses.
- 251-500 kW:Heavy-duty engine-generator sets serving continuous industrial loads and utility-scale distributed generation. Brazil's southeastern manufacturing corridor and Chilean copper concentrators specify these units for baseload power where pipeline or LNG infrastructure supports sustained operation.
- 101-250 kW:Mid-range systems dominating commercial and light industrial applications. Peru's Andean mining camps and Argentina's agro-industrial processing facilities cluster procurement here, balancing capital efficiency against fuel logistics complexity in regions lacking pipeline access.
- 51-100 kW:Compact units serving small commercial facilities and remote construction sites. Brazilian rental fleets in Minas Gerais and São Paulo infrastructure projects favor this bracket for modular capacity scaling.
- 10-50 kW:Entry-level systems for residential backup and small commercial standby. Urban centers across southern Brazil and Argentina's Córdoba region show demand concentration where grid reliability concerns drive contingency investment.
The 101-250 kW bracket anchors volume shipments; 251-500 kW systems show the steepest expansion trajectory as mining electrification scales.
End User:
Application-driven procurement separates continuous-duty industrial buyers from intermittent commercial and residential purchasers.
- Industrial:Manufacturing, mining, and processing facilities requiring prime or continuous power for production continuity. Chile's Atacama copper belt and Brazil's southeastern industrial corridor dominate demand, with ANP pipeline access in Brazil and LNG-to-power frameworks in Chile enabling fuel switching from diesel.
- Commercial:Retail, hospitality, and office facilities seeking standby power for revenue protection. São Paulo's commercial real estate and Colombia's Caribbean tourism developments concentrate procurement where grid instability threatens operational continuity.
- Construction:Temporary power for infrastructure projects, extraction sites, and urban development. Argentina's post-stabilization recovery and Brazil's federal infrastructure pipeline are accelerating rental fleet deployment for road, bridge, and housing construction.
- Residential:Single-family and multi-unit backup systems for grid-failure contingency. Affluent neighborhoods in São Paulo, Santiago, and Buenos Aires show demand concentration where income levels support premium standby installations.
Industrial end users command the dominant revenue position; construction applications are expanding most quickly as rental models proliferate.
Fuel Type:
Geography determines fuel viability, with pipeline density, LNG terminal proximity, and trucking logistics creating distinct supply economics.
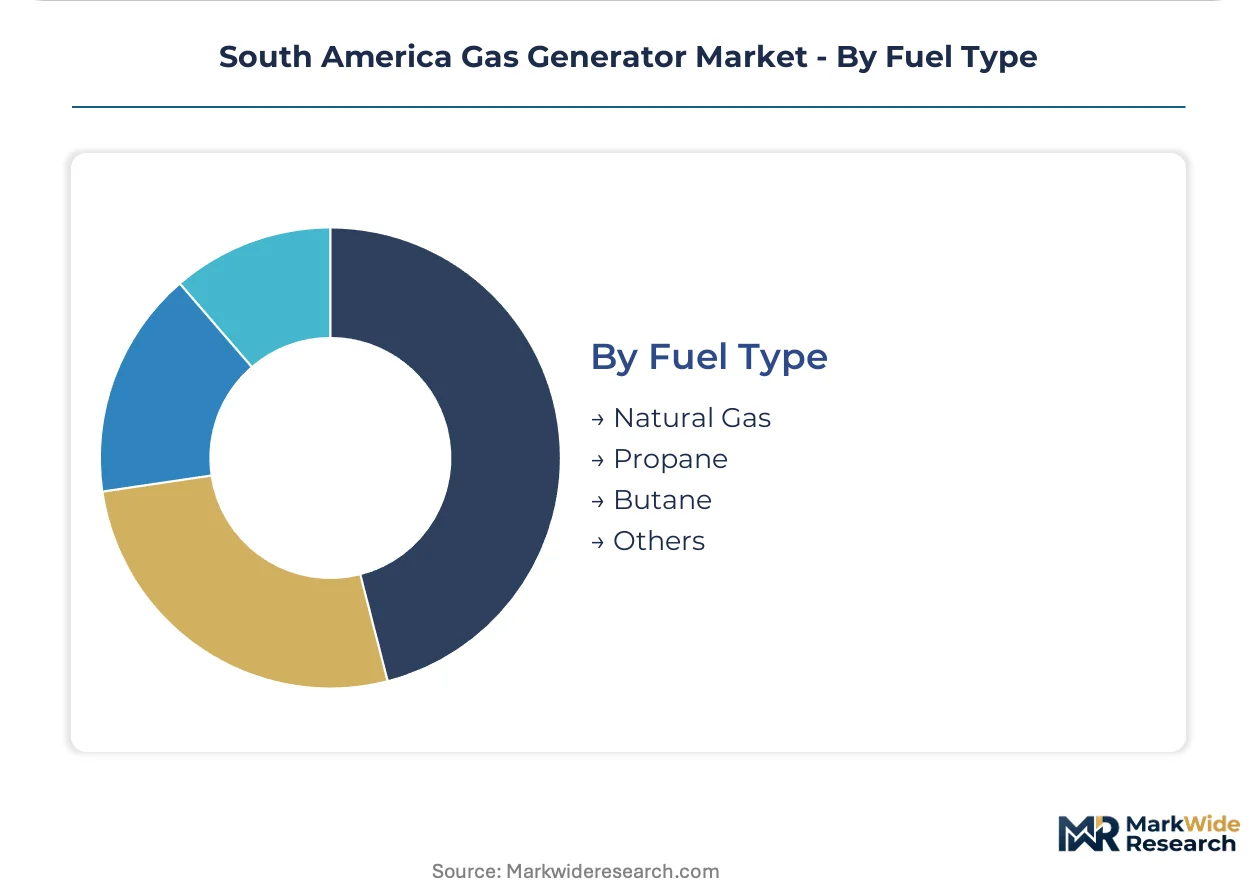
- Natural Gas:Pipeline-delivered methane dominating where distribution infrastructure exists. Brazil's ANP third-party access regulations and Chile's LNG import terminal connectivity standards are expanding addressable market for grid-interconnected and remote power applications previously restricted to diesel.
- Propane:Liquefied petroleum gas stored on-site in bulk tanks, essential for regions beyond pipeline reach. Peru's southern Andean mining corridors and Argentina's Mendoza province rely on trucked propane where domestic gas transmission suffers chronic underinvestment.
- Butane:Higher-vapor-pressure LPG variant common in warmer climates and specific industrial processes. Coastal Brazilian facilities and select Chilean processing applications specify butane where storage temperature conditions favor its handling characteristics.
- Others:Biogas, landfill gas, and synthetic methane emerging in pilot configurations. São Paulo's industrial parks are testing biogas integration from agricultural waste streams under INMETRO emissions certification frameworks.
Natural gas handles the majority of throughput; propane is climbing the fastest as mining electrification extends into pipeline-deficient Andean territories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean copper concentrate flows to Chinese smelters are electrifying mining camps across the Atacama Desert, pulling gas generator deployment northward from Brazil's traditional industrial stronghold. Pipeline infrastructure asymmetries between Pacific and Atlantic basins are fragmenting fuel logistics across five national markets.
Brazil
ANP third-party access regulations have opened natural gas distribution networks to stationary generator operators previously excluded from pipeline supply. INMETRO emissions certification frameworks govern grid-interconnected installations above 10 MW capacity. São Paulo's southeastern industrial corridor and Minas Gerais manufacturing clusters anchor procurement concentration where pipeline density enables baseload operation without fuel logistics constraints.
Chile
LNG-to-power frameworks from the Ministry of Energy are enabling mining operators to substitute diesel with regasified natural gas at remote extraction sites. Emissions monitoring telemetry mandates apply to all grid-connected generators above 10 MW, forcing continuous exhaust gas analyzer installation. The Atacama copper belt and Escondida district concentrate demand where containerized turbine packages compress commissioning timelines from 18 months to 90 days.
Peru
Andean mining electrification is extending gas generator viability into pipeline-deficient southern territories previously dependent on liquid fuels. Fuel quality variance across the southern distribution network forces weekly combustion control recalibration. The southern Andean mining corridors rely on trucked propane where domestic gas transmission infrastructure remains underdeveloped.
Argentina
Vaca Muerta shale production is expanding domestic gas supply but transmission underinvestment forces Córdoba and Mendoza generators to rely on costlier compressed natural gas trucking. The Secretariat of Energy enforces dispatch regulations influencing backup power system sizing for critical infrastructure. Construction sector recovery in Buenos Aires and infrastructure projects across the federal pipeline are accelerating mobile rental fleet deployment.
Colombia
Caribbean coastal tourism developments are piloting hybrid microgrid configurations combining solar PV, battery storage, and gas generator prime power. Grid instability in coastal zones drives commercial standby procurement where revenue protection justifies premium installations. Cartagena and Barranquilla hospitality clusters concentrate demand for load-following architectures that reduce fuel consumption during low-load periods.
South America Gas Generator Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with energy equipment divisions rather than pure-play generator specialists. Market structure exhibits moderate consolidation around heavy-engineering groups with established South American dealer networks. Three archetypes dominate: full-service power solution providers with integrated maintenance capabilities, modular architecture specialists serving mining camp mobility requirements, and aeroderivative turbine packagers targeting utility-scale distributed generation. Competitive moves center on rental fleet expansion and cogeneration retrofit service bundling.
Among US-based industrial equipment manufacturers, Caterpillar Inc and Cummins Inc exemplify contrasting strategic positions within the regional market. Caterpillar anchors the full-service archetype through its São Paulo and Santiago dealer infrastructure, while Cummins occupies the modular architecture tier for rapid-deployment mining applications. General Electric Company represents the aeroderivative turbine packager segment with utility-scale distributed generation positioning. These three entities collectively illustrate how technology specialization and geographic channel density determine competitive positioning across Brazil's industrial corridor and Chile's mining regions.
| Leading Market Players |
|---|
| Caterpillar Inc |
| Cummins Inc |
| Kohler Co |
| Generac Power Systems |
| General Electric Company |
| Yanmar Co |
| MTU Onsite Energy |
| Wärtsilä |
| Atlas Copco |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with take-or-pay provisions anchor gas generator procurement across Brazil's ANP-regulated pipeline zones, locking in fuel access and insulating industrial buyers from spot volatility while compressing margin visibility for rental fleet operators exposed to diesel-to-gas arbitrage.
Pricing Analysis
Reciprocating engine-generator pricing gaps widen substantially against aeroderivative turbine alternatives, with the latter commanding premiums driven by INMETRO emissions certification tiers and modular redeployment flexibility for Chilean mining camps. Three-tier pricing structure across premium, standard, and economy levels separates Caterpillar's full-service bundled offerings from Cummins' modular architectures and regional assembler economy units. Pricing pressure stems from Mercosur import duty cascades on turbocharger and control system components, forcing cost compression in mid-range 101-250 kW brackets. Construction rental buyers exhibit highest price sensitivity due to unbundled service contracts, while copper concentrators in Atacama show lowest sensitivity given diesel displacement economics.
Supply Chain Analysis
Inventory lead times for heavy-duty engine blocks and aeroderivative turbine packages stretch 16-24 weeks from US and European manufacturing hubs, compressing to 8-12 weeks for skid-mounted modular units sourced from Brazilian assembly plants. Supply concentration centers on Germany, the United States, and China for turbocharger assemblies, power electronics, and emissions control catalysts. Raw material dependencies include nickel-based superalloys for turbine blades, rare earth elements for permanent magnet alternators, and platinum-group metals for catalytic reduction systems. Single-source vulnerability runs through specialized combustion control firmware licensed from European engineering groups. Distribution runs through Caterpillar and Cummins dealer networks anchored in São Paulo and Santiago, with secondary channels serving Peru and Argentina via Lima and Buenos Aires logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified gas turbine maintenance engineers number fewer than 400 across Brazil's northern Amazon states, creating a binding constraint on fleet expansion and service response times that rewards preemptive capability investment.
For Market Incumbents: Consolidate dealer network density in São Paulo and Minas Gerais to defend against emerging Chinese manufacturers penetrating through Argentine construction recovery channels. Prioritize backward integration into aftermarket parts warehousing to compress service response times below 48 hours for mining camp clients. INMETRO certification requirements for grid-interconnected units above 10 MW represent a defendable moat against unqualified entrants. For New Entrants and Emerging Players: ANP fast-track certification for third-party pipeline access creates regulatory entry velocity for modular gas generator specialists targeting Brazil's rental fleet gap. White-space concentrates in hybrid microgrid configurations for Colombia's Caribbean tourism developments and containerized turbine packages for Chilean mining mobility requirements. Go-to-market positioning should emphasize 90-day commissioning windows against 18-month civil works cycles for permanent installations. For Investors and Strategic Acquirers: Capital is best deployed toward rental fleet operators with established INMETRO service certification and LNG logistics partnerships across Chile's Atacama corridor. Long-term viability hinges on exposure to mining electrification tailwinds rather than Brazilian industrial cyclicality. Monitor ANP regulatory enforcement consistency as the inflection signal—accelerated third-party access expansion would re-rate pipeline-connected stationary generator assets.| Strategic Initiative | Industry Significance |
|---|---|
| Cogeneration Retrofit Service Bundling | São Paulo industrial parks recover waste thermal energy under INMETRO efficiency standards. |
| LNG Logistics Partnership Formation | Chilean mining operators substitute diesel with regasified supply from Ministry of Energy terminals. |
| Mobile Rental Fleet Expansion | Argentina's construction recovery bypasses 12-18 month permanent installation permitting timelines. |
| Hybrid Microgrid Pilot Deployment | Colombia's Caribbean tourism developments integrate solar PV and battery storage with gas prime power. |
| Emissions Telemetry Compliance Investment | Chilean grid-connected generators above 10 MW install continuous exhaust analyzers per Ministry mandates. |
Research Methodology
Initial hypotheses were tested against primary input from gas generator fleet operators, mining camp energy managers, ANP regulatory affairs officers, and EPC contractors active in distributed generation projects, then refined through secondary validation against Brazilian customs records, Chilean Ministry of Energy LNG import statistics, SEC filings from Caterpillar and Cummins, and INMETRO certification databases. Bottom-up unit shipment estimates by power rating and fuel type were triangulated against top-down market value reconstruction from disclosed contract values and rental fleet utilization rates.
Variance decomposition across the projection horizon isolates volume drivers (mining electrification capex cycles, ANP pipeline access expansion velocity) from price drivers (fuel cost differentials, import duty pass-through, service unbundling trends). Segmentation dimensions modeled include product mobility class, power rating tier, end-use application, fuel infrastructure dependency, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical penetration rates, with terminal growth assumptions anchored to copper production forecasts and Brazilian manufacturing capacity utilization.
Decision-makers should treat outputs as directional under stable ANP third-party access enforcement and Chilean LNG terminal connectivity expansion; material deviation in either would warrant model refresh. Specific risks include Mercosur tariff renegotiation, Vaca Muerta transmission investment delays, and EU carbon border adjustment implementation timing for Chilean copper exports. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Electric Generators Market
Generators
United States Portable Generator Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Generator Sales Market
Generators
Europe Gas Generator Market
Generators
Telecom Generator Market
Generators
Gasoline Generator Market
Generators
Construction Prime Power Generators Market
Generators
Turbo Generator Market
Generators
Residential Gas Generator Market
Generators
North America Gas Generator Market
Generators
Commercial Generator Market
Generators
India Diesel Generator Market
Generators
Portugal Gas Generator Market
Generators
North America Diesel Generator Market
Generators
South Africa Diesel Generator Market