
 Bluetooth Smart and Smart Ready Market | 2026-2036
Bluetooth Smart and Smart Ready Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth Smart and Smart Ready Market Intelligence
The EU Green Deal's right-to-repair mandates is shifting procurement criteria across European healthcare and industrial sectors toward modular, upgradeable Bluetooth-enabled devices. Nordic Semiconductor leverages its integrated protocol stack to dominate ultra-low-power designs for medical wearables. Texas Instruments Incorporated anchors industrial automation through its Bluetooth 5.2 SoC portfolio with integrated power management. Qualcomm Incorporated competes on brand strength and channel control, extending its Snapdragon platform into premium smartwatch segments.
Bluetooth Smart and Smart Ready encompasses low-energy wireless communication systems operating in the 2.4 GHz ISM band with power consumption below 15 mA in active transmit mode, designed primarily for intermittent data exchange between battery-operated devices and central hubs. Bluetooth 5.2 technology leads on throughput and direction-finding precision, concentrating margin pools in audio streaming and indoor positioning applications. Smart Home Devices represents the fastest-growing product category as interoperability standards consolidate around Matter protocol integration. Fitness Tracking applications sustain volume leadership through consumer electronics channel saturation, though Industrial Automation commands premium pricing per node deployed.
The EU AI Act and REACH chemical compliance frameworks shape hardware design rules for devices entering European healthcare and consumer markets, mandating material traceability and algorithmic transparency in connected diagnostics. The FCC in the United States enforces spectrum allocation and emission limits that determine antenna design and certification timelines for Bluetooth 5.x products. Stakeholders must monitor evolving interoperability mandates from the Bluetooth SIG alongside national cybersecurity labeling schemes that will determine market access thresholds for next-generation connected devices.
Market Dynamics
The Bluetooth Smart and Smart Ready market is experiencing structural pressure from interoperability mandates and power-efficiency thresholds that favor integrated protocol stacks over discrete component architectures. Matter protocol consolidation and EU right-to-repair requirements are reshaping procurement specifications across healthcare and industrial verticals.
Growth Catalysts
- EU Green Deal right-to-repair mandates:Procurement criteria in German industrial automation now prioritize modular, upgradeable Bluetooth 5.x devices with field-replaceable subsystems.
- Wearable health monitors:Healthcare providers in the United States are integrating continuous patient monitoring systems that rely on ultra-low-power Bluetooth LE connectivity.
- Bavaria and Baden-Württemberg industrial clusters:Enterprise-grade Bluetooth 5.x deployments in these German regions are driving demand for direction-finding precision and enhanced throughput.
Market Restraints
- Silicon supply concentration:Advanced Bluetooth 5.2 SoC fabrication depends on concentrated foundry capacity in Taiwan, creating vulnerability to geographic disruption.
- REACH chemical compliance:Material traceability requirements for substances of very high concern extend hardware design cycles and certification timelines for European market entry.
- Wi-Fi 6/6E substitution:Higher-bandwidth indoor positioning and audio streaming applications are migrating to Wi-Fi alternatives where power constraints permit.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives are attracting Bluetooth module assembly and testing operations to domestic facilities serving South Asian markets.
- Ambient IoT convergence:Bluetooth Low Energy is integrating with energy-harvesting photovoltaic and RF power systems to eliminate battery dependence in smart home sensors.
- FCC spectrum efficiency mandates:New emission limits and antenna design rules are creating first-mover advantage for vendors with pre-certified, integrated RF front-end solutions.
Industry Challenges
- RF engineering talent scarcity:Design of 2.4 GHz antenna systems with coexistence filtering requires specialized expertise that outpaces university program output.
- Bluetooth SIG certification backlog:Interoperability testing queue delays are compressing product launch windows for seasonal consumer electronics cycles.
- Legacy industrial protocol integration:Brownfield automation deployments require gateway architectures that bridge Bluetooth 5.x with PROFIBUS and Modbus fieldbus systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth Smart and Smart Ready Market |
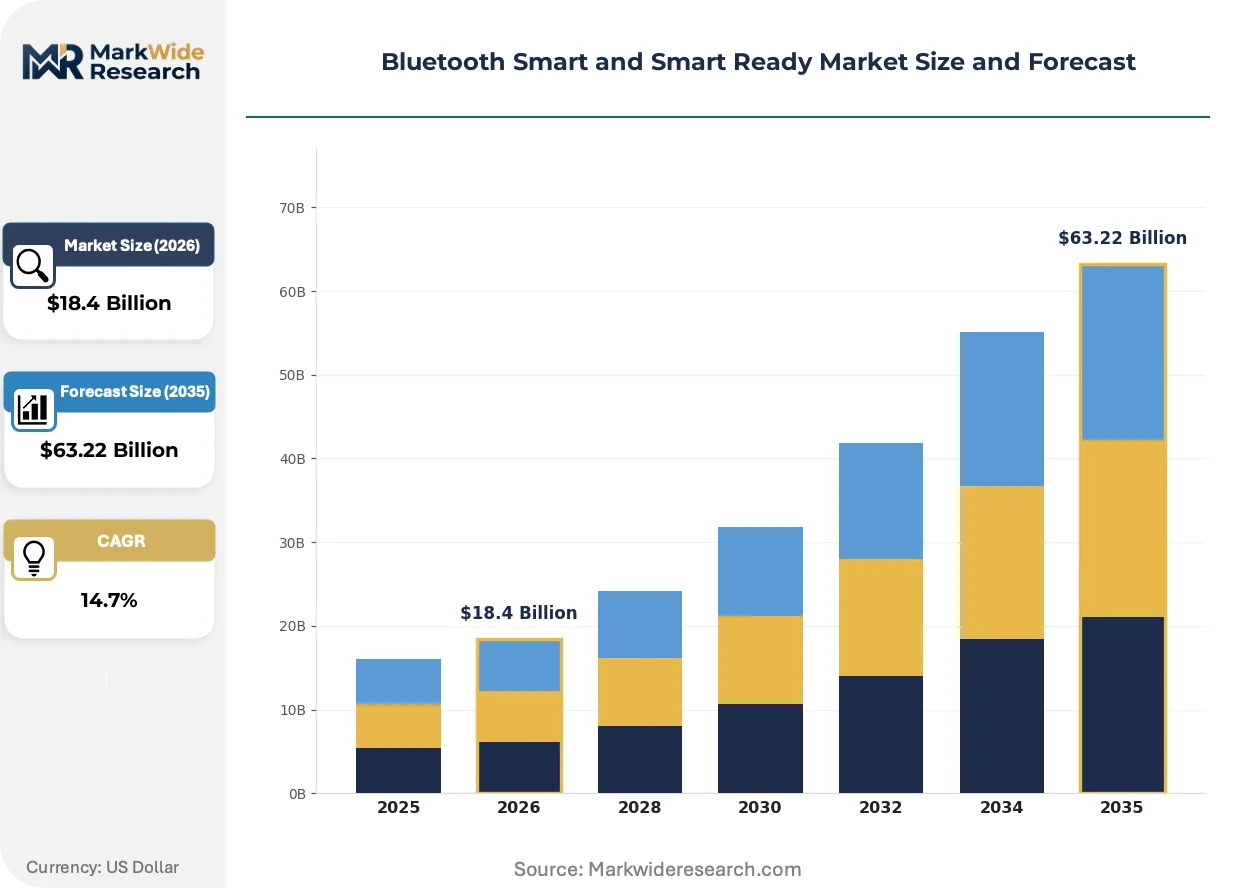
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $63.22 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Smart Watches, Smart Home Devices, Smart Accessories, Smart Beacons, Smart Tags Technology: Bluetooth 4.0, Bluetooth 4.1, Bluetooth 4.2, Bluetooth 5.0, Bluetooth 5.1, Bluetooth 5.2 Application: Fitness Tracking, Asset Management, Smart Lighting, Industrial Automation, Personal Healthcare, Smart Agriculture End User: Consumer Electronics, Healthcare Providers, Manufacturing Plants, Logistics Companies, Agriculture Firms, Fitness Centers |
| Companies Covered | Qualcomm Incorporated, Nordic Semiconductor, Texas Instruments Incorporated, Broadcom Inc., STMicroelectronics, NXP Semiconductors N.V., Microchip Technology Inc., Silicon Labs, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth Smart and Smart Ready Market Strategic Shifts & Innovations
Bluetooth technology is undergoing functional expansion beyond audio and data pipes into precise spatial awareness and ambient power domains. Three concurrent developments are redefining competitive positioning and value capture mechanisms.
Direction-finding using angle-of-arrival and angle-of-departure techniques is integrating into industrial asset tracking and indoor navigation systems. Warehouse operators in Germany are deploying Bluetooth 5.1 and 5.2 infrastructure to achieve sub-meter location precision for automated guided vehicles. This capability is integrating real-time location services into enterprise resource planning systems, compressing implementation timelines for smart factory transformations.
The EU AI Act's risk classification framework is mandating algorithmic transparency for connected diagnostic devices using Bluetooth data transmission. Hardware manufacturers must now document machine-learning inference pathways and data provenance to achieve CE marking under the Medical Device Regulation. European healthcare procurement is responding by requiring compliance documentation as a mandatory bid evaluation criterion, favoring vendors with pre-established regulatory dossiers.
Healthcare systems are unbundling device procurement from continuous monitoring service contracts. German hospital networks are negotiating direct relationships with remote patient monitoring platform operators, bypassing traditional medical device distributors. This disintermediation is most visible in cardiology and diabetes management verticals, where recurring revenue models are displacing capital equipment sales cycles.
Bluetooth Smart and Smart Ready Market Segmentation
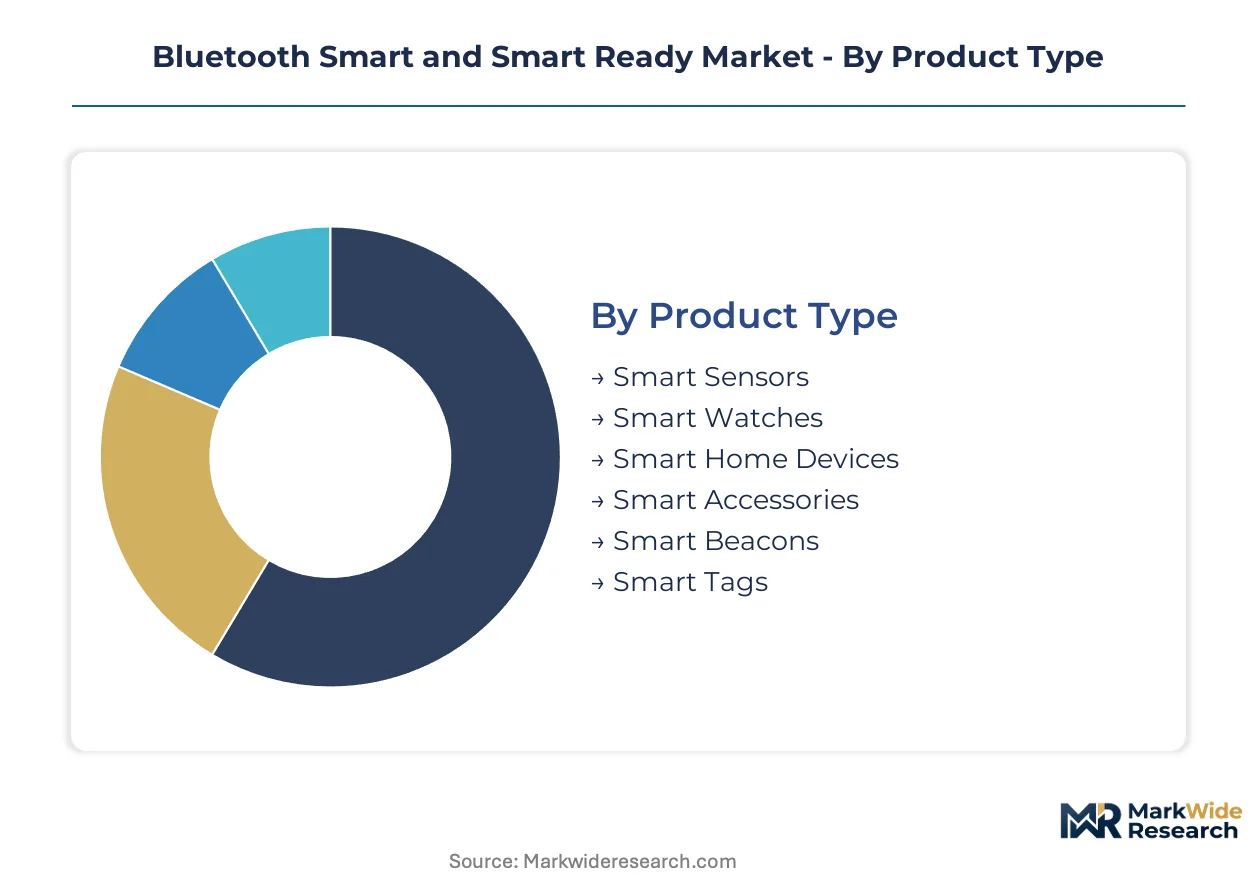
Segmentation in Bluetooth Smart and Smart Ready markets reveals divergent margin structures across power-performance tradeoffs and vertical compliance burdens. Procurement committees weigh protocol version longevity against field-upgradeability mandates that vary sharply by end-use jurisdiction.
Product Type:
Buyer decisions pivot on battery lifecycle economics and subsystem modularity under emerging repairability regulations.
- Smart Sensors:Compact transducers with sub-10mA active draw enable decade-long deployment in agricultural soil monitoring and industrial vibration analysis. German manufacturing plants in Bavaria specify IP67-rated variants with field-replaceable power modules to satisfy EU Green Deal procurement criteria.
- Smart Home Devices:Matter protocol integration drives interoperability certification costs upward, compressing margins for standalone gateway manufacturers while rewarding ecosystem-integrated suppliers. Demand concentrates in North American retrofit installations where Wi-Fi backhaul congestion pushes low-latency Bluetooth mesh adoption.
- Smart Watches:Premium tier devices integrate multi-protocol stacks with FDA-cleared biometric algorithms.
- Smart Accessories:Audio peripherals and input devices prioritize codec efficiency over location services.
- Smart Beacons:Retail and warehousing deployments leverage direction-finding for sub-meter asset positioning.
- Smart Tags:Ultra-low-power designs target luggage and equipment tracking with multi-year coin cell operation.
Volume sits with Smart Sensors; growth tilts toward Smart Home Devices.
Technology:
Protocol version selection determines antenna complexity, certification queue position, and coexistence filtering requirements.
- Bluetooth 5.2:Isochronous channels and power control enhance audio streaming reliability while LE Power Control mitigates interference in dense industrial deployments. Texas Instruments and Nordic Semiconductor anchor design wins in German automation clusters seeking direction-finding precision for automated guided vehicle coordination.
- Bluetooth 5.1:Angle-of-arrival and angle-of-departure positioning enable sub-meter indoor navigation without UWB infrastructure. Warehouse operators in the United States deploy 5.1 infrastructure to compress smart factory implementation timelines while avoiding FCC certification delays associated with newer protocol revisions.
- Bluetooth 5.0:Doubled range and quadrupled throughput sustain volume leadership in legacy fitness tracker designs.
- Bluetooth 4.2:Data length extension and privacy features persist in cost-optimized medical wearables.
- Bluetooth 4.1:Coexistence improvements with LTE radios retain niche presence in smartphone companion devices.
- Bluetooth 4.0:Original low-energy specification maintains installed base in simple beacon and proximity applications.
Deployment concentrates in Bluetooth 5.0; steepest expansion trajectory belongs to Bluetooth 5.2.
Application:
End-use verticals impose distinct regulatory overlays that reshape hardware design rules and channel economics.
- Industrial Automation:Brownfield integration demands gateway architectures bridging Bluetooth 5.x with PROFIBUS and Modbus fieldbus systems. German automotive suppliers in Baden-Württemberg specify ruggedized nodes with 10-year availability guarantees to align with EU right-to-repair mandates.
- Personal Healthcare:FDA 510(k) and EU MDR compliance documentation now functions as mandatory bid evaluation criterion in hospital network procurement. Remote patient monitoring platform operators in the United States negotiate direct device contracts, bypassing traditional medical distributors in cardiology and diabetes management verticals.
- Fitness Tracking:Consumer electronics channel saturation sustains volume leadership through seasonal retail cycles.
- Asset Management:Real-time location services integrate with enterprise resource planning systems.
- Smart Lighting:Mesh networking enables scalable commercial building control without proprietary protocols.
- Smart Agriculture:Soil moisture and livestock monitoring applications prioritize decade-long battery autonomy.
Revenue tilts toward Industrial Automation; unit volume concentrates in Fitness Tracking.
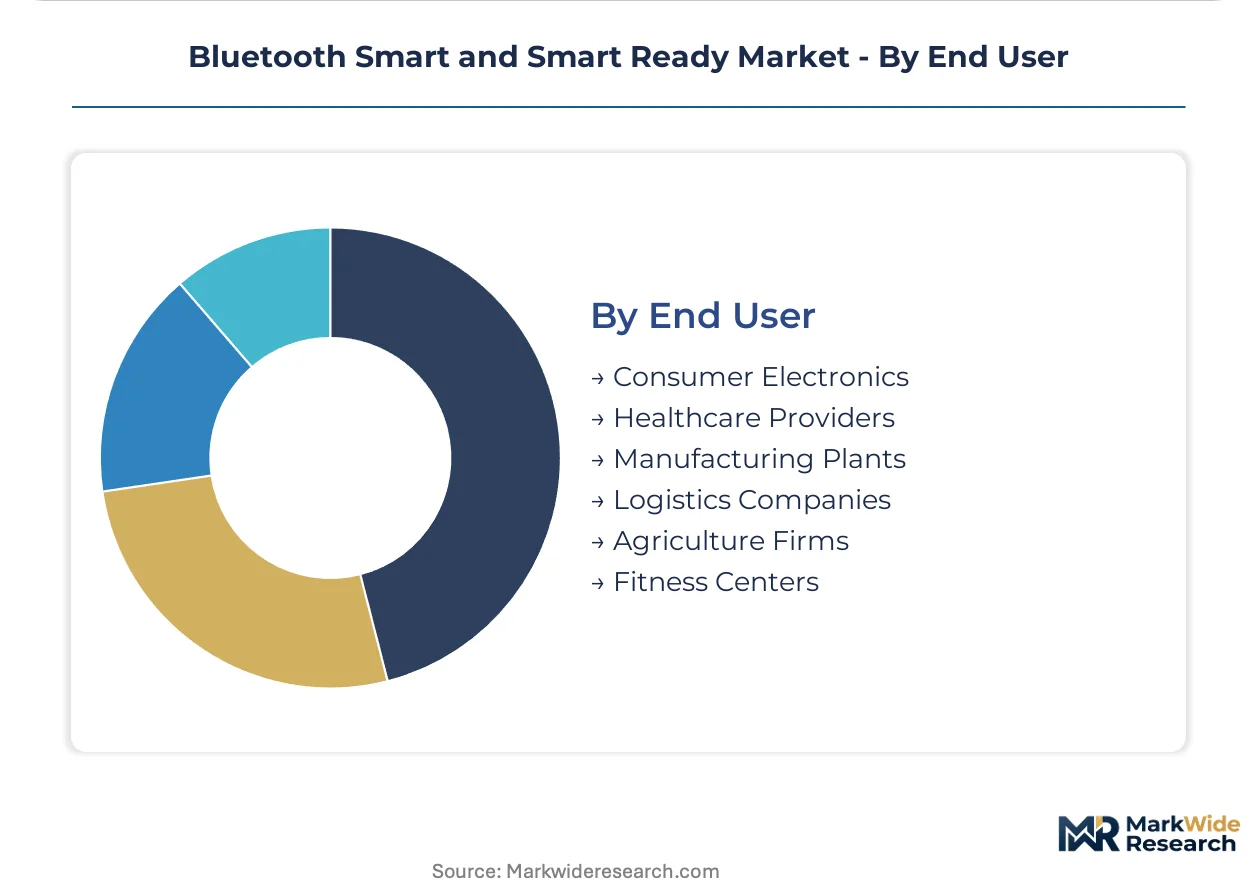
End User:
Customer procurement maturity determines specification granularity and supplier qualification duration.
- Healthcare Providers:Integrated delivery networks in Germany and the United States mandate algorithmic transparency documentation under EU AI Act risk classification and FDA software precertification pilots. CE marking dossiers now require machine-learning inference pathway disclosure for connected diagnostic devices.
- Manufacturing Plants:Industrial automation clusters specify enterprise-grade Bluetooth 5.x with direction-finding infrastructure for automated guided vehicle coordination. REACH chemical compliance and material traceability for substances of very high concern extend hardware design cycles for European market entry.
- Consumer Electronics:Seasonal product launch windows compress development schedules and favor pre-certified module suppliers.
- Logistics Companies:Warehouse operators prioritize sub-meter location precision for inventory optimization.
- Agriculture Firms:Outdoor deployments specify extended temperature range and moisture ingress protection.
- Fitness Centers:Equipment-integrated sensors enable usage-based maintenance and member engagement analytics.
Specification stringency peaks with Healthcare Providers; fastest procurement velocity characterizes Consumer Electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's industrial automation corridor anchors Bluetooth 5.x demand through automotive supplier clusters requiring direction-finding precision for automated guided vehicles. German procurement committees now embed EU Green Deal right-to-repair criteria into vendor qualification protocols.
United States
Healthcare providers in the United States are integrating continuous patient monitoring systems that rely on ultra-low-power Bluetooth LE connectivity. FDA software precertification pilots and HIPAA compliance frameworks shape hardware design rules for connected diagnostic devices. Hospital networks in the Northeast Corridor negotiate direct contracts with remote patient monitoring platform operators, bypassing traditional medical distributors.
Germany
Industrial automation clusters in Baden-Württemberg and Bavaria drive enterprise-grade Bluetooth 5.x deployments with 10-year availability guarantees. EU Green Deal right-to-repair mandates and REACH chemical compliance extend hardware design cycles for European market entry. Stuttgart-based automotive suppliers specify ruggedized nodes with field-replaceable subsystems to satisfy modular procurement criteria.
China
MIIT spectrum allocation rules and GB standards determine antenna design and certification timelines for Bluetooth 5.x products entering domestic markets. Yangtze River Delta manufacturing zones concentrate module assembly operations serving consumer electronics export channels. Shenzhen-based fabricators prioritize Matter protocol interoperability certification for smart home device shipments to North American retail channels.
India
PLI scheme production-linked incentives are attracting Bluetooth module assembly and testing operations to domestic facilities serving South Asian markets. BIS certification requirements and TRAI emission standards shape product qualification protocols for devices entering Indian healthcare and consumer channels. Karnataka's electronics manufacturing clusters host assembly lines for fitness tracker and wearable health monitor exports.
Japan
METI industrial policy directives and JIS standards govern Bluetooth integration into factory automation and precision equipment sectors. Kansai region manufacturing plants deploy Bluetooth 5.1 direction-finding infrastructure for warehouse inventory optimization. Osaka-based industrial equipment vendors specify sub-meter location precision for automated guided vehicle coordination in automotive component logistics.
Bluetooth Smart and Smart Ready Market Key Industry Players
Premium-margin players sit above commodity-margin players across protocol integration depth and regulatory pre-certification breadth. The vendor base stratifies between integrated SoC architects holding Bluetooth SIG interoperability credentials and module assemblers competing on cost-engineered reference designs. Three archetypes dominate: ultra-low-power specialists with medical-grade power budgets, industrial automation anchors with fieldbus gateway capabilities, and consumer electronics scale players with seasonal channel velocity. Competitive moves concentrate on strategic partnerships for Matter protocol certification and geographic expansion into India PLI-subsidized manufacturing zones.
Among integrated protocol stack architects, Nordic Semiconductor and Texas Instruments Incorporated exemplify the ultra-low-power and industrial automation archetypes respectively. Qualcomm Incorporated occupies a position within the premium-tier consumer electronics vector. These three anchors represent divergent competitive positioning strategies: Nordic Semiconductor sits within medical wearable power efficiency, Texas Instruments Incorporated anchors German automation cluster design wins, and Qualcomm Incorporated extends Snapdragon platform integration into premium smartwatch segments. Each exemplifies how protocol version leadership translates into margin tier separation.
| Leading Market Players |
|---|
| Qualcomm Incorporated |
| Nordic Semiconductor |
| Texas Instruments Incorporated |
| Broadcom Inc. |
| STMicroelectronics |
| NXP Semiconductors N.V. |
| Microchip Technology Inc. |
| Silicon Labs |
| Infineon Technologies |
| Others |
Cost & Logistics Intelligence
Bluetooth 5.2 protocol migration toward integrated SoC architectures is compressing module-level margins while concentrating procurement power among vendors with pre-certified RF front-end solutions. This technology shift simultaneously raises fixed certification costs and rewards scale economies in Taiwan and South Korean foundry partnerships.
Pricing Analysis
Value-based pricing anchored to direction-finding precision and medical-grade algorithmic transparency separates premium-tier Bluetooth 5.2 SoC vendors from commodity module assemblers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FDA-cleared biometric stacks command substantial premiums over uncertified consumer variants. Pricing pressure stems from Matter protocol interoperability mandates raising fixed compliance costs for gateway manufacturers. Consumer electronics buyers exhibit highest price sensitivity, while German automotive suppliers in Baden-Württemberg prioritize decade-long availability guarantees over unit cost.
Supply Chain Analysis
CE marking and FCC certification queues function as gating mechanisms that extend lead times for European and North American market entry. Advanced Bluetooth 5.2 SoC fabrication centers on Taiwan, South Korea, and the United States, with Yangtze River Delta module assembly serving export channels. Silicon wafer supply draws from concentrated foundry capacity, while antenna substrate materials and precision crystal oscillators constitute critical input dependencies. Single-source vulnerability in Taiwan semiconductor fabrication exposes supply continuity to geographic disruption. Distribution runs through certified module suppliers to OEM integration facilities, bypassing discrete component channels for integrated protocol stack designs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as interoperability certification costs and REACH compliance documentation requirements force sub-scale module vendors toward exit. EU AI Act algorithmic transparency mandates and Bluetooth SIG testing backlogs compound competitive pressure on undifferentiated assemblers.
For Market Incumbents: Acquire pre-certified RF front-end design houses to secure FCC and CE marking dossiers ahead of queue congestion. Texas Instruments and Nordic Semiconductor exemplify defensive positioning through integrated power management and ultra-low-power medical-grade portfolios. Capacity addition in Karnataka PLI-subsidized zones counters Taiwan foundry concentration risk. Channel control through direct hospital network relationships in the United States bypasses distributor margin erosion. For New Entrants and Emerging Players: Energy-harvesting photovoltaic integration for ambient IoT sensors offers technology-first entry with minimal incumbent saturation. India's BIS certification pathway presents the most penetrable regulatory frontier for fitness tracker and wearable health monitor assembly. White-space targets include German automotive supplier aftermarket retrofit for PROFIBUS gateway bridging. Go-to-market leverage rests on Matter protocol pre-certification partnerships with Shenzhen ecosystem integrators. For Investors and Strategic Acquirers: Exit pathways concentrate in industrial automation anchor acquisitions by semiconductor conglomerates seeking fieldbus gateway capabilities. Long-term viability favors vendors with dual FDA and EU MDR regulatory dossiers in remote patient monitoring. Acquisition target archetype: mid-cap specialists with Bluetooth SIG interoperability credentials and REACH material traceability systems. Watch for FCC emission limit revisions as inflection indicator for pre-certified RF front-end demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Interoperability validation unlocks North American smart home retail channel access. |
| EU MDR Compliance Investment | CE marking dossiers with algorithmic transparency documentation secure German hospital procurement. |
| India PLI Manufacturing Expansion | Production-linked incentives attract module assembly serving South Asian export markets. |
| Direction-Finding Infrastructure Deployment | Bluetooth 5.1/5.2 precision positioning enables automated guided vehicle coordination in Stuttgart automotive logistics. |
| Energy-Harvesting Sensor Development | Photovoltaic and RF power integration eliminates battery dependence in smart home ambient IoT. |
Research Approach
Independent corroboration across Bluetooth SIG interoperability filings, FCC equipment authorization databases, and EU MDR notified body documentation underwrites the qualitative findings. Primary interviews with biomedical engineers at German hospital networks, RF design leads at Nordic Semiconductor and Texas Instruments, and procurement managers at Baden-Württemberg automotive suppliers informed segmentation dynamics. Secondary validation drew from SEC 10-K disclosures, MIIT spectrum allocation notices, and India PLI scheme beneficiary registries. Bottom-up unit demand modeling triangulated against top-down semiconductor foundry capacity allocations.
Comparable-period anchoring to Bluetooth 4.x through 5.x deployment trajectories calibrated the projection horizon's growth rate assumptions. Segmentation dimensions modeled include protocol version, product type, application vertical, and end-user procurement maturity. CAGR derivation incorporated technology substitution elasticity estimates for Wi-Fi 6/6E in audio streaming and indoor positioning. Industry-specific inputs encompassed Matter protocol adoption curves and EU Green Deal right-to-repair procurement penetration rates.
Several conditions sit outside the modeled scope, including unannounced Bluetooth SIG specification revisions, Taiwan semiconductor supply disruptions, and abrupt REACH substance restriction amendments. Forecasts reflect documented assumptions regarding certification queue durations and foundry capacity expansion timelines. A model refresh is warranted upon material change in FCC emission limit enforcement or FDA software precertification pilot expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Japan Digital Signal Processor Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Nano GPS Chip Market
Communication Chips & Hardware
Wireless Connectivity Chipset Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Global Application Specific Communications Analog IC Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
Bluetooth Low Energy Market
Communication Chips & Hardware
Nano GPS Chipset Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
GNSS Chip Market